
 Polymer Catalyst Market | 2026-2036
Polymer Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Catalyst Market Analytics
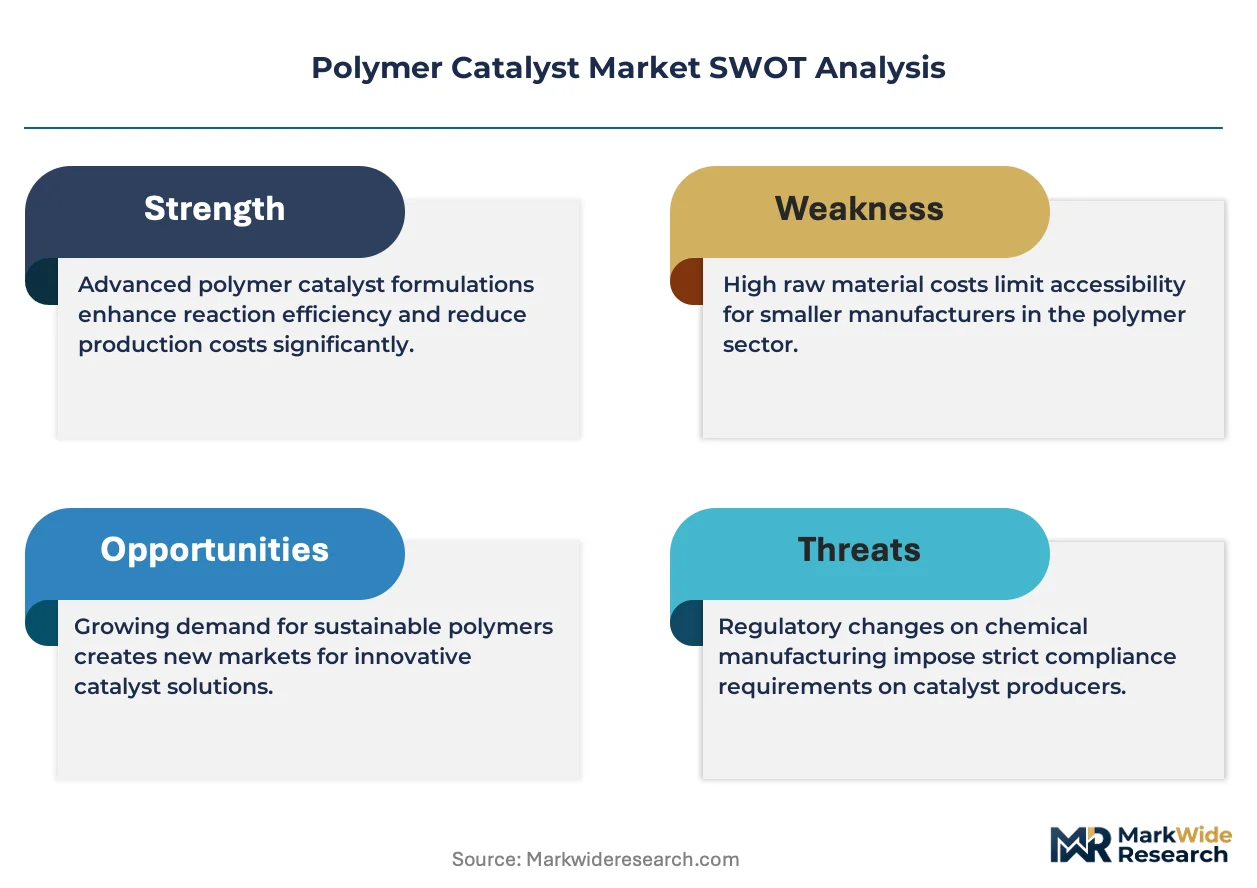
ISO 14001 environmental management certification is reorganizing supplier qualification protocols across the polymer catalyst value chain. BASF SE leverages its integrated catalyst-polymer technology platform to sustain premium positioning in metallocene systems. Evonik Industries AG anchors its competitive stance through specialized high-activity Ziegler-Natta catalyst manufacturing at scale. Clariant AG differentiates via advanced catalyst carrier technologies that extend reactor run-times for polyethylene producers.
Polymer catalysts are substances that accelerate or enable the formation of polymer chains from monomer feedstocks, typically operating at pressures of 10-80 bar and temperatures of 50-150°C depending on the catalytic system and target polymer grade. These catalysts primarily serve to control molecular weight distribution, stereoregularity, and process efficiency in the industrial production of polyethylene, polypropylene, and engineering thermoplastics. Heterogeneous catalysts occupy the largest volume share due to their ease of separation and reuse in continuous slurry and gas-phase processes. Metallocene catalysts represent the fastest-expanding product category, commanding margin premiums through precise control of polymer architecture that enables differentiated performance grades for automotive and medical applications.
REACH registration requirements in Europe, EPA emissions standards in the United States, and China's GB standards for chemical catalyst manufacturing collectively tighten product specifications and facility permitting timelines. ECHA substance evaluation protocols now require comprehensive migration testing for catalyst residues in food-contact plastics, directly influencing formulation decisions by catalyst producers. Stakeholders must monitor evolving regulatory timelines for per- and polyfluoroalkyl substance restrictions, as these intersect with certain high-performance polymerization systems and may force accelerated reformulation cycles.
Market Dynamics
REACH compliance deadlines and the EU Green Deal are compressing formulation cycles for catalyst producers, forcing simultaneous residue reduction and performance maintenance across polyethylene and polypropylene lines.
Growth Catalysts
- Automotive lightweighting mandates:Tier-1 suppliers in Germany and the United States specify metallocene-grade polypropylene for bumper and interior panels, pulling high-activity catalyst demand.
- ECHA migration testing protocols:Food-contact polymer regulations now require demonstrable catalyst residue containment, creating specification premiums for certified low-migration systems.
- China's dual carbon goals:Domestic polyolefin producers retrofit gas-phase reactors with advanced Ziegler-Natta systems to cut energy intensity per ton of output.
Market Restraints
- Titanium tetrachloride feedstock volatility:Ziegler-Natta catalyst production faces margin pressure from spot price swings in this critical chloride intermediate.
- Specialty carrier supply concentration:High-purity silica and alumina carriers for supported catalysts source predominantly from a narrow German and Belgian supplier base.
- Metallocene IP thickets:Dow and ExxonMobil heritage patent estates constrain independent development of constrained-geometry catalyst architectures.
Strategic Opportunities
- India's petrochemical buildout:Reliance Industries and Indian Oil Corporation expand ethylene capacity at Jamnagar and Paradip, opening catalyst qualification windows for new suppliers.
- Chemical recycling integration:Pyrolysis-derived naphtha streams require catalyst systems tolerant of oxygenated and heteroatom contaminants absent in virgin feedstock.
- EU ETS carbon border adjustments:Low-carbon catalyst manufacturing processes gain preference among European polyethylene exporters seeking scope 3 emissions reductions.
Industry Challenges
- Organometallic synthesis expertise gap:PhD-level talent capable of scaling metallocene and post-metallocene molecular designs from lab to tonnage production commands premium compensation and retention difficulty.
- Reactor run-time certification delays:Extended validation protocols at BASF's Ludwigshafen and LyondellBasell's Channelview facilities stretch new catalyst qualification timelines beyond eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Catalyst Market |
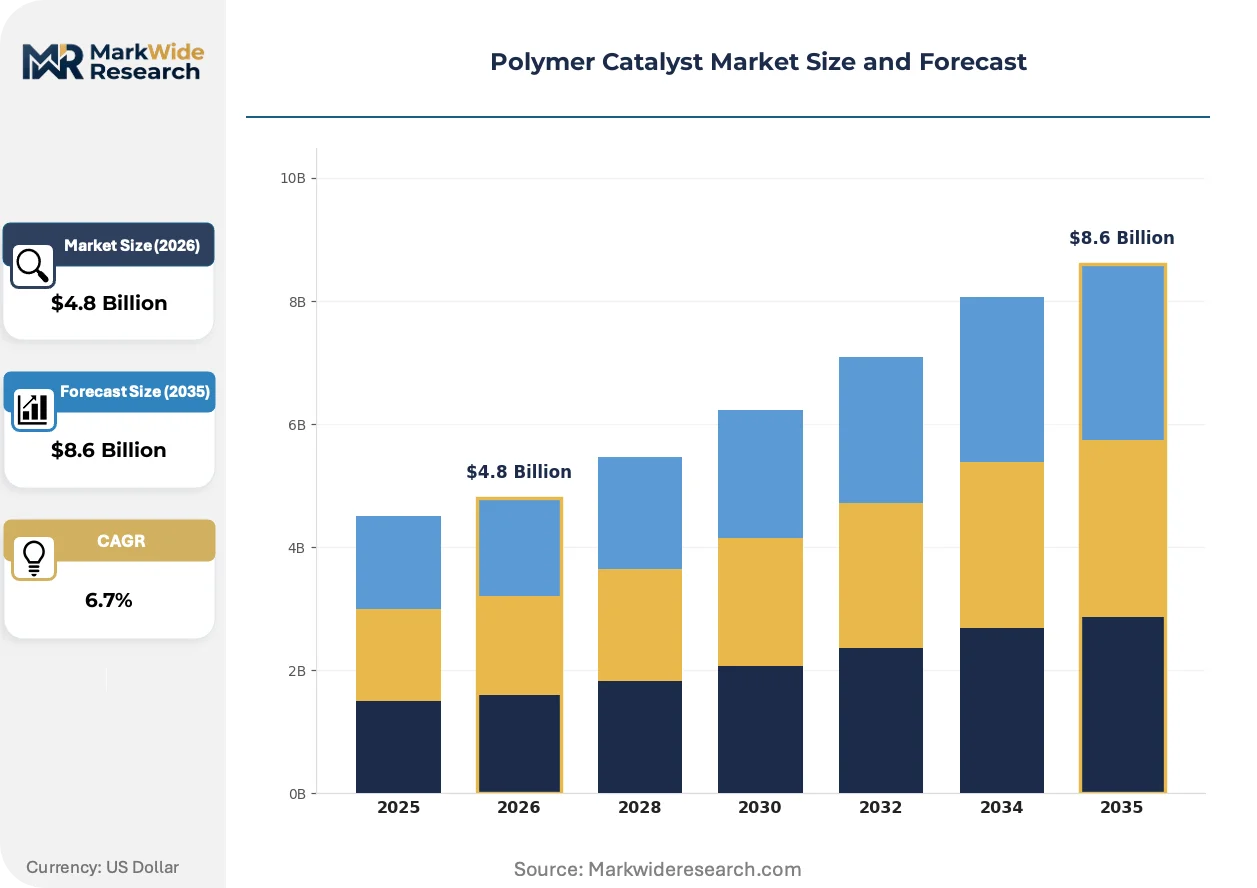
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homogeneous Catalysts, Heterogeneous Catalysts, Ziegler-Natta Catalysts, Metallocene Catalysts Application: Polymerization, Petrochemical Processing, Chemical Synthesis, Biofuel Production End User: Plastic Manufacturers, Pharmaceutical Companies, Automotive Industry, Research Institutions Technology: Conventional Method, Advanced Catalyst Systems, Green Chemistry Techniques, Reactive Recycling |
| Companies Covered | Mitsui Chemicals Inc., Evonik Industries AG, LyondellBasell Industries Holdings B.V., China Petrochemical Corporation, Univation Technologies LLC, W. R. Grace & Co., BASF SE, Toho Titanium Co. Ltd, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Catalyst Market Evolving Landscape
Digital twin deployment across polymerization reactor networks is compressing catalyst optimization cycles from months to weeks, enabling real-time molecular weight distribution tuning.
Single-site catalyst technology is bifurcating the polyethylene market into commodity linear low-density grades and ultra-high-molecular-weight specialty tiers. Medical device manufacturers in Switzerland and Minnesota specify the latter for orthopedic implants and surgical equipment. This split is compressing margins on standard-grade catalysts while expanding pricing power for architectural precision systems.
REACH authorization requirements for chromium-based catalyst precursors are forcing reformulation across high-density polyethylene lines. Producers in the Port of Antwerp cluster and the US Gulf Coast face simultaneous substance sunset dates and customer specification lock-ins. The sector responds with accelerated non-chromium single-site platform development.
Consolidated procurement by resin super-majors now bundles catalyst supply with technical service and reactor optimization contracts. This disintermediates traditional distributor channels in favor of direct manufacturer partnerships. The shift is most visible among Middle Eastern polyethylene exporters seeking integrated performance guarantees for their Asian offtake agreements.
Polymer Catalyst Market Segmentation
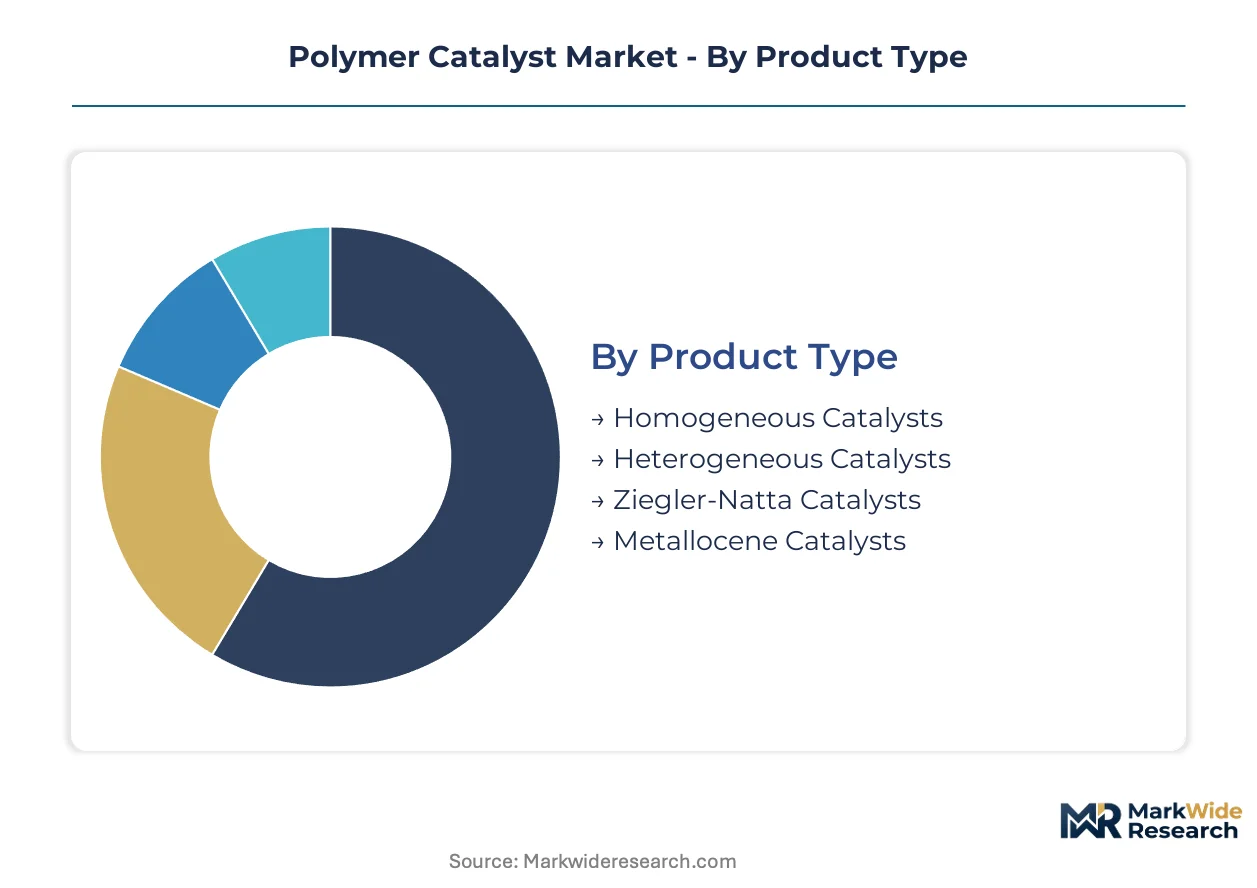
Polymer catalyst procurement patterns diverge sharply between commodity polyolefin producers seeking volume efficiency and specialty compounders demanding architectural precision. Segmentation reveals how catalyst selection cascades through molecular weight control, regulatory compliance, and reactor compatibility decisions.
Product Type:
Domestic supply chains in Germany and China favor heterogeneous systems for continuous gas-phase operations, while export-oriented specialty producers in Switzerland and Minnesota specify metallocene architectures for medical-grade output.
- Heterogeneous Catalysts:Solid-phase systems deploy on silica or alumina carriers for easy separation in slurry and gas-phase polyethylene processes. Demand concentrates among Saudi Arabian and US Gulf Coast resin exporters running Unipol and Innovene reactor technologies, with reactor run-time extension driving carrier quality specifications.
- Metallocene Catalysts:Single-site organometallic systems enable precise stereoregularity control for differentiated polypropylene grades. Automotive lightweighting mandates in Germany and the United States pull demand for high-flow, high-impact copolymers used in bumper and interior panel applications.
- Ziegler-Natta Catalysts:Titanium-based systems dominate commodity polypropylene production through controlled porosity and electron donor modification.
- Homogeneous Catalysts:Soluble systems serve niche solution polymerization processes for specialty elastomers and advanced thermoplastics.
Heterogeneous catalysts hold the largest share; momentum sits with metallocene systems.
Application:
Cost tier separation distinguishes high-volume polymerization from premium chemical synthesis, with petrochemical processing occupying the mid-tier investment band.
- Polymerization:Core application spanning polyethylene, polypropylene, and polystyrene production through coordination polymerization mechanisms. Capacity buildouts at Jamnagar and Paradip in India concentrate new catalyst demand for virgin resin output.
- Petrochemical Processing:Catalytic cracking and reforming applications in integrated refinery-petrochemical complexes. European facilities face EU ETS carbon border adjustment pressures favoring catalyst systems that reduce energy intensity per ton of olefin output.
- Chemical Synthesis:Fine chemical and intermediate production requiring enantioselective catalysis for pharmaceutical precursors.
- Biofuel Production:Transesterification and hydrodeoxygenation catalysts for renewable diesel and sustainable aviation fuel pathways.
Polymerization commands the dominant value position; biofuel production shows the steepest expansion trajectory.
End User:
Customer type fragmentation separates integrated resin super-majors from fragmented specialty compounders, with procurement scale determining technical service bundling.
- Plastic Manufacturers:Polyolefin producers and engineering thermoplastic compounders specifying catalyst systems for reactor optimization. REACH migration testing protocols for food-contact applications now require demonstrable residue containment, creating specification premiums for certified low-migration systems.
- Automotive Industry:Tier-1 suppliers and OEM material engineers driving metallocene-grade polypropylene adoption for lightweighting compliance. German bumper producers and US interior panel manufacturers specify narrow molecular weight distribution grades for consistent processing.
- Pharmaceutical Companies:Active pharmaceutical ingredient manufacturers requiring chiral catalysts for asymmetric synthesis.
- Research Institutions:Academic and government laboratories evaluating next-generation single-site and post-metallocene architectures.
Plastic manufacturers represent the largest procurement base; automotive specifications are climbing fastest.
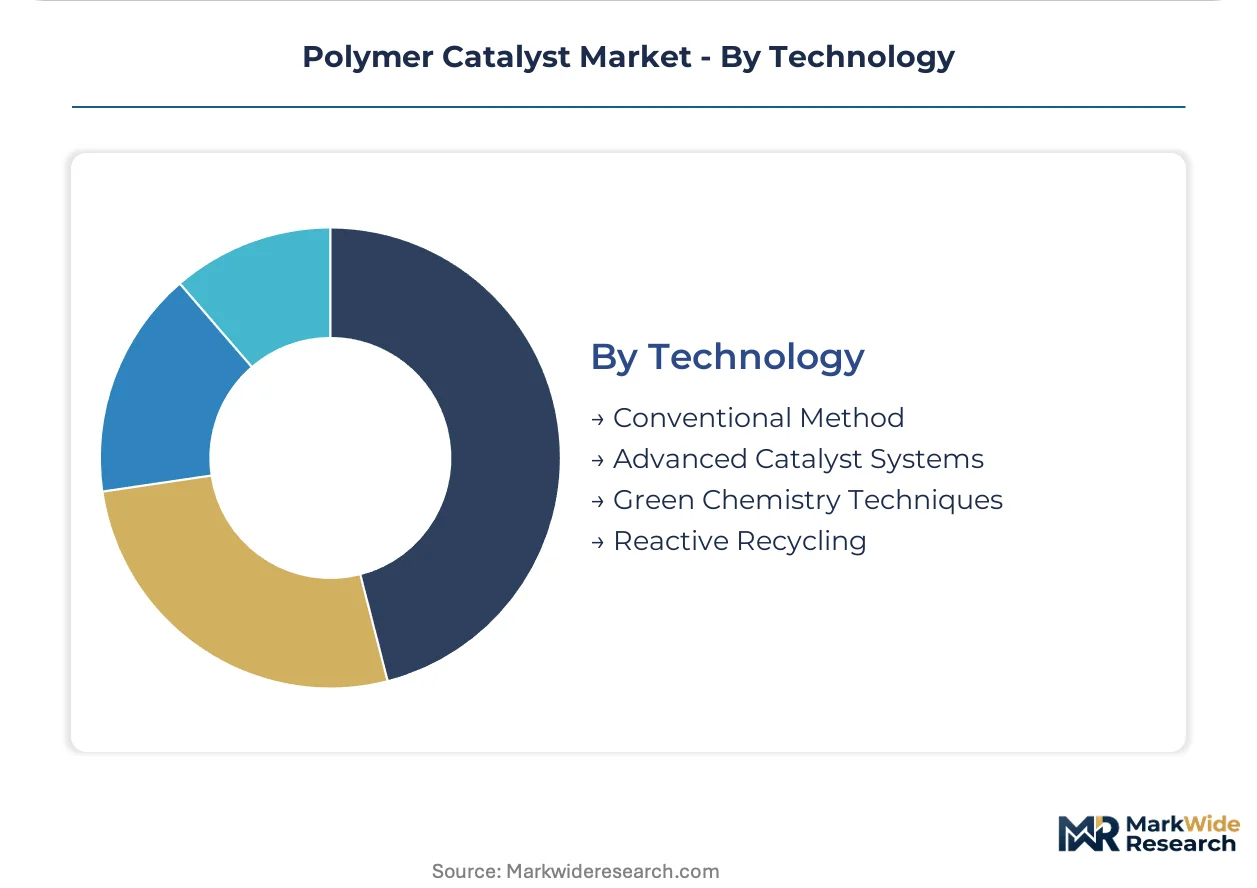
Technology:
Supply concentration for advanced systems sits with German and US catalyst producers, while conventional methods diffuse across Chinese and Indian licensing arrangements.
- Advanced Catalyst Systems:Digital twin-integrated reactor optimization platforms enabling real-time molecular weight distribution tuning. Digital deployment across polymerization networks compresses catalyst optimization cycles from months to weeks.
- Green Chemistry Techniques:Solvent-free synthesis and atom-economical routes reducing catalyst production environmental footprint. EU Green Deal compliance deadlines force simultaneous residue reduction and performance maintenance across European catalyst lines.
- Conventional Method:Established slurry and gas-phase technologies with mature supply chains and qualified reactor compatibility.
- Reactive Recycling:Catalyst systems tolerant of oxygenated and heteroatom contaminants in pyrolysis-derived naphtha streams for chemical recycling integration.
Conventional methods retain volume dominance; green chemistry techniques are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated resin super-majors and specialty compounders cluster in Germany, the United States, China, Saudi Arabia, and India, each pulling distinct catalyst specifications based on regulatory exposure and end-use mix.
United States
Gulf Coast polyethylene exporters running gas-phase Unipol reactors specify high-activity Ziegler-Natta systems for volume efficiency. EPA emissions standards tighten facility permitting timelines for catalyst production sites in Texas and Louisiana. The Channelview cluster hosts extended validation protocols that stretch new catalyst qualification beyond eighteen months.
Germany
Automotive Tier-1 suppliers in Bavaria and Baden-Württemberg specify metallocene-grade polypropylene for bumper and interior panel lightweighting compliance. REACH authorization requirements for chromium-based precursors force reformulation across high-density polyethylene lines. The Ludwigshafen chemical cluster concentrates integrated catalyst-polymer technology platforms.
China
Domestic polyolefin producers retrofit gas-phase reactors with advanced Ziegler-Natta systems to meet dual carbon goals for energy intensity reduction. GB standards for chemical catalyst manufacturing tighten product specifications and facility compliance timelines. Capacity buildouts in the Yangtze River Delta and Pearl River Delta concentrate new catalyst demand.
Saudi Arabia
State-backed resin super-majors seek bundled catalyst supply with technical service and reactor optimization contracts for Asian offtake agreements. The country's national chemical regulator aligns with GCC standardization protocols for catalyst residue specifications. The Jubail industrial city cluster anchors bulk polyethylene export capacity.
India
Reliance Industries and Indian Oil Corporation expand ethylene capacity at Jamnagar and Paradip, opening catalyst qualification windows for new suppliers. BIS certification requirements for food-contact polymer applications create specification premiums for low-migration systems. The Gujarat chemical corridor concentrates domestic petrochemical buildout activity.
Polymer Catalyst Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with captive catalyst-polymer integration, creating tiered competition between scale-driven commodity suppliers and precision-focused specialty architects. Market structure concentrates among German, US, and Japanese heritage firms with deep organometallic synthesis expertise. Strategic archetypes include integrated technology platforms, specialized high-activity manufacturers, and advanced carrier technology developers. Competitive moves center on reactor run-time certification partnerships and direct procurement bundling with resin super-majors.
Among Germany-based diversified chemical conglomerates, BASF SE and Evonik Industries AG occupy positions reflecting integrated catalyst-polymer technology platforms and specialized high-activity manufacturing at scale respectively. Clariant AG, a Swiss specialty chemicals company, exemplifies the advanced carrier technology archetype through reactor run-time extension capabilities. Japan-based Mitsui Chemicals Inc. and Toho Titanium Co. Ltd represent Asia-Pacific heritage players with deep organometallic synthesis expertise. These five entities collectively span the technology platform, manufacturing scale, and materials science specializations that define competitive positioning in this sector.
| Leading Market Players |
|---|
| Mitsui Chemicals Inc. |
| Evonik Industries AG |
| LyondellBasell Industries Holdings B.V. |
| China Petrochemical Corporation |
| Univation Technologies LLC |
| W. R. Grace & Co. |
| BASF SE |
| Toho Titanium Co. Ltd |
| Clariant AG |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Belgian high-purity silica carriers sets price floors for supported Ziegler-Natta systems, compressing margins for catalyst producers unable to secure long-term carrier offtake. This scale concentration forces tiered pricing stratification across premium metallocene architectures, standard heterogeneous systems, and economy-grade titanium-based formulations.
Pricing Analysis
Cost-plus contracts indexed to titanium tetrachloride spot markets dominate Ziegler-Natta procurement, while metallocene systems command fixed-price premiums tied to reactor run-time guarantees. Price differentiation hinges on REACH migration certification tier and bundled technical service intensity. Cost compression in standard-grade lines intensifies as Chinese producers expand domestic Ziegler-Natta capacity. Commodity polyolefin manufacturers exhibit highest price sensitivity; medical-grade compounders prioritize architectural precision over unit economics.
Supply Chain Analysis
Container availability constraints on Rotterdam-Antwerp feedstock lanes elevate inbound logistics costs for chloride intermediates sourced from German chemical clusters. Manufacturing concentrates in Germany, the United States, and China, with high-purity alumina carriers drawing from Belgian and German supplier bases. The supply chain rests on titanium tetrachloride and organometallic precursor dependencies. Single-source vulnerability permeates specialty carrier procurement. Distribution runs through direct manufacturer partnerships with resin super-majors, disintermediating traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and reactor optimization contracts now expand faster than standalone catalyst hardware sales, transforming procurement into recurring-revenue relationships. This service-attach dynamic favors providers capable of embedding digital twin capabilities and real-time molecular weight tuning into long-term supply agreements.
For Market Incumbents: Secure eighteen-month reactor qualification pipelines at Channelview and Ludwigshafen facilities to lock out emerging competitors. Deepen backward integration into high-purity silica carrier production to neutralize Belgian and German supply concentration. Patent estate thickets around constrained-geometry architectures require aggressive defense against post-metallocene challengers.
For New Entrants and Emerging Players: Reactor run-time certification backlogs at incumbent validation facilities represent the most exploitable service-layer gap. Target India's Jamnagar and Paradip buildouts where Reliance Industries and Indian Oil Corporation actively qualify new catalyst suppliers. Lead with low-migration system certification for BIS food-contact compliance, bypassing established European qualification queues.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors organometallic synthesis specialists with scalable post-metallocene platforms. Five-to-ten year viability hinges on regulatory alignment with REACH chromium precursor phase-outs and EU ETS carbon border adjustments. Monitor ECHA substance evaluation timelines for per- and polyfluoroalkyl substance restrictions as inflection indicators forcing accelerated reformulation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carrier Production | Captive silica supply neutralizes Belgian-German concentration risk for polyethylene catalyst producers. |
| Digital Twin Platform Deployment | Real-time molecular weight tuning compresses optimization cycles from months to weeks at Unipol reactors. |
| REACH Low-Migration Certification | ECHA food-contact compliance commands specification premiums from European plastic manufacturers. |
| Long-term Supply Agreement with Resin Super-Majors | Bundled technical service contracts disintermediate distributor channels in Middle Eastern export markets. |
| Joint Venture for Chemical Recycling Catalyst Development | Pyrolysis-derived naphtha tolerance opens qualification windows at European circular economy facilities. |
Research Methodology
Operator-level perspectives from polymerization plant managers, catalyst procurement leads at polyolefin producers, technical R&D directors, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance registration databases. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against titanium tetrachloride price volatility, REACH authorization timeline shifts, and carbon border adjustment implementation scenarios. Segmentation dimensions modeled include catalyst product type, polymerization application grade, end-user procurement scale, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and capacity buildout pipeline assessment, with energy intensity per ton of olefin output serving as key efficiency input alongside dual carbon goal compliance rates.
Material uncertainties — feedstock price shocks, regulatory acceleration or delay, and single-site catalyst IP litigation outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification timeline norms and carrier supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Photocatalyst Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Europe Refining Catalysts Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Catalyst Handling Services Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Refining Catalysts Market