
 Pond Liners Market | 2026-2036
Pond Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Pond Liners Market Intelligence
A shift from single-source to multi-source procurement is decoupling project timelines from individual supplier capacity, reducing dependency on any single manufacturer. Carlisle Companies Incorporated leverages its broad product portfolio to capture demand across both residential and commercial segments. Huesker Synthetic GmbH differentiates with engineered textiles for specialized agricultural and industrial containment needs. Solmax Geosynthetics sustains its market position through large-scale, cost-efficient production of HDPE and LDPE materials.
Pond liners are impermeable geomembrane barriers engineered to retain water in artificial ponds, lagoons, and reservoirs. These liners are manufactured from synthetic polymers like EPDM or PVC, with thickness typically ranging from 20 to 60 mils for puncture resistance. While flexible EPDM materials lead in high-value decorative applications, HDPE sheets dominate large-scale agricultural projects due to lower costs and chemical resistance. Demand from the commercial end-user segment for architectural water features is expanding at a notable rate.
In the United States, the EPA's guidelines on water containment for agricultural runoff influence material selection for liners. European markets must adhere to REACH regulations concerning chemical composition, while China's GB standards dictate material durability and safety for aquaculture. Future material innovation will focus on balancing biodegradability with the long-term impermeability and UV stability required for effective water storage.
Market Dynamics
The pond liner market's structure is defined by the growing need for water conservation in agriculture. This creates a fundamental tension between the demand for low-cost, large-scale HDPE liners and stricter environmental regulations pushing for higher-performance materials.
Growth Catalysts
- Water Management Policies:The EU's Water Framework Directive and similar mandates for efficient water containment create regulatory-driven demand for impermeable liner solutions.
- Agricultural Expansion:Intensive farming and aquaculture in arid regions, such as Australia and the Southwestern United States, depend on liners for water storage and conservation.
- Material Cost-Effectiveness:The adoption of high-density polyethylene (HDPE) for large-scale projects provides a cost-effective solution, driving volume in agricultural and civil applications.
Market Restraints
- Input Cost Volatility:Prices for raw materials like EPDM, PVC, and polyethylene are tied to volatile petrochemical markets, creating pricing instability for manufacturers.
- Material Trade-offs:A persistent technical challenge involves balancing the need for long-term durability and UV resistance with market demands for more biodegradable materials.
- Alternative Solutions:In some applications, traditional methods such as compacted clay liners or concrete basins present viable, low-technology substitutes for synthetic pond liners.
Strategic Opportunities
- Emerging Aquaculture Markets:The expansion of aquaculture in Southeast Asia presents an opportunity for liners with specific properties for fish and shrimp farming.
- Smart Liner Technology:Developing liners with integrated sensors for real-time leak detection offers a high-value proposition for critical industrial and environmental containment.
- Conservation Incentives:Government subsidies for water conservation technologies in agriculture, particularly in water-stressed nations like India, can accelerate market penetration.
Industry Challenges
- Installation Skill Gap:A shortage of technicians trained in proper seam welding and installation techniques can lead to liner failure and performance issues.
- Complex Compliance Landscape:Manufacturers must navigate a fragmented web of international standards, including REACH in Europe and GB standards in China, for material safety.
- Logistical Hurdles:The transportation and handling of large, heavy rolls of liner material to remote agricultural or mining sites pose significant logistical and cost challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pond Liners Market |
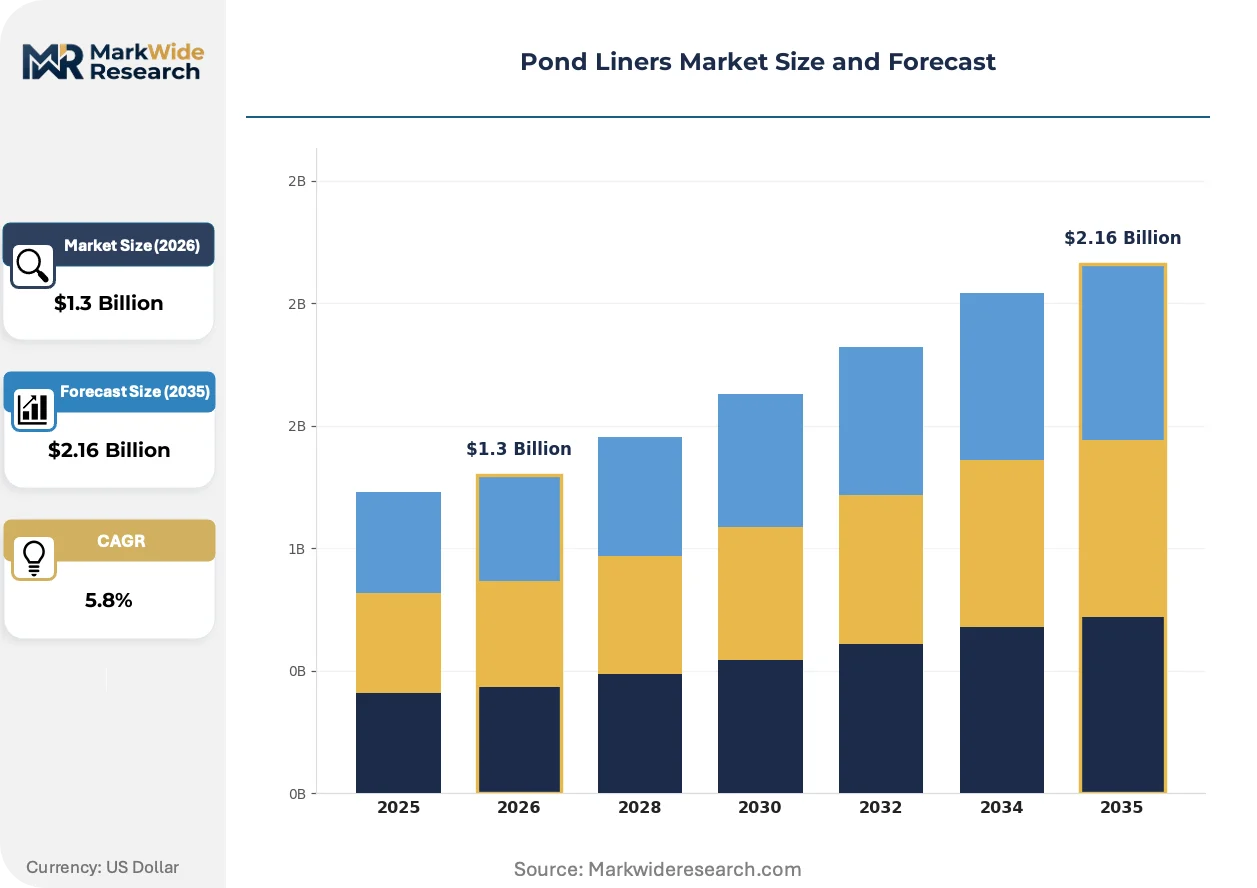
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: EPDM, PVC, HDPE, LDPE Product Form: Sheet, Roll, Tile, Preformed Application: Fish Ponds, Decorative Ponds, Agricultural Applications, Irrigation End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Layfield Group Ltd., Huesker Synthetic GmbH, Solmax Geosynthetics, Shandong Geosino New Material Co., Ltd., Maccaferri Group, GSE Environmental, NAUE GmbH & Co. KG, Carlisle Companies Incorporated, AGRU America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pond Liners Market Strategic Shifts & Innovations
Material science advancements are pushing pond liners toward greater specialization. This evolution creates a divergence between highly engineered materials for niche industrial uses and cost-optimized polymers for mass-market agricultural and decorative applications.
Multi-layered co-extruded geomembranes combine discrete polymer layers, such as flexible LLDPE cores with chemically resistant HDPE caps. Industrial sectors like mining and landfill management are adopting these materials for secure hazardous waste containment. This advanced composite technology is expanding into critical infrastructure projects, such as canal lining and reservoir protection, where long-term impermeability is paramount.
The United States EPA's regulations for Concentrated Animal Feeding Operations (CAFOs) require secure containment of animal waste lagoons. These rules compel farm operators to use liners with certified chemical resistance to prevent groundwater contamination. The agricultural sector, particularly in the American Midwest and West, is most impacted, standardizing on HDPE liners to meet compliance and mitigate liability.
Large project developers are now favoring multi-source procurement strategies to de-risk supply chain dependencies. This approach disrupts traditional exclusive supplier agreements by splitting large orders across multiple manufacturers to ensure timeline adherence. The shift is most pronounced in major agricultural irrigation schemes in India and Australia, where project scopes often exceed a single supplier's capacity.
Pond Liners Market Segmentation
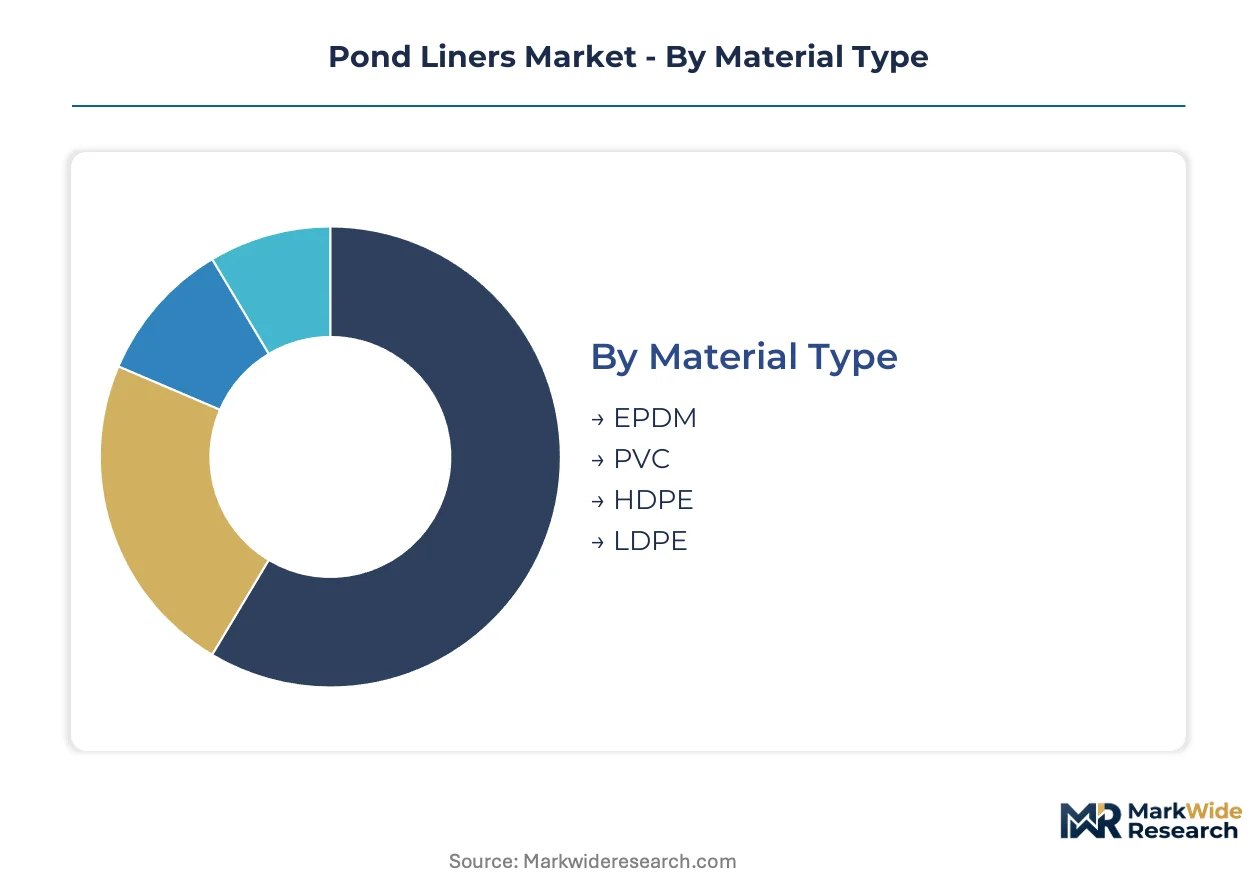
Understanding the pond liners market through segmentation reveals how diverse material properties and application requirements shape product development and procurement strategies. Each segment reflects distinct end-user needs, from large-scale agricultural water management to specialized decorative features, influencing material selection and installation techniques across various projects.
Material Type:
The material type segmentation highlights how advancements in polymer science drive both new installations and the upgrade cycle for existing water containment systems.
- HDPE:High-density polyethylene liners offer exceptional chemical resistance and durability, making them the preferred choice for large-scale agricultural reservoirs and industrial containment applications due to their cost-effectiveness and long lifespan. Demand is concentrating in arid agricultural zones like the Southwestern United States for water storage.
- EPDM:Ethylene propylene diene monomer provides superior flexibility and UV resistance, making it ideal for high-value decorative ponds and landscape applications where aesthetic integration and ease of installation are paramount. Commercial architectural projects are expanding their use of EPDM for water features.
- PVC:Polyvinyl chloride liners offer good flexibility and puncture resistance at a lower cost, often utilized in smaller residential ponds and temporary containment solutions.
- LDPE:Low-density polyethylene provides high flexibility and tear resistance, finding applications in projects requiring conformity to irregular shapes, such as complex landscaping designs.
HDPE sits at the top of the volume ranking, with EPDM climbing the fastest in high-value applications.
Product Form:
Different product forms reflect varied installation complexities and cost-efficiency requirements across diverse project scales.
- Roll:Large rolls of geomembrane material are standard for extensive agricultural and civil engineering projects, enabling efficient coverage of vast areas with minimized seams. Logistical hurdles associated with transporting these heavy rolls to remote sites are a significant consideration.
- Sheet:Pre-cut sheets provide versatility for medium-sized installations and custom shapes, allowing for more precise fitting and reducing on-site waste in commercial and industrial settings. This form is often used for specialized containment.
- Preformed:Factory-molded rigid basins offer a quick and easy solution for small, standardized decorative ponds and water features, eliminating the need for extensive on-site shaping. Residential users frequently select preformed liners for garden ponds.
- Tile:Segmented tile-like liners are less common but offer modularity for specific repair or specialized containment scenarios where traditional rolls are impractical.
Rolls offer the most flexible and cost-effective solution for extensive projects, while preformed liners cater to specific aesthetic and functional needs.
Application:
The application segmentation illustrates the primary drivers of pond liner consumption, from large-scale water management to specialized containment.
- Agricultural Applications:This segment includes liners for irrigation ponds, livestock watering, and water conservation reservoirs, driven by the increasing need for efficient water management in farming operations. The EU's Water Framework Directive mandates efficient water containment solutions, bolstering demand here.
- Fish Ponds:Liners for aquaculture and fish farming require specific chemical resistance and durability to maintain water quality and prevent leakage, supporting the expansion of seafood production in Southeast Asia. This application demands specialized material properties.
- Decorative Ponds:Liners for aesthetic water features in gardens, parks, and commercial landscapes prioritize flexibility and UV stability to ensure long-term visual appeal and minimal maintenance. Architectural water features drive demand in this segment.
- Irrigation:Similar to agricultural applications, irrigation projects utilize liners for canals and water channels to minimize seepage and maximize water delivery efficiency to crops.
Agricultural applications drive significant volume due to water conservation mandates, while fish ponds see expansion driven by aquaculture growth.
End User:
End-user segments define the specific performance criteria and purchasing patterns for pond liner solutions.
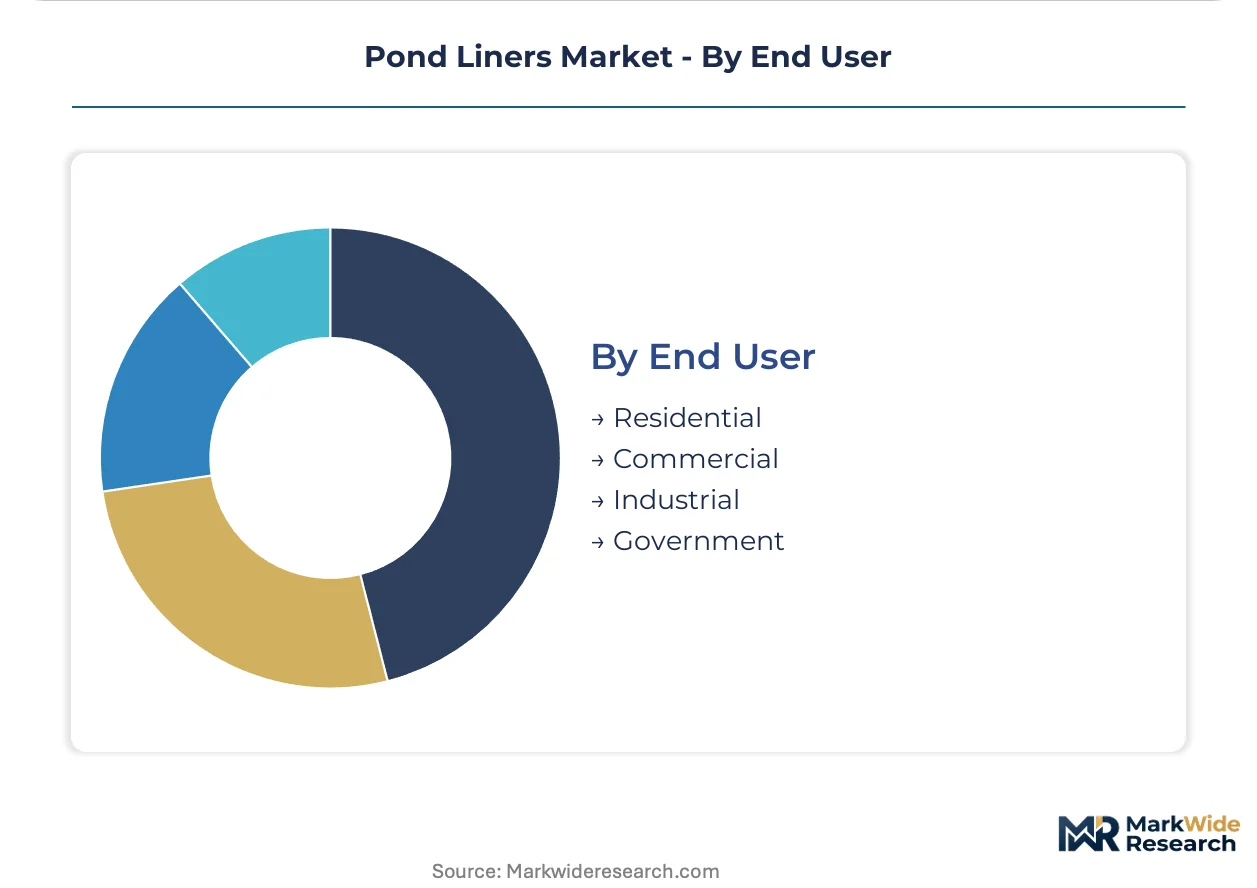
- Commercial:This segment includes businesses and institutions requiring liners for architectural water features, golf course ponds, and commercial landscaping projects, often demanding high-quality, aesthetically pleasing materials. Demand from this segment is expanding at a notable rate.
- Industrial:Industrial users deploy pond liners for critical applications such as hazardous waste containment, mining leach pads, and wastewater treatment lagoons, where chemical resistance and long-term impermeability are paramount. Strict environmental regulations influence material selection for industrial sites.
- Residential:Homeowners utilize pond liners for garden ponds, small decorative water features, and backyard aquatic ecosystems, typically prioritizing ease of installation and cost-effectiveness.
- Government:Government entities procure pond liners for public works projects, including municipal water reservoirs, stormwater retention basins, and environmental remediation sites.
Commercial projects are expanding their demand for specialized water features, contrasting with the established, utility-driven needs of industrial users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across regions creates opportunities for production arbitrage, influencing the geographic distribution of pond liner manufacturing and supply. Manufacturers adapt material specifications to meet varied environmental standards, optimizing costs and market access. This dynamic shapes investment in new capacities across different continents.
United States
The Southwestern United States drives demand for large-scale HDPE liners in agricultural water storage and conservation projects. The EPA's guidelines for Concentrated Animal Feeding Operations (CAFOs) mandate secure containment, influencing material selection for animal waste lagoons. California's Central Valley, a major agricultural hub, standardizes HDPE liners to meet compliance and mitigate environmental liability effectively.
India
Indian agricultural expansion, particularly in water-stressed regions, generates substantial demand for cost-effective pond liners. Government subsidies for water conservation technologies, such as those under the Pradhan Mantri Krishi Sinchayee Yojana, accelerate market penetration for irrigation projects. The Maharashtra region, with its extensive farming, utilizes liners for efficient water management and reservoir protection.
Australia
Australia's arid agricultural zones, including the Murray-Darling Basin, require extensive pond liner applications for irrigation and water conservation. The country's environmental protection agencies enforce strict regulations on water containment to prevent seepage and minimize ecological impact. Western Australia's mining sector also employs specialized liners for process water and tailings management.
Germany
European markets, including Germany, prioritize high-performance liners for industrial and specialized agricultural containment applications. REACH regulations concerning chemical composition directly impact material selection and manufacturing processes for all geomembranes. The Rhine-Ruhr industrial area, a significant manufacturing and chemical hub, demands robust liners for wastewater treatment and chemical storage.
China
China's rapidly expanding aquaculture sector fuels significant demand for pond liners with specific durability and safety properties. The GB standards dictate material durability and safety for aquaculture applications, ensuring long-term performance in fish and shrimp farming. Coastal provinces like Guangdong, a major aquaculture producer, extensively use specialized liners to support seafood production.
Pond Liners Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-performance material niches. The pond liners market exhibits a tiered structure, with global leaders competing on scale and efficiency, while smaller players often focus on regional distribution and custom solutions. Strategic archetypes include large-scale geomembrane manufacturers, specialized engineered textile providers, and regional fabricators. Dominant competitive moves involve portfolio diversification to address various end-user needs and strategic partnerships for enhanced market reach.
At the scale-driven end, Solmax Geosynthetics, a Canadian-headquartered company, exemplifies cost-efficient production of HDPE and LDPE materials, essential for large-scale agricultural and civil applications globally. Carlisle Companies Incorporated, a US-based firm, represents a diversified player leveraging its broad product portfolio to capture demand across both residential and commercial segments, offering a wide array of liner types. Huesker Synthetic GmbH, a German entity, occupies a position as a specialist in engineered textiles, differentiating with solutions for specialized agricultural and industrial containment needs, particularly in Europe. These companies collectively anchor significant market share through their distinct approaches to material science and application focus across different geographies.
| Leading Market Players |
|---|
| Layfield Group Ltd. |
| Huesker Synthetic GmbH |
| Solmax Geosynthetics |
| Shandong Geosino New Material Co., Ltd. |
| Maccaferri Group |
| GSE Environmental |
| NAUE GmbH & Co. KG |
| Carlisle Companies Incorporated |
| AGRU America Inc. |
| Others |
Cost & Logistics Intelligence
Skilled installation technicians represent a concentrated workforce, and labor-cost differentials for specialized welding techniques influence pricing tiers for complex projects. This expertise ensures proper geomembrane deployment and impacts overall project costs for critical containment.
Pricing Analysis
Distributor margins and project-based contracting define the dominant pricing model for pond liners. Price differentiation stems from material quality grade, such as HDPE versus EPDM, and required certification levels for specific applications. Pricing pressure stems from volatile petrochemical markets, creating instability for manufacturers. The agricultural segment exhibits the highest price sensitivity, preferring cost-effective HDPE solutions for large-scale water management.
Supply Chain Analysis
Single-source vulnerability sits with raw material suppliers for polyethylene, EPDM, and PVC, making manufacturers susceptible to commodity price fluctuations. Geographic supply concentration for finished geomembranes draws from key production hubs in China, Germany, and the United States. Key raw material dependencies include crude oil derivatives for polymer production. Logistics chokepoints, particularly for large rolls of material, create a structural risk for remote project delivery. Downstream distribution primarily involves direct-to-project sales for large civil works and specialized distributor networks for smaller commercial and residential applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a compelling margin-expansion story, driven by the increasing adoption of specialized multi-layered geomembranes for high-value industrial applications.
For Market Incumbents: Hedge against raw material price volatility by diversifying supplier bases and exploring long-term procurement contracts. Invest in R&D for advanced material composites that offer superior UV stability and biodegradability to counter emerging alternative solutions. Expand manufacturing capacity in key agricultural zones like India and Australia to leverage government conservation incentives. Broaden product portfolios to capture demand across both high-volume agricultural and high-value industrial segments.
For New Entrants and Emerging Players: Advanced sensor integration into liners offers a technology-first wedge into the high-value industrial and environmental containment sectors. Target emerging aquaculture markets in Southeast Asia, which demand specific material properties for fish and shrimp farming. Develop cost-effective, specialized liners that meet stringent local GB standards for durability and safety. Focus go-to-market strategies on offering complete solutions, including installation training, to address the skill gap.
For Investors and Strategic Acquirers: Specialized technology developers are the most active acquirer in this space, seeking advanced material science and smart liner capabilities. The long-term viability of pond liners is anchored in global water conservation mandates and expanding agricultural and industrial applications. Target regional fabricators with strong local distribution networks and expertise in specialized installation techniques. The signal to watch is the increasing allocation of government subsidies for water conservation technologies in water-stressed nations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Arid Regions | Enhances supply chain resilience and addresses growing demand from water-stressed agricultural zones. |
| Multi-layered Geomembrane Development | Captures high-value industrial demand for secure hazardous waste containment and critical infrastructure. |
| Smart Liner Technology Integration | Offers a premium solution for real-time leak detection, crucial for environmental compliance and industrial safety. |
| Geographic Expansion into Aquaculture | Unlocks significant growth opportunities in Southeast Asia, driven by expanding fish and shrimp farming. |
| Green Certification Program | Differentiates products by addressing market demands for biodegradability balanced with long-term impermeability. |
Research Approach
Multiple input streams—primary interviews, secondary research, and quantitative modeling—were reconciled to construct a comprehensive market view. This involved engaging agricultural engineers, industrial procurement managers, geomembrane manufacturers, and environmental regulators. Secondary validation drew from EPA guidelines, REACH regulations, GB standards, and industry association reports, triangulating findings from bottom-up and top-down analyses.
Historical market data was cross-referenced with expert panel input to establish a robust forecast framework across the analysis window. The analytical model integrated segmentation dimensions including material type, product form, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from projected shifts in water conservation mandates and raw material price forecasts, ensuring a dynamic and responsive projection.
The model holds under current geopolitical and environmental policy conditions; deviation in global petrochemical supply or unexpected shifts in environmental regulations would shift the market trajectory. Forecasts reflect a synthesis of these assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Biodegradable Mulch Film Market