
 Asia-Pacific Agricultural Films Market | 2026-2036
Asia-Pacific Agricultural Films Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Films Market Outlook
Buyer concentration across the Asia-Pacific Agricultural Films Market is shifting as commercial producers and large greenhouse operators consolidate procurement volumes, displacing fragmented smallholder purchasing. Dow Inc. leverages its polyethylene resin supply chain to anchor downstream film pricing power across Southeast Asian distribution channels. BASF SE differentiates through biodegradable polymer R&D intensity, targeting premium horticulture segments with compostable mulch solutions. Ginegar Plastic Products Ltd. dominates Israeli-export-influenced greenhouse film specifications across India and Vietnam.
Asia-Pacific agricultural films comprise polymeric sheeting engineered from polyethylene, polyvinyl chloride, ethylene-vinyl acetate, or biodegradable formulations, manufactured through blown-film extrusion at thicknesses ranging from 20 to 200 microns to regulate soil temperature, moisture retention, and crop microclimates. Mulch film and greenhouse film categories command the largest volume positions due to their penetration across China's vegetable belts and India's floriculture zones, while biodegradable material types represent the fastest-expanding margin pool as regulatory bans on conventional plastics intensify. Silage film occupies a mature niche with stable replacement demand among Australia's dairy operations and Japan's livestock cooperatives.
China's SAMR enforces GB standards for agricultural film durability and recyclability, while India's BIS mandates thickness minimums to reduce soil-residue pollution, and Australia's TGA-aligned state environmental agencies impose extended producer responsibility schemes. These frameworks compel manufacturers to reformulate virgin resin blends and invest in post-consumer recycling infrastructure to maintain market access. Stakeholders must monitor evolving biodegradability certification requirements across ASEAN member states to anticipate raw material substitution timelines and capital allocation priorities.
Market Dynamics
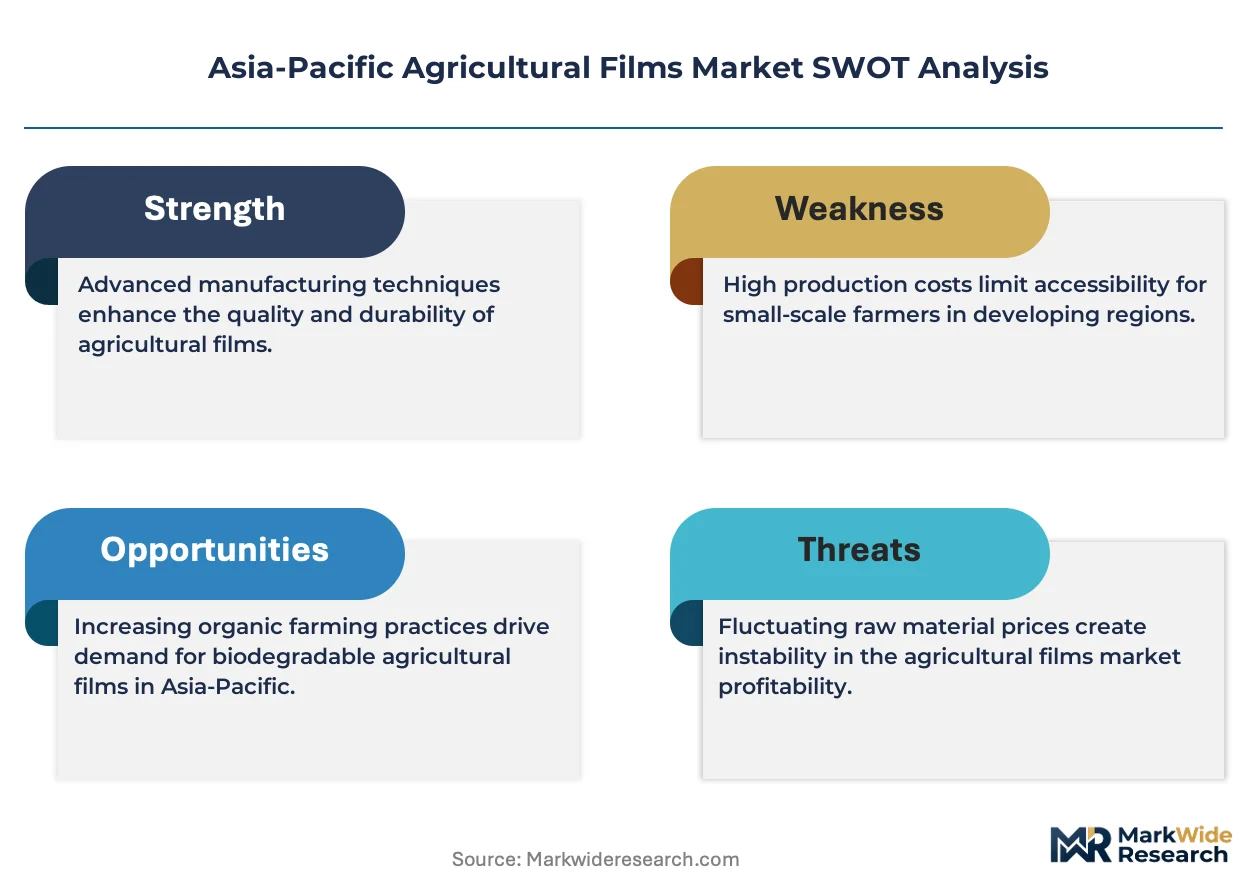
China's GB standards for agricultural film recyclability and India's BIS thickness mandates are compressing virgin polyethylene demand while accelerating biodegradable resin substitution across Shandong and Jiangsu vegetable belts.
Growth Catalysts
- GB Standard Recyclability Mandates:China's SAMR enforces durability specifications that extend film service life and create replacement cycles for premium-grade polyethylene formulations.
- Shandong-Jiangsu Vegetable Belt Expansion:Intensive greenhouse construction across these provinces concentrates mulch film procurement volumes among commercial producers.
- Biodegradable Polymer R&D:PLA and PBAT formulation advances are narrowing performance gaps with conventional polyethylene in moisture retention applications.
Market Restraints
- Crude-Derived Resin Volatility:Naphtha and ethylene feedstock costs swing with Brent crude benchmarks, compressing blown-film extrusion margins.
- Shandong Petrochemical Cluster Concentration:Over 60% of Asia-Pacific polyethylene resin supply concentrates in this single province, creating geographic vulnerability.
- Biodegradation Rate Variability:Soil temperature and microbial activity differences across ASEAN climates produce inconsistent composting outcomes for certified films.
Strategic Opportunities
- Vietnam Floriculture Expansion:Da Lat greenhouse operators are adopting Israeli-influenced film specifications for year-round rose and orchid production.
- Extended Producer Responsibility Schemes:Australia's state-level environmental agencies are mandating post-consumer collection infrastructure that rewards integrated manufacturers.
- Smart Film Convergence:Integration of temperature-responsive additives with IoT soil monitoring systems enables precision agriculture premium pricing.
Industry Challenges
- Biodegradability Certification Lag:ASEAN member states lack harmonized testing protocols, forcing manufacturers to run parallel certification tracks for each export destination.
- Blown-Film Extrusion Technician Scarcity:Specialized operators capable of calibrating 20-200 micron thickness ranges across biodegradable and conventional resins command wage premiums that inflate conversion costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Films Market |
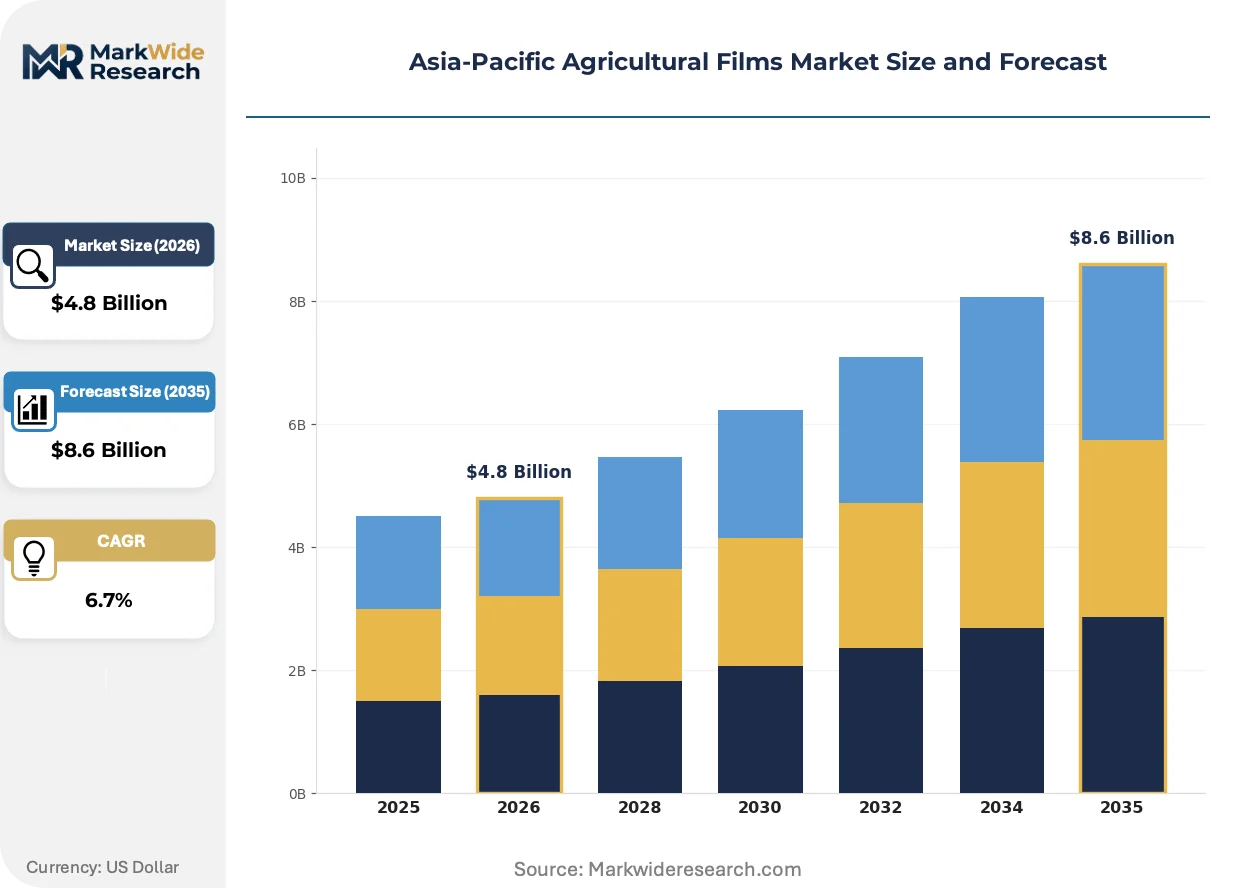
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Mulch Film, Greenhouse Film, Silage Film, Stretch Film Material Type: PE, PVC, Biodegradable, EVA Application: Crops, Horticulture, Aquaculture, Landscaping End User: Farmers, Growers, Greenhouses, Commercial Producers |
| Companies Covered | BASF SE, Berry Global Inc., Dow Inc., ExxonMobil Chemical, RKW Group, Ginegar Plastic Products Ltd., Kuraray Co., Ltd., Plastika Kritis SA, Armando Alvarez Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Films Market Strategic Shifts
Active research pipelines are converging on sensor-embedded films and climate-adaptive polymer formulations that shift competitive advantage from scale economies to formulation precision.
Multilayer co-extrusion technology incorporating ethylene-vinyl acetate barriers and UV-stabilized outer skins is automating the labor-intensive manual monitoring of greenhouse microclimates. Large commercial vegetable producers across China's Jiangsu province are retrofitting existing greenhouse infrastructure with these intelligent films at replacement rates exceeding conventional polyethylene cycles. The technology is automating temperature and humidity regulation decisions previously delegated to farm managers, compressing operational headcount requirements while improving yield consistency.
India's BIS mandates on agricultural film thickness minimums are eliminating sub-30 micron products from distribution channels and forcing reformulation of virgin resin blends. The industrial consequence is a wholesale shift toward heavier-gauge films that reduce soil-residue pollution but increase per-hectare material costs. Smallholder segments in Maharashtra and Karnataka are responding through cooperative procurement pooling to maintain access to compliant products without absorbing full price premiums.
Buyer concentration among commercial greenhouse operators is consolidating procurement volumes and displacing fragmented smallholder purchasing patterns across Vietnam's Central Highlands. Agricultural input distributors are ceding ground to direct manufacturer relationships as operators above 50-hectare scale negotiate annual volume contracts with technical service attachments. This pattern is most visible in Da Lat's floriculture zone, where Israeli-influenced greenhouse film specifications now dominate technical procurement criteria.
Asia-Pacific Agricultural Films Market Segmentation
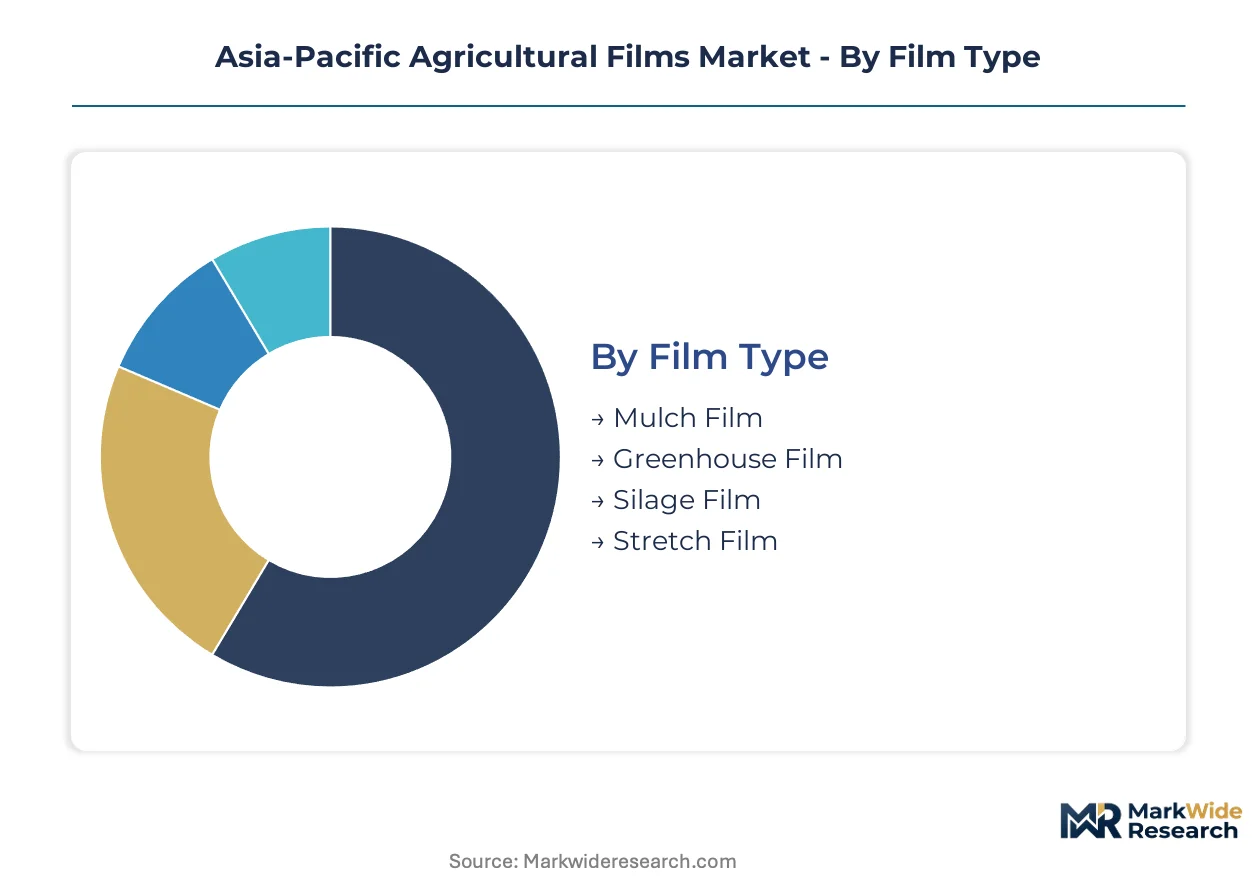
Segmentation in Asia-Pacific agricultural films reveals how procurement power, regulatory pressure, and crop economics intersect to determine material selection. Buyers optimize across film durability, biodegradability certification, and greenhouse infrastructure investment cycles.
Film Type:
Commercial producers prioritize performance specifications that match replacement cycles to crop rotation schedules and climatic stress factors.
- Mulch Film:Polyethylene sheeting manufactured at 15-50 micron thicknesses for soil temperature modulation and moisture retention. China's Shandong vegetable belt drives bulk procurement as commercial producers replace films every growing season to comply with GB standard recyclability mandates.
- Greenhouse Film:Multilayer co-extruded formulations incorporating UV stabilizers and anti-drip additives for controlled environment agriculture. Da Lat floriculture operators in Vietnam specify Israeli-influenced 150-200 micron grades for year-round rose and orchid production.
- Silage Film:Oxygen-barrier formulations for anaerobic fermentation preservation across Australia's dairy cooperatives and Japan's livestock associations.
- Stretch Film:Linear low-density polyethylene wraps for haylage and silage bale handling with emphasis on puncture resistance.
Mulch film leads on scale across China's intensive vegetable zones; greenhouse film leads on momentum as controlled environment agriculture expands.
Material Type:
Regulatory bans on soil-residue pollution are compressing virgin resin demand while accelerating certified biodegradable substitution timelines.
- PE:Linear low-density and high-density polyethylene formulations dominating conventional mulch and greenhouse applications. India's BIS thickness mandates are forcing reformulation toward heavier-gauge virgin resin blends that increase per-hectare material costs.
- Biodegradable:PLA and PBAT polymer formulations engineered for microbial decomposition under controlled soil conditions. ASEAN regulatory divergence on certification protocols creates parallel testing requirements for manufacturers serving multiple export destinations.
- PVC:Rigid and flexible formulations for tunnel greenhouse structures requiring structural stability across monsoon climates.
- EVA:Ethylene-vinyl acetate copolymers specified for premium greenhouse films demanding optical clarity and thermal insulation.
PE retains volume dominance; biodegradable materials are climbing the fastest as China's SAMR and India's BIS accelerate compliance deadlines.
Application:
Crop economics and export orientation determine willingness to absorb premium pricing for certified biodegradable or smart-enabled film specifications.
- Horticulture:Floriculture and protected vegetable production requiring precise microclimate control through multilayer film formulations. Vietnam's Central Highlands greenhouse operators above 50-hectare scale negotiate direct manufacturer contracts with technical service attachments.
- Crops:Field-scale grain and oilseed production utilizing standard mulch films with minimal performance differentiation.
- Aquaculture:Pond lining and cage covering applications across Southeast Asian shrimp farming operations.
- Landscaping:Turf protection and erosion control films for golf course and municipal green space maintenance.
Horticulture commands premium pricing tiers; crops maintain replacement-driven volume stability.
End User:
Scale thresholds determine procurement channel selection between distributor intermediaries and direct manufacturer relationships.
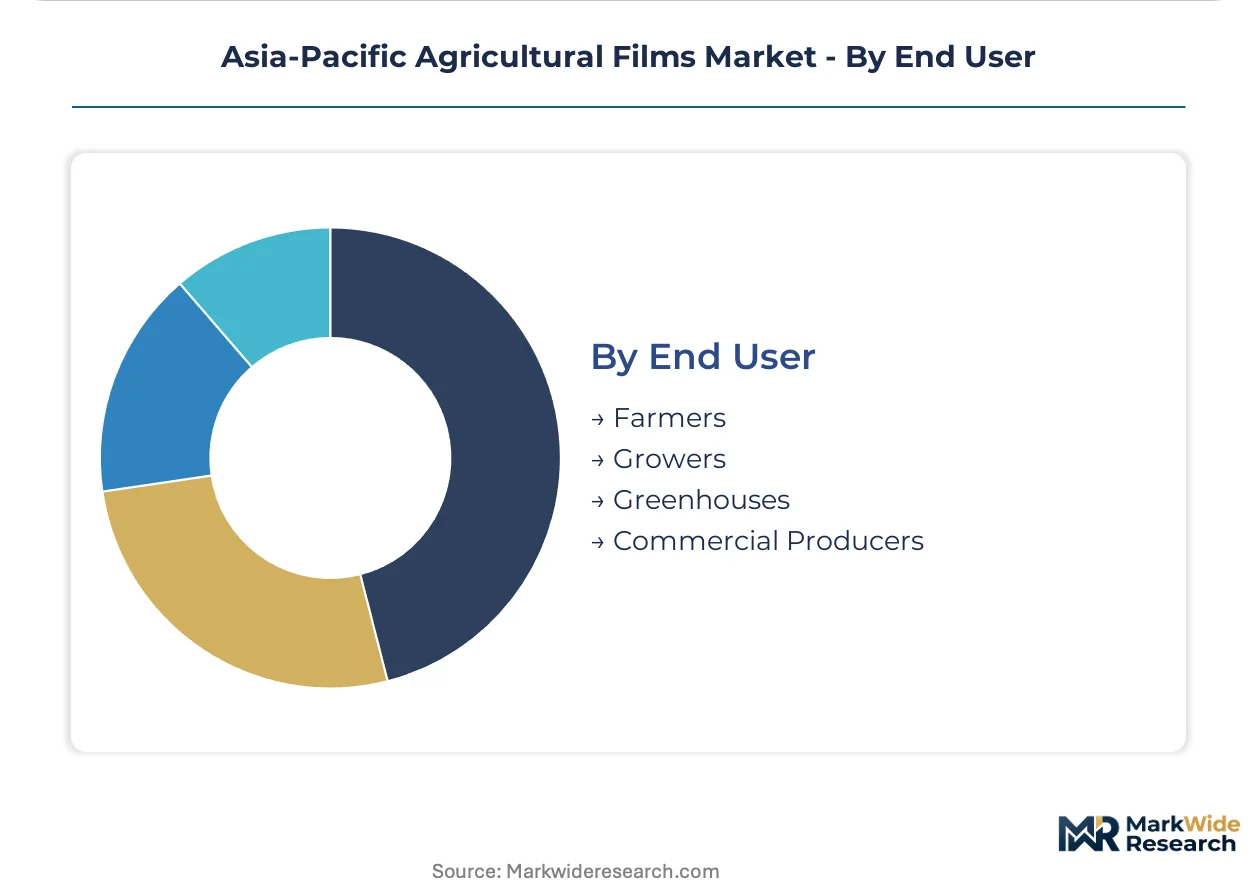
- Commercial Producers:Corporate farming entities and integrated agribusiness operations with centralized procurement functions. These buyers consolidate annual volumes across multiple sites to negotiate technical service packages and extended payment terms.
- Greenhouses:Dedicated protected agriculture facilities requiring specialized film specifications for climate control automation.
- Growers:Mid-scale operations transitioning from distributor purchasing toward cooperative pooling to access BIS-compliant thickness grades.
- Farmers:Fragmented smallholder segments in Maharashtra and Karnataka responding to price premiums through cooperative procurement structures.
Commercial producers concentrate negotiating leverage; growers are gaining share fastest as cooperative structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong province processes more polyethylene resin than India's entire agricultural film sector consumes annually, yet Indian demand is accelerating faster as BIS thickness mandates force rapid product upgrading.
China
Shandong and Jiangsu vegetable belts concentrate bulk procurement of mulch and greenhouse films among commercial producers expanding intensive protected agriculture. SAMR's GB standards enforce recyclability and durability specifications that compress replacement cycles for premium-grade formulations. Zibo and Weifang petrochemical clusters supply over sixty percent of regional polyethylene resin, creating geographic concentration risk for downstream film manufacturers.
India
Maharashtra and Karnataka smallholders are pooling cooperative procurement to access BIS-compliant thickness grades above thirty microns. CDSCO-aligned state agricultural departments enforce soil-residue pollution controls that eliminate sub-standard film distribution. Nashik and Bengaluru floriculture zones drive specification upgrades toward multilayer greenhouse films with UV stabilization.
Vietnam
Da Lat greenhouse operators above fifty-hectare scale negotiate direct manufacturer contracts for Israeli-influenced film specifications in year-round rose and orchid production. The Ministry of Agriculture and Rural Development is drafting biodegradability certification protocols that parallel ASEAN harmonization efforts. Lam Dong province's Central Highlands cluster is displacing fragmented distributor channels with centralized technical procurement.
Australia
TGA-aligned state environmental agencies mandate extended producer responsibility schemes for post-consumer film collection infrastructure. Victoria and New South Wales dairy cooperatives maintain stable replacement demand for silage and stretch film categories. Melbourne polymer compounders are integrating recycled content streams to maintain market access under tightening circular economy regulations.
Japan
METI guidelines on agricultural plastic resource efficiency are accelerating biodegradable material trials in Hokkaido and Tohoku vegetable production zones. JIS standards for film thickness and degradability create technical barriers for imported conventional polyethylene products. Nagoya-based polymer distributors are consolidating procurement volumes among livestock cooperatives for silage film replacement cycles.
Asia-Pacific Agricultural Films Market Competitive Environment
Chinese petrochemical-anchored producers dominate resin supply and blown-film extrusion capacity; Israeli-influenced specialists hold premium greenhouse specifications across Southeast Asian horticulture zones. The vendor base organizes into three tiers: integrated resin-to-film manufacturers, regional extrusion specialists, and biodegradable formulation innovators. Consolidation pressures concentrate among mid-scale extruders lacking captive polyethylene supply or certified biodegradable polymer access. Competitive moves center on backward integration into resin compounding and technology licensing for multilayer co-extrusion capabilities.
Within the integrated petrochemical tier, Dow Inc. and ExxonMobil Chemical exemplify resin supply chain control that anchors downstream pricing power across Asia-Pacific distribution channels. BASF SE occupies a position representing biodegradable polymer R&D intensity targeting premium horticulture segments with compostable mulch solutions. Ginegar Plastic Products Ltd. sits within the Israeli-export-influenced specification tier that dominates technical procurement criteria across Indian and Vietnamese greenhouse operators.
| Leading Market Players |
|---|
| BASF SE |
| Berry Global Inc. |
| Dow Inc. |
| ExxonMobil Chemical |
| RKW Group |
| Ginegar Plastic Products Ltd. |
| Kuraray Co., Ltd. |
| Plastika Kritis SA |
| Armando Alvarez Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between BIS-compliant thickness mandates and conventional polyethylene grades manifests in dual pricing tracks and fragmented procurement channels across Maharashtra and Karnataka smallholder cooperatives. China's SAMR recyclability specifications compress margins on sub-premium formulations while rewarding multilayer co-extrusion investments with pricing power in Jiangsu greenhouse clusters.
Pricing Analysis
Capacity additions in Shandong's Zibo petrochemical corridor are reshaping price floors for virgin polyethylene resin while biodegradable polymer premiums hold firm against PLA and PBAT feedstock volatility. Three-tier pricing structure across premium multilayer greenhouse films, standard BIS-compliant mulch grades, and economy-tier legacy products reflects certification level and volume scale differentiation. Pricing pressure stems from naphtha cost volatility tracking Brent crude benchmarks, compressing blown-film extrusion margins. Smallholder cooperatives in India's Deccan Plateau exhibit highest price sensitivity, whereas Da Lat floriculture operators above fifty-hectare scale absorb technical premiums for Israeli-influenced specifications.
Supply Chain Analysis
Single-source vulnerability sits with Shandong province's petrochemical clusters, which feed over sixty percent of regional polyethylene resin through Zibo and Weifang production hubs. Raw material dependencies center on naphtha-derived ethylene, imported LLDPE grades, and certified biodegradable polymer feedstocks from European compounders. Tariff exposure on ASEAN biodegradability certification parallel tracks compounds supply chain risk for manufacturers serving multiple export destinations. Distribution runs through agricultural input distributors ceding ground to direct manufacturer relationships as commercial greenhouse operators consolidate procurement volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific agricultural films function as a regulatory compounder where India's BIS thickness mandates and China's GB recyclability standards force rapid product upgrading and raw material substitution timelines.
For Market Incumbents: To counter biodegradable polymer R&D intensity from European chemical majors, anchor pricing power through captive polyethylene resin supply in Shandong clusters while accelerating certified compostable formulation pipelines. Prioritize backward integration into naphtha cracking capacity to buffer feedstock volatility. Defend channel position by embedding technical service teams with Vietnam's Central Highlands greenhouse operators negotiating direct annual contracts. For New Entrants and Emerging Players: Capture white-space in Australia's extended producer responsibility scheme infrastructure, where state-level environmental agencies mandate post-consumer collection systems with limited domestic supplier penetration. Target Maharashtra and Karnataka cooperative procurement pooling structures as the most penetrable buyer segment. Lead with BIS certification compliance bundled with volume aggregation platforms for fragmented smallholder access. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale extruders lack captive resin supply or certified biodegradable polymer access, creating acquisition opportunities among regional specialists in ASEAN markets. Frame long-term viability around regulatory compliance durability as SAMR and BIS accelerate enforcement timelines. Watch biodegradability certification harmonization across ASEAN member states as the critical inflection signal for capital reallocation toward compostable formulation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply from Shandong petrochemical clusters anchors downstream pricing power against naphtha volatility. |
| Biodegradable Polymer R&D Partnership | PLA and PBAT formulation advances with European chemical majors accelerate compliance with India's BIS and China's SAMR mandates. |
| Multilayer Co-Extrusion Technology Licensing | Israeli-influenced specifications for Da Lat greenhouse operators command technical procurement premiums in floriculture zones. |
| Extended Producer Responsibility Infrastructure | Post-consumer collection systems satisfy Australia's TGA-aligned state environmental agency requirements for circular economy access. |
| Direct Manufacturer Relationship Programs | Technical service attachments with Vietnam's Central Highlands operators displace fragmented agricultural input distributor channels. |
Study Parameters
Multiple input streams — primary interviews with blown-film extrusion plant managers, procurement leads at Indian horticulture cooperatives, and distribution channel partners across Southeast Asia — were reconciled against secondary validation from customs and trade data, BIS and SAMR regulatory filings, and SEC disclosures from integrated petrochemical majors. Bottom-up volume estimates from individual production facility outputs and top-down demand assessments from crop hectarage and film application rates were triangulated to constrain forecast variance.
Data-stream reconciliation across film type, material grade, application intensity, and end-user scale dimensions informed analytical framework construction over the projection horizon. CAGRs were derived from segmented growth rate aggregation weighted by base-year value contributions. Industry-specific forecast inputs incorporated polyethylene resin price elasticity coefficients and biodegradable substitution timelines driven by regulatory compliance deadlines.
Feedstock cost volatility, ASEAN regulatory divergence on certification protocols, and biodegradation rate variability across climatic zones are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Silo Bags Market