
 Agricultural Gloves Market | 2026-2036
Agricultural Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Gloves Market Analysis
A capital-intensity divergence between automated knitting facilities and manual assembly operations is rotating competitive advantage toward manufacturers with in-house yarn-to-glove production. Superior Glove Works Ltd. leverages its North American manufacturing base to sustain rapid fulfillment for industrial-scale farm cooperatives. Hartalega Holdings anchors its position through advanced nitrile-dipping technology that commands premium positioning in chemical-intensive applications. Ansell Limited competes via specialized cut-resistant formulations targeting mechanized harvest equipment operators.
Agricultural gloves are engineered hand-protection garments constructed from leather hides, woven cotton, polymer-coated fabrics, or dipped elastomers, typically measuring 0.3–1.2 mm in palm thickness and rated for abrasion resistance under EN 388 or ASTM D3389 protocols. Their primary purpose is to shield workers from lacerations, chemical exposure, thermal hazards, and biological contaminants during crop cultivation, livestock handling, and pesticide application. Leather gloves occupy the largest volume share in heavy-duty tillage and thorny brush clearing where puncture resistance determines replacement cycles. PVC-coated variants represent the fastest-expanding material category as viticulture and orchard operations prioritize liquid-chemical barrier properties. Synthetic fiber segments, particularly aramid and HPPE blends, concentrate margin pools where landscaping professionals specify ANSI A4–A6 cut levels for powered-trimmer operation.
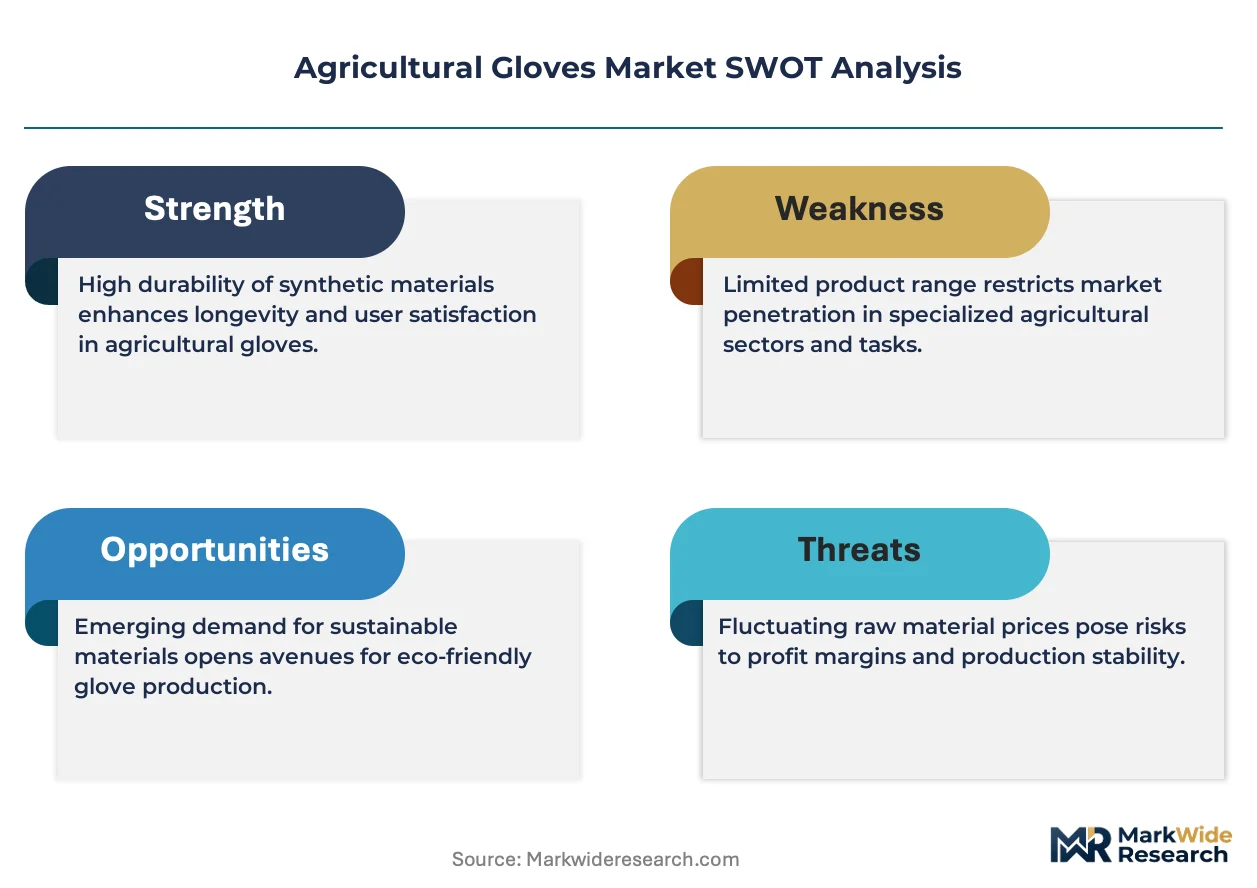
OSHA's hand-protection standards under 29 CFR 1910.138 mandate employer-provided gloves where exposure to skin-absorbed chemicals or laceration hazards exists, directly shaping procurement volume in US commercial agriculture. The EU's PPE Regulation and REACH restrictions on chromium VI in leather tanning are forcing material substitutions across European supply chains. India's BIS certification requirements for industrial safety gloves are creating compliance barriers for unorganized domestic manufacturers. Stakeholders must monitor divergence between emerging biodegradable polymer formulations and incumbent petroleum-based elastomers when allocating R&D budgets across sustainability and performance targets.
Market Dynamics
EU REACH restrictions on chromium VI in leather tanning are forcing material substitutions across European supply chains, while automated knitting facilities are rotating competitive advantage away from manual assembly operations toward manufacturers with captive yarn-to-glove production.
Growth Catalysts
- OSHA hand-protection mandates:US employer-provided glove requirements under 29 CFR 1910.138 directly shape procurement volume in commercial agriculture where skin-absorbed chemical exposure exists.
- Contract labor expansion:Large-scale wheat and rice estates in India's Punjab and Haryana states drive bulk purchasing of durable synthetic fiber gloves for seasonal workforce protection.
- Nitrile-dipping advances:Chemical-intensive viticulture and orchard operations prioritize liquid-chemical barrier properties, accelerating PVC-coated and advanced nitrile variant adoption.
Market Restraints
- Petroleum-based elastomer dependency:Nitrile and PVC feedstock costs track crude oil volatility, compressing margins for dipped-glove manufacturers without backward integration into polymer supply.
- European supply chain reconfiguration:REACH-compliant chromium-free leather tanning requires capital retooling for tanneries supplying heavy-duty tillage glove producers.
- Biodegradable polymer performance gap:Emerging plant-based elastomers currently fail EN 388 abrasion resistance benchmarks, limiting substitution in mechanized harvest applications.
Strategic Opportunities
- Brazil commercial farming safety mandates:Expanding glove procurement requirements across mechanized soybean and sugarcane operations create volume openings for certified chemical-resistant suppliers.
- Aramid-HPPE blend penetration:Landscaping professionals specifying ANSI A4–A6 cut levels for powered-trimmer operation concentrate margin pools in high-performance synthetic fiber segments.
- Direct-to-cooperative distribution:Industrial-scale farm cooperatives are consolidating purchasing through specialized agricultural safety distributors, bypassing traditional retail channels.
Industry Challenges
- BIS certification timelines:India's industrial safety glove standards create compliance barriers for unorganized domestic manufacturers, delaying market access for smaller producers.
- Multi-protocol testing burden:Simultaneous EN 388, ASTM D3389, and emerging biodegradable certification requirements strain R&D allocation across sustainability and performance targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Gloves Market |
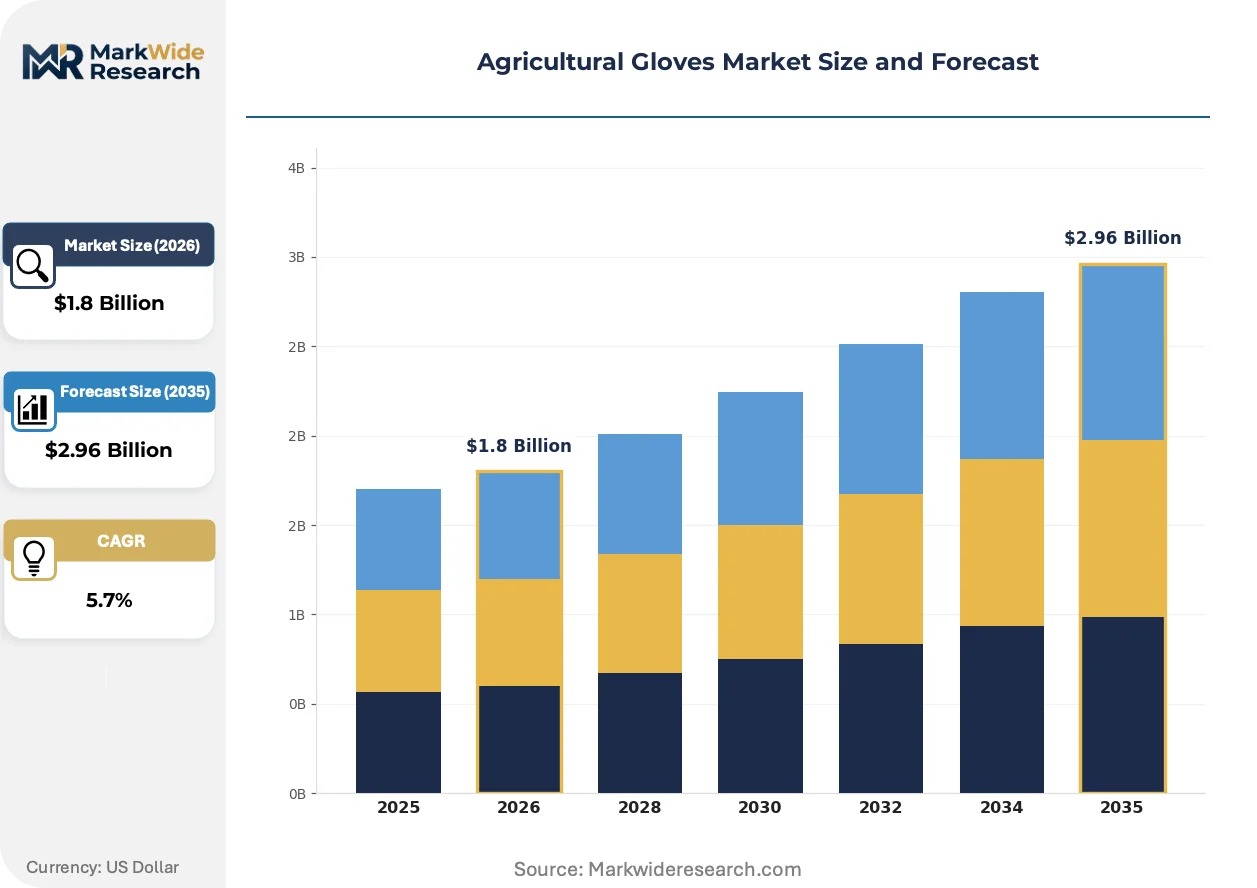
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leather Gloves, Cotton Gloves, PVC Coated Gloves, Rubber Gloves Application: Farming, Gardening, Horticulture, Pest Control Material: Natural Fiber, Synthetic Fiber, Neoprene, Latex End User: Farmers, Agricultural Workers, Garden Enthusiasts, Landscape Professionals |
| Companies Covered | Superior Glove Works Ltd., Hartalega Holdings, Ansell Limited, Towa Corporation, Magid Glove & Safety, Top Glove Corporation Bhd, Honeywell International Inc., Youngstown Glove Company, Showa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Gloves Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are actively splitting the market between petroleum-derived performance polymers and emerging bio-based alternatives, reshaping R&D priorities and supplier positioning simultaneously.
Biodegradable polymer formulations derived from corn starch and natural rubber latex are bifurcating the chemical-resistant glove segment. Viticulture operators in France and Italy are piloting these materials for pesticide application tasks despite 15-20% durability trade-offs against nitrile. The technology is compressing replacement cycle economics while opening premium positioning for sustainability-certified suppliers.
EU PPE Regulation (EU) 2016/425 tightened certification requirements for chemical-resistant hand protection in 2023. Module B+C2 conformity assessment procedures now mandate annual factory production control audits for Category III gloves. German and Dutch agricultural distributors are consolidating supplier bases to reduce compliance verification overhead, favoring manufacturers with in-house testing laboratories.
Buyer concentration among agricultural cooperatives is consolidating procurement decisions into centralized safety committees. Large-scale grain operations in Iowa and Illinois are unbundling glove purchasing from general PPE contracts, creating dedicated hand-protection specifications with performance-based renewal terms. This pattern is most visible in North American row-crop agriculture where seasonal labor scaling demands predictable unit economics.
Agricultural Gloves Market Segmentation
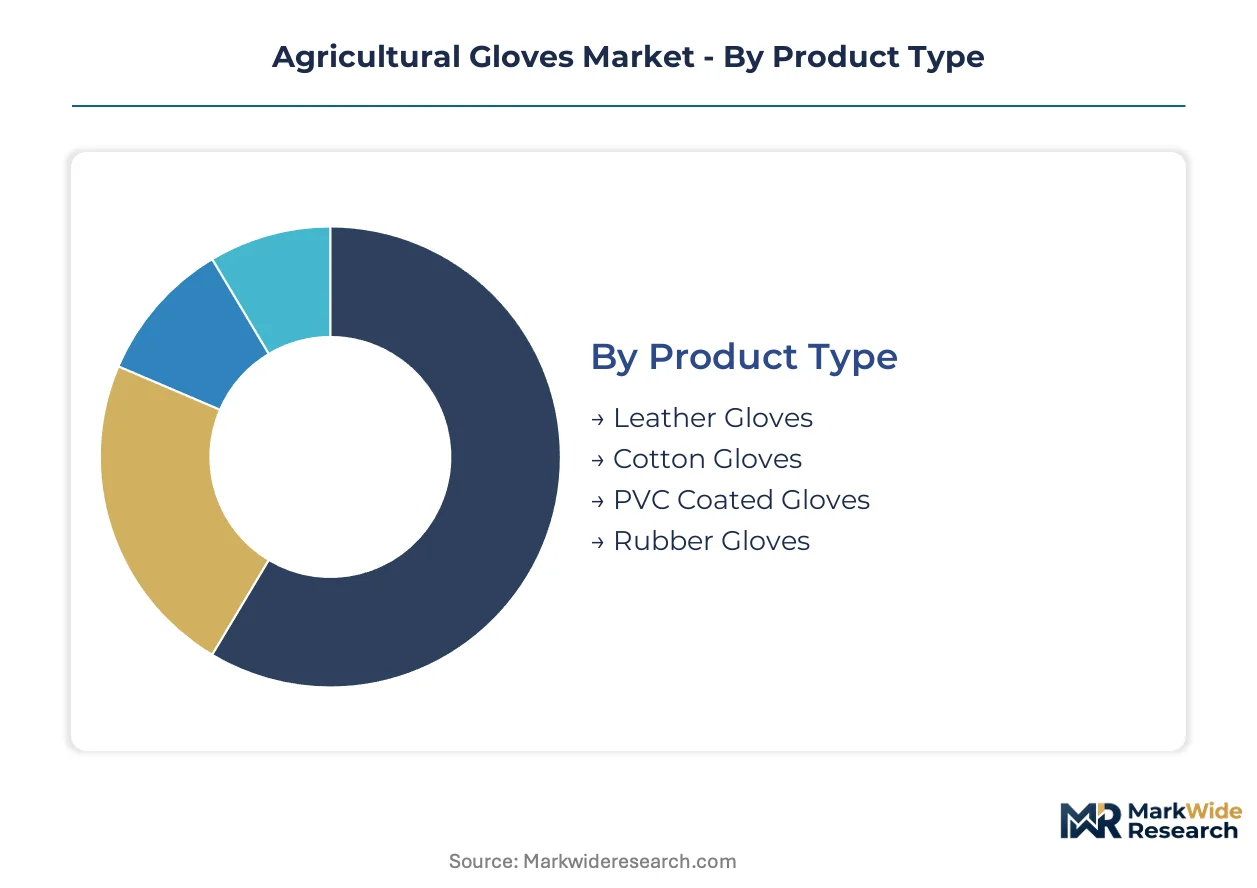
Segmentation in agricultural gloves reveals how procurement channels bifurcate between bulk commercial contracts and fragmented retail distribution. Material specifications and end-use intensity determine whether gloves flow through agricultural cooperatives, safety distributors, or garden center networks.
Product Type:
Channel mix splits sharply: leather and cotton variants dominate cooperative bulk purchasing, while PVC-coated and rubber gloves concentrate in specialized chemical-resistant distributors serving viticulture and pesticide application.
- Leather Gloves:Constructed from cowhide or goatskin with 0.8–1.2 mm palm thickness, these withstand abrasion from tillage equipment and thorny brush. Demand concentrates in Brazil's mechanized soybean operations where operator safety mandates drive replacement cycles for heavy-duty tillage crews.
- PVC Coated Gloves:Polyvinyl chloride-dipped shells provide liquid-chemical barrier properties critical for orchard pesticide application. French and Italian viticulture operators are expanding procurement fastest as EU PPE Regulation tightens certification requirements for chemical-resistant hand protection.
- Cotton Gloves:Woven natural fiber construction offers breathability for light-duty cultivation tasks. Garden center retail channels and smallholder farming supply stores in India's Punjab state move significant volume.
- Rubber Gloves:Latex and nitrile formulations deliver elasticity and chemical resistance for wet-condition handling. Landscape professionals in North American urban markets specify these for irrigation system maintenance.
Leather gloves dominate installed base across heavy tillage applications. PVC-coated variants are where expansion concentrates as chemical-intensive horticulture intensifies.
Application:
Cost-tier stratification separates commodity-grade gloves for seasonal labor from premium formulations for specialized horticulture. Volume scales inversely with unit margin across these four use cases.
- Farming:Large-scale wheat and rice estates in India's Haryana state drive bulk purchasing of durable synthetic fiber gloves for contract labor protection. OSHA hand-protection mandates under 29 CFR 1910.138 directly shape procurement volume in US commercial agriculture.
- Horticulture:Precision crop management demands cut-resistant aramid-HPPE blends for greenhouse and nursery operations. German agricultural distributors are consolidating supplier bases to reduce compliance verification overhead for Category III gloves.
- Gardening:Consumer-grade cotton and light latex variants flow through home improvement retailers and e-commerce platforms. Replacement cycles accelerate in suburban markets with seasonal landscaping activity.
- Pest Control:Chemical-resistant nitrile-dipped gloves protect against skin-absorbed pesticide exposure. REACH restrictions on chromium VI in leather tanning are forcing material substitutions across European supply chains serving this segment.
Farming commands the largest volume footprint. Horticulture is climbing the fastest as protected cultivation expands.
Material:
Supply concentration tracks petroleum-based elastomer dependency against emerging biodegradable alternatives. Performance benchmarks and sustainability certifications create divergent margin pools.
- Natural Fiber:Cotton and wool blends offer biodegradability and moisture absorption for dry-climate cultivation. Indian BIS certification requirements create compliance barriers for unorganized domestic manufacturers of these commodity-grade products.
- Synthetic Fiber:Aramid and HPPE blends achieve ANSI A4–A6 cut levels for powered-trimmer and mechanized harvest equipment operation. Landscaping professionals in Iowa and Illinois are unbundling glove purchasing from general PPE contracts to specify these performance tiers.
- Neoprene:Chloroprene rubber delivers thermal stability and chemical resistance across temperature extremes. Orchard operations in Mediterranean climates specify neoprene for early-morning harvest conditions.
- Latex:Natural rubber latex provides tactile sensitivity and elasticity for precision handling tasks. Corn starch-derived biodegradable formulations are bifurcating this segment despite 15-20% durability trade-offs.
Natural fiber holds the broadest installed base. Synthetic fiber is gaining share fastest as mechanization intensifies.
End User:
Customer-type fragmentation separates price-sensitive seasonal workers from specification-driven professionals. Procurement authority concentrates differently across each user category.
- Farmers:Owner-operators and estate managers prioritize durability and total cost of ownership in bulk purchasing decisions. Brazil's commercial farming safety mandates are expanding glove procurement requirements across mechanized sugarcane operations.
- Agricultural Workers:Contract labor on large-scale estates receives employer-provided protection under OSHA and equivalent national regulations. India's Punjab and Haryana states show concentrated demand for durable synthetic fiber gloves.
- Garden Enthusiasts:Residential consumers purchase through retail and e-commerce channels with brand sensitivity and aesthetic preferences. Replacement cycles follow seasonal gardening activity patterns.
- Landscape Professionals:Municipal and commercial landscaping contractors specify ANSI-rated cut resistance for powered equipment operation. Direct-to-cooperative distribution is consolidating purchasing through specialized agricultural safety distributors.
Farmers and agricultural workers together dominate volume. Landscape professionals are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across agricultural economies. Price-sensitive contract labor markets in South Asia drive volume through commodity-grade synthetic fiber gloves, while premium chemical-resistant formulations command sustained margins in European viticulture and North American mechanized operations.
United States
OSHA's 29 CFR 1910.138 mandates employer-provided hand protection where skin-absorbed chemical exposure exists, directly shaping procurement volume across Iowa and Illinois grain cooperatives. Large-scale operations are unbundling glove purchasing from general PPE contracts to specify ANSI-rated cut resistance for powered equipment. The Corn Belt's industrial-scale farm cooperatives now consolidate decisions through centralized safety committees.
Brazil
Commercial farming safety mandates are expanding glove procurement requirements across mechanized soybean and sugarcane operations in Mato Grosso and São Paulo states. Operator protection regulations for agricultural machinery are accelerating replacement cycles for heavy-duty tillage crews. Certified chemical-resistant suppliers are capturing volume openings as estate managers professionalize safety protocols.
India
Contract labor on large-scale wheat and rice estates in Punjab and Haryana states drives bulk purchasing of durable synthetic fiber gloves for seasonal workforce protection. BIS certification requirements for industrial safety gloves create compliance barriers for unorganized domestic manufacturers. The Indo-Gangetic Plain's agricultural labor intensity concentrates demand in commodity-grade natural fiber and synthetic blends.
Germany
EU PPE Regulation (EU) 2016/425 tightened certification requirements for chemical-resistant hand protection, mandating annual factory production control audits for Category III gloves. Agricultural distributors are consolidating supplier bases to reduce compliance verification overhead, favoring manufacturers with in-house testing laboratories. The Rhine-Ruhr industrial corridor anchors distribution networks serving viticulture operators across Baden-Württemberg and Rhineland-Palatinate.
France
REACH restrictions on chromium VI in leather tanning are forcing material substitutions across supply chains serving pesticide-intensive viticulture. French and Italian vineyard operators are piloting biodegradable polymer formulations derived from corn starch despite durability trade-offs against nitrile. The Bordeaux and Champagne clusters are compressing replacement cycle economics while opening premium positioning for sustainability-certified suppliers.
Agricultural Gloves Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the agricultural gloves market. The vendor base splits between automated knitting facilities with captive yarn-to-glove production and manual assembly operations dependent on outsourced components. Three strategic archetypes dominate: North American manufacturers leveraging rapid fulfillment for industrial-scale farm cooperatives, Asian producers anchoring positions through advanced dipping technology for chemical-intensive applications, and European specialists competing via cut-resistant formulations for mechanized harvest equipment. Competitive moves concentrate on backward integration into polymer supply and geographic expansion into Brazil's expanding commercial farming sector.
Among Malaysia-based manufacturers, Hartalega Holdings and Top Glove Corporation Bhd occupy positions exemplifying scale-driven nitrile-dipping specialization. North American fabricators including Superior Glove Works Ltd. and Ansell Limited represent the technology-forward tier, with the former leveraging regional manufacturing bases and the latter anchoring cut-resistant formulation expertise. Japanese specialists Towa Corporation and Showa Group sit within the precision-engineering archetype, while diversified industrial conglomerates such as Honeywell International Inc. exemplify portfolio-breadth strategies spanning multiple PPE categories.
| Leading Market Players |
|---|
| Superior Glove Works Ltd. |
| Hartalega Holdings |
| Ansell Limited |
| Towa Corporation |
| Magid Glove & Safety |
| Top Glove Corporation Bhd |
| Honeywell International Inc. |
| Youngstown Glove Company |
| Showa Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for nitrile-dipped gloves concentrate pricing power with Malaysian manufacturers holding captive polymer supply, while REACH-compliant leather tanneries in Italy and Spain face capital retooling costs that transmit into premium positioning for heavy-duty tillage segments.
Pricing Analysis
After-market service contracts for cut-resistant glove replacement programs anchor lifetime value in North American farm cooperatives. Three-tier pricing structure across premium ANSI A6-rated aramid blends, standard nitrile-dipped chemical barriers, and economy cotton work gloves stratifies procurement decisions. Cost compression in synthetic fiber segments intensifies as petroleum-based elastomer feedstock volatility squeezes dipped-glove margins. Contract labor purchasers in India's Punjab state exhibit highest price sensitivity, while German viticulture operators prioritize certification-grade chemical resistance over unit economics.
Supply Chain Analysis
Strait of Malacca transit lanes underpin nitrile and latex raw material flows from Southeast Asian petrochemical hubs to glove manufacturing centers. Malaysia, Thailand, and Indonesia anchor global dipped-elastomer production capacity. Nitrile butadiene rubber, polyvinyl chloride resin, and chromium-free tanning agents constitute critical input dependencies. Single-source vulnerability concentrates in Malaysian nitrile-dipping facilities serving European Category III certification requirements. Distribution runs through specialized agricultural safety distributors consolidating cooperative purchasing in Iowa, Illinois, and Brazil's Mato Grosso state.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural gloves constitute a high-growth disruption as EU PPE Regulation (EU) 2016/425 mandates annual factory audits for chemical-resistant hand protection, forcing supplier base consolidation and opening margin expansion for compliant manufacturers.
For Market Incumbents: Shield market position by accelerating backward integration into polymer supply to offset petroleum-based elastomer cost volatility, and secure in-house EN 388 testing laboratories to reduce compliance verification overhead as German distributors consolidate supplier bases against REACH restrictions on chromium VI tanning. For New Entrants and Emerging Players: BIS certification fast-track pathways for industrial safety gloves present entry corridors into India's Punjab and Haryana contract labor markets, where unorganized domestic manufacturers face compliance barriers; target biodegradable polymer formulations for French and Italian viticulture pilot programs as sustainability-certified positioning opens premium pricing tiers. For Investors and Strategic Acquirers: Long-term, this sits as a defensive consolidation play because agricultural labor protection mandates are hardening across Brazil's commercial farming sector and OSHA's 29 CFR 1910.138 enforcement is deepening employer liability exposure; acquisition targets should exhibit captive yarn-to-glove production and Category III certification infrastructure, with the signal to watch being distributor consolidation velocity in German and Dutch agricultural supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive nitrile and PVC feedstock production insulates margins from crude oil volatility affecting Malaysian manufacturers. |
| Category III Certification Investment | EU PPE Regulation (EU) 2016/425 compliance opens access to German and French viticulture distributor networks consolidating supplier bases. |
| Biodegradable Polymer R&D Partnership | Corn starch and natural rubber latex formulations capture sustainability premiums in French vineyard pesticide application trials. |
| Direct-to-Cooperative Distribution Buildout | Bypassing traditional retail channels captures volume from Iowa and Illinois grain cooperatives unbundling glove purchasing from general PPE contracts. |
| Aramid-HPPE Blend Capacity Expansion | ANSI A4–A6 cut level production serves North American landscape professionals specifying powered-trimmer protection. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with agricultural cooperative safety directors, Malaysian glove manufacturing plant managers, German agricultural distribution channel partners, and Italian viticulture estate operators, validated against secondary sources including EU PPE Regulation (EU) 2016/425 conformity assessment databases, OSHA enforcement records under 29 CFR 1910.138, BIS industrial safety certification registries, and customs trade data for nitrile and latex raw material flows, with bottom-up volume estimates triangulated against top-down market sizing across material and application segments.
Across the projection horizon, the analytical framework modeled product type splits between leather, PVC-coated, cotton, and rubber glove categories; application stratification across farming, horticulture, gardening, and pest control; material dependencies tracking natural fiber, synthetic fiber, neoprene, and latex inputs; and end-user fragmentation among farmers, agricultural workers, garden enthusiasts, and landscape professionals, with CAGRs derived from regression analysis of procurement volume trends against regulatory mandate implementation timelines and mechanization intensity indices.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA enforcement, EU REACH restriction expansion, and Brazilian commercial farming safety mandate adoption; material deviation in petroleum feedstock pricing or biodegradable polymer performance benchmarks would warrant model refresh. Practitioners should keep alternative scenarios live as India's BIS certification timeline enforcement and German distributor consolidation velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Agricultural Films and Bonding Market