
 Agriculture Bags Market | 2026-2036
Agriculture Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Bags Market Outlook
Multi-source procurement for woven and laminated agricultural packaging is decoupling from traditional single-source polymer supply contracts. Berry Global leverages vertical integration across resin conversion and film extrusion to control input costs. Mondi Group anchors European demand through kraft paper and sustainable fiber-based solutions. Greif competes in industrial bulk formats with steel and plastic drum adjacencies that extend its agriculture bag portfolio.
Agriculture bags are purpose-built containment systems manufactured from polyethylene films, woven polypropylene, natural jute fibers, or compostable polymers, designed to protect seeds, fertilizers, and harvested crops from moisture, pests, and mechanical damage during storage and transport. Polyethylene bags dominate volume due to moisture barrier performance and heat-seal compatibility with automated filling lines. Jute bags retain structural importance in food-grade grain exports where breathability prevents condensation spoilage. Biodegradable bags represent the fastest-growing product type as ECHA REACH restrictions on conventional microplastics intensify reformulation timelines across European supply chains.
FDA food-contact regulations govern agriculture bags destined for seed and grain handling in the United States, while EPA guidelines on pesticide container residue shape secondary-use prohibitions. EU REACH and F-Gas Regulation frameworks constrain fluorinated barrier coatings, pushing converters toward bio-based alternatives. Stakeholders must monitor evolving compostability certifications and extended producer responsibility schemes to secure market access and avoid stranded inventory in regulated jurisdictions.
Market Dynamics
EU REACH restrictions on conventional microplastics are forcing converters toward bio-based polymer formulations, compressing reformulation timelines and reshaping competitive positioning across European supply chains.
Growth Catalysts
- Precision Agriculture Expansion:Seed packaging demand accelerates as GPS-guided planting systems expand acreage coverage and require specialized moisture-barrier containment for treated seed varieties.
- EU Green Deal Packaging Rules:Mandatory compostability targets under the EU Green Deal framework create regulatory pull for biodegradable polymer formulations in member state agricultural sectors.
- India PLI Scheme Incentives:Production-linked incentive schemes for domestic manufacturing are reshaping supply chain geography and attracting woven polypropylene capacity expansion to Gujarat and Maharashtra clusters.
Market Restraints
- Polypropylene Resin Volatility:Feedstock cost swings in naphtha-derived polypropylene constrain margin predictability for woven bag converters operating on thin conversion spreads.
- Fluorinated Barrier Restrictions:EU F-Gas Regulation constraints on perfluorinated coatings eliminate high-performance moisture barrier options without fully mature bio-based replacements.
- Jute Substitution Pressure:Natural fiber bag demand faces displacement from laminated polyethylene alternatives offering superior automated filling line compatibility.
Strategic Opportunities
- Biodegradable Seed Packaging:Compostable polymer formulations for precision agriculture seed containment represent underpenetrated white space with premium pricing potential.
- Extended Producer Responsibility Schemes:France and Germany's advancing EPR frameworks for agricultural plastics create first-mover advantage for closed-loop collection infrastructure investment.
- Kraft Paper Convergence:Mondi Group's fiber-based solutions demonstrate channel opening for paper-laminated hybrid formats in European organic grain export segments.
Industry Challenges
- Compostability Certification Timelines:EN 13432 and OK Compost HOME certification processes create 18-24 month product launch delays for bio-based formulations.
- Heat-Seal Equipment Retrofit Costs:Automated filling line reconfiguration for biodegradable film sealing parameters demands capital outlay that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Bags Market |
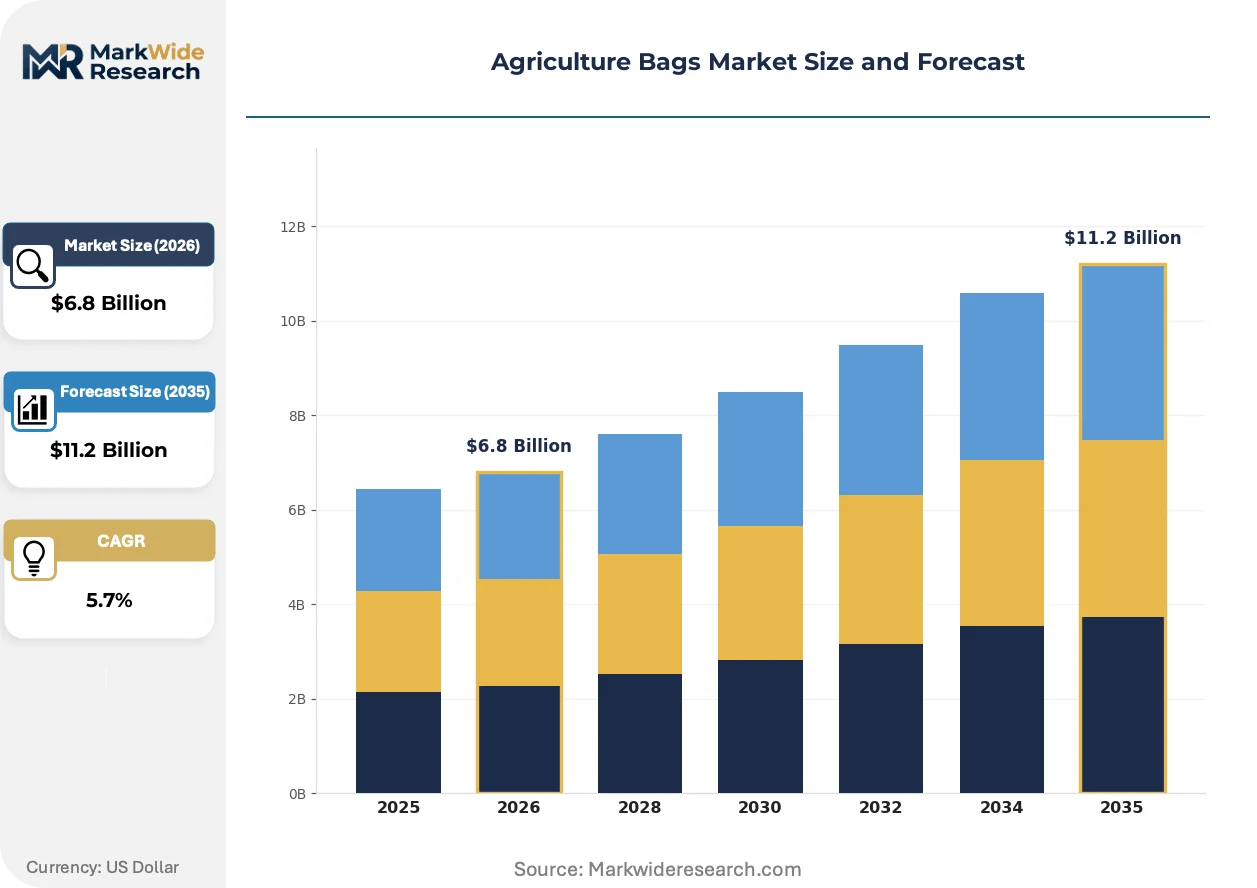
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Bags, Jute Bags, Paper Bags, Biodegradable Bags End Use: Crops, Seeds, Fertilizers, Pesticides Size: Standard Size, Custom Size, Bulk Size, Retail Size Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Berry Global, Mondi Group, Greif, Sonoco Products Company, Amcor, LC Packaging, NNZ Group, ProAmpac, ULINE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Bags Market Strategic Shifts
Active reformulation of barrier coating chemistry and procurement model fragmentation are compressing traditional supply relationships while opening channel entry points for specialty converters.
Multilayer coextruded films with bio-based outer layers and functionalized inner barriers are modularizing the agriculture bag construction process. Seed treatment facilities in Iowa and São Paulo state are piloting these formats for high-value hybrid corn varieties. The technology is modularizing converter capabilities by separating barrier performance from structural substrate sourcing.
EU F-Gas Regulation phase-down schedules for perfluorinated compounds are eliminating incumbent moisture barrier chemistries from REACH-registered formulations. Agricultural packaging converters face reformulation deadlines without fully scaled bio-based alternatives achieving equivalent water vapor transmission rates. German and Dutch grain exporters are accelerating kraft paper laminated trials as fluorinated coating inventories deplete.
Buyer consolidation among multinational seed companies is compressing supplier qualification cycles and unbundling regional procurement from global master agreements. Corteva and Bayer crop science divisions now run parallel tender processes for North American versus European packaging specifications. India-based woven bag manufacturers report lengthening payment terms as buyer concentration shifts negotiating leverage toward input suppliers with captive resin conversion.
Agriculture Bags Market Segmentation
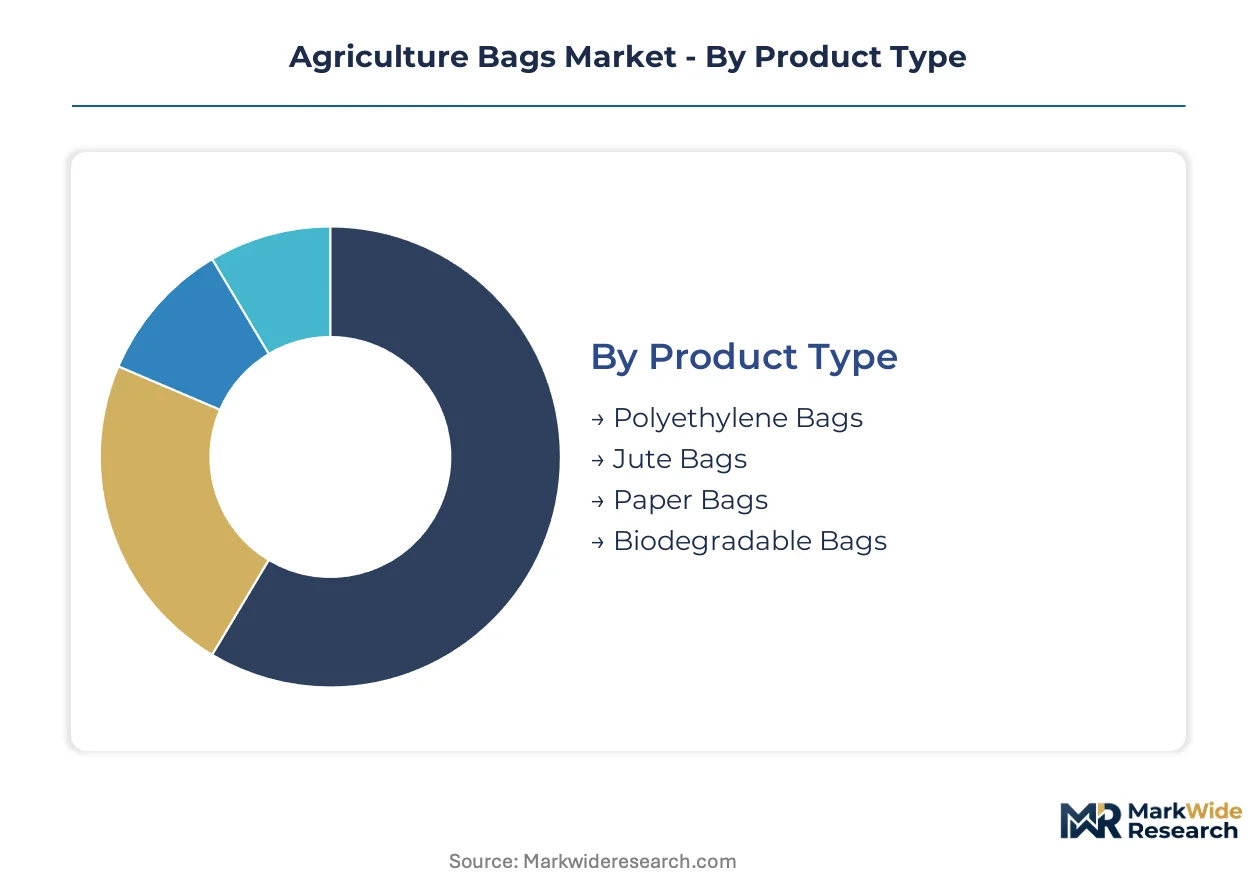
Agriculture bag specifications diverge sharply across crop handling workflows, moisture sensitivity thresholds, and automated filling compatibility. Material selection and dimensional standards directly determine barrier performance, regulatory compliance, and total cost of ownership for end-users.
Product Type:
Material chemistry and barrier architecture define functional performance against moisture ingress, pest penetration, and mechanical stress during field handling.
- Polyethylene Bags:Multilayer coextruded films deliver superior moisture vapor transmission resistance and heat-seal compatibility with high-speed automated filling lines. Demand concentrates in North American corn belt seed treatment facilities where treated hybrid varieties require hermetic containment.
- Biodegradable Bags:Compostable polymer formulations—PLA, PBAT, and starch blends—degrade under industrial composting conditions per EN 13432 certification. European grain exporters in Germany and France are adopting these formats ahead of EU Green Deal packaging mandates, despite 40-60% cost premiums over conventional polyethylene.
- Jute Bags:Natural fiber construction provides breathability that prevents condensation spoilage in tropical grain storage. Indian basmati rice exporters and Bangladesh jute mills maintain procurement contracts for food-grade export certification.
- Paper Bags:Kraft paper laminates with bio-based moisture barriers serve organic grain segments where plastic-free positioning commands shelf price premiums. Mondi Group's European production lines supply laminated formats to Dutch and German organic cooperatives.
Mature deployment sits with polyethylene formats across industrial-scale seed operations. Newer deployment is concentrated in biodegradable formulations as ECHA REACH restrictions on conventional microplastics compress reformulation timelines.
End Use:
Application-specific containment requirements shape material thickness, closure mechanisms, and secondary labeling for chemical hazard communication.
- Seeds:Precision agriculture expansion drives demand for moisture-barrier packaging with tamper-evident closures and GPS-tracked lot coding. Treated seed varieties in Iowa and São Paulo state require fluorinated barrier coatings that face phase-down under EU F-Gas Regulation schedules.
- Crops:Post-harvest grain storage demands breathability for moisture equilibrium or hermetic sealing for fumigation protocols. Jute dominates Indian wheat procurement while laminated polyethylene captures Brazilian soybean export volumes.
- Fertilizers:Hygroscopic nutrient formulations require multilayer barriers against caking and moisture-induced degradation. Bulk tote formats with PE liners displace woven polypropylene in North American nitrogen distribution.
- Pesticides:EPA container residue regulations and EU CLP hazard labeling mandate specialized chemical-resistant constructions with child-resistant closures. Secondary containment requirements prohibit reuse for food-contact applications.
Volume concentration aligns with seed packaging as precision agriculture acreage expands. Fastest share gains are appearing in pesticide containment as regulatory labeling complexity increases.
Size:
Dimensional standardization versus customization reflects trade-offs between automated handling efficiency and crop-specific bulk density requirements.
- Bulk Size:One-tonne flexible intermediate bulk containers (FIBCs) and 50-kg woven sacks serve grain elevator intake and containerized export. Indian PLI scheme incentives are expanding domestic woven polypropylene capacity for 50-kg fertilizer sacks.
- Standard Size:25-kg and 10-kg formats align with retail agricultural cooperative stocking and smallholder purchasing patterns. These dimensions optimize pallet cube utilization for regional distribution.
- Custom Size:Seed companies specify non-standard dimensions for proprietary metering equipment compatibility. Corteva and Bayer crop science divisions tender separately for North American versus European packaging specifications.
- Retail Size:1-kg to 5-kg formats serve home garden and specialty crop segments through garden center channels. Laminated paper and stand-up pouches dominate this premium-priced tier.
Equipment compatibility locks in standard sizes across cooperative distribution. Custom formats are expanding most quickly in precision agriculture seed segments where proprietary planting systems dictate containment geometry.
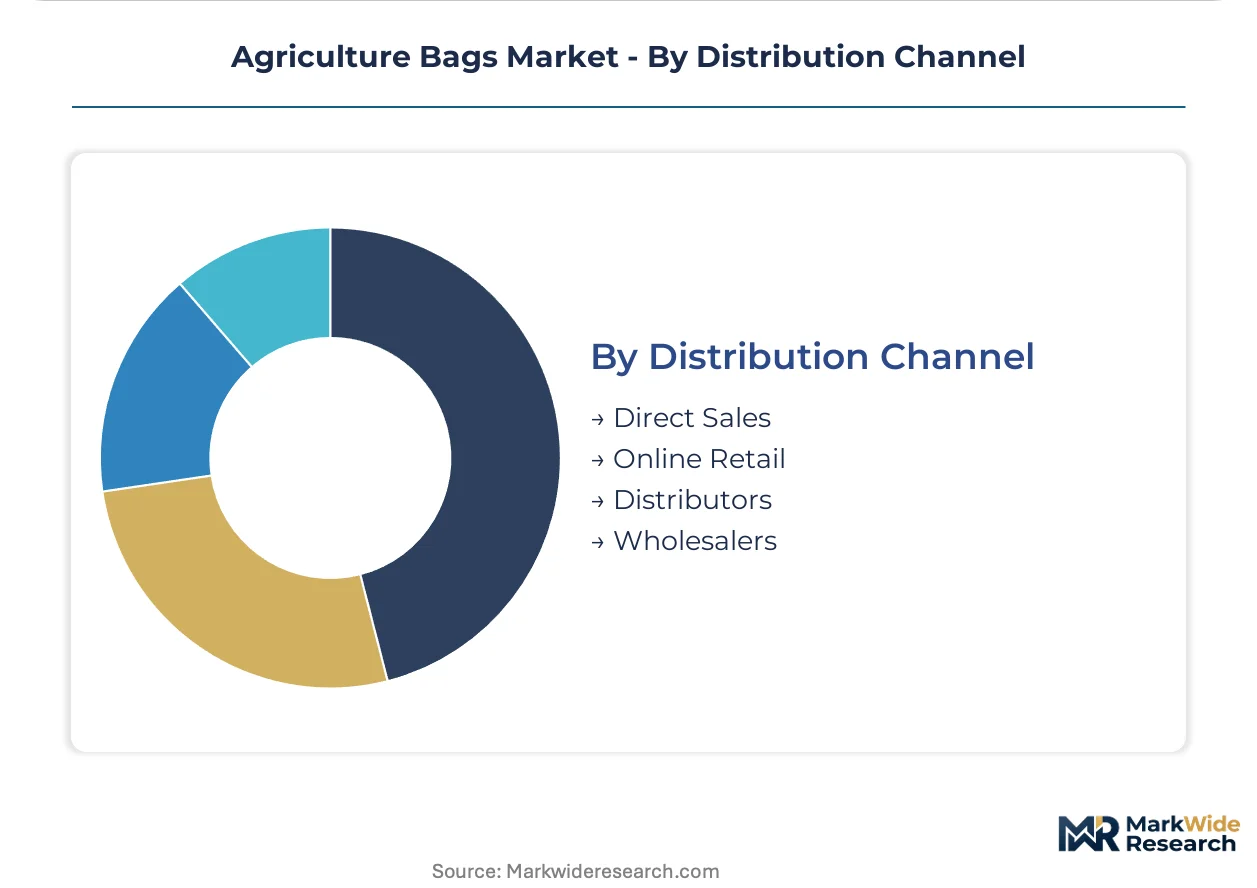
Distribution Channel:
Channel selection determines payment terms, technical service intensity, and geographic reach into fragmented agricultural end-user bases.
- Distributors:Regional agricultural supply distributors maintain inventory positions for planting season demand surges and provide credit terms to cash-constrained farm operations. These intermediaries dominate North American and European input supply.
- Direct Sales:Multinational seed and agrochemical companies contract directly with converters for global master agreements with regional specification variants. Buyer consolidation is compressing supplier qualification cycles and extending payment terms.
- Wholesalers:Volume aggregators serve developing market smallholders through informal supply chains with minimal technical support. Price competition is intense and quality verification limited.
- Online Retail:E-commerce platforms are penetrating home garden and specialty organic segments with direct-to-farmer fulfillment. This channel remains marginal for bulk agricultural inputs due to logistics cost structures.
Established volume flows through distributor networks with seasonal inventory financing. Direct procurement is climbing fastest as buyer consolidation enables unbundled regional tendering from global agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin production clusters in Texas and Louisiana anchor North American supply chains for woven agricultural packaging. Gujarat's petrochemical corridors feed South Asian converter demand. German chemical engineering expertise shapes European barrier coating innovation.
United States
Corn belt seed treatment facilities in Iowa and Illinois drive precision agriculture packaging demand for moisture-barrier containment. EPA container residue regulations govern secondary-use prohibitions for pesticide bags. Houston-Galveston petrochemical corridors supply polyethylene resin to domestic film extrusion operations.
Germany
Organic grain exporters in Lower Saxony and Schleswig-Holstein pilot kraft paper laminated formats for plastic-free positioning. EU F-Gas Regulation phase-down schedules eliminate perfluorinated moisture barriers from REACH-registered formulations. Hamburg port logistics clusters handle transshipment for Scandinavian and Baltic agricultural input distribution.
India
BIS certification requirements reshape domestic woven polypropylene manufacturing standards for fertilizer and grain sacks. PLI scheme incentives attract capacity expansion to Gujarat and Maharashtra industrial corridors. Basmati rice exporters in Punjab and Haryana maintain jute bag procurement contracts for food-grade export certification.
Brazil
Soybean export volumes through Santos port drive laminated polyethylene demand for containerized grain shipment. ANVISA agricultural input regulations govern pesticide packaging labeling and child-resistant closure mandates. São Paulo state seed treatment facilities pilot multilayer coextruded films for high-value hybrid corn varieties.
China
Dual carbon goals accelerate bio-based polymer formulation trials for compostable agricultural films. NMPA and MIIT standards govern food-contact packaging for seed and grain handling. Yangtze River Delta chemical engineering clusters develop barrier coating alternatives to fluorinated chemistries.
Agriculture Bags Market Competitive Environment
Capacity expansion dominates the current landscape as converters respond to EU Green Deal packaging mandates and India PLI scheme incentives. The vendor base spans multinational diversified packaging conglomerates, regional woven polypropylene specialists, and emerging bio-based material innovators. Three archetypes define competitive positioning: resin-integrated film extruders controlling input costs, fiber-based sustainable solution providers, and industrial bulk format specialists with drum adjacencies. Geographic expansion into Gujarat and Maharashtra clusters and portfolio diversification toward biodegradable formulations represent the dominant competitive moves.
Among diversified packaging conglomerates, Berry Global exemplifies resin-integrated positioning through captive polyethylene conversion capabilities. Mondi Group anchors European fiber-based demand through kraft paper and sustainable laminates. Greif occupies the industrial bulk format tier with steel and plastic drum portfolios extending into agricultural bag adjacencies.
| Leading Market Players |
|---|
| Berry Global |
| Mondi Group |
| Greif |
| Sonoco Products Company |
| Amcor |
| LC Packaging |
| NNZ Group |
| ProAmpac |
| ULINE |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging mandates gate qualified supply and premium-tier pricing access, compressing converter margins for non-compliant inventory while rewarding EN 13432-certified producers with 40-60% price premiums over conventional polyethylene formats.
Pricing Analysis
Service bundling separates certified biodegradable formulations with technical compliance support from unbundled commodity polyethylene sourced through spot resin markets. Three-tier pricing structure across premium, standard, and economy levels reflects EN 13432 certification grade, volume scale, and geographic delivery cost from Gujarat or Houston-Galveston clusters. Cost compression in standard polyethylene tiers is intensifying because polypropylene resin volatility constrains conversion spreads. Smallholder cooperatives and informal wholesalers exhibit highest price sensitivity; multinational seed companies with global master agreements demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
India PLI scheme domestic-content mandates are reshaping sourcing patterns for woven polypropylene capacity, displacing informal import channels with BIS-certified Gujarat and Maharashtra production. Raw material flows draw from naphtha-derived polypropylene in Texas and Louisiana, kraft pulp from Nordic forests, and bio-based PLA/PBAT from Yangtze River Delta chemical engineering clusters. Single-source vulnerability concentrates in fluorinated barrier coatings facing EU F-Gas Regulation phase-down without fully scaled bio-based replacements. Distribution runs through regional agricultural supply distributors with seasonal inventory financing for planting season demand surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
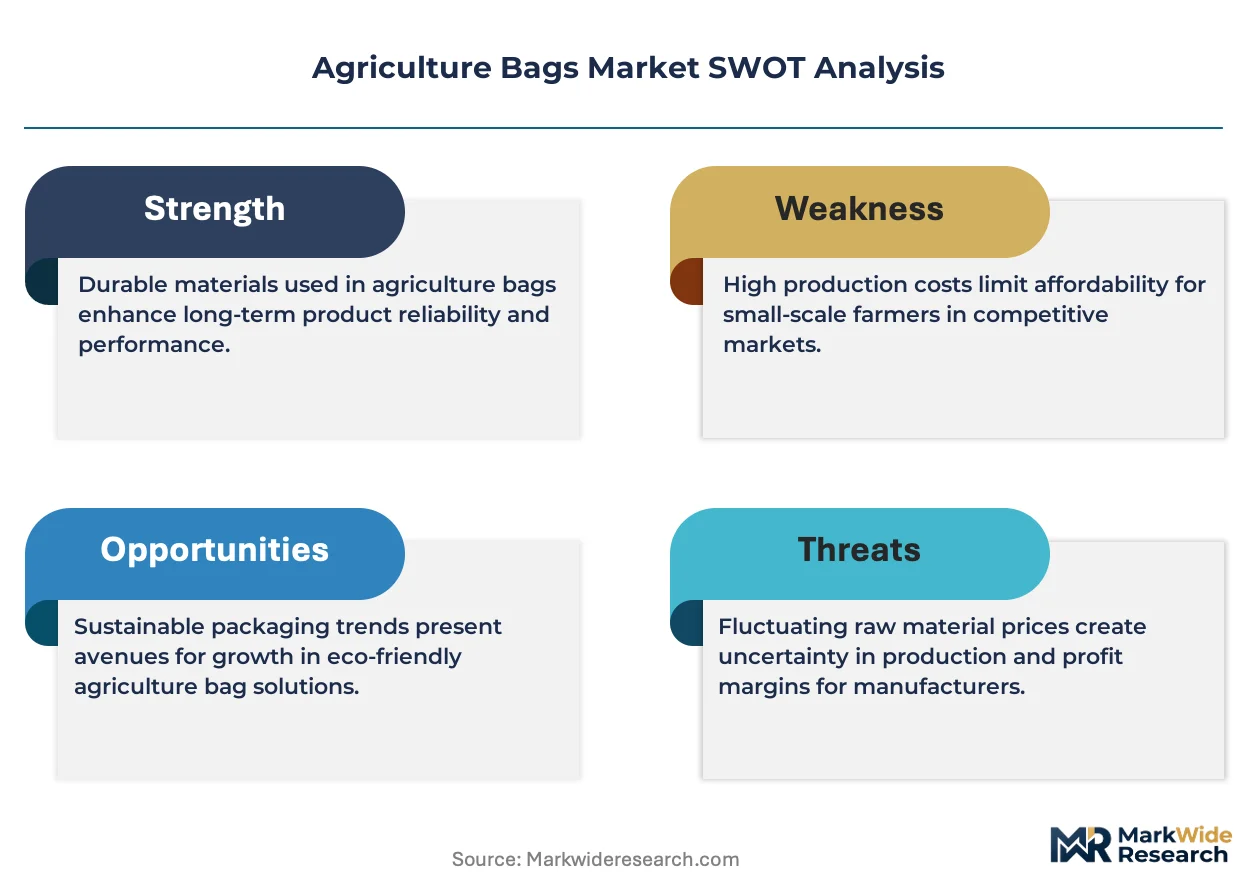
This market is a vertical-integration race where backward integration into captive resin conversion separates margin-defensible leaders from price-takers exposed to feedstock volatility.
For Market Incumbents: Deepen backward integration into polyethylene resin conversion to offset naphtha feedstock cost swings compressing woven bag margins. Prioritize EN 13432 certification investment ahead of EU Green Deal enforcement deadlines to avoid stranded inventory in regulated member states. Anchor capacity in Gujarat and Maharashtra clusters to capture India PLI scheme incentives and defend against emerging regional competitors. For New Entrants and Emerging Players: Capture biodegradable seed packaging white space in Iowa and São Paulo state precision agriculture corridors where fluorinated barrier phase-downs create specification gaps. Target kraft paper laminated formats for German and Dutch organic grain exporters seeking plastic-free positioning premiums. Lead with compostability certification technical service bundled with product supply to differentiate from commodity converters. For Investors and Strategic Acquirers: First-mover closed-loop collection infrastructure investment in France and Germany's advancing EPR frameworks is the leading indicator that agricultural plastics circularity economics are approaching viability. Position for 5-10 year consolidation of mid-tier woven polypropylene specialists lacking certification capabilities or resin integration. Monitor EU F-Gas Regulation reformulation deadline compliance rates as inflection signal for bio-based barrier coating scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Conversion | Berry Global's captive polyethylene supply chains demonstrate margin insulation against naphtha volatility. |
| Biodegradable Formulation Certification | EN 13432 and OK Compost HOME certifications unlock EU Green Deal-compliant market access with premium pricing. |
| Regional Capacity Expansion | Gujarat and Maharashtra cluster investments capture India PLI scheme incentives and BIS certification requirements. |
| Closed-Loop Collection Infrastructure | France and Germany EPR frameworks reward first-movers in agricultural plastics circularity systems. |
| Kraft Paper Laminate Development | Mondi Group's fiber-based solutions open organic grain export channels as fluorinated coatings phase down. |
Study Parameters
Document review covered customs and trade data, EU REACH and F-Gas Regulation filings, SEC 10-K disclosures from packaging conglomerates, and BIS certification registries, complemented by interviews with converter plant managers, multinational seed company procurement directors, agricultural cooperative supply planners, and technical R&D directors at barrier coating specialists. Bottom-up volume modeling from country-level seed and grain handling statistics was cross-referenced with top-down value estimates derived from resin price benchmarks and conversion margin analysis.
Historical shipment trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include material chemistry, end-use application, dimensional format, and distribution channel structure. CAGRs were derived from fitted trend extrapolation moderated by regulatory milestone timing and capacity expansion announcements. Forecast inputs incorporated EU Green Deal packaging mandate compliance timelines, India PLI scheme incentive disbursement patterns, and polypropylene resin price volatility bands.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bio-based barrier coating scalability, EPR framework implementation pace, and polypropylene feedstock cost trajectories. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution elasticity between material formats. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Hay Bags Market