
 Aquaculture Market | 2026-2036
Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Market Intelligence
Modular cage-array configurations is pivoting buyer choice toward scalable, site-adaptable marine farming systems. Mowi ASA leverages its integrated egg-to-market value chain across Norway, Scotland, and Canada to sustain volume leadership in Atlantic salmon. Grieg Seafood ASA anchors its competitive position through specialized large-smolt production in Rogaland, while Charoen Pokphand Foods PCL dominates Southeast Asian shrimp feed and hatchery supply through controlled channel networks.
Aquaculture denotes the controlled cultivation of aquatic organisms including finfish, mollusks, crustaceans, and aquatic plants in marine, brackish, or freshwater environments, typically operating at stocking densities of 10–50 kg per cubic meter depending on species and system design. Its primary commercial purpose centers on protein production for human consumption, pharmaceutical extraction, and ornamental trade. Fish Feed commands the largest product-type revenue pool due to recurring input demand across all farming scales, while Recirculating Systems represent the fastest-expanding technology segment as land and water access tightens in coastal Norway and British Columbia. Pharmaceutical Ingredients within the application dimension attracts premium margins from collagen and omega-3 refinement, though Food Production retains absolute volume dominance.
Norway's Food Safety Authority encloses strict sea-lice thresholds and escape-prevention standards that shape farm-site licensing and operational costs for Atlantic salmon producers. The EU's Aquaculture Strategy under the European Green Deal mandates reduced antibiotic use and nutrient discharge limits, redirecting investment toward closed-containment and integrated multi-trophic systems. Stakeholders must monitor how evolving marine spatial planning frameworks in Scotland, Chile, and Vietnam allocate near-shore zones between aquaculture, offshore wind, and conservation reserves.
Market Dynamics
Land-based recirculating aquaculture systems are compressing coastal site dependency as water-quality thresholds tighten and marine spatial planning restricts near-shore expansion. Producers now face capital allocation trade-offs between retrofitting existing cage arrays and migrating production inland.
Growth Catalysts
- EU Aquaculture Strategy nutrient discharge limits:The European Green Deal mandates reduced antibiotic use and discharge caps, redirecting investment toward closed-containment systems and integrated multi-trophic aquaculture configurations.
- Modular cage-array scalability:Site-adaptable marine farming systems enable producers to expand stocking densities in 10–50 kg per cubic meter ranges without full infrastructure replacement.
- Omega-3 and collagen refinement demand:Pharmaceutical ingredient extraction from farmed species attracts premium margins, diversifying revenue beyond food production volumes.
Market Restraints
- Fish meal and fish oil price volatility:Feed input costs fluctuate with wild-catch quotas, compressing margins for salmon and shrimp producers dependent on marine protein sources.
- Norwegian sea-lice threshold enforcement:The Norwegian Food Safety Authority's strict monitoring and escape-prevention standards elevate operational compliance costs and site licensing timelines.
- Plant-based protein substitution:Alternative seafood products from pea and algae proteins capture flexitarian consumer segments, constraining volume growth in conventional finfish categories.
Strategic Opportunities
- Vietnamese integrated shrimp-feed complexes:Controlled channel networks across Southeast Asia offer underpenetrated expansion nodes for hatchery-to-processing vertical coordination.
- Recirculating system technology convergence:Biofiltration and sensor automation integration enables land-based Atlantic salmon production in water-scarce regions previously excluded from aquaculture development.
- Scotland marine spatial planning reallocation:Near-shore zone designation between aquaculture and offshore wind creates licensing opportunities for deep-water cage platforms beyond traditional coastal boundaries.
Industry Challenges
- Veterinary and marine biology specialist shortages:Disease management and genetic breeding programs require scarce technical talent, extending recruitment cycles for large-smolt production facilities.
- Closed-containment certification timelines:Third-party aquaculture stewardship verification involves multi-year audit processes, delaying market access for new land-based entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Market |
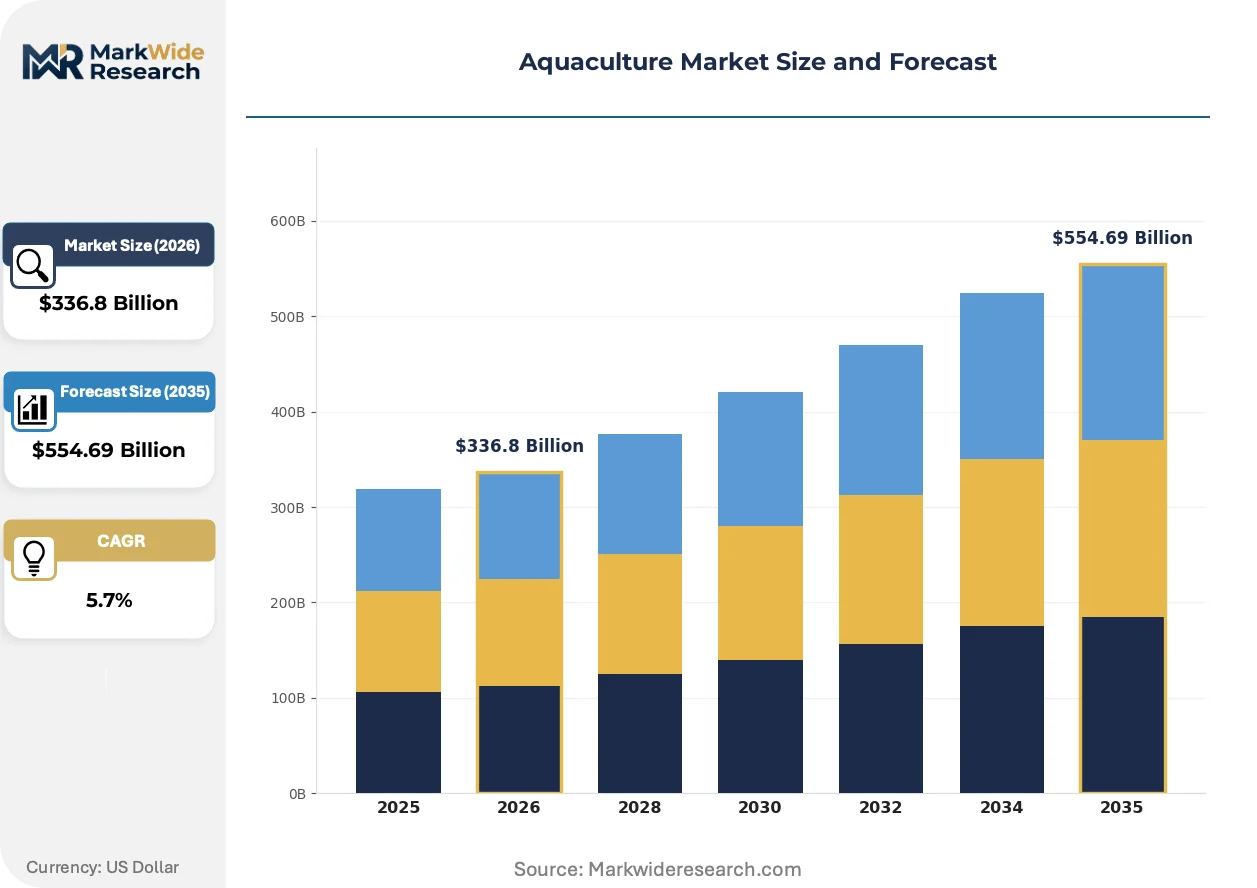
| Market Size in 2026 | $336.8 Billion |
| Market Size in 2035 | $554.69 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Feed, Shellfish Hatcheries, Aquatic Health Products, Breeding Stock, Aquatic Plants Technology: Recirculating Systems, Cage Culture, Flow-through Systems, Pond Culture, Biofloc Technology Application: Food Production, Ornamental Aquatics, Pharmaceutical Ingredients, Nutraceuticals, Animal Feed Ingredients End User: Fish Farmers, Seafood Processing Companies, Research Institutions, Aquaculture Equipment Suppliers |
| Companies Covered | Cooke Aquaculture Inc., Grieg Seafood ASA, Mowi ASA, Huon Aquaculture Group Limited, Charoen Pokphand Foods PCL, Lerøy Seafood Group ASA, Empresas AquaChile S.A., Multiexport Foods S.A., Cermaq Group AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Market Strategic Shifts & Innovations
Automation and biological monitoring systems are compressing mortality rates and feed conversion ratios across intensive production environments. Three developments are restructuring competitive positioning.
Sensor-integrated feeding systems is overtaking manual distribution protocols in large-scale salmon operations. Norwegian and Scottish producers deploy real-time biomass monitoring to adjust ration delivery, cutting feed waste by precise calibration. The technology is compressing cost differentials between high-volume incumbents and mid-scale challengers.
The EU F-Gas Regulation and parallel ECHA restrictions on synthetic refrigerants are accelerating cold-chain infrastructure retrofitting. Seafood processing facilities must replace hydrofluorocarbon-dependent systems with ammonia or CO2 alternatives, elevating capital intensity for export-oriented Chilean and Vietnamese plants. Smolt transportation and harvest logistics bear the highest compliance burden.
Direct contracting between retailers and land-based producers is fragmenting traditional auction-house procurement. British Columbia and Norwegian recirculating facilities now supply specified-origin Atlantic salmon to European supermarket chains, bypassing commodity spot markets. The shift is most visible in premium private-label seafood programs where traceability commands shelf-space allocation.
Aquaculture Market Segmentation
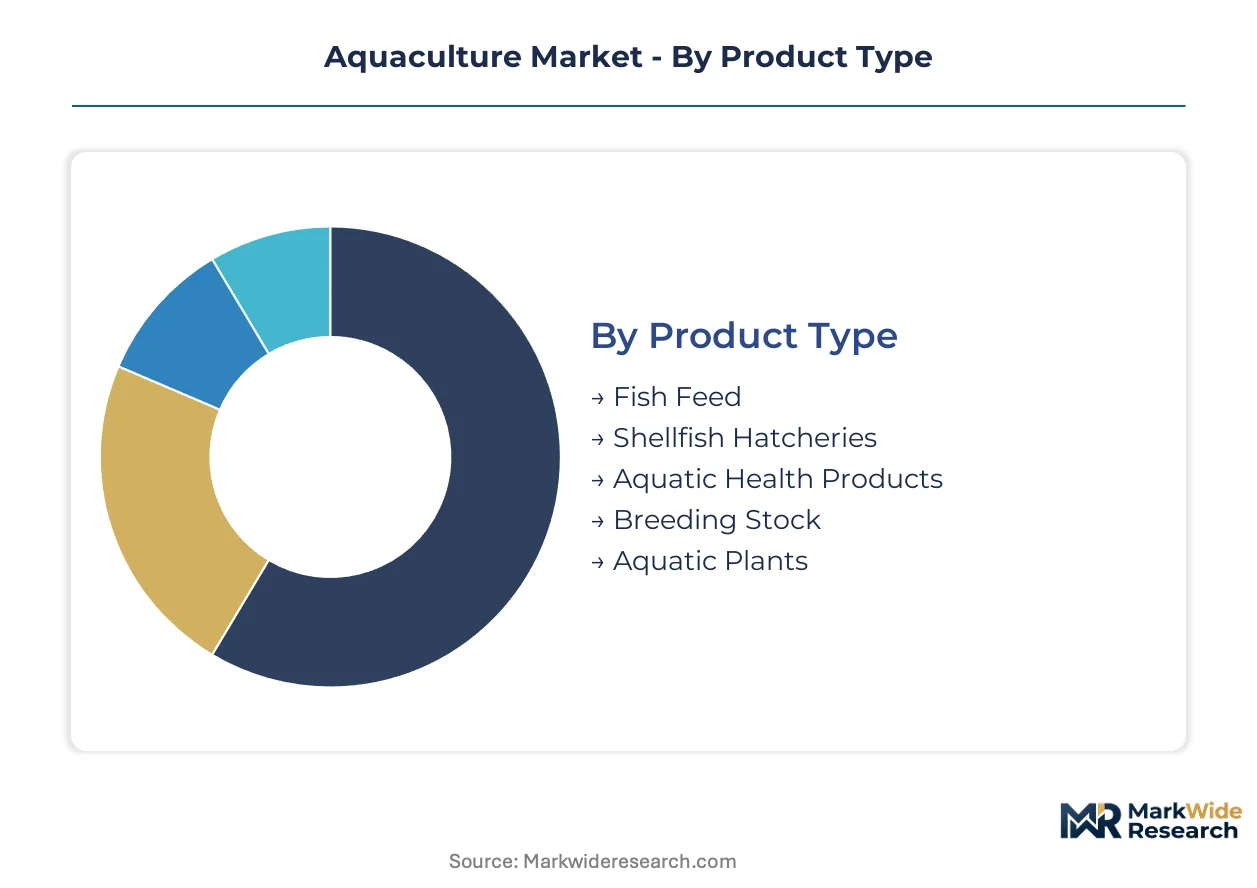
Segmentation in aquaculture reveals how capital allocation, regulatory pressure, and end-use specifications reshape procurement patterns across input suppliers and technology providers. Buyers differentiate by production scale, species specialization, and compliance requirements rather than price alone.
Product Type:
Buyers in this category separate by recurring input intensity versus specialized genetic or biological asset requirements.
- Fish Feed:Formulated diets containing 30-50% protein from fish meal, soybean, or insect meal sources depending on species nutritional profiles. Demand concentrates among Atlantic salmon producers in Norway and shrimp farmers in Vietnam as feed conversion ratios directly determine unit economics. Norwegian Mowi ASA and Thai Charoen Pokphand Foods PCL anchor procurement volumes through multi-year supply agreements.
- Shellfish Hatcheries:Controlled larval production facilities for oysters, mussels, and clams operating at billion-larva annual scales. Demand clusters in France, Spain, and British Columbia where marine spatial planning reserves near-shore zones for bivalve cultivation; climate-driven ocean acidification elevates hatchery dependency for seed reliability.
- Aquatic Health Products:Vaccines, antibiotics, and probiotics for disease prevention in intensive systems.
- Breeding Stock:Genetically selected broodstock for egg and fry production.
- Aquatic Plants:Seaweed and macroalgae cultivation inputs for food and biostimulant markets.
Volume sits with Fish Feed; growth tilts toward Aquatic Health Products as antibiotic restrictions tighten.
Technology:
Capital deployment in this category tracks land availability, water access constraints, and species-specific biological requirements.
- Recirculating Systems:Closed-loop aquaculture with mechanical and biological filtration achieving 90%+ water reuse rates. Deployment accelerates in water-scarce regions and jurisdictions with strict discharge limits; Norwegian and British Columbia producers retrofit existing sites while new entrants in Denmark and Netherlands build greenfield facilities.
- Cage Culture:Open-water net pens anchored in coastal or fjord environments at 10-50 kg per cubic meter stocking densities. Norway and Chile dominate installed base; Scottish and Canadian sites face marine spatial planning competition from offshore wind development.
- Flow-through Systems:Single-pass water exchange raceways for trout and salmon smolt production.
- Pond Culture:Extensive earthen basin systems for shrimp and tilapia in Southeast Asia and Latin America.
- Biofloc Technology:Microbial floc-based water quality management for intensive shrimp and tilapia.
Deployment share concentrates in Cage Culture; steepest expansion trajectory belongs to Recirculating Systems as licensing constraints harden.
Application:
End-use differentiation in this category separates commodity protein markets from premium extraction and specialty ingredient segments.
- Food Production:Finfish, crustacean, and mollusk harvest for direct human consumption representing the foundational revenue base. Demand concentrates in Southeast Asian retail and foodservice channels, with European and North American buyers prioritizing certified sustainable sourcing through ASC and BAP verification.
- Pharmaceutical Ingredients:Collagen, omega-3 fatty acids, and bioactive compound refinement from farmed species. Norwegian and Chilean salmon processors extract these materials for nutraceutical and cosmetic manufacturers; premium margins attract investment from integrated producers seeking revenue diversification.
- Ornamental Aquatics:Koi, tropical fish, and coral cultivation for aquarium markets.
- Nutraceuticals:Functional food additives and dietary supplements derived from aquatic biomass.
- Animal Feed Ingredients:Fish meal and oil for pet food and livestock nutrition.
Absolute volume dominance rests with Food Production; margin expansion concentrates in Pharmaceutical Ingredients.
End User:
Procurement sophistication in this category varies by technical capability, scale economies, and integration depth.
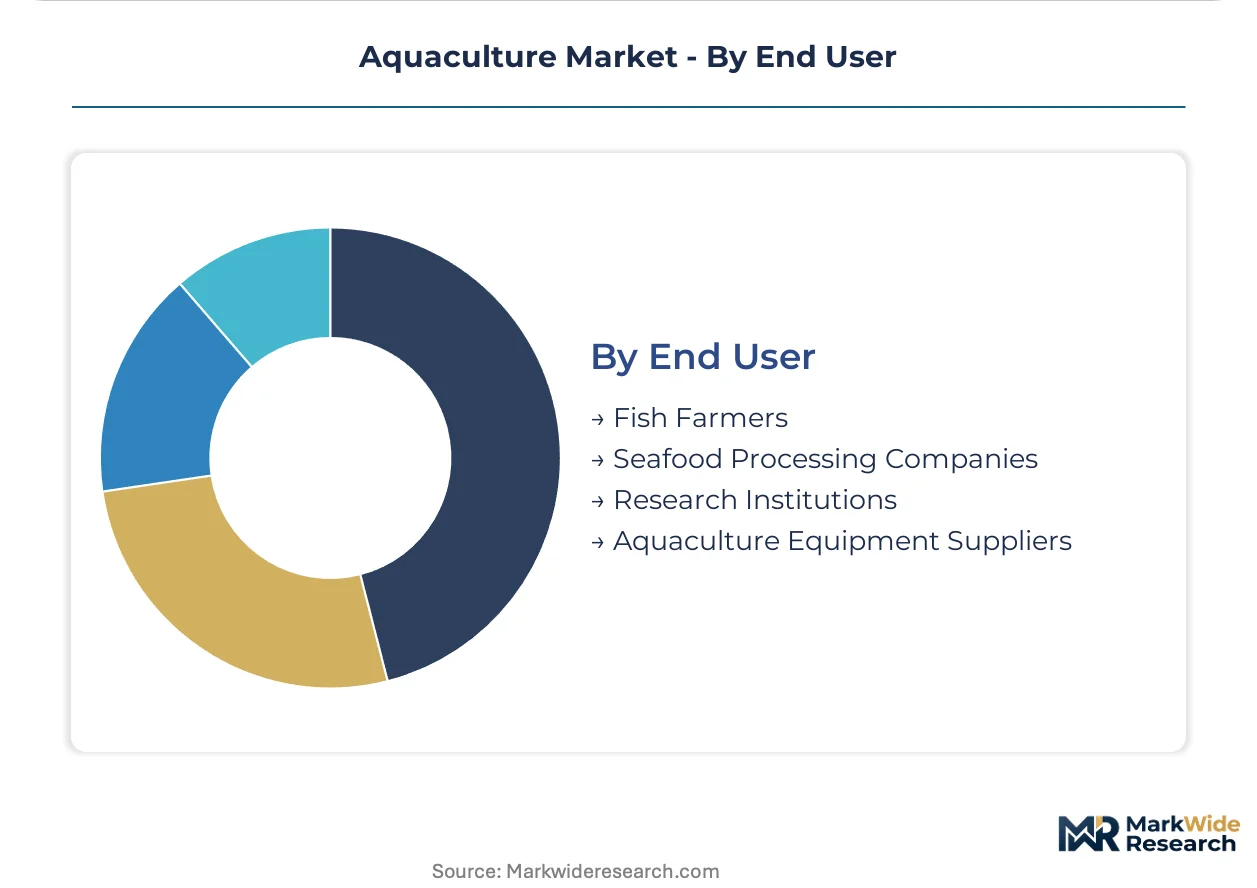
- Fish Farmers:Primary producers operating grow-out facilities from smallholder ponds to industrial cage arrays. Southeast Asian smallholders purchase through distributor networks, while Norwegian and Chilean integrated firms source directly from feed mills and equipment manufacturers.
- Seafood Processing Companies:Post-harvest operations adding value through filleting, smoking, and extraction. Demand for traceable raw material intensifies among European retailers; direct contracting with land-based producers bypasses traditional auction mechanisms.
- Research Institutions:Universities and government laboratories developing breeding programs and disease diagnostics.
- Aquaculture Equipment Suppliers:Vendors of aeration, monitoring, and handling systems for farm operations.
Procurement volume aggregates with Fish Farmers; specification complexity rises fastest among Seafood Processing Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in coastal temperate zones while consumption clusters in Asian urban centers. Norway and Chile supply Atlantic salmon to European and North American buyers. Southeast Asian nations absorb shrimp and tilapia through domestic retail and foodservice channels.
Norway
Integrated salmon producers dominate export volumes to Germany and France. The Norwegian Food Safety Authority enforces strict sea-lice thresholds and escape-prevention standards that shape farm-site licensing timelines. Bergen and Stavanger anchor processing and logistics clusters where smolt production and harvest operations converge.
Chile
Rainbow trout and Atlantic salmon operations serve Brazilian and US West Coast demand through direct shipping routes. National fisheries regulators monitor antibiotic use and zone rotation requirements under coastal concession frameworks. Puerto Montt and Chiloé Island concentrate cage-array installations and primary processing infrastructure.
Vietnam
Shrimp farming expansion targets European retail certification programs. The Ministry of Agriculture and Rural Development administers disease surveillance and coastal land-use permits for Mekong Delta operations. Cà Mau and Bạc Liêu provinces host integrated hatchery-to-processing complexes with controlled distribution networks.
Thailand
Domestic tilapia and export-oriented shrimp production balance feed mill capacity against EU import standards. The Department of Fisheries regulates hatchery licensing and water discharge parameters for intensive pond systems. Samut Sakhon and Surat Thani integrate feed manufacturing with grow-out operations across coastal plains.
Canada
Land-based recirculating facilities in British Columbia bypass marine spatial planning constraints affecting traditional cage sites. Health Canada and provincial regulators coordinate veterinary drug approvals and containment system certifications. Campbell River and Nanaimo support smolt production and equipment supply chains for Pacific salmon operations.
Aquaculture Market Key Industry Players
The competitive structure tilts toward vertically integrated salmon specialists with captive breeding programs. Scale economies favor firms controlling egg-to-market value chains across multiple coastal jurisdictions. Two archetypes dominate: full-cycle Atlantic salmon producers with proprietary genetics and Southeast Asian shrimp-feed integrators with distributor-captive networks. Capacity expansion and direct retail contracting represent the primary competitive moves.
Among Norwegian integrated producers, Mowi ASA and Grieg Seafood ASA exemplify the full-cycle archetype through controlled smolt supply and processing assets. Charoen Pokphand Foods PCL anchors the Southeast Asian feed-and-hatchery model through Thailand and Vietnam channel networks. These three occupy positions that illustrate how geographic specialization and input control separate competitive tiers.
| Leading Market Players |
|---|
| Cooke Aquaculture Inc. |
| Grieg Seafood ASA |
| Mowi ASA |
| Huon Aquaculture Group Limited |
| Charoen Pokphand Foods PCL |
| Lerøy Seafood Group ASA |
| Empresas AquaChile S.A. |
| Multiexport Foods S.A. |
| Cermaq Group AS |
| Others |
Cost & Logistics Intelligence
Captive smolt production across Norway, Scotland, and Chile anchors both supply security and pricing power for integrated Atlantic salmon producers, insulating them from spot-market volatility in egg and fry procurement while compressing margins for non-integrated competitors dependent on external hatcheries.
Pricing Analysis
Margin tightening in standard-grade Atlantic salmon reflects fish meal and fish oil price volatility as Peruvian anchovy quotas fluctuate. Three-tier pricing structure across premium ASC-certified, standard BAP-verified, and economy unlabeled tiers separates contract-based long-term offtake agreements from spot auction sales. Norwegian integrated producers command least price sensitivity through direct retail contracting, while Southeast Asian shrimp smallholders face acute cost-down pressure as feed conversion ratios dominate unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Peruvian and Chilean fish meal processors supplying marine protein inputs to Norwegian and Vietnamese feed mills. Raw material dependencies center on wild-caught forage fish, soybean meal, and increasingly insect meal alternatives. Commodity price volatility in marine protein sources creates margin compression risks for non-integrated producers. Distribution runs through controlled channel networks in Southeast Asia and direct processor contracting in European retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
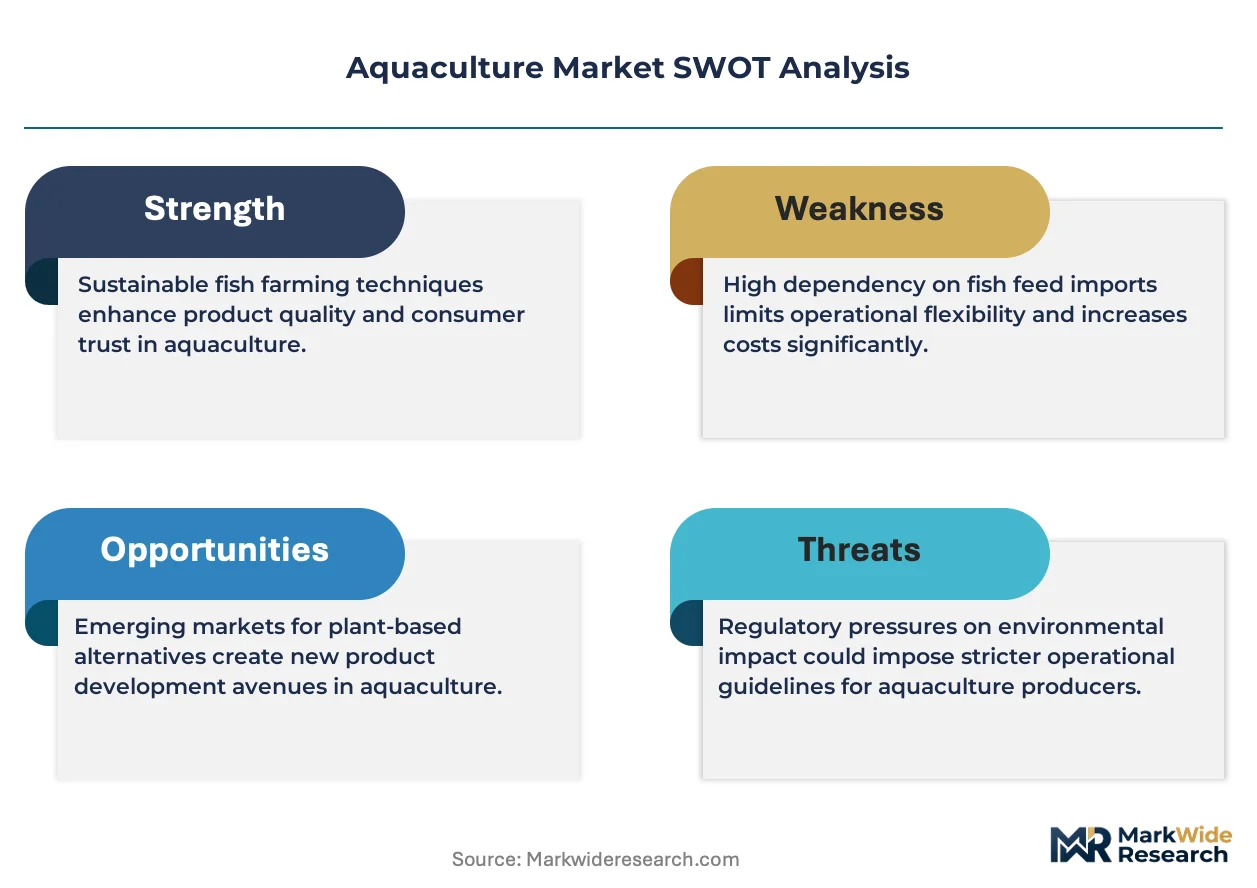
Recirculating aquaculture systems are displacing open-water cage culture as the dominant production technology, with land-based closed containment replacing legacy coastal licensing dependent on marine spatial planning carve-outs.
For Market Incumbents: Deepen captive smolt supply through large-smolt production facilities in Rogaland and British Columbia, insulating against Norwegian Food Safety Authority sea-lice threshold enforcement that elevates operational compliance costs. Secure ASC and BAP certification investments to defend shelf-space allocation as European retailers fragment procurement through direct land-based producer contracting. For New Entrants and Emerging Players: Sensor-integrated feeding systems offer technology-first wedge positioning against manual distribution protocols in mid-scale salmon operations, enabling real-time biomass monitoring to compress feed waste differentials. Target Vietnamese integrated shrimp-feed complexes through hatchery-to-processing vertical coordination in Cà Mau and Bạc Liêu provinces, leveraging controlled distribution networks underpenetrated by incumbent feed integrators. For Investors and Strategic Acquirers: Exit pathways concentrate in land-based recirculating facility acquisitions by European supermarket chains seeking specified-origin traceability for premium private-label seafood programs. Long-term viability favors producers with proprietary genetics and water-scarce region deployment capabilities. Monitor marine spatial planning reallocation decisions in Scotland and British Columbia as inflection indicators for deep-water cage platform licensing versus inland migration.| Strategic Initiative | Industry Significance |
|---|---|
| Recirculating System Deployment | Enables Atlantic salmon production in water-scarce Denmark and Netherlands previously excluded from aquaculture development. |
| Direct Retail Contracting | Bypasses commodity spot markets as British Columbia and Norwegian facilities supply specified-origin salmon to European supermarket chains. |
| Large-Smolt Production Investment | Compresses grow-out time in marine cages, reducing sea-lice exposure duration under Norwegian Food Safety Authority thresholds. |
| Certification Program Alignment | Secures ASC and BAP verification for European retail shelf-space allocation as traceability commands procurement priority. |
| Feed Input Substitution | Reduces fish meal dependency through insect meal and algae protein integration as Peruvian anchovy quotas tighten. |
Research Approach
Independent corroboration across salmon producer operations managers, shrimp feed procurement leads, seafood processing plant directors, and veterinary health product specialists underwrites the qualitative findings. Secondary validation draws from Norwegian Food Safety Authority licensing records, EU Aquaculture Strategy implementation documents, Thai Department of Fisheries hatchery registrations, and customs trade data on fish meal imports. Bottom-up facility capacity assessments and top-down consumption projections triangulate volume estimates.
Comparable-period anchoring to historical production cycles across Atlantic salmon, rainbow trout, and Pacific white shrimp sectors structures the projection horizon. Segmentation dimensions modeled include production technology, species specialization, end-use application, and regional regulatory cluster. CAGRs derive from installed capacity trajectories, licensing approval timelines, and feed conversion ratio improvements. Industry-specific inputs incorporate marine spatial planning reallocation scenarios and closed-containment certification audit completion rates.
Several conditions sit outside the modeled scope, including abrupt climatic shifts affecting ocean acidification patterns, trade policy reversals on seafood import tariffs, and breakthroughs in plant-based protein substitution capturing flexitarian consumer segments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Global Aquafeed Market