
 Silage Wrap Films Market | 2026-2036
Silage Wrap Films Market Size, Share, and Industry Trends Forecast 2026-2036
Silage Wrap Films Market Analytics
Market Context
Modular bundling of silage wrap with stretch netting and oxygen barrier films is rebalancing how dairy cooperatives and large crop farms procure preservation systems. DUO PLAST AG leverages its German manufacturing base to dominate high-performance multilayer supply across Northern European dairy belts. Scientex anchors its position through backward integration into resin compounding, securing cost control over linear low-density polyethylene feedstocks. Tilak Polypack competes on specialized gauge configurations tailored to tropical humidity conditions in South Asian markets.
Technical Definition and Segment Structure
Silage wrap films are extruded polymeric membranes, typically 300 to 750 gauge in thickness, manufactured through blown or cast processes with UV stabilizers and oxygen barrier layers to create anaerobic conditions for fermented fodder storage. These films prevent aerobic spoilage, preserve nutritional value in haylage and maize silage, and enable year-round feed security for intensive livestock operations. Linear low-density polyethylene leads material type selection due to puncture resistance and cling properties, while 750 gauge thickness commands premium positioning among dairy farmers managing high-moisture baleage. The organic farmer end-user segment represents the fastest-expanding demand pool as certification programs mandate non-toxic additive packages and film recyclability.
Regulatory Frame and Outlook
The European Chemicals Agency enforces REACH restrictions on phthalate plasticizers and heavy-metal pigments in agricultural films, while the EPA oversees pesticide and additive migration limits in the United States through FIFRA-aligned protocols. FDA indirect food contact regulations also shape film composition where silage enters dairy production chains destined for human consumption. Germany's national packaging ordinance and extended producer responsibility frameworks are forcing redesign of film recovery logistics. Stakeholders must monitor evolving biodegradability certification standards and carbon border adjustments that will reshape resin sourcing decisions and regional manufacturing placement.
Market Dynamics
REACH compliance across the European Union is forcing manufacturers to reformulate additive chemistries, redirecting R&D spending toward bio-based stabilizers and accelerating consolidation among resin compounders serving Northern European dairy belts.
Growth Catalysts
- EU Green Deal agricultural targets:Member states must cut methane emissions from livestock operations by 2030, pressuring dairy farmers to adopt oxygen-barrier silage systems that reduce feed spoilage and enteric fermentation losses.
- Large-scale dairy consolidation:Feed storage infrastructure investments across Wisconsin and Minnesota are concentrating procurement volumes with multi-year supply agreements favoring 750-gauge high-performance wraps.
- Multi-layer co-extrusion advances:Seven-layer blown film lines now integrate UV stabilizers and oxygen scavengers in single-pass production, cutting unit costs for premium baleage preservation.
Market Restraints
- Linear low-density polyethylene feedstock volatility:Ethylene monomer prices tied to naphtha cracking margins in Rotterdam and Houston create quarterly cost swings that compress converter margins.
- Extended producer responsibility mandates:Germany's national packaging ordinance forces manufacturers to internalize film collection and recycling logistics, raising delivered costs for exports into Central European markets.
- Mechanical recycling contamination limits:Soil and crop residue entanglement in used silage films degrades reprocessed pellet quality, capping circular economy claims and exposing brands to greenwashing liability.
Strategic Opportunities
- Brazilian Cerrado expansion:Beef feedlot operators in Mato Grosso and Goiás are converting from bunker silos to baled haylage systems, creating first-mover advantage for humidity-optimized gauge configurations.
- Carbon border adjustment mechanisms:The EU's phased CBAM implementation from 2026 favors regional European manufacturing over Asian resin imports, rewarding backward-integrated compounders with captive polyethylene supply.
- Organic certification premiums:EU Regulation 2018/848 mandates non-toxic additive packages for organic livestock operations, opening price differentiation for bio-based stabilizer formulations in France and Denmark.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing oxygen transmission rates with UV degradation resistance command premium salaries, constraining mid-tier converter expansion.
- Biodegradability certification timelines:EN 13432 and ASTM D6400 testing protocols require 180-day industrial composting validation, delaying product launches and freezing development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silage Wrap Films Market |
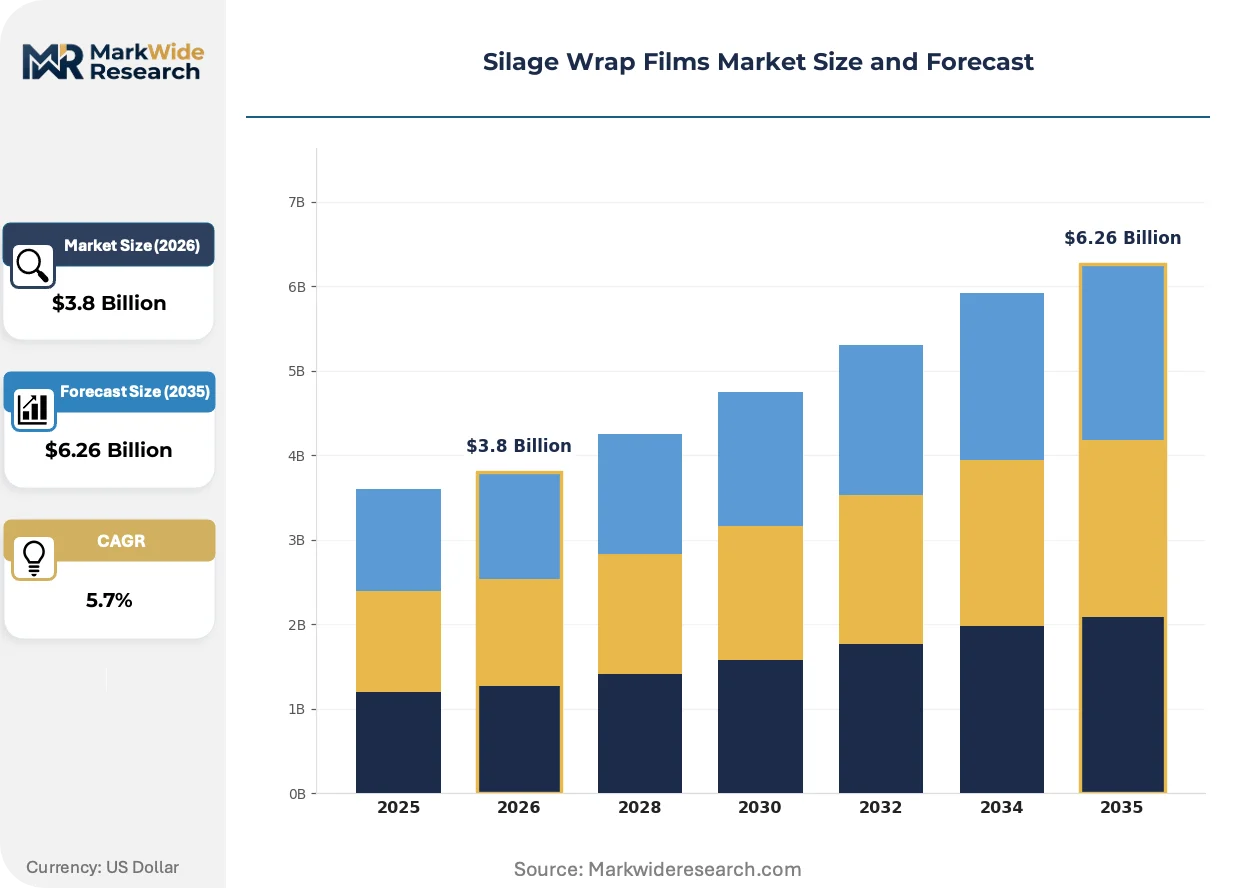
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
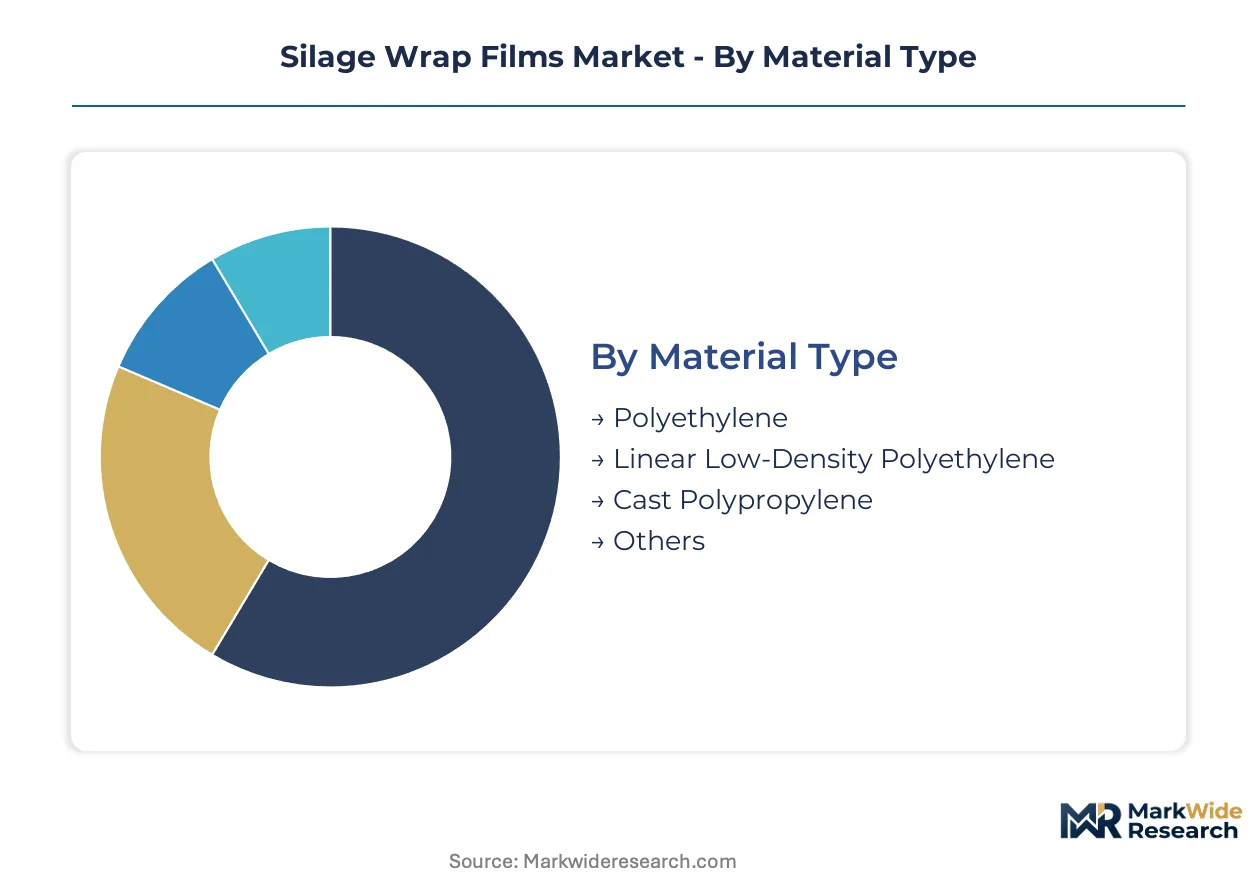
| Segmentation | Material Type: Polyethylene, Linear Low-Density Polyethylene, Cast Polypropylene, Others Thickness: 750 gauge, 500 gauge, 400 gauge, 300 gauge End User: Dairy Farmers, Crop Farmers, Organic Farmers, Agricultural Cooperatives Application: Forage Preservation, Crop Silage, Animal Feed, Biogas Production |
| Companies Covered | DUO PLAST AG, Tilak Polypack, Scientex, Bischof Klein, Blue Lake Plastics, Coveris, JUHONG Packing Materials, HONREL Agriculture, Triowrap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silage Wrap Films Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are converging to redefine performance benchmarks for anaerobic preservation systems across intensive livestock regions.
Seven-layer co-extruded barrier films incorporating ethylene vinyl alcohol copolymers are absorbing oxygen transmission duties previously handled by secondary vacuum-seal pouches. Dairy cooperatives in Bavaria and the Netherlands are specifying these integrated constructions for high-moisture baleage contracts. The technology is absorbing margin from standalone oxygen barrier film suppliers and collapsing the traditional two-step wrapping workflow into single-pass operations.
ECHA enforcement of REACH Annex XVII restrictions on cadmium and lead-based heat stabilizers is compelling compounders to switch to calcium-zinc and organotin alternatives. The industrial consequence is reformulation lag: existing masterbatch inventories must be exhausted before new additive packages achieve full regulatory clearance. Organic dairy operations in Denmark and Austria are responding fastest, mandating additive disclosure documentation from film suppliers ahead of the 2025 compliance deadline.
Cooperative procurement consortia are displacing individual farm purchasing across the Upper Midwest. Dairy Farmers of America and similar aggregators now negotiate multi-year supply agreements directly with German and domestic film converters, bypassing agricultural distributors. This concentration is most visible in Wisconsin's Fox River Valley, where three cooperatives account for the majority of 750-gauge premium wrap offtake and have forced distributors to unbundle technical advisory services from product margins.
Silage Wrap Films Market Segmentation
Silage wrap procurement patterns diverge sharply between commodity dairy operations seeking volume discounts and specialized organic farms demanding certified additive packages. Understanding these segment boundaries clarifies where formulation investments yield margin protection versus where price competition dominates.
Material Type:
Customization intensity spans from off-the-shelf polyethylene grades to proprietary multi-layer coextrusions with captive resin supply.
- Polyethylene:Standard-grade blown film resins dominate volume production for cost-sensitive crop farmers in the Upper Midwest. Demand concentrates where dairy cooperatives negotiate annual supply contracts based on tonnage thresholds rather than performance specifications.
- Linear Low-Density Polyethylene:Hexene and octene copolymer formulations deliver puncture resistance for high-moisture baleage in humid climates. Bavarian dairy cooperatives specify these grades for 750-gauge oxygen barrier applications where spoilage losses exceed material cost premiums.
- Cast Polypropylene:Oriented film structures serve niche biogas digester applications requiring elevated temperature resistance during anaerobic breakdown.
- Others:Bio-based polyhydroxyalkanoate trials are emerging in Danish organic certification programs.
Most installed capacity flows through Linear Low-Density Polyethylene. Expansion is steepest in bio-based alternatives.
Thickness:
Cost-per-bale calculations drive gauge selection, with climate risk and baling equipment capability determining upgrade thresholds.
- 750 gauge:Seven-layer constructions integrate ethylene vinyl alcohol oxygen barriers for high-moisture haylage preservation. Wisconsin's Fox River Valley cooperatives mandate this specification for baleage contracts exceeding 60% moisture content.
- 500 gauge:Standard-duty wraps balance material cost against puncture resistance for maize silage in temperate Northern European conditions. German dairy belts represent concentrated offtake where mechanized wrapping lines minimize handling damage.
- 400 gauge:Mid-range option for dry haylage in low-humidity regions.
- 300 gauge:Economy grade for temporary field coverage and dry forage applications.
Revenue concentrates in 750 gauge specifications. Volume expansion is climbing the fastest in 500 gauge.
End User:
Procurement scale and certification requirements fragment this category from individual farm purchasing to consolidated cooperative tenders.
- Dairy Farmers:Intensive livestock operations in Minnesota and Wisconsin drive premium wrap demand through multi-year supply agreements. Feed security requirements during winter months justify 750-gauge oxygen barrier investments that reduce aerobic spoilage losses.
- Agricultural Cooperatives:Aggregated purchasing power across Dairy Farmers of America and similar consortia is displacing distributor intermediaries. Technical advisory services now unbundle from product margins as cooperatives negotiate direct with German and domestic converters.
- Crop Farmers:Grain operations seeking silage alternatives for livestock feed or biogas feedstock.
- Organic Farmers:EU Regulation 2018/848 compliance mandates non-toxic additive disclosure, creating price differentiation for bio-based stabilizer formulations in France and Denmark.
Procurement volume flows through Dairy Farmers. Certification-driven demand is expanding most quickly among Organic Farmers.
Application:
Preservation objectives range from nutritional retention in dairy rations to methane capture optimization in energy systems.
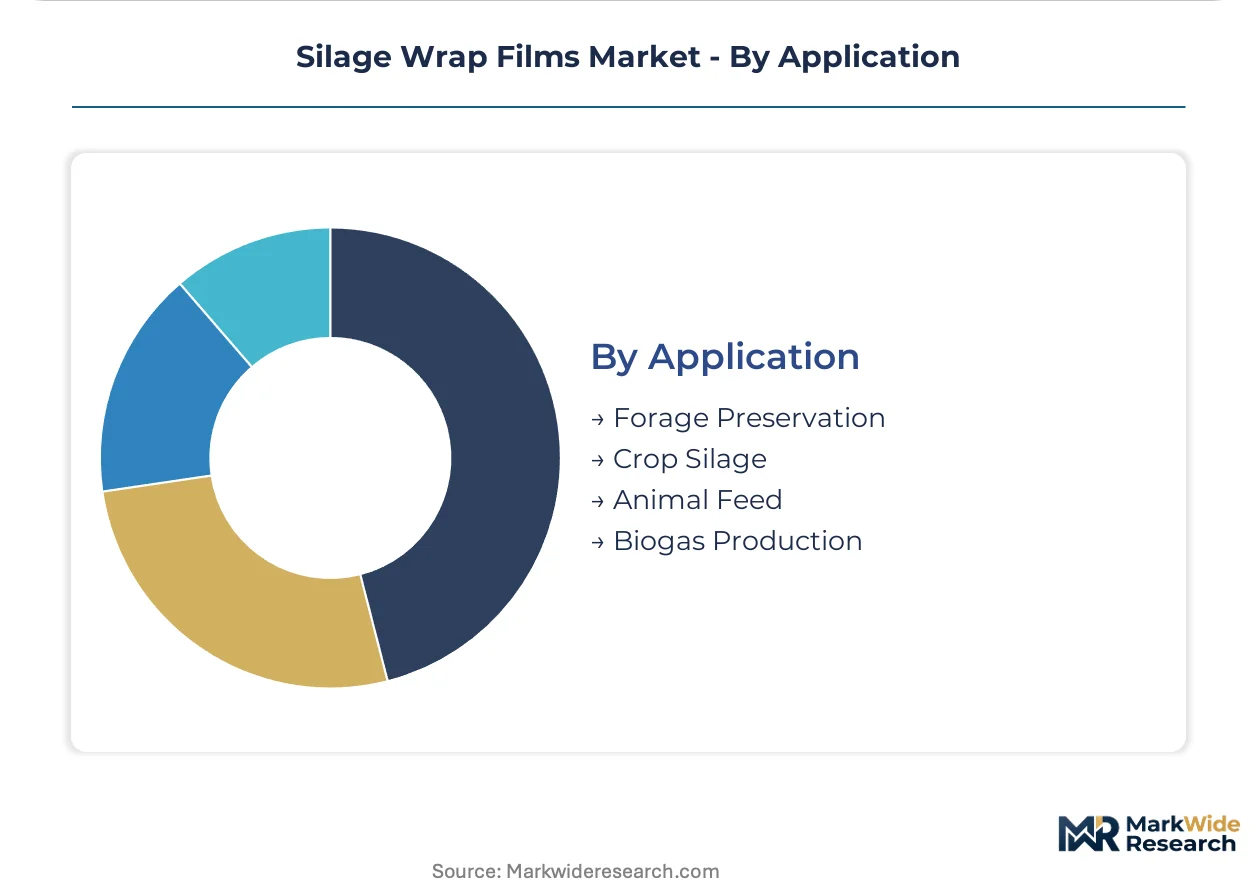
- Forage Preservation:Anaerobic storage of grass haylage and legume silage commands the largest material volumes. Bavarian and Dutch cooperatives specify integrated oxygen barrier constructions to meet EU Green Deal methane reduction targets.
- Biogas Production:Dedicated silage for anaerobic digesters requires modified fermentation profiles. German farm-scale biogas installations specify film formulations that accelerate initial acidification while maintaining storage stability.
- Crop Silage:Maize and whole-crop cereal preservation for beef and dairy rations.
- Animal Feed:General livestock nutrition applications with standard preservation requirements.
Material tonnage concentrates in Forage Preservation. Application development is advancing fastest in Biogas Production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silage wrap film manufacturing originated in post-war Germany, where blown film extrusion techniques developed for industrial packaging migrated into agricultural applications during the 1970s intensification of European dairy farming.
Germany
Bavarian dairy cooperatives drive specification-grade demand for 750-gauge oxygen barrier films. REACH enforcement through ECHA mandates calcium-zinc stabilizer transitions ahead of 2025 deadlines. The Lower Saxony polymer processing cluster around Hanover anchors multi-layer co-extrusion capacity serving Northern European export markets.
United States
Wisconsin's Fox River Valley and Minnesota's dairy belt concentrate procurement through cooperative consortia negotiating multi-year supply agreements. EPA oversight of additive migration limits under FIFRA-aligned protocols shapes film composition for dairy operations supplying fluid milk markets. Madison-area technical service hubs support precision agriculture integration for large-scale operations.
France
Normandy and Brittany dairy belts specify high-performance wraps meeting EU Green Deal methane reduction targets for 2030. ANSM disclosure requirements for food-contact materials extend to silage films entering dairy production chains. The Grand Est region hosts compounding operations reformulating masterbatches for organic certification compliance.
Brazil
Mato Grosso and Goiás beef feedlot operators are converting bunker silo infrastructure to baled haylage systems. ANVISA regulates agricultural chemical residues in films destined for export beef supply chains. Campinas-based distribution networks are establishing technical advisory capacity for humidity-optimized gauge configurations.
Denmark
Organic dairy operations mandate non-toxic additive disclosure ahead of EU Regulation 2018/848 full implementation. The country's national packaging ordinance extends producer responsibility to agricultural film recovery logistics. Jutland's cooperative processing infrastructure tests bio-based polyhydroxyalkanoate formulations for certified organic livestock operations.
Silage Wrap Films Market Competitive Landscape
The competitive structure tilts toward backward-integrated resin compounders with captive polyethylene supply. German and Malaysian manufacturers anchor premium-tier supply through multi-layer co-extrusion expertise, while mid-scale converters compete on specialized gauge configurations for tropical humidity conditions. Three archetypes dominate: integrated petrochemical players controlling resin feedstocks, regional specialists with climate-adapted formulations, and agricultural cooperative affiliates securing dedicated offtake. Capacity expansion and geographic licensing represent the dominant competitive vectors as manufacturers position for carbon border adjustment mechanisms.
Among European fabricators, DUO PLAST AG occupies a position exemplifying integrated multi-layer supply capability, while Scientex anchors the Southeast Asian tier through upstream control over resin compounding operations. Tilak Polypack represents the climate-specialist archetype with formulations adapted to South Asian humidity conditions. These three entities collectively illustrate the geographic and technical segmentation shaping procurement decisions across dairy belts in Northern Europe, Southeast Asia, and the Upper Midwest.
| Leading Market Players |
|---|
| DUO PLAST AG |
| Tilak Polypack |
| Scientex |
| Bischof Klein |
| Blue Lake Plastics |
| Coveris |
| JUHONG Packing Materials |
| HONREL Agriculture |
| Triowrap |
| Others |
Value Network & Pricing Analysis
Rotterdam ethylene monomer pricing cascades through naphtha cracking margins into converter cost structures, stratifying final film pricing across premium oxygen-barrier grades, standard multi-layer wraps, and economy polyethylene sheeting for price-sensitive crop farmers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with 750-gauge oxygen barrier films commanding spreads based on EVOH layer integration and organic certification grade. Price differentiation reflects REACH-compliant additive packages and cooperative volume scale, with Wisconsin dairy consortia extracting discounts through multi-year offtake commitments. Cost compression in standard-grade polyethylene is intensifying because LLDPE feedstock volatility erodes converter margins. Crop farmers in the Upper Midwest exhibit highest price sensitivity, while Bavarian organic cooperatives accept premium positioning for certified non-toxic formulations.
Supply Chain Analysis
EU organic certification and REACH Annex XVII compliance gates upstream masterbatch supply, forcing compounders to exhaust legacy additive inventories before new calcium-zinc formulations achieve regulatory clearance. Manufacturing concentrates in Germany, Malaysia, and the United States, with blown film extrusion capacity anchored in Lower Saxony and captive resin supply in Southeast Asia. Raw material flows draw from ethylene monomer, calcium-zinc stabilizers, and EVOH barrier resins. Single-source vulnerability runs through Rotterdam naphtha cracking economics. Distribution runs through cooperative procurement consortia displacing traditional agricultural distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silage wrap films constitute a late-cycle quality story as dairy cooperatives shift procurement toward 750-gauge oxygen barrier specifications that reduce aerobic spoilage losses and meet EU Green Deal methane targets.
For Market Incumbents: To counter feedstock margin compression from Rotterdam ethylene volatility, prioritize backward integration into resin compounding operations and expand seven-layer co-extrusion capacity in Germany to serve REACH-mandated reformulation demand. Secure multi-year supply agreements with Dairy Farmers of America and similar cooperative consortia to lock in volume offtake and unbundle technical advisory services from product margins. For New Entrants and Emerging Players: EU Regulation 2018/848 in France and Denmark opens a window for bio-based stabilizer formulations targeting certified organic livestock operations with mandatory non-toxic additive disclosure requirements. Penetrate the Brazilian Cerrado through humidity-optimized gauge configurations for Mato Grosso beef feedlot conversions from bunker silos to baled haylage systems. Lead with technical advisory partnerships rather than distributor channel reliance. For Investors and Strategic Acquirers: Asymmetric upside sits with backward-integrated compounders controlling captive polyethylene supply and multi-layer co-extrusion expertise serving Northern European dairy belts. Long-term viability favors manufacturers positioned for carbon border adjustment mechanism implementation from 2026, with regional European production shielded from Asian resin import exposure. Watch for consolidation triggers when REACH enforcement accelerates masterbatch reformulation timelines and freezes development budgets at mid-tier converters lacking formulation chemistry capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Scientex demonstrates cost control over LLDPE feedstocks through captive supply. |
| Multi-Layer Co-Extrusion Capacity Expansion | DUO PLAST AG leverages German manufacturing base for seven-layer oxygen barrier output. |
| Bio-Based Stabilizer Formulation Investment | Danish organic operations mandate calcium-zinc alternatives ahead of REACH deadlines. |
| Cooperative Direct Supply Agreements | Wisconsin consortia bypass distributors to negotiate technical service unbundling. |
| Humidity-Optimized Gauge Development | Tilak Polypack captures South Asian demand through tropical climate specialization. |
Research Methodology
Coverage spans Germany, the United States, France, Brazil, and Denmark, with primary inputs from each market combining interviews with blown film extrusion plant managers, dairy cooperative procurement directors, resin compounding R&D leads, and agricultural distributor channel partners. Secondary validation draws from ECHA REACH substance databases, EPA FIFRA registration filings, EU Regulation 2018/848 implementation guidance, and customs trade data on polyethylene film exports. Bottom-up demand modeling triangulates against top-down resin consumption analysis.
Rate-of-change decomposition separates volume growth from price mix effects across material type, thickness specification, end-user procurement scale, and application preservation objective. CAGRs derive from segment-level growth trajectory blending. Modeled dimensions span polyethylene grade tier, gauge thickness, cooperative versus individual farm purchasing, and regional regulatory cluster. Forecast inputs incorporate LLDPE feedstock cost curves and REACH enforcement timeline assumptions.
Revisions become necessary when ECHA accelerates additive restriction timelines, when carbon border adjustment mechanisms alter regional manufacturing economics, or when Brazilian feedlot conversion rates exceed baseline infrastructure capacity assumptions. A model refresh is warranted upon material change in EU Green Deal methane reduction target enforcement or naphtha cracking margin volatility regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Agriculture Bags Market