
 North America Silo Bags Market | 2026-2036
North America Silo Bags Market Size, Share, and Industry Trends Forecast 2026-2036
North America Silo Bags Market Analytics
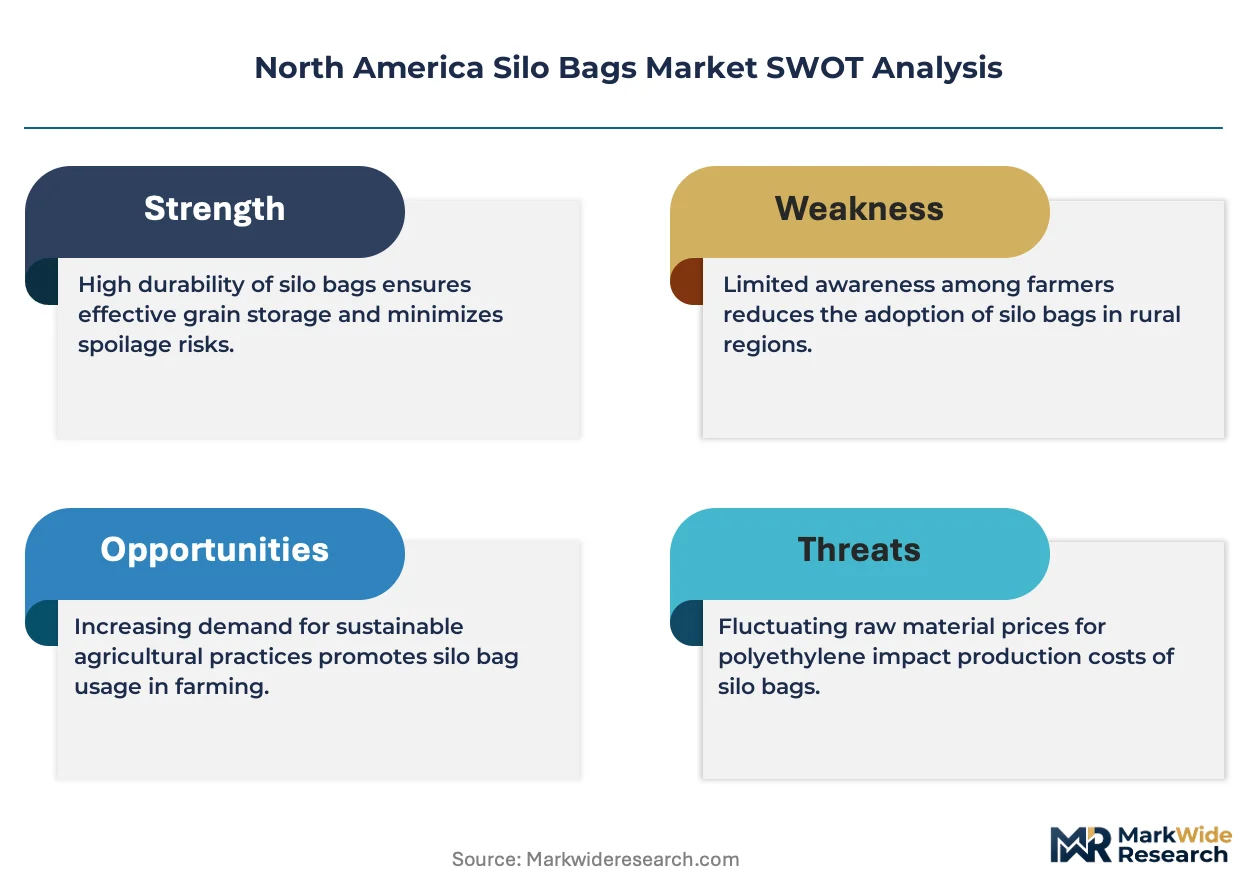
Project finance tied to harvest-season working capital is narrowing the competitive field in temporary grain storage. BagMan LLC leverages direct distribution across the Corn Belt to sustain price competitiveness against larger film suppliers. GEM Silage Products anchors its position through specialized UV-stabilized formulations for extended outdoor exposure. Canadian Tarpaulin Manufacturers Ltd. competes on proximity to Prairie province cooperatives with shorter fulfillment windows.
Silo bags are extruded polyethylene or polypropylene tubes, typically 2.7 to 3.6 meters in diameter and up to 60 meters in length, designed for anaerobic storage of harvested grain and fermented silage on unprepared ground. Grain Storage dominates product type demand as large-scale corn and soybean operations seek overflow capacity beyond permanent elevator infrastructure. Polyethylene leads material selection for its moisture barrier properties and heat-sealing compatibility, though Laminated constructions are gaining traction among livestock farmers requiring longer storage cycles without spoilage.
USDA's Farm Service Agency conservation compliance rules and EPA renewable fuel standards shape on-farm storage investment timing and capacity planning across U.S. operations. Health Canada's PMRA regulates pesticide residue containment protocols that influence bag specifications for fertilizer and treated seed applications. Stakeholders must monitor how FERC rail rate decisions and Canadian National Railway capacity allocations alter regional arbitrage incentives for temporary versus permanent storage infrastructure.
Market Dynamics
Elevator congestion across the U.S. Plains is forcing grain traders toward temporary storage infrastructure. USDA conservation compliance rules and EPA biogas incentives are redirecting working capital into on-farm containment systems.
Growth Catalysts
- USDA Farm Service Agency conservation programs:Conservation compliance rules mandate buffer zones and runoff containment, accelerating investment in portable storage that meets environmental standards.
- Polyethylene moisture barrier technology:Heat-sealable film formulations enable anaerobic grain preservation without permanent concrete infrastructure, cutting capital deployment timelines.
- Canadian Prairie rail bottlenecks:Persistent Canadian National Railway capacity constraints force cooperative elevators to expand temporary storage rather than wait for permanent elevator construction.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene resin prices fluctuate with natural gas liquids markets, compressing film manufacturer margins during harvest-season demand spikes.
- UV degradation technical ceiling:Extended outdoor exposure beyond 18 months degrades polyethylene tensile strength, limiting silage storage cycles for livestock operations.
- FERC rail rate uncertainty:Federal Energy Regulatory Commission decisions on freight pricing alter the arbitrage math between temporary bag storage and permanent elevator investment.
Strategic Opportunities
- Laminated construction for extended silage cycles:Multi-layer barrier films open livestock farmer segments requiring 24-month fermentation storage without spoilage.
- Manitoba and Saskatchewan cooperative networks:Underpenetrated Prairie province distribution channels offer first-mover positioning for regional fulfillment optimization.
- EPA renewable fuel standard biogas incentives:Methane capture mandates for dairy operations create demand for anaerobic silage containment qualifying for carbon credits.
Industry Challenges
- UV stabilization formulation expertise gap:Specialized polymer chemistry talent for harvest-season film production concentrates at a handful of compounders, constraining quality scaling.
- Health Canada PMRA pesticide residue certification:Treated seed and fertilizer containment protocols require bag specification testing that extends product development timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Silo Bags Market |
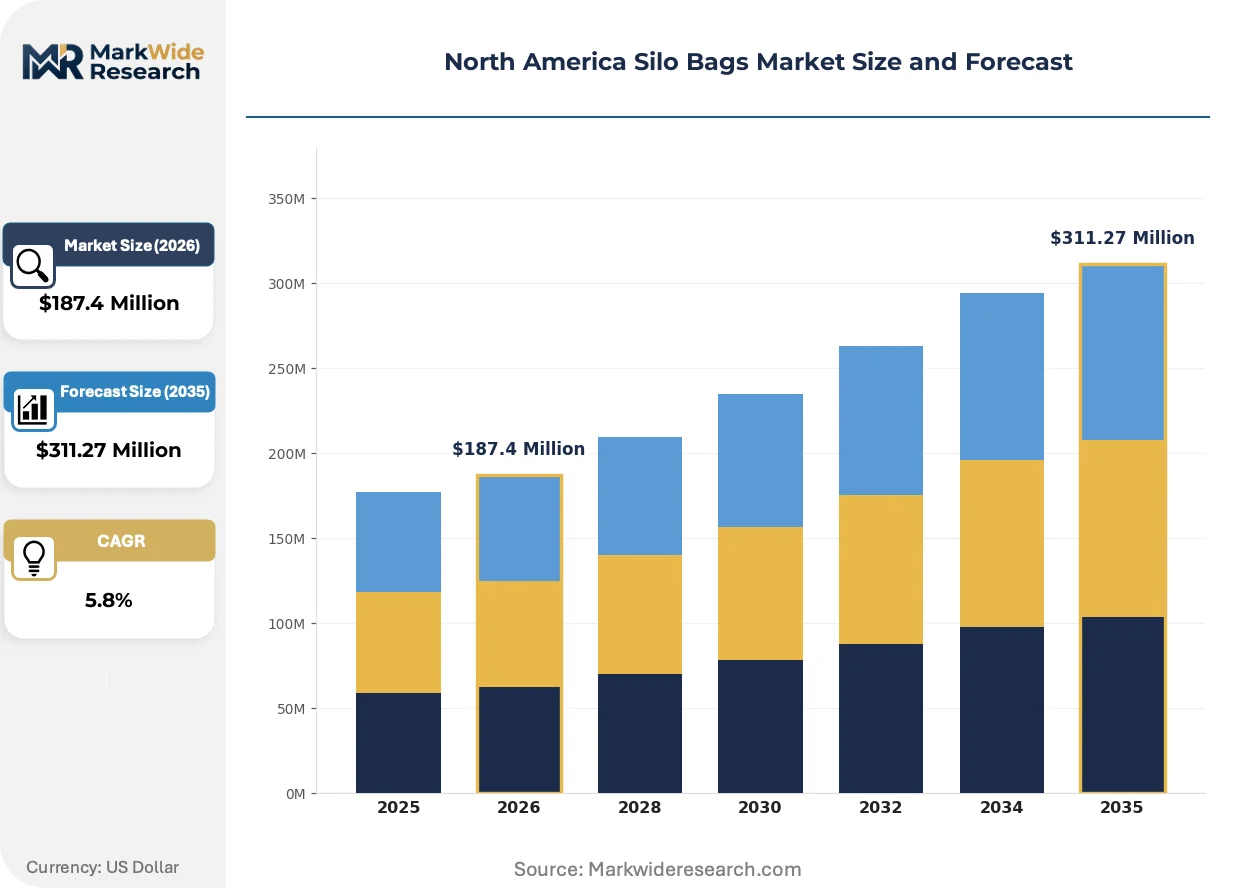
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain Storage, Feed Storage, Silage Bags, Fertilizer Bags Material: Polyethylene, Polypropylene, Laminated, Coated End User: Agricultural Producers, Livestock Farmers, Grain Traders, Cooperatives Capacity: 10 Tons, 20 Tons, 30 Tons, 50 Tons |
| Companies Covered | BagMan LLC, Grain Bags Canada, IPESA - Rio Chico S.A., Grain Pro, Inc., Blue Lake Plastics, LLC, GEM Silage Products, Canadian Tarpaulin Manufacturers Ltd., KSI Supply, Inc., RKW Hyplast NV., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Silo Bags Market Evolving Landscape
Film formulation advances and regulatory pressure on permanent infrastructure are compressing the traditional elevator construction cycle. Buyers now treat temporary storage as a core operational layer rather than emergency overflow.
Multi-layer laminated polyethylene constructions with embedded ethylene-vinyl alcohol barriers are rendering obsolete single-layer silo bags for extended silage fermentation. Large-scale dairy cooperatives in Wisconsin and Minnesota are adopting these constructions for 18-24 month storage cycles. The technology is compressing the addressable market for traditional polyethylene-only suppliers while opening premium pricing tiers for barrier-grade formulations.
EPA renewable fuel standards and USDA conservation compliance rules are tightening runoff containment mandates across Corn Belt operations. On-farm storage investment timing now aligns with federal program enrollment windows rather than harvest cycles alone. Grain traders in Iowa and Illinois are front-loading bag procurement to meet Farm Service Agency environmental assessment deadlines.
Direct distribution partnerships between film manufacturers and regional cooperative networks are displacing traditional agricultural supply house channels. Prairie province buyers now expect 72-hour fulfillment windows during September-October harvest peaks. Canadian distributors are consolidating procurement through single-source agreements that bundle UV-stabilized grain bags with silage-specific laminated constructions.
North America Silo Bags Market Segmentation
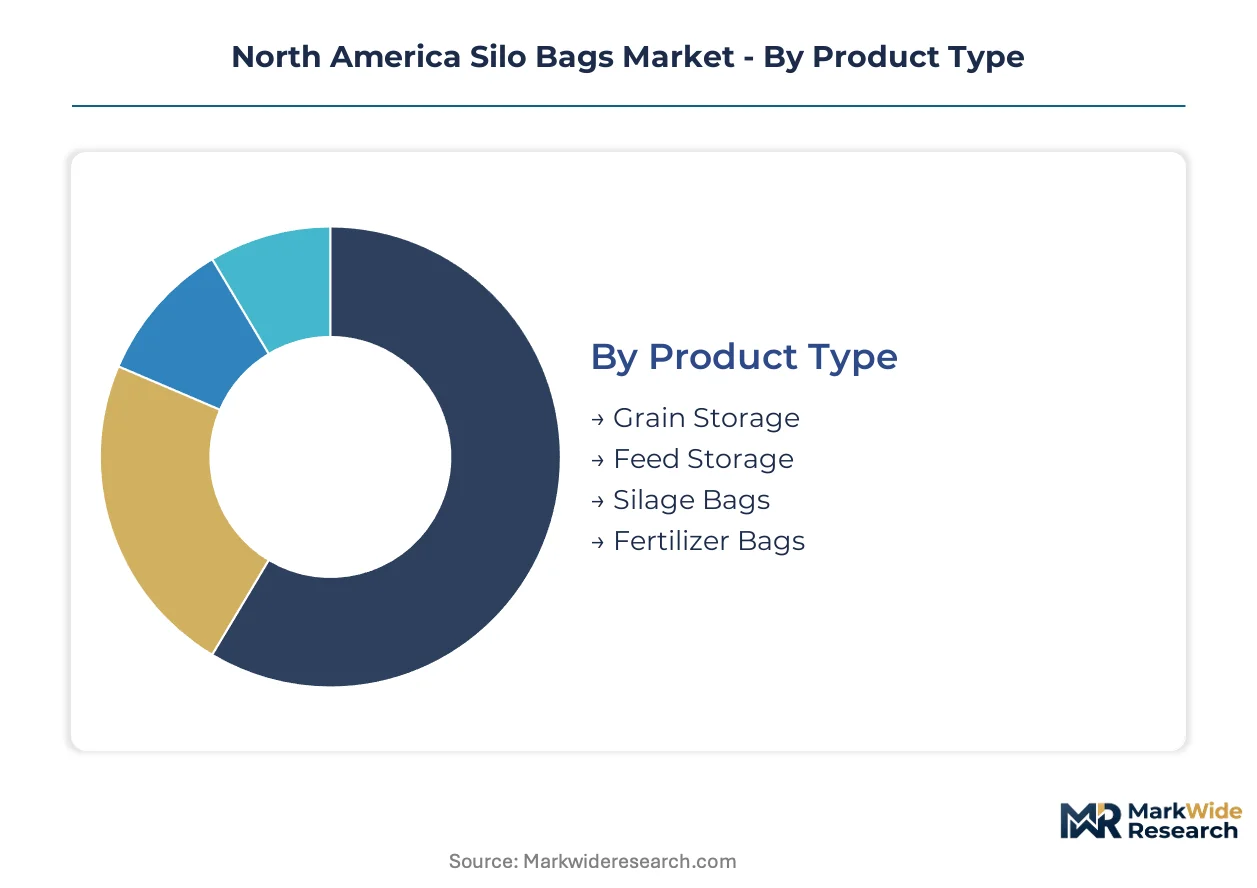
Segmentation in the North America Silo Bags Market reflects divergent technical requirements across grain preservation, livestock nutrition, and input containment applications. Each dimension—product type, material composition, end-user profile, and capacity specification—carries distinct procurement patterns and margin structures that reshape competitive positioning.
Product Type:
Mature overflow storage applications coexist with emerging precision fermentation containment as operational priorities shift across the Corn Belt and Prairie provinces.
- Grain Storage:Extruded polyethylene tubes engineered for anaerobic corn and soybean preservation without permanent concrete infrastructure. Large-scale operations across Iowa and Illinois deploy these systems during elevator congestion peaks, with USDA Farm Service Agency conservation compliance deadlines accelerating September procurement cycles.
- Silage Bags:Multi-layer barrier constructions supporting 18-24 month anaerobic fermentation for dairy operations. Wisconsin and Minnesota cooperatives are adopting laminated ethylene-vinyl alcohol formulations to qualify for EPA renewable fuel standard biogas incentives and carbon credit programs.
- Feed Storage:Mid-duty polyethylene constructions for on-farm livestock ration containment. Alberta and Manitoba cattle operations favor these specifications for shorter-duration storage with lower capital deployment.
- Fertilizer Bags:Heavy-duty coated formulations meeting Health Canada PMRA pesticide residue containment protocols. Prairie province distributors require 8-12 month certification timelines that extend product development cycles for treated seed applications.
Grain Storage retains volume leadership; Silage Bags holds the steepest expansion curve.
Material:
Cost tier differentiation separates commodity film suppliers from specialized compounders commanding premium positioning through barrier technology.
- Polyethylene:Heat-sealable moisture barrier film dominating harvest-season demand for its compatibility with rapid field deployment. U.S. Plains grain traders specify these formulations for working capital efficiency during temporary storage expansions.
- Laminated:Multi-layer constructions embedding ethylene-vinyl alcohol barriers for extended silage fermentation cycles. Dairy cooperatives in Minnesota and Wisconsin pay premium pricing for 24-month spoilage prevention without infrastructure investment.
- Polypropylene:Higher tensile strength alternative for fertilizer and treated seed containment. Canadian Prairie applications favor this material for puncture resistance during mechanical handling.
- Coated:Surface-treated formulations addressing UV degradation ceilings in extended outdoor exposure. Livestock operations in South Dakota and North Dakota specify these for seasonal storage beyond 18-month polyethylene limits.
Polyethylene dominates procurement volume; Laminated formulations are climbing the fastest on dairy sector biogas qualification requirements.
End User:
Customer type segmentation maps directly to fulfillment velocity requirements and specification complexity, with cooperative networks demanding compressed delivery windows.
- Grain Traders:Working capital-driven procurement concentrated in U.S. Plains elevator congestion zones. These buyers front-load bag acquisition to align with harvest logistics rather than permanent infrastructure construction cycles.
- Livestock Farmers:Specification-intensive demand for anaerobic silage containment qualifying for EPA methane capture incentives. Wisconsin dairy operations represent the most advanced adoption of laminated barrier technology.
- Agricultural Producers:Broad-base demand spanning grain overflow and input storage across Corn Belt row-crop operations. These buyers prioritize price competitiveness and rapid field deployment over extended durability.
- Cooperatives:Consolidated procurement power with 72-hour fulfillment expectations during September-October peaks. Prairie province networks are consolidating single-source agreements bundling multiple product specifications.
Grain Traders anchor procurement volume; Livestock Farmers drive the steepest specification upgrade trajectory.
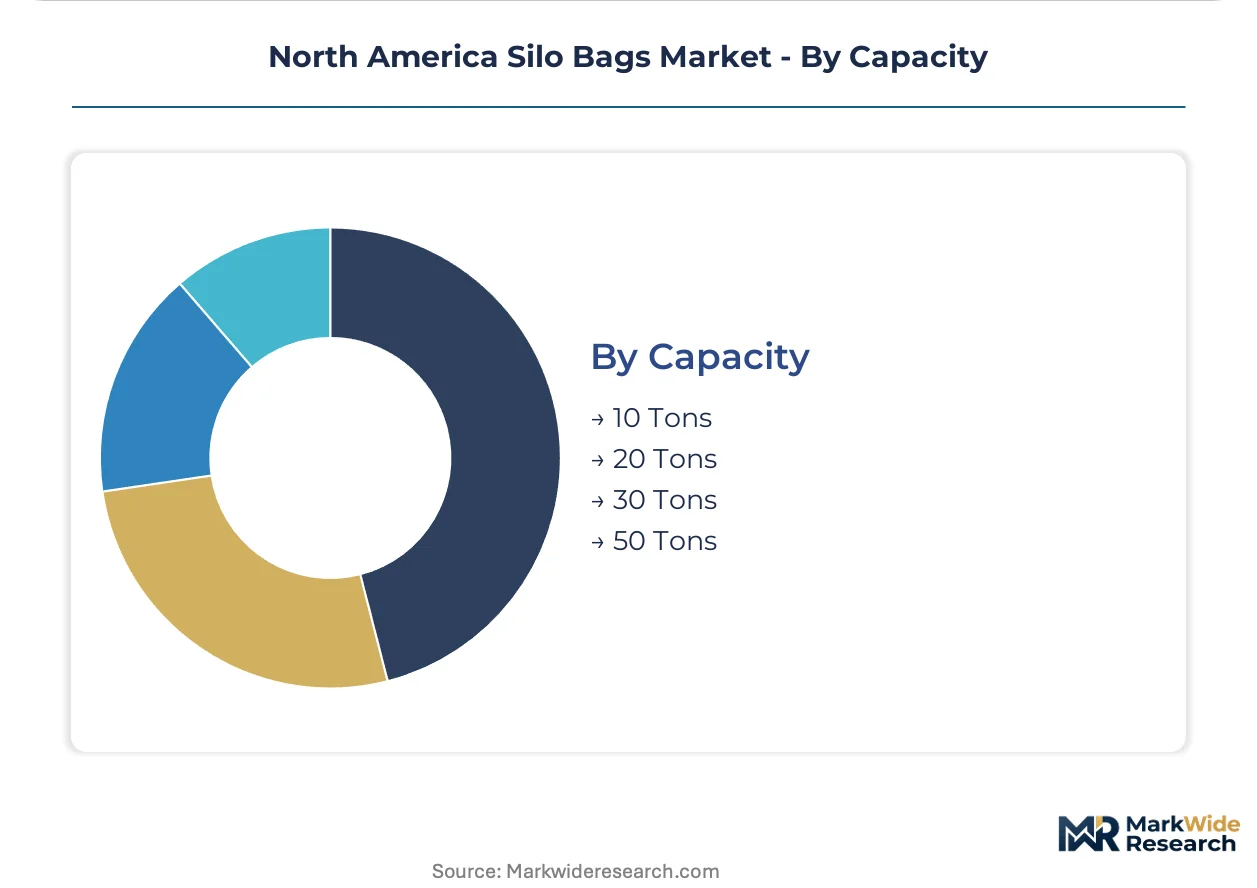
Capacity:
Volume scale segmentation correlates with farm size distribution and rail export bottleneck severity across North American production regions.
- 50 Tons:Large-diameter extrusions deployed by commercial grain operations facing Canadian National Railway capacity constraints. Saskatchewan and Manitoba cooperatives favor this scale for deferred rail loading during export bottlenecks.
- 30 Tons:Mid-scale specification balancing handling efficiency with field placement flexibility. Iowa and Illinois row-crop operations specify this capacity for USDA conservation program compliance without permanent structure investment.
- 20 Tons:Compact format for livestock farmers with limited equipment access. Alberta cattle operations deploy these for seasonal silage staging near feeding infrastructure.
- 10 Tons:Specialty capacity for treated seed and fertilizer containment requiring Health Canada PMRA certification. These smaller formats support precise input management on diversified operations.
50 Tons specifications retain volume leadership; 30 Tons capacity is gaining share fastest on Corn Belt conservation program alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain traders and livestock cooperatives concentrate procurement across the Corn Belt and Prairie provinces, with USDA conservation windows and Canadian rail bottlenecks dictating regional timing.
United States
Corn Belt elevator congestion drives overflow storage demand across Iowa and Illinois. USDA Farm Service Agency conservation compliance deadlines compress September procurement into narrow enrollment windows. Large-scale operations in the U.S. Plains front-load bag acquisition to align with harvest logistics rather than permanent infrastructure cycles.
Canada
Prairie province cooperatives face persistent Canadian National Railway capacity constraints that defer grain loading. Health Canada PMRA pesticide residue protocols extend fertilizer bag certification timelines by 8-12 months. Saskatchewan and Manitoba distribution networks now expect 72-hour fulfillment during October harvest peaks.
Mexico
Northern border state grain operations expand temporary storage for cross-border trade arbitrage. SADER agricultural support programs incentivize on-farm containment infrastructure in Sonora and Sinaloa. Bajío Region dairy cooperatives are piloting multi-layer silage constructions for extended fermentation cycles.
North America Silo Bags Market Competitive Landscape
Channel-controlling players compete with product-specialist players across temporary grain storage procurement. The vendor base separates into three tiers: direct-distribution film manufacturers, regional cooperative suppliers, and specialized compounders. Strategic differentiation runs through fulfillment velocity, UV-stabilization chemistry, and laminated barrier technology. Competitive moves concentrate on geographic consolidation through cooperative network partnerships and backward integration into resin compounding.
Among North American fabricators, BagMan LLC and GEM Silage Products exemplify contrasting archetypes. BagMan LLC represents the direct-distribution model with Corn Belt field presence. GEM Silage Products occupies a position in specialized UV-stabilized formulations for extended outdoor exposure. Canadian Tarpaulin Manufacturers Ltd. anchors the proximity-fulfillment tier with Prairie province cooperative relationships. These three illustrate how regional density and technical specialization split competitive positioning.
| Leading Market Players |
|---|
| BagMan LLC |
| Grain Bags Canada |
| IPESA - Rio Chico S.A. |
| Grain Pro, Inc. |
| Blue Lake Plastics, LLC |
| GEM Silage Products |
| Canadian Tarpaulin Manufacturers Ltd. |
| KSI Supply, Inc. |
| RKW Hyplast NV. |
| Others |
Value Network & Pricing Analysis
Houston-area petrochemical clusters anchor polyethylene resin supply for silo bag manufacturers, with ethylene cracker utilization rates translating directly into film pricing leverage across harvest-season procurement cycles. Capacity tightness at these Gulf Coast facilities propagates downstream into margin compression for Corn Belt distributors during September-October demand peaks.
Pricing Analysis
Cost-plus contracts indexed to ICIS polyethylene resin assessments dominate procurement between film manufacturers and Prairie province cooperatives. Price differentiation separates UV-stabilized premium grades from commodity polyethylene constructions based on certification tier and volume scale commitments. Margins are tightening due to natural gas liquids feedstock volatility that outpaces bag price adjustments. Grain traders exhibit highest price sensitivity, while dairy cooperatives purchasing laminated barrier grades demonstrate inelastic demand for extended fermentation specifications.
Supply Chain Analysis
Contract manufacturing concentrates at RKW Hyplast NV compounding facilities in Belgium and regional extrusion partners across Ohio and Indiana. Raw material sourcing draws from Gulf Coast ethylene crackers, imported polypropylene from South Korea, and domestic ethylene-vinyl alcohol barrier resin from Texas. Single-source vulnerability concentrates at specialized UV stabilizer compounders with limited qualified alternatives. Distribution runs through direct manufacturer relationships with cooperative networks, displacing traditional agricultural supply house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates white-space opportunities as USDA conservation compliance deadlines and EPA biogas incentives splinter demand across specialized specification tiers. The divergence between commodity grain storage and premium silage containment is spawning niche positioning openings.
For Market Incumbents: Insulate margin position through backward integration into resin compounding and captive UV stabilizer formulation capacity. Defend against laminated barrier entrants by locking Prairie province cooperatives into multi-year single-source agreements with 72-hour fulfillment guarantees. Prioritize certification investment for Health Canada PMRA pesticide residue protocols to extend product development lead times that deter challengers. For New Entrants and Emerging Players: Manitoba and Saskatchewan cooperative networks present the most penetrable geographic entry point, with fragmented procurement creating first-mover positioning for regional fulfillment optimization. Target dairy sector laminated silage specifications where EPA renewable fuel standard biogas incentives justify premium pricing. Pursue go-to-market partnerships with existing Canadian Tarpaulin Manufacturers Ltd. distribution relationships to bypass channel development timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with neglected agricultural film divisions lacking UV stabilization expertise. Long-term viability centers on barrier technology differentiation as single-layer polyethylene commoditizes. Watch for consolidation signals when Prairie province rail bottlenecks persist beyond two consecutive harvest seasons, forcing permanent infrastructure deferrals that entrench temporary storage demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Gulf Coast ethylene cracker partnerships secure supply priority during harvest-season demand spikes. |
| Laminated Barrier Technology Licensing | Ethylene-vinyl alcohol construction patents open dairy sector biogas qualification revenue streams. |
| Cooperative Network Exclusive Distribution | Manitoba and Saskatchewan single-source agreements compress competitor fulfillment windows. |
| Health Canada PMRA Certification Investment | Treated seed containment protocols extend product development timelines that deter fast followers. |
| Direct Field Service Expansion | Corn Belt deployment teams accelerate September procurement alignment with USDA conservation deadlines. |
Research Methodology
A standing panel of grain elevator operations managers, dairy cooperative procurement directors, and polyethylene film technical compounders provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against USDA Farm Service Agency program enrollment data, EPA renewable fuel standard compliance filings, and Canadian National Railway capacity allocation reports. Bottom-up volume estimates from cooperative procurement data triangulated against top-down resin consumption figures from Gulf Coast petrochemical trade associations.
Scenario-bracketing framed demand projections across the analysis window, modeling low-case rail bottleneck resolution against high-case conservation program expansion. Segmentation dimensions included product type, material construction, end-user archetype, and regional capacity specification. CAGRs derived from historical harvest-season procurement patterns and federal program enrollment timing. Industry-specific inputs incorporated FERC rail rate decision probabilities and Health Canada certification timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Gulf Coast resin producers or rapid laminated barrier technology licensing would shift outcomes. Forecasts assume continued Canadian National Railway congestion and stable EPA biogas incentive structures. Quarterly review of USDA conservation program enrollment windows, FERC docket filings, and Prairie province rail loading statistics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Africa Agricultural Film Market