
 Global Greenhouse Film Market | 2026-2036
Global Greenhouse Film Market Size, Share, and Industry Trends Forecast 2026-2036
Global Greenhouse Film Market Foresight
The EU Green Deal is rebalancing capital allocation across European greenhouse film supply chains by embedding carbon-accounting requirements into agricultural subsidy eligibility. Berry Global Group leverages its North American manufacturing footprint to serve export-intensive Latin American vegetable growers. Ginegar Plastic Products Ltd. anchors Israel's technology corridor with specialized anti-drip and thermal insulation formulations. RKW Group competes through backward integration into masterbatch compounding, capturing margin pools that commodity converters cannot access.
Greenhouse film denotes polymer-based cladding materials engineered to transmit photosynthetically active radiation while moderating thermal exchange, typically manufactured through multi-layer blown film coextrusion at thicknesses between 80 and 200 microns to achieve durability targets spanning multiple growing seasons. Polyethylene dominates installed volume due to its cost-performance ratio and ease of recycling infrastructure, though ethylene vinyl acetate commands premium positioning in high-value flower production where optical clarity and flexibility extend replacement intervals. Vegetable cultivation absorbs the largest share of tonnage, while hydroponics applications represent the fastest-expanding demand channel as soilless systems proliferate in water-stressed regions.
The EPA governs volatile organic compound emissions from film manufacturing facilities in the United States, while REACH restricts phthalate plasticizer use across European supply chains, and China's MEE enforces stricter waste classification rules for agricultural plastics that reshape export compliance burdens. These frameworks collectively elevate testing and certification costs, favoring suppliers with established regulatory affairs capabilities over regional entrants. Stakeholders must monitor evolving extended producer responsibility schemes, as these programs threaten to shift end-of-life collection costs upstream to film manufacturers within the next planning cycle.
Market Dynamics
The EU Green Deal's plastics sustainability mandates are compressing replacement cycles across Mediterranean horticulture clusters while forcing raw material transitions toward bio-based and recycled-content formulations.
Growth Catalysts
- Almería Province Expansion:Intensive vegetable cultivation clusters in Spain's southeastern coast drive premium film replacement demand as commercial farmers expand covered-acre programs.
- REACH Compliance Migration:European formulators are accelerating phthalate-free masterbatch development to meet restricted substance thresholds, opening substitution windows for compliant suppliers.
- Hydroponics Proliferation:Soilless growing systems in water-stressed regions are absorbing specialized anti-drip and thermal insulation films at expanded tonnage.
Market Restraints
- Ethylene Feedstock Volatility:Polyethylene resin costs fluctuate with naphtha-cracker economics, compressing converter margins during upstream price spikes.
- Collection Infrastructure Gaps:Agricultural plastics waste streams lack unified sorting systems across rural districts, elevating extended producer responsibility compliance burdens.
- Optical Degradation Limits:Multi-season durability targets face inherent polymer photoxidation constraints that cap replacement intervals regardless of additive loading.
Strategic Opportunities
- Latin American Export Horticulture:Mexican and Peruvian berry producers are scaling protected cultivation to serve North American off-season demand.
- Carbon-Accounting Integration:The EU Green Deal's subsidy eligibility rules reward film suppliers with verified lifecycle emissions data.
- Masterbatch Compounding Control:Captive additive formulation capabilities allow margin capture unavailable to commodity converters dependent on merchant supply.
Industry Challenges
- Multi-Layer Coextrusion Expertise:Blown film technicians capable of calibrating 80-200 micron thickness tolerances across five-layer structures remain scarce in emerging supply bases.
- Recycling Certification Timelines:Third-party validation of post-consumer content claims for agricultural films requires 12-18 month testing protocols that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Greenhouse Film Market |
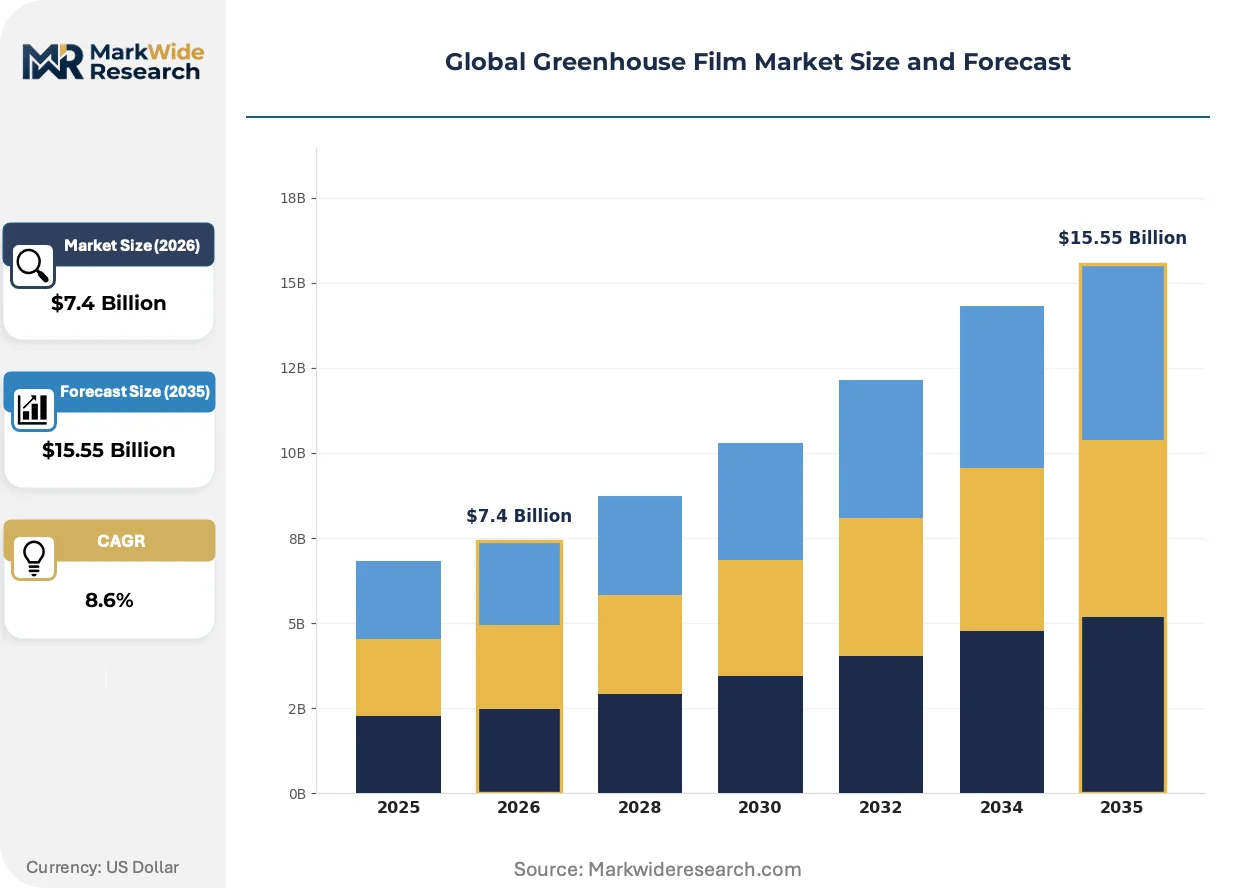
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinyl Chloride, Ethylene Vinyl Acetate, Polypropylene, Polysilicone, Polycarbonate Application: Vegetable Cultivation, Flower Production, Herb Growing, Aquaponics, Hydroponics, Orchard Cover End User: Commercial Farmers, Horticulturists, Nurseries, Botanical Gardens, Research Institutions, Agricultural Cooperatives Technology: Anti-Drip, UV Resistant, Thermal Insulation, Anti-Fog, Diffused Light, Moisture Control |
| Companies Covered | Berry Global Group, Ginegar Plastic Products Ltd., RKW Group, Plastika Kritis, Armando Alvarez Group, Polifilm Group, Essen Multipack, Amcor PLC, Lumite Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Greenhouse Film Market Shifts & Advancements
Material science advances and regulatory carbon-accounting are converging to reshape competitive positioning across greenhouse film supply chains, with sustainability credentials becoming a procurement filter rather than a premium option.
Multi-layer barrier formulations are modularizing the functional architecture of greenhouse cladding, allowing discrete film layers to be swapped or upgraded without full system replacement. High-value flower producers in the Netherlands and Colombia are adopting modular stacks that separate thermal, optical, and mechanical functions. This architecture is modularizing capex deployment patterns, enabling growers to phase investments across growing seasons rather than absorbing lump-sum replacement costs.
China's MEE waste classification enforcement is reclassifying agricultural films as regulated hazardous waste in certain provinces, triggering mandatory tracking and disposal documentation. Domestic manufacturers face elevated compliance testing burdens that reshape export certification workflows. Southeast Asian greenhouse operators dependent on Chinese film supply are accelerating dual-sourcing strategies to mitigate documentation delays.
Certification-driven procurement is elevating optical clarity and thermal retention metrics above price in Mediterranean vegetable supply chains. Almería-based grower cooperatives now mandate EN 13206 compliance as a baseline qualification, displacing uncertified commodity suppliers from tender processes. This behavioral shift is most visible in Spanish and Italian protected horticulture, where supermarket chain sustainability audits cascade requirements upstream to cladding specifications.
Global Greenhouse Film Market Segmentation
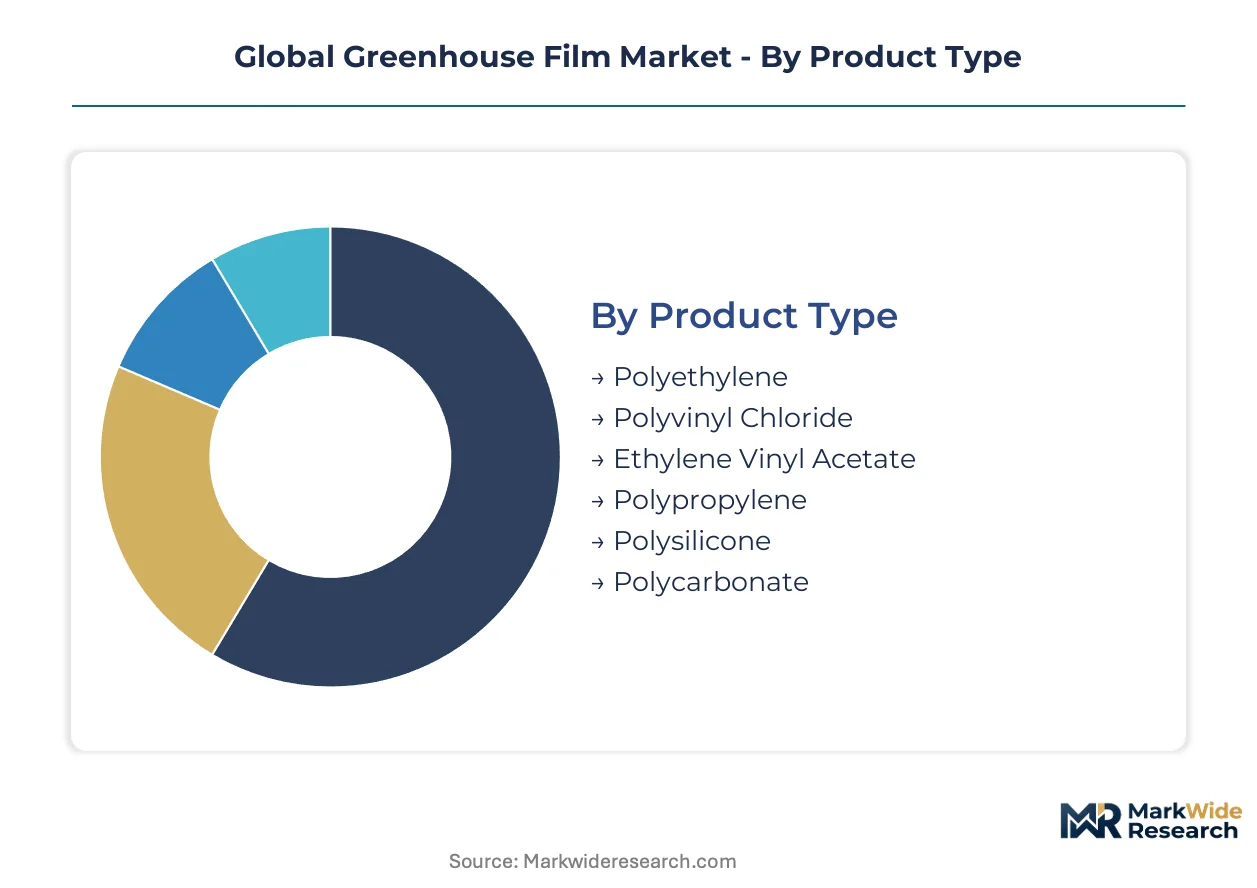
Greenhouse film segmentation reveals how material specifications, cultivation methods, and functional technologies align with distinct value pools across protected agriculture. Procurement patterns diverge sharply between commodity vegetable operations and premium flower producers, with technology choices often locking in multi-season supplier relationships.
Product Type:
Polymer selection governs optical transmission spectra, thermal retention coefficients, and mechanical durability across climatic zones.
- Polyethylene:Linear low-density formulations dominate installed volume through favorable cost-transparency tradeoffs and established mechanical recycling streams. Almería's intensive tomato and pepper growers specify 150-200 micron coextruded grades for two-to-three season replacement cycles.
- Ethylene Vinyl Acetate:Copolymer architectures with 12-18% vinyl acetate content deliver superior flexibility and impact resistance in high-altitude Colombian flower farms where hail exposure demands mechanical resilience. Premium positioning reflects extended service intervals that offset higher material costs.
- Polyvinyl Chloride:Rigid calendered sheets serve permanent structural glazing in Dutch research facilities requiring decade-long optical stability.
- Polypropylene:Biaxially oriented films command niche positioning in Israeli desert installations where thermal stress cracking resistance outweighs polyethylene's cost advantage.
- Polysilicone:Silane-crosslinked formulations enable ultra-thin 80-micron deployment in Japanese precision horticulture with automated film handling systems.
- Polycarbonate:Rigid twin-wall panels insulate Nordic greenhouse operations where heating cost containment drives capital-intensive infrastructure choices.
Mature deployment sits with polyethylene. Newer deployment is concentrated in ethylene vinyl acetate for high-value flower segments.
Application:
Cultivation system economics dictate film performance priorities, from bulk vegetable tonnage to precision-controlled hydroponic environments.
- Vegetable Cultivation:Mediterranean protected horticulture absorbs maximum polyethylene tonnage for tomato, cucumber, and pepper production. Spanish grower cooperatives specify EN 13206-certified films to satisfy supermarket chain audit requirements.
- Flower Production:Colombian and Dutch rose and chrysanthemum operations prioritize optical clarity and uniform light diffusion to maximize bud count and stem length. Premium pricing tolerates specialized additive packages unavailable to commodity vegetable converters.
- Herb Growing:Basil and mint producers in Israel's Arava desert deploy thermal insulation films to moderate extreme diurnal temperature swings.
- Aquaponics:Integrated fish-vegetable systems in Australian urban farms require food-contact compliant formulations with zero plasticizer migration risk.
- Hydroponics:Soilless substrate cultivation in water-stressed Moroccan installations absorbs anti-drip films that prevent canopy wetting and foliar disease pressure.
- Orchard Cover:Spanish citrus and Israeli avocado growers deploy rain-shelter films to manage peel quality and harvest timing.
Volume concentration remains in vegetable cultivation. Steepest expansion trajectory belongs to hydroponics as water scarcity accelerates substrate-based system adoption.
End User:
Buyer scale and sophistication determine specification authority, with large commercial operators driving standardization while research institutions pioneer functional innovations.
- Commercial Farmers:Almería-based integrated producers command direct masterbatch formulation input, specifying additive loading rates for UV stabilization and anti-drip performance. Volume procurement leverages multi-year supply agreements with price-indexed resin clauses.
- Horticulturists:Specialized flower and ornamental producers in the Netherlands and Colombia maintain technical staff capable of evaluating spectral transmission data and thermal emissivity coefficients.
- Nurseries:Propagation-focused operations in Florida and California prioritize diffuse light films to prevent seedling scorch and optimize photosynthetic efficiency.
- Botanical Gardens:Conservation-oriented institutions in Singapore and Kew Gardens specify archival-grade films with documented 20-year optical degradation curves.
- Research Institutions:Wageningen University and Israeli agricultural research stations pilot multilayer barrier films before commercial release.
- Agricultural Cooperatives:Spanish and Italian grower associations aggregate procurement to negotiate certified film supply with verified lifecycle emissions documentation.
Procurement sophistication concentrates with commercial farmers. Emerging specification authority is shifting toward agricultural cooperatives responding to EU Green Deal carbon-accounting requirements.
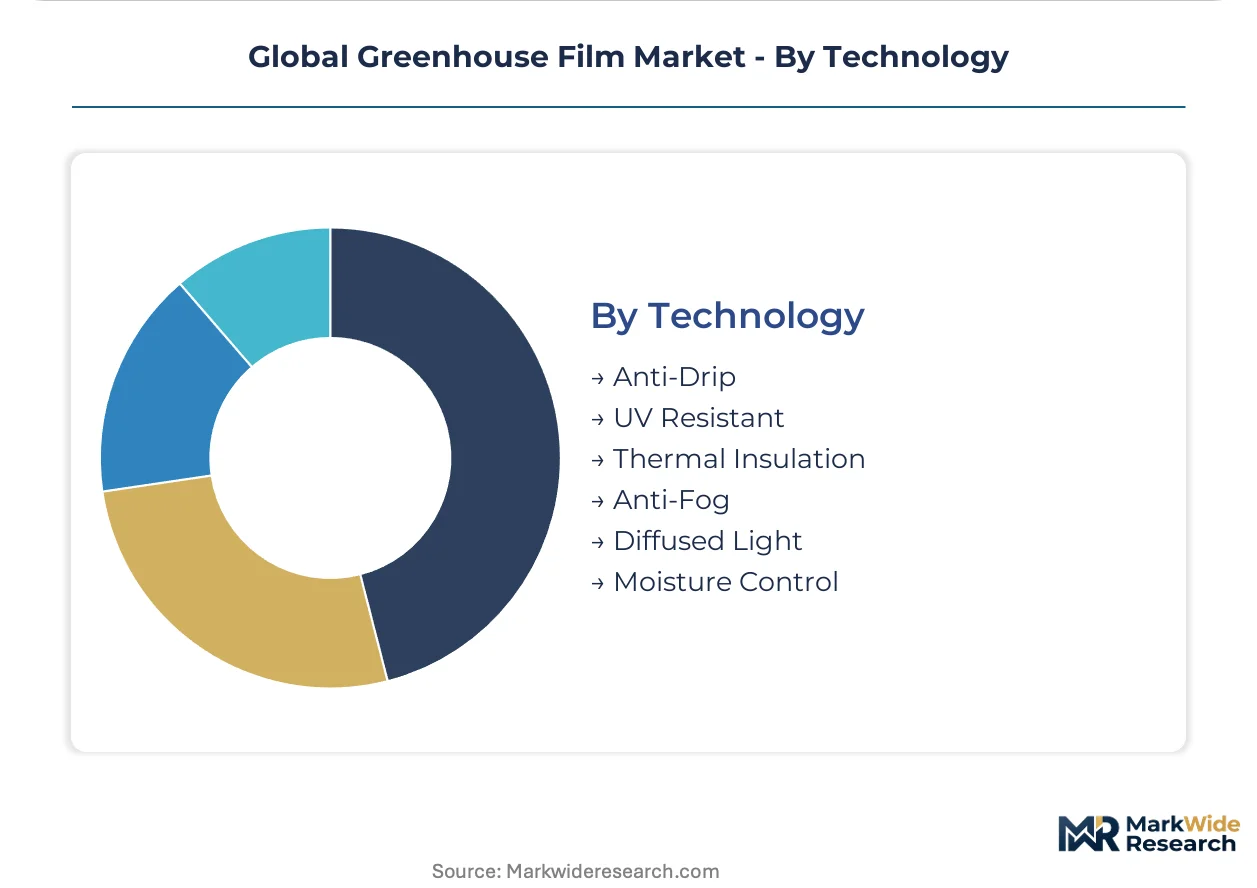
Technology:
Functional additive integration transforms base polymers into climate management tools, with layer-specific engineering enabling modular performance stacking.
- Anti-Drip:Hydrophilic surface treatments modify water contact angles to promote sheet flow rather than droplet formation, preventing crop damage and disease pressure in humid subtropical greenhouses.
- UV Resistant:Hindered amine light stabilizer packages extend service life in high-irradiance equatorial installations where unprotected polyethylene degrades within single growing seasons.
- Thermal Insulation:Infrared-reflective mineral loading reduces radiative heat loss in Nordic and high-altitude operations, cutting nighttime heating fuel consumption.
- Anti-Fog:Internal surface treatments maintain transparency in temperature-differential conditions, critical for winter vegetable production in Chinese protected agriculture.
- Diffused Light:Mineral scattering additives redistribute direct solar radiation to penetrate lower canopy zones, increasing photosynthetic efficiency in dense tomato plantings.
- Moisture Control:Vapor-permeable microporous structures manage humidity flux in semi-arid environments without compromising thermal retention.
Technology adoption concentrates in anti-drip and UV resistant formulations as baseline requirements. Fastest technology expansion belongs to thermal insulation as energy cost volatility intensifies heating efficiency priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Almería province anchors global greenhouse film consumption through intensive vegetable cultivation clusters. Commercial farmers across Mediterranean climates are expanding covered-acre programs. The EU Green Deal's plastics sustainability mandates are accelerating material transitions toward bio-based and recycled-content formulations.
Spain
Almería's intensive horticulture clusters drive premium film replacement cycles for tomato and pepper growers. The EU Green Deal embeds carbon-accounting requirements into agricultural subsidy eligibility. Grower cooperatives in southeastern Spain now mandate EN 13206 compliance as a baseline qualification for tender processes.
China
Protected agriculture expansion in Shandong and Hebei provinces absorbs substantial polyethylene tonnage for winter vegetable production. The MEE enforces stricter waste classification rules for agricultural plastics that reshape export compliance burdens. Domestic manufacturers face elevated compliance testing burdens in eastern coastal provinces.
Colombia
High-altitude flower farms around Bogotá deploy ethylene vinyl acetate films for hail resistance and optical clarity in rose production. The national agricultural regulator enforces phytosanitary standards that cascade into cladding specifications. Cundinamarca and Antioquia departments concentrate specialized anti-drip and thermal insulation demand.
Netherlands
Research institutions and flower producers in Westland and Aalsmeer pilot multilayer barrier films before commercial release. REACH restrictions on phthalate plasticizer use accelerate phthalate-free masterbatch development. Wageningen University anchors technology transfer to commercial greenhouse operators.
Israel
Desert installations in the Arava and Negev regions deploy thermal insulation films to moderate extreme diurnal temperature swings. Specialized anti-drip formulations serve hydroponics applications in water-stressed conditions. The country's technology corridor supports additive package innovation for export markets.
Global Greenhouse Film Market Competitive Landscape
European producers anchor one tier; North American and Israeli specialists hold differentiated positions in premium additive formulations. The vendor base spans integrated resin converters, captive masterbatch compounders, and regional distribution-focused fabricators. Three archetypes dominate: backward-integrated compounders capturing margin pools, technology specialists in optical and thermal performance, and scale-driven commodity converters. Competitive moves concentrate on M&A for geographic footprint and capacity expansion in Latin American export horticulture corridors.
Among Israel-based specialists, Ginegar Plastic Products Ltd. exemplifies the technology-archetype tier with specialized formulation capabilities. Berry Global Group represents the scale-driven North American fabricator with export-oriented manufacturing positioning. RKW Group anchors the European compounder archetype through captive masterbatch production that commodity converters cannot replicate.
| Leading Market Players |
|---|
| Berry Global Group |
| Ginegar Plastic Products Ltd. |
| RKW Group |
| Plastika Kritis |
| Armando Alvarez Group |
| Polifilm Group |
| Essen Multipack |
| Amcor PLC |
| Lumite Inc. |
| Others |
Supply & Pricing Matrix
Backward integration into masterbatch compounding anchors both supply resilience and pricing power for European compounders serving Mediterranean horticulture clusters. RKW Group's captive additive production captures margin pools that commodity converters dependent on merchant supply cannot access, while resin price volatility transmits unevenly across these tiered supply positions.
Pricing Analysis
Volume concentration in polyethylene commodity grades compresses margins, while premium ethylene vinyl acetate formulations retain pricing power through extended service intervals and hail-resilience specifications. Pricing stratifies across EN 13206-certified premium tiers, phthalate-compliant standard grades, and uncertified economy supply. Cost compression in commodity polyethylene intensifies as naphtha-cracker economics transmit resin volatility directly to converter margins. Commercial farmers in Almería exhibit highest price sensitivity, whereas Dutch flower producers prioritize optical clarity above unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for agricultural film collection remains underdeveloped across rural Mediterranean districts, elevating extended producer responsibility compliance burdens. Manufacturing concentrates in Germany, Israel, and China, with resin supply drawing from Saudi Arabian and US Gulf Coast ethylene feedstock. Single-source vulnerability runs through European masterbatch additive supply anchored in German chemical corridors. Distribution runs through grower cooperative procurement aggregators in Spain and Italy, bypassing traditional merchant distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon-accounting mandates construct a compliance moat that favors established compounders with verified lifecycle documentation, raising capital barriers for regional entrants lacking regulatory affairs infrastructure.
For Market Incumbents: Lock in multi-year supply agreements with Almería grower cooperatives before REACH phthalate restrictions fully phase in, securing volume commitments against substitute material transitions. Deepen backward integration into bio-based resin sourcing to preempt EU Green Deal recycled-content thresholds. Prioritize certification investment in EN 13206 and emerging carbon-accounting standards to displace uncertified commodity competitors from tender processes.
For New Entrants and Emerging Players: Mid-scale hydroponics operators in water-stressed Moroccan and Peruvian installations represent the most penetrable buyer archetype, as these segments prioritize functional performance over established supplier relationships. Target specialized anti-drip and thermal insulation formulations where technical specification authority rests with individual growers rather than cooperative procurement committees. Pursue direct technical sales engagement with demonstration trials to bypass incumbent distributor lock-in.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to North American packaging conglomerates seeking Mediterranean horticulture exposure. Long-term viability hinges on regulatory compliance scalability rather than commodity volume positioning. Acquisition targets should demonstrate captive masterbatch capabilities and established EU Green Deal certification workflows. Monitor MEE enforcement intensity in Chinese agricultural plastics classification as an inflection indicator for Asian supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Masterbatch Compounding | Captures additive formulation margins unavailable to resin-dependent commodity converters serving Almería clusters. |
| Carbon-Accounting Certification Investment | Secures EU Green Deal subsidy eligibility for grower customers, embedding supplier relationships through compliance dependency. |
| Latin American Export Corridor Expansion | Positions supply capacity to serve Mexican and Peruvian berry producers scaling protected cultivation for North American off-season demand. |
| Phthalate-Free Formulation Development | Anticipates REACH restriction timelines, opening substitution windows as European compounders accelerate compliant masterbatch migration. |
| Collection Infrastructure Partnership | Addresses extended producer responsibility compliance gaps through grower cooperative alliances in Spanish and Italian rural districts. |
Research Methodology
Multi-period observation of resin price indices, regulatory filing timelines, and grower cooperative procurement patterns anchored the trend analysis, supplemented by interviews with blown film plant managers, agricultural cooperative procurement directors, masterbatch R&D leads, and regulatory affairs specialists at European compounders. Secondary validation drew from ECHA REACH substance restrictions, EU Green Deal implementation documents, MEE waste classification notices, SEC filings of listed packaging conglomerates, and trade flow data from Mediterranean customs authorities. Bottom-up grower acreage and replacement cycle estimates triangulated against top-down resin consumption figures from regional chemical industry associations.
Input-output matrix modeling connected polyethylene and ethylene vinyl acetate resin supply assumptions through multi-layer coextrusion capacity utilization rates to end-use demand across vegetable cultivation, flower production, and hydroponics applications. Segmentation dimensions included polymer type, cultivation system, functional technology additive, and regional regulatory cluster. CAGRs were derived from trend extrapolation of replacement cycle compression and acreage expansion patterns across the analysis window. Key forecast inputs incorporated EU Green Deal carbon-accounting implementation pace and MEE agricultural plastics enforcement intensity in eastern Chinese provinces.
Revisions become necessary when REACH restriction timelines accelerate, EU Green Deal subsidy eligibility rules tighten, or MEE waste reclassification spreads beyond pilot provinces. Forecasts reflect documented assumptions regarding resin price transmission, certification adoption curves, and grower cooperative procurement centralization. Practitioners should monitor ECHA substance restriction proposals, EU Commission implementing acts on agricultural plastics, and Chinese provincial environmental enforcement bulletins for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Anti Wind Net Market