
 Asia-Pacific Crop Protection Chemicals Market | 2026-2036
Asia-Pacific Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Crop Protection Chemicals Market Analysis
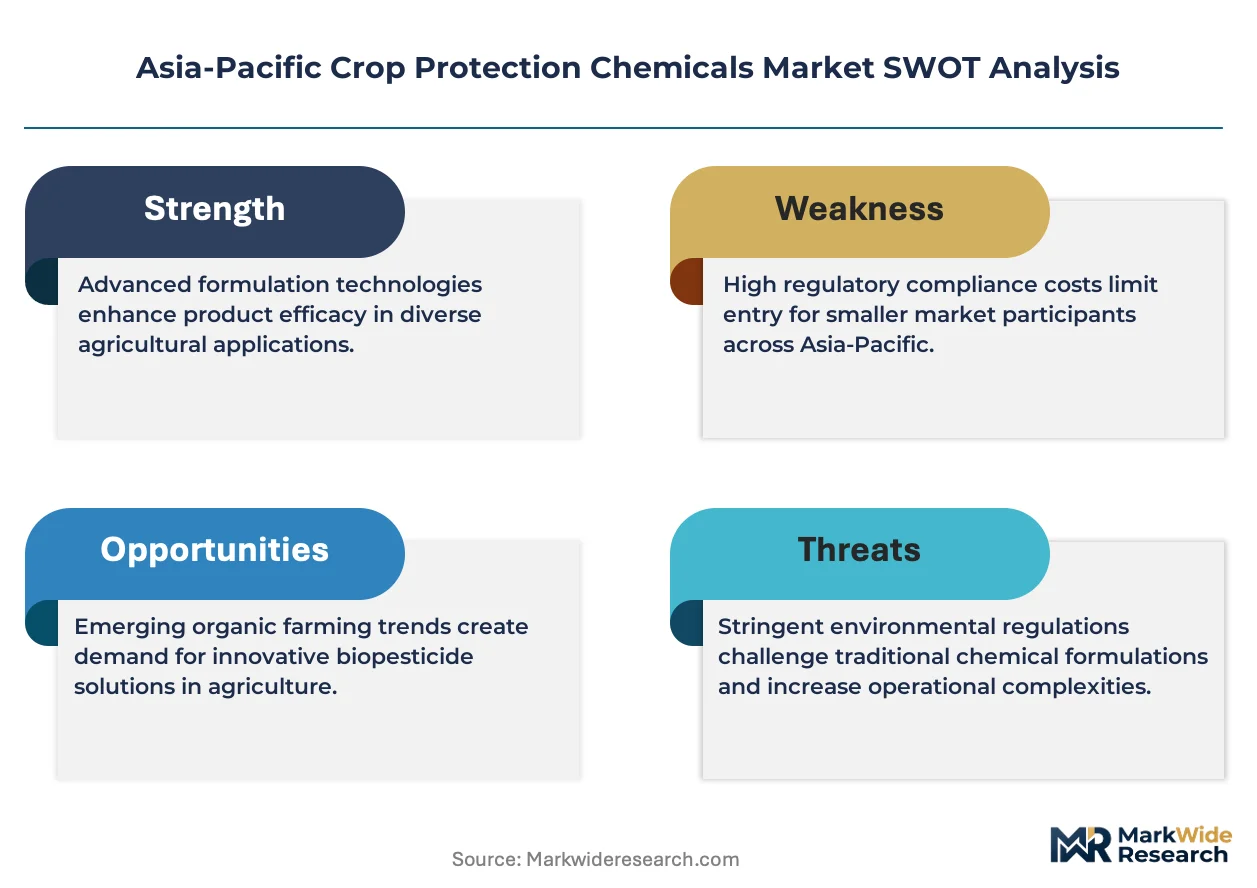
The EU Green Deal's residue threshold benchmarks is pivoting formulation priorities across Asia-Pacific export-oriented suppliers. UPL Limited leverages its India-centric manufacturing footprint to sustain cost competitiveness in generic agrochemicals. BASF SE anchors premium fungicide development through proprietary SDHI chemistry platforms. Corteva Agriscience differentiates via seed-trait integration that bundles herbicide tolerance with proprietary chemistries.
Crop protection chemicals encompass synthetic and biological formulations engineered to suppress agricultural pests, weeds, and pathogens through specified active ingredient concentrations and application rates. These compounds function primarily to safeguard yield volume and quality in commercial farming systems. Herbicides command the largest value share across the Asia-Pacific landscape, reflecting intensified mechanized rice and wheat production. Bio pesticides represent the fastest-expanding product category, though from a smaller base, as export-facing growers confront tightening maximum residue limits in destination markets. Liquid formulations dominate procurement patterns due to compatibility with aerial and mechanized spray infrastructure prevalent across large-scale Australian and Chinese operations.
China's MEE enforces emission caps on active ingredient synthesis facilities along the Yangtze River basin, redirecting capacity toward compliant chemical parks. Australia's APVMA recalibration of neonicotinoid registrations is constraining insecticide options for horticultural exporters. India's CIBRC mandate for indigenous technical grade manufacturing is reshaping import dependency for key molecules. Stakeholders must monitor regulatory divergence between ASEAN harmonization frameworks and country-specific re-registration timelines to anticipate product portfolio obsolescence risks.
Market Dynamics
China's MEE emission caps along the Yangtze River basin are forcing active ingredient manufacturers into compliant chemical parks, compressing legacy synthesis capacity while redirecting investment toward integrated production clusters in Shandong and Jiangsu provinces.
Growth Catalysts
- Herbicide intensification in rice-wheat systems:Mechanized cultivation across Southeast Asian deltas is expanding glyphosate and pre-emergent herbicide volumes. Vietnam's Mekong Delta and Thailand's Central Plains drive procurement scale.
- EU Green Deal residue benchmarks:Export-oriented suppliers in India and China are reformulating toward lower-MRL fungicide and insecticide grades. Australia's APVMA is synchronizing tolerance protocols with European destination markets.
- Biological fermentation advances:Bacillus-based biopesticide production is achieving cost parity with synthetic alternatives in Indonesian and Philippine contract manufacturing facilities.
Market Restraints
- Technical-grade import dependency:India's CIBRC indigenous manufacturing mandate has exposed supply gaps for key pyrethroid and neonicotinoid intermediates, forcing domestic producers to absorb elevated input costs.
- Neonicotinoid registration erosion:Australia's APVMA recalibration is eliminating systemic insecticide options for stone fruit and vegetable exporters, constraining pest management flexibility without viable chemical substitutes at scale.
- Active ingredient synthesis concentration:China's Yangtze River basin environmental enforcement has shuttered dispersed capacity, concentrating technical production in licensed chemical parks and amplifying supply disruption risks from localized compliance actions.
Strategic Opportunities
- Biostimulant-biopesticide convergence:Australian broadacre operators are integrating microbial inoculants with reduced-synthetic programs to meet supermarket chain residue specifications. Queensland and New South Wales grain handlers are piloting bundled input procurement.
- Drone spray infrastructure:Japan's aging agricultural workforce is accelerating unmanned aerial vehicle adoption for paddy field applications. METI subsidy frameworks are covering precision equipment deployment in Honshu rice belts.
- Seed-trait chemistry bundling:Cotton and corn growers in India's Maharashtra and Gujarat are shifting toward trait-herbicide packages that lock in multi-season chemistry commitments through germplasm licensing.
Industry Challenges
- Formulation chemist scarcity:China's Shandong manufacturing cluster faces recruitment gaps for adjuvant and delivery-system specialists capable of developing suspension concentrate and oil dispersion formats for tropical export markets.
- Re-registration timeline compression:ASEAN harmonization frameworks are diverging from country-specific data requirements, forcing multi-jurisdiction dossier preparation that strains regulatory affairs teams and extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Crop Protection Chemicals Market |
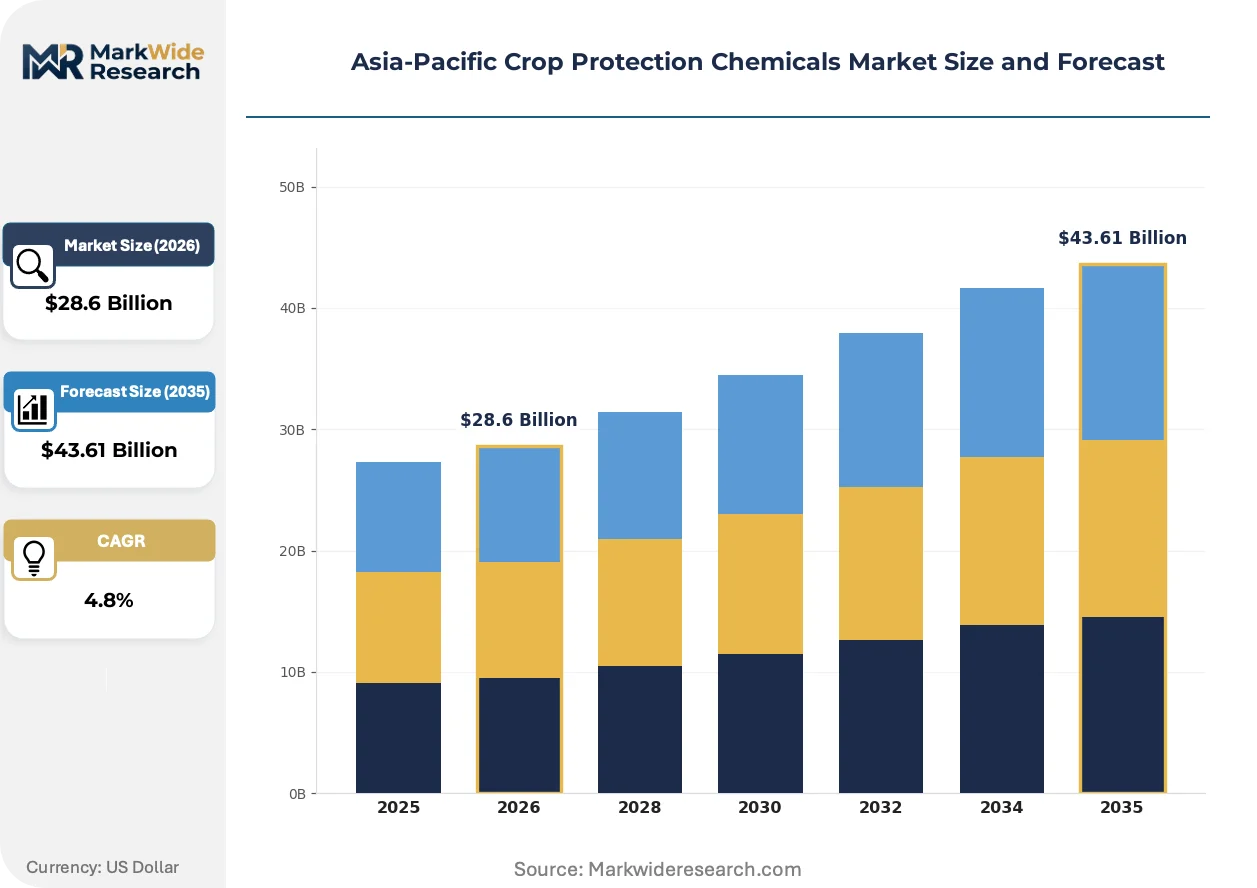
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Bio Pesticides Application: Agricultural, Horticultural, Forestry, Turf & Ornamental Formulation: Liquid, Granular, Powder, Emulsifiable Concentrates End Use Sector: Crops, Livestock, Public Health, Others |
| Companies Covered | UPL Limited, Corteva Agriscience, Syngenta Group, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical Co. Ltd, BASF SE, FMC Corporation, Nufarm Limited, Bayer AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Crop Protection Chemicals Market Emerging Trajectories
SDHI fungicide chemistry and RNA interference platforms are absorbing capital allocation from legacy synthetic R&D, while digital extension services reshape how growers access application guidance and resistance management protocols across fragmented Asian smallholder networks.
RNA interference crop protection is absorbing early-stage development resources from major agrochemical portfolios. Australian cotton and grape growers are field-testing sprayable dsRNA formulations for helicoverpa and fungal pathogen suppression. The technology is absorbing regulatory scrutiny from APVMA and FSSAI residue committees, compressing commercialization timelines against conventional chemistry benchmarks.
India's FSSAI residue monitoring protocols are tightening import tolerances for organophosphate and carbamate active ingredients in fresh produce consignments. Exporters to Middle Eastern and European markets are reformulating with lower-toxicity alternatives. Horticultural value chains in Karnataka and Andhra Pradesh are bearing compliance costs through third-party residue testing infrastructure.
Buying cooperatives and aggregator platforms are consolidating input procurement decisions across Southeast Asian smallholder networks. Vietnam's rice belt and Indonesia's palm oil estates are shifting from individual retailer purchases toward volume-contracted supply through provincial farmer organizations. This concentration is compressing distributor margins and favoring manufacturers with direct technical support capabilities in provincial hubs.
Asia-Pacific Crop Protection Chemicals Market Segmentation
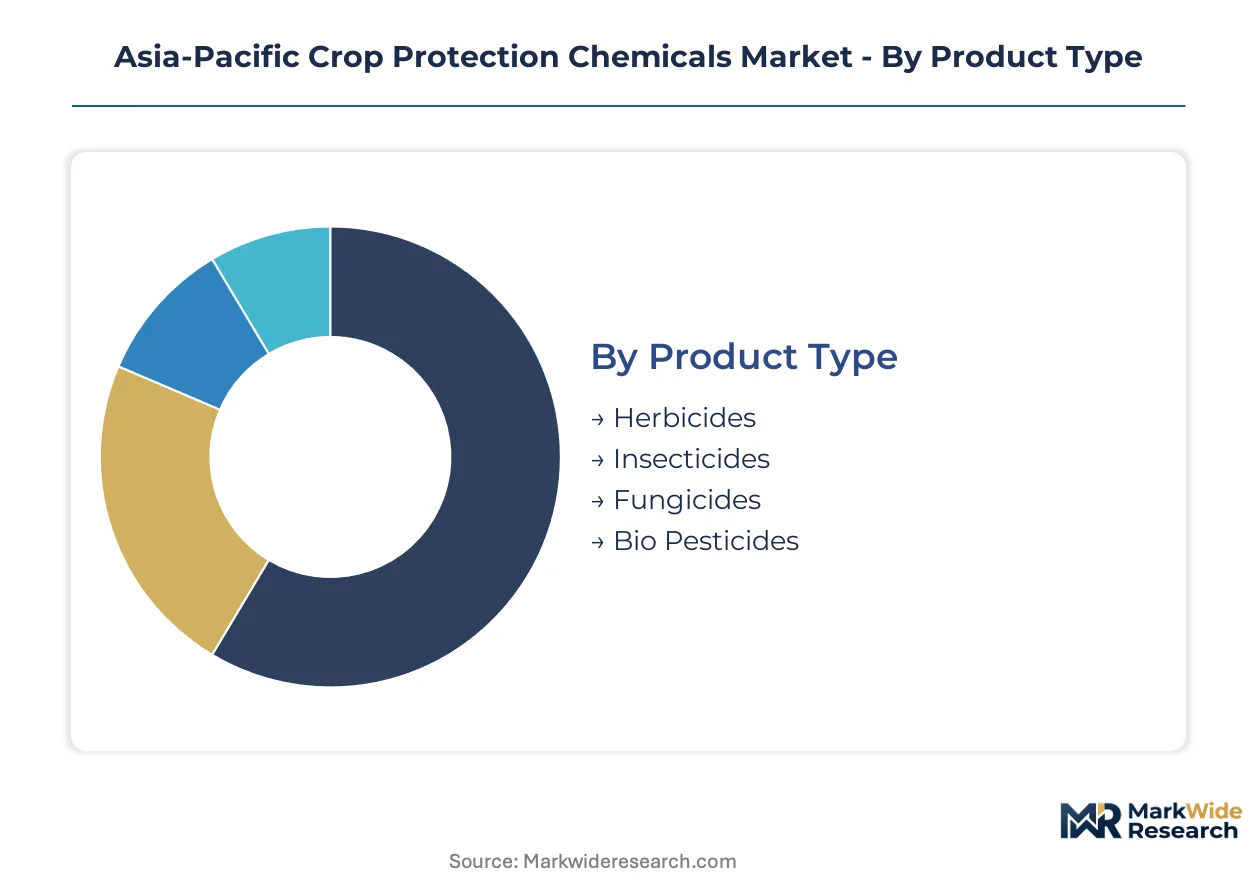
Segmentation across the Asia-Pacific Crop Protection Chemicals Market reveals how formulation chemistry, crop-specific application intensity, and regulatory pressure on residue thresholds are fragmenting procurement patterns. Suppliers must align technical portfolios with divergent mechanization levels and export compliance requirements across rice belts, horticultural zones, and broadacre operations.
Product Type:
Supply concentration in glyphosate technical manufacturing across Shandong and Jiangsu provinces is tilting competitive dynamics toward herbicide-dominant portfolios, with fungicide and insecticide capacity absorbing reformulation investments to meet tightening EU Green Deal residue benchmarks.
- Herbicides:Glyphosate, glufosinate, and pre-emergent formulations command procurement scale across mechanized rice-wheat systems in Vietnam's Mekong Delta and Thailand's Central Plains. Southeast Asian delta cultivation is absorbing volume as labor costs displace manual weeding.
- Insecticides:Pyrethroid and neonicotinoid chemistries face registration compression from Australia's APVMA recalibration, constraining options for stone fruit and vegetable exporters. India's CIBRC indigenous manufacturing mandate is exposing supply gaps for key intermediates.
- Fungicides:SDHI chemistry platforms from BASF SE and generic azole formulations dominate premium and standard tiers respectively, with proprietary strobilurin combinations absorbing R&D allocation for tropical export markets.
- Bio Pesticides:Bacillus-based fermentation products from Indonesian and Philippine contract facilities are climbing the fastest, achieving cost parity with synthetics in certain applications as FSSAI and EU residue protocols tighten.
Today's leader: Herbicides. Tomorrow's challenger: Bio Pesticides.
Application:
Cost tier differentiation separates premium proprietary chemistries for high-value horticultural export crops from economy generic formulations for domestic food grain production, with intermediate pricing capturing mechanized broadacre operations in Australia and China.
- Agricultural:Rice, wheat, and corn cultivation across India's Maharashtra and Gujarat absorbs the largest formulation volumes, with seed-trait chemistry bundling from Corteva Agriscience locking in multi-season procurement commitments.
- Horticultural:Stone fruit, vegetables, and grape production in Australia's export-oriented zones faces the steepest residue compliance costs, with third-party testing infrastructure in Karnataka and Andhra Pradesh bearing similar burdens for Indian exporters to Middle Eastern markets.
- Forestry:Plantation timber protection in Indonesia and Malaysia concentrates demand for long-residual herbicides and termiticides, with aerial application infrastructure determining formulation compatibility.
- Turf & Ornamental:Golf course and landscape maintenance in Japan's Honshu belt and Australia's urban centers absorbs selective herbicide and fungicide volumes, with METI subsidy frameworks accelerating precision equipment deployment.
Agricultural applications anchor current procurement scale; horticultural compliance requirements are expanding fastest as supermarket chain specifications proliferate.
Formulation:
Customer type fragmentation—large-scale Australian and Chinese operators versus Southeast Asian smallholder networks—is driving divergence between liquid formats compatible with aerial and mechanized spray infrastructure and solid formulations suited to manual application.
- Liquid:Suspension concentrates and oil dispersions dominate procurement from large-scale Australian broadacre operators and Chinese state farms, with drone spray infrastructure in Japan's aging rice belts accelerating adoption of ultra-low-volume formats.
- Granular:Slow-release and soil-incorporated formats concentrate in Southeast Asian smallholder rice systems where water management constraints favor basal application, with Vietnam's provincial farmer organizations volume-contracting supply.
- Powder:Wettable powder formulations retain share in manual application contexts across fragmented Indonesian and Philippine smallholder networks, though dust exposure regulations are compressing growth.
- Emulsifiable Concentrates:Traditional EC formats face displacement from suspension concentrates in premium segments, though cost-sensitive Indian and Bangladeshi markets sustain residual demand for generic active ingredient delivery.
Liquid formulations hold installed base dominance; granular formats are gaining share fastest through Southeast Asian cooperative procurement consolidation.
End Use Sector:
Maturity gradients separate established crop protection applications with decades of residue data and registration dossiers from emerging livestock and public health segments confronting novel toxicology requirements and vector resistance management protocols.
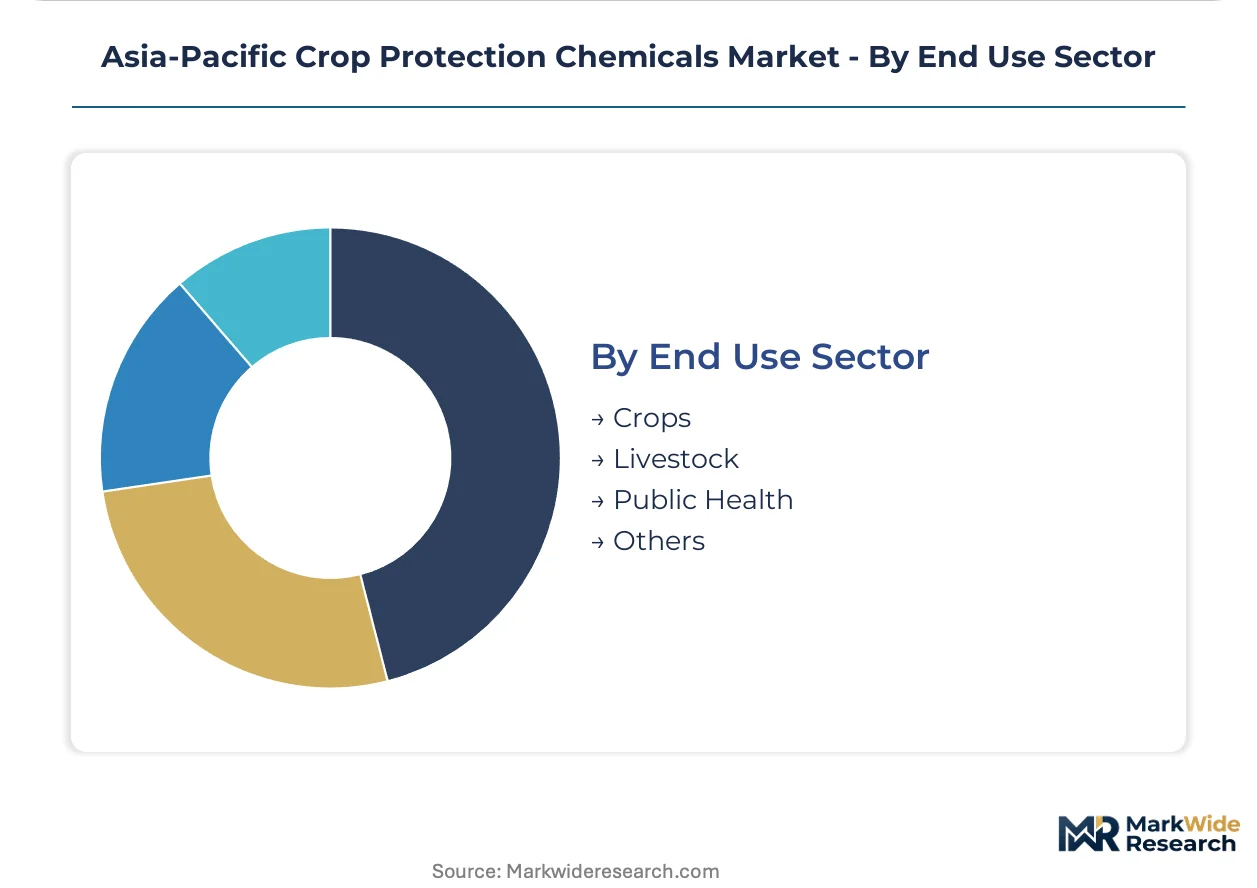
- Crops:Commercial farming systems across China's manufacturing clusters and Australia's grain belts absorb the preponderance of synthetic and biological formulation volumes, with yield protection driving specified active ingredient concentrations and application rates.
- Livestock:Ectoparasiticides and feed additive biocides face divergent regulatory pathways across India's FSSAI monitoring protocols and Australia's APVMA veterinary registration frameworks, with import tolerance harmonization still incomplete.
- Public Health:Vector control applications for malaria and dengue programs in Indonesia, Philippines, and Papua New Guinea concentrate demand for WHO-prequalified insecticide formulations, with resistance management rotating chemistries.
- Others:Industrial vegetation management and aquatic weed control absorb niche volumes, with China's MEE emission caps constraining synthesis of certain phenoxy herbicide intermediates along the Yangtze River basin.
Crops dominate current value capture; public health vector control programs are expanding most quickly as climate shifts extend transmission seasons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural chemist talent pools concentrate in provincial manufacturing clusters across China and India, with formulation specialists gravitating toward Shandong's chemical parks and Gujarat's technical-grade facilities.
China
Glyphosate technical synthesis dominates procurement from Shandong and Jiangsu manufacturing clusters serving Southeast Asian rice-wheat systems. MEE emission caps along the Yangtze River basin have shuttered dispersed capacity, redirecting investment toward licensed chemical parks with integrated wastewater treatment infrastructure.
India
Maharashtra and Gujarat cotton-corn belts absorb seed-trait chemistry bundling through Corteva Agriscience germplasm licensing. CIBRC indigenous manufacturing mandates expose supply gaps for pyrethroid intermediates, forcing domestic producers to absorb elevated input costs or reformulate with alternative chemistries.
Japan
Honshu rice belts deploy METI-subsidized drone spray infrastructure to offset aging agricultural workforce constraints. Precision equipment adoption accelerates ultra-low-volume liquid formulation demand, with suspension concentrates displacing traditional emulsifiable concentrates in paddy field applications.
Australia
Queensland and New South Wales broadacre operators integrate microbial inoculants with reduced-synthetic programs to meet supermarket chain residue specifications. APVMA neonicotinoid recalibration eliminates systemic insecticide options for stone fruit exporters, constraining pest management flexibility without scaled chemical substitutes.
Vietnam
Mekong Delta mechanized cultivation expands glyphosate and pre-emergent herbicide volumes as labor costs displace manual weeding. Provincial farmer organizations consolidate input procurement through volume-contracted supply, compressing distributor margins and favoring manufacturers with direct technical support capabilities.
Asia-Pacific Crop Protection Chemicals Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and active ingredient synthesis. The market structure tilts toward consolidation in technical-grade manufacturing while fragmenting in regional distribution networks. Three strategic archetypes dominate: integrated agrochemical-seed conglomerates, generic technical-grade specialists, and biological fermentation contractors. Competitive moves concentrate on backward integration into proprietary active ingredient synthesis and geographic expansion through distributor acquisition in Southeast Asian cooperative networks.
Within the integrated conglomerate tier, UPL Limited and BASF SE exemplify divergent geographic anchoring strategies. UPL Limited occupies a position leveraging India-centric manufacturing footprints for generic agrochemical cost competitiveness. BASF SE anchors premium fungicide development through proprietary SDHI chemistry platforms. Corteva Agriscience sits within the seed-trait integration archetype, bundling herbicide tolerance with proprietary chemistries to lock in multi-season procurement commitments across India's Maharashtra and Gujarat cotton belts.
| Leading Market Players |
|---|
| UPL Limited |
| Corteva Agriscience |
| Syngenta Group |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical Co. Ltd |
| BASF SE |
| FMC Corporation |
| Nufarm Limited |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Biological fermentation scale-up across Indonesian and Philippine contract facilities is compressing production economics for Bacillus-based biopesticides while concentrating technical-grade synthesis capacity in China's licensed chemical parks. This dual transition simultaneously erodes synthetic pricing premiums and amplifies supply vulnerability from environmental compliance actions along the Yangtze River basin.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with SDHI fungicide platforms commanding brand premiums against generic azole alternatives. Price differentiation rests on EU Green Deal MRL certification tiers and volume scale through cooperative procurement. Cost compression in economy-tier herbicides is intensifying because glyphosate technical oversupply from Shandong manufacturing clusters compresses margins. Smallholder cooperatives in Vietnam's Mekong Delta exhibit highest price sensitivity; export-oriented Australian horticultural operators show lowest.
Supply Chain Analysis
Dual-sourcing requirements from India's CIBRC indigenous manufacturing mandate are forcing domestic formulators to qualify alternative pyrethroid intermediate suppliers beyond traditional China channels. Geographic supply concentration centers on China, India, and Vietnam for technical-grade synthesis and formulation packaging. Raw material dependencies include glyphosate technical, neonicotinoid intermediates, and Bacillus fermentation substrates. Single-source vulnerability from China's Yangtze River basin environmental enforcement threatens active ingredient availability. Distribution runs through provincial farmer organizations and buying cooperatives consolidating Southeast Asian smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Crop Protection Chemicals Market functions as a geographic-arbitrage play between India's CIBRC-mandated domestic manufacturing incentives and China's MEE emission-driven supply constraints, creating divergent cost structures for identical molecules.
For Market Incumbents: Hedge technical-grade supply exposure by securing alternative intermediate sourcing from Vietnam and Indonesia before China's Yangtze River basin enforcement tightens further. Backward integration into proprietary SDHI chemistry platforms defends margin position against generic azole erosion. Prioritize formulation R&D in suspension concentrate and oil dispersion formats for Japan's drone spray infrastructure. For New Entrants and Emerging Players: Australian broadacre operators integrating microbial inoculants represent an underserved buyer archetype seeking bundled biostimulant-biopesticide procurement without legacy synthetic supplier entanglements. White-space targets include Queensland grain handler cooperative contracts and METI-subsidized precision equipment partnerships in Japan's Honshu rice belts. Go-to-market angle: residue-testing infrastructure bundled with input supply to capture horticultural compliance expenditure. For Investors and Strategic Acquirers: Valuations sit cheapest among generic technical-grade specialists lacking proprietary synthesis routes or seed-trait licensing leverage. Long-term viability favors integrated agrochemical-seed conglomerates with captive germplasm platforms and multi-season chemistry lock-in across India's cotton belts. Watch for FSSAI residue protocol harmonization with EU Green Deal benchmarks as inflection indicator for biopesticide adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Active Ingredient Synthesis | BASF SE's SDHI chemistry platforms demonstrate how captive R&D moats sustain premium pricing against generic competition. |
| Seed-Trait Chemistry Bundling | Corteva Agriscience's germplasm licensing across Maharashtra and Gujarat locks multi-season procurement commitments through herbicide tolerance stacking. |
| Biological Fermentation Scale-Up | Indonesian and Philippine contract facilities achieving cost parity with synthetics reshape competitive economics under tightening FSSAI residue protocols. |
| Drone Spray Infrastructure Deployment | METI subsidies accelerating ultra-low-volume liquid adoption in Japan's aging rice belts create formulation format switching costs. |
| Cooperative Procurement Consolidation | Vietnam's provincial farmer organizations volume-contracting supply compress distributor margins and favor direct technical support capabilities. |
Methodological Framework
Coverage spans China, India, Japan, Australia, and Vietnam, with primary inputs from each market's regulatory and manufacturing clusters. The analysis combines interviews with plant managers at Shandong and Jiangsu chemical parks, procurement leads at Australian broadacre cooperatives, distribution channel partners across Southeast Asian rice belts, and regulatory affairs specialists navigating CIBRC and APVMA frameworks. Secondary validation draws from MEE emission enforcement records, FSSAI residue monitoring protocols, customs trade data for glyphosate technical flows, and SEC filings from listed agrochemical conglomerates. Bottom-up formulation volume estimates triangulate against top-down crop acreage and application intensity benchmarks.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product chemistry class, crop application intensity, formulation format compatibility with mechanized infrastructure, and export-versus-domestic orientation. CAGRs derive from weighted average of historical trajectory and forward scenario analysis. Industry-specific inputs incorporate CIBRC indigenous manufacturing mandate implementation timelines and EU Green Deal MRL benchmark adoption curves.
Underlying measurement precision varies by segment; biopesticide fermentation volumes carry tighter precision than synthetic active ingredient synthesis where environmental enforcement disrupts reporting consistency. Forecasts reflect assumptions on regulatory harmonization pace and cooperative procurement consolidation velocity. Deviation in China's MEE enforcement intensity or India's intermediate supply gap resolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Acaricides Market
Crop Protection
Global Turf Protection Market
Crop Protection
US Herbicide Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
US Insecticide Market
Crop Protection
Pest Control Products Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Propiconazole Market
Crop Protection
US Pest Control Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Generic Crop Protection Chemicals Market