
 Hay Bags Market | 2026-2036
Hay Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Hay Bags Market Analytics
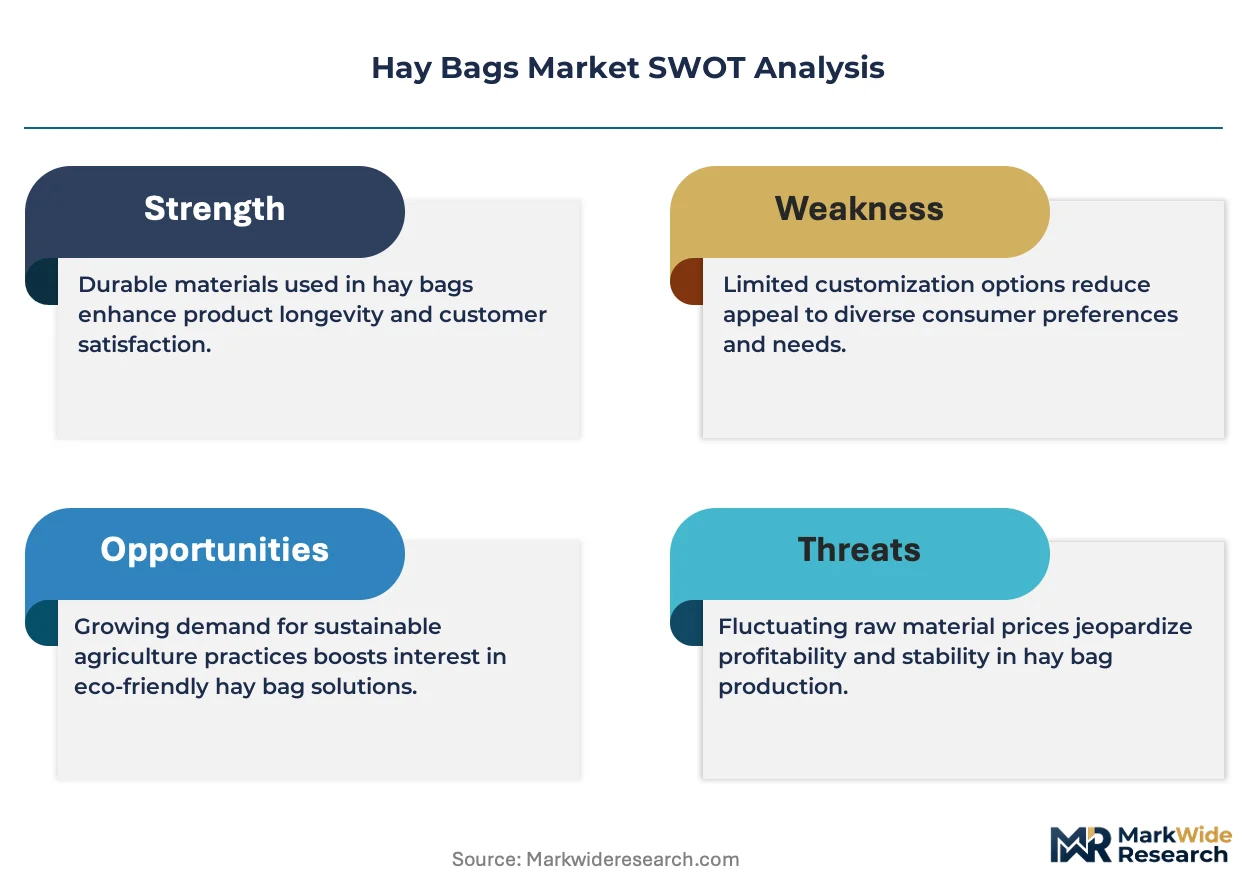
ASTM F963 compliance is collapsing the field of qualified suppliers, forcing smaller fabricators to either invest in third-party testing or exit the North American channel entirely. HORKA leverages its European manufacturing base to sustain certification dualities across REACH and U.S. consumer safety frameworks. Weaver Equine anchors its competitive position through specialized equine channel relationships and rodeo circuit distribution.
Hay bags are woven or sewn textile containers engineered to hold, dispense, and protect forage for livestock, typically constructed with denier ratings between 600D and 1200D and reinforced stress points to withstand equine biting and pulling forces. Their primary commercial purpose centers on reducing feed waste, controlling consumption rates, and enabling portable forage management across stable, trail, and competition environments. Mesh hay bags command premium positioning among equine owners seeking slow-feed functionality, while durable hay bags built from ballistic nylon occupy the margin-rich professional rancher segment where replacement cycles extend operational cost calculations. Standard hay bags in polyester remain the volume foundation, though cotton variants are gaining traction in show preparation applications where aesthetic presentation intersects with natural fiber preferences.
FDA guidance on animal food safety under the Food Safety Modernization Act shapes material selection and cleanability standards for hay bags entering commercial livestock operations, while CPSC jurisdiction over consumer products mandates child-safety labeling and flammability testing for retail-channel items. State-level agricultural extension services in Kentucky and Texas supplement federal frameworks with region-specific recommendations on feed storage hygiene. Stakeholders must monitor how pending PFAS restrictions in textile coatings could force material reformulations across the nylon and polyester supply chains.
Market Dynamics
ASTM F963 compliance mandates are compressing the supplier base for North American distribution, forcing fabricators to absorb third-party testing costs or surrender retail shelf presence to certified competitors.
Growth Catalysts
- USDA livestock feed handling guidelines:Evolving federal standards on forage storage hygiene are compelling commercial equine operations to replace open-ground feeding with contained bag systems.
- Mesh slow-feed engineering:Veterinary-endorsed consumption-rate control is driving premium adoption among performance horse trainers seeking digestive health optimization.
- Texas and Kentucky corridor concentration:Dense horse-breeding clusters generate localized demand pull that sustains specialized distributor networks and reduces customer acquisition costs.
Market Restraints
- Ballistic nylon input volatility:Petroleum-derived fiber costs fluctuate with upstream polymer pricing, squeezing margin on professional-grade rancher SKUs.
- PFAS coating dependency:Pending EPA restrictions on per- and polyfluoroalkyl substances threaten water-repellent finishes across polyester and nylon supply chains.
- Certification cost asymmetry:Small-batch weavers face disproportionate testing burdens relative to volume, accelerating supplier consolidation.
Strategic Opportunities
- Show preparation cotton variants:Natural fiber aesthetics at elite equine competitions create price-insensitive niche above commodity polyester.
- European REACH alignment:Dual-certified manufacturers can access premium positioning in Equestrian disciplines where import buyers prioritize chemical safety documentation.
- Direct-to-stable digital channels:Bypassing rodeo-circuit distributors lets specialized brands capture margin from tech-adopting hobbyist segments.
Industry Challenges
- ASTM F963 testing timeline compression:Certification backlog at accredited labs delays product launches and strains working capital.
- Denier specification talent scarcity:Technical weaving expertise for 1200D stress-point engineering concentrates in legacy textile regions, limiting geographic flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hay Bags Market |
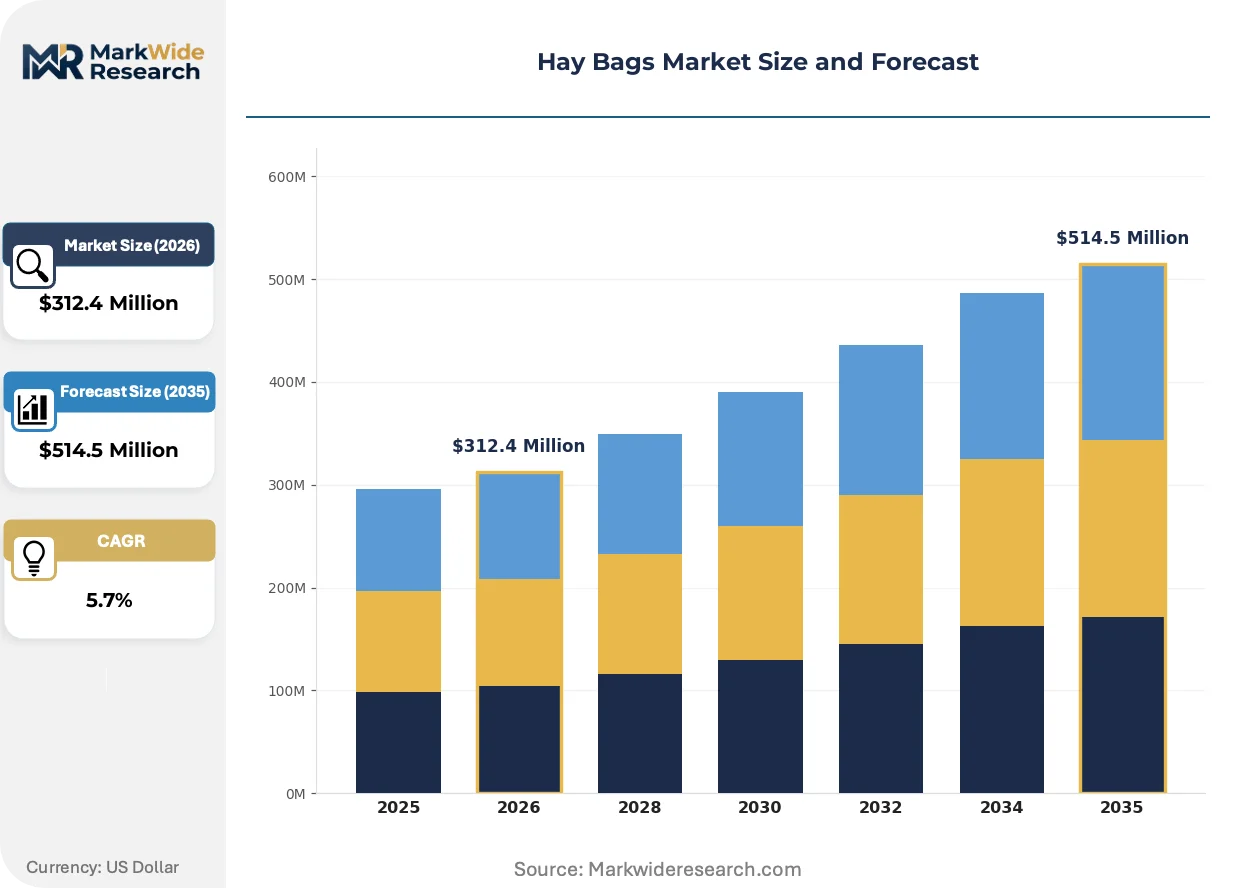
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $514.5 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hay Bags, Feed Bags, Mesh Hay Bags, Durable Hay Bags Material: Polyester, Nylon, Cotton, Canvas End User: Farmers, Ranchers, Equine Owners, Veterinarians Application: Animal Feed Storage, Transportation, Feeding, Show preparation |
| Companies Covered | HORKA, Tack Wholesale LLC, Jacks Manufacturing Inc., Arrow International, Thin Air Canvas, Hay Chix, Weaver Equine, Coolhorse, Standlee Premium Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hay Bags Market Evolving Landscape
Material science advances and regulatory chemistry constraints are rewriting product specifications faster than brand positioning can stabilize, creating temporary advantage windows for agile manufacturers.
Recycled ocean-bound polyester filament is supplanting virgin polymer feedstock in standard hay bag construction. Equestrian retail buyers in California and Florida are demanding visible sustainability credentials at parity pricing. This shift is compressing first-mover advantage windows as supply chains scramble for certified recycled sources.
REACH SVHC disclosure requirements are forcing reformulation of textile dyes and antimicrobial treatments across EU-bound production. Manufacturers serving dual markets now maintain parallel material specifications, raising complexity but creating defensible positioning against single-market competitors. Kentucky-based exporters are investing in segregated inventory systems to preserve European channel access.
Subscription-based forage bag replacement programs are emerging among professional boarding facilities seeking predictable operational expenditures. Traditional distributor relationships face disintermediation as stable managers prioritize automated reorder systems over rodeo-circuit sales relationships. This pattern is most pronounced in Texas metro corridors where facility consolidation has created concentrated buyer power.
Hay Bags Market Segmentation
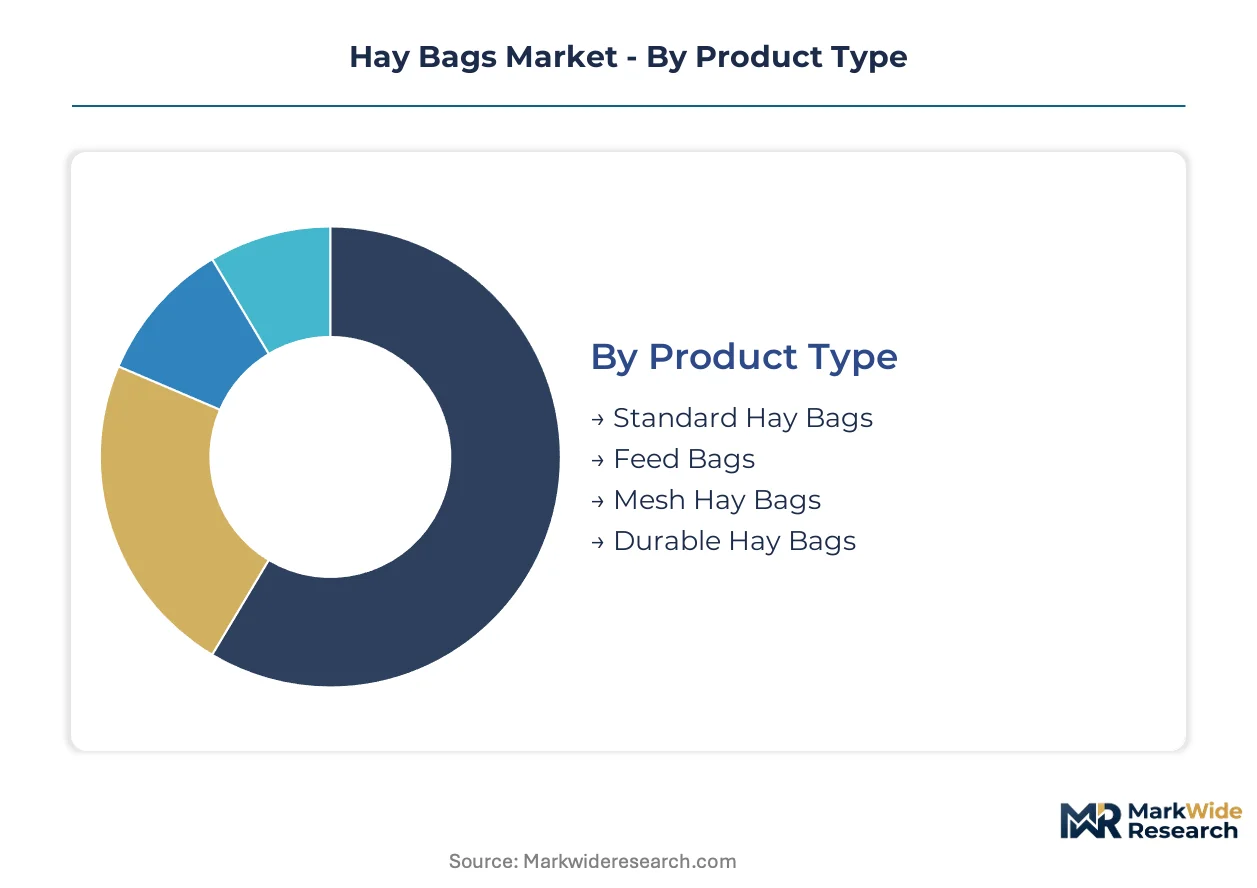
Channel differentiation in hay bags depends heavily on material certification tiers and end-use durability requirements. Product positioning across rodeo-circuit distributors, direct-to-stable digital platforms, and agricultural supply cooperatives varies sharply by segment characteristics.
Product Type:
Channel mix splits sharply between retail-shelf standard units and professional-grade SKUs moving through specialized equine distributors.
- Mesh Hay Bags:Engineered with aperture-controlled openings to regulate forage extraction speed and extend consumption time. Demand concentrates among Kentucky and Texas performance horse trainers where veterinary-endorsed digestive health protocols command premium pricing.
- Durable Hay Bags:Constructed from ballistic nylon or reinforced polyester with 1200D denier ratings and double-stitched stress points. Professional ranchers across Texas breeding corridors drive procurement, prioritizing replacement cycle economics over upfront cost.
- Standard Hay Bags:Volume foundation built from 600D polyester with basic reinforced openings. Hobbyist equine owners and small-scale farmers purchase through mass-market agricultural retailers.
- Feed Bags:General-purpose containers lacking specialized slow-feed engineering. Price-sensitive agricultural operations in secondary markets represent core demand.
Standard hay bags dominate installed base. Mesh hay bags are where expansion concentrates.
Material:
Cost tier stratification separates commodity synthetics from natural fiber premiums in show-ring applications.
- Polyester:Petroleum-derived filament dominates volume production with 600D-900D specifications standard. FDA Food Safety Modernization Act compliance on cleanability drives material selection in commercial livestock operations.
- Nylon:Superior abrasion resistance and tensile strength support 1200D professional-grade construction. Input cost volatility tied to upstream polymer pricing squeezes margin on rancher-targeted SKUs.
- Cotton:Natural fiber aesthetic appeals to elite competition preparation segments where presentation standards override durability metrics.
- Canvas:Heavy-duty woven cotton or cotton-blend construction serving heritage-brand positioning and artisanal fabricator niches.
Polyester holds the volume base. Cotton is climbing the fastest in premium positioning.
End User:
Customer type determines procurement channel and price elasticity, from automated facility purchasing to individual hobbyist transactions.
- Equine Owners:Spanning hobbyist to professional trainer segments with divergent priorities between slow-feed functionality and show-presentation aesthetics. Kentucky corridor concentration sustains specialized distributor networks.
- Ranchers:Large-scale commercial operations calculating total cost of ownership across extended replacement cycles. Texas metro corridor facility consolidation is driving subscription-based reorder system adoption.
- Farmers:General livestock operations prioritizing feed waste reduction and basic containment over specialized equine features.
- Veterinarians:Professional endorsement channel influencing trainer purchasing decisions rather than direct procurement authority.
Equine owners represent the deepest installed base. Ranchers are gaining share fastest through operational consolidation.
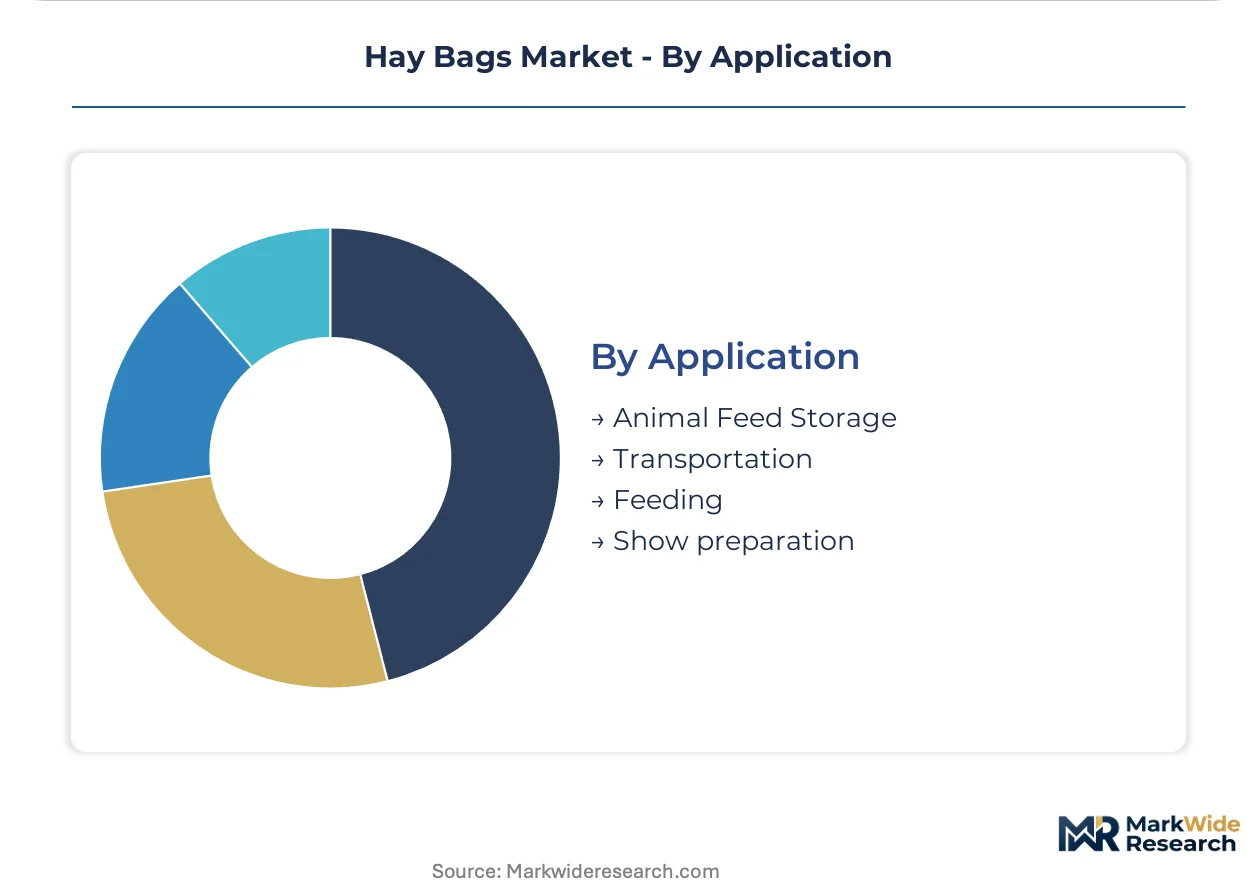
Application:
Volume distribution tracks operational setting, from permanent stable infrastructure to mobile competition logistics.
- Feeding:Core functional deployment encompassing both ground-level consumption and elevated slow-feed installation. Mesh engineering penetration is highest in this use case.
- Animal Feed Storage:Containment-focused applications emphasizing protection from moisture, pests, and contamination. USDA livestock feed handling guidelines are compelling contained system adoption.
- Transportation:Portable forage management for trail riding, competition travel, and rotational grazing operations. Durability specifications prioritize stress-point reinforcement.
- Show preparation:Aesthetic presentation requirements at elite competitions where natural fiber preferences intersect with grooming and turnout standards.
Feeding commands the largest operational footprint. Show preparation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional equine operations and commercial breeding facilities concentrate procurement authority in distinct geographic corridors where regulatory density and veterinary infrastructure align. Buyer archetypes cluster around USDA-compliant commercial stables, performance training centers, and large-scale ranching operations with distinct compliance obligations.
United States
Kentucky and Texas breeding corridors generate concentrated demand pull from Thoroughbred racing operations and quarter horse breeding facilities. FDA Food Safety Modernization Act guidance on animal feed storage hygiene compels commercial operations toward contained bag systems. The Kentucky Horse Park region sustains specialized distributor networks serving elite competition stables.
Germany
Equestrian discipline excellence drives premium positioning for REACH-certified equipment across professional dressage and show jumping facilities. ECHA SVHC disclosure requirements force reformulation of textile dyes and antimicrobial treatments. The Münsterland region anchors manufacturing capacity for dual-certified export production serving both EU and North American channels.
United Kingdom
Elite eventing and hunting traditions sustain demand for natural fiber presentation standards at competition venues. Defra agricultural standards on livestock feed storage supplement EU regulatory frameworks pre- and post-Brexit. The Cotswolds corridor concentrates high-value equine operations with specialized procurement requirements.
Australia
Endurance riding and station-based working horse operations drive demand for extreme durability specifications in remote grazing environments. Biosecurity regulations under the Department of Agriculture, Fisheries and Forestry govern feed storage and transport containment. The Hunter Valley region combines Thoroughbred breeding density with racing industry infrastructure.
France
Selle Français breeding programs and international competition hosting create demand for dual-aesthetic-functional equipment. ANSM oversight of consumer product safety intersects with agricultural ministry guidelines on livestock feed handling. The Normandy region concentrates breeding operations with export-oriented quality standards.
Hay Bags Market Competitive Landscape
Player mix skews toward specialized equine equipment fabricators and diversified agricultural textile manufacturers. The supplier base compresses around ASTM F963 certification requirements, with third-party testing costs forcing exit or consolidation among smaller weavers. Three strategic archetypes dominate: European REACH-certified exporters, rodeo-circuit specialized distributors, and direct-to-stable digital-first brands. Competitive moves concentrate on certification dualities and subscription-based reorder system deployment.
Among European-based manufacturers, HORKA exemplifies the dual-certification archetype spanning REACH and U.S. consumer safety frameworks. Weaver Equine anchors the specialized equine channel position through rodeo circuit distribution relationships. Hay Chix occupies a position within the slow-feed engineering segment where veterinary endorsement drives premium positioning.
| Leading Market Players |
|---|
| HORKA |
| Tack Wholesale LLC |
| Jacks Manufacturing Inc. |
| Arrow International |
| Thin Air Canvas |
| Hay Chix |
| Weaver Equine |
| Coolhorse |
| Standlee Premium Products |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day fabric lead times from Asian textile mills compress working capital cycles for North American distributors, concentrating pricing power with REACH-certified manufacturers who maintain segregated inventory buffers against ASTM F963 certification delays. This temporal asymmetry rewards dual-certified European suppliers while squeezing margin on commodity polyester standard units.
Pricing Analysis
Cost-plus contracts indexed to upstream polymer pricing dominate professional-grade ballistic nylon procurement, with rancher-facing SKUs carrying 1200D denier premiums tied to replacement cycle guarantees. Three-tier pricing structure across premium mesh slow-feed, standard polyester, and economy feed bag levels separates veterinary-endorsed functionality from basic containment. Cost compression in standard polyester units is intensifying because recycled ocean-bound filament supply scarcity forces parity pricing against virgin material. Hobbyist equine owners show highest price sensitivity, while Texas facility managers purchasing through subscription reorder systems prioritize predictable operational expenditure over per-unit cost.
Supply Chain Analysis
Ninety-day raw fabric lead times from Chinese and Vietnamese weaving operations tether North American distributors to ocean freight scheduling volatility. Ballistic nylon filament draws from petroleum-derived polymer supply chains centered in South Korea and Taiwan, while recycled polyester feedstock sources from Southeast Asian collection networks. Single-source vulnerability concentrates in 1200D denier technical weaving capacity located in legacy textile regions. Distribution runs through rodeo-circuit specialized networks and direct-to-stable digital platforms serving Kentucky and Texas corridor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hay bag adoption sits in early-cycle expansion as USDA livestock feed handling guidelines compel commercial equine operations toward contained bag systems, creating regulatory tailwinds that outpace penetration in general agricultural livestock segments.
For Market Incumbents: Compound certification advantages by extending REACH-compliant production capacity into Münsterland-adjacent facilities, securing dual-market positioning against emerging digital-first entrants threatening rodeo-circuit distributor relationships. Absorb third-party ASTM F963 testing costs to compress the qualified supplier field, converting certification burden into structural moat. For New Entrants and Emerging Players: Differentiate on subscription-based reorder automation targeting Texas metro corridor facility consolidation, where stable managers prioritize predictable expenditure over established distributor relationships. Penetrate the show preparation cotton variant segment where natural fiber aesthetics command price-insensitive positioning at elite competitions. Deploy direct-to-stable digital channels bypassing traditional rodeo-circuit intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural textile manufacturers with idle equine-specialized capacity and existing 1200D denier weaving expertise. Five-to-ten year viability hinges on PFAS coating reformulation capabilities and recycled feedstock certification access. Monitor EPA per- and polyfluoroalkyl substance restriction timelines as inflection indicator for material science investment prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Investment | REACH and ASTM F963 alignment preserves European and North American channel access against regulatory divergence. |
| Recycled Feedstock Integration | Ocean-bound polyester certification satisfies California and Florida retailer sustainability credential requirements at parity pricing. |
| Subscription Reorder Platform Launch | Automated replenishment captures Texas facility consolidation procurement authority from traditional distributor networks. |
| Slow-Feed Engineering Patent Filing | Veterinary-endorsed consumption-rate control secures premium positioning among Kentucky performance horse trainers. |
| PFAS-Free Coating Reformulation | Anticipatory EPA compliance investment protects nylon and polyester supply chain continuity against pending restrictions. |
Research Methodology
Operator-level perspectives from equine facility managers, rodeo-circuit distributors, textile procurement leads, veterinary nutrition specialists, and agricultural cooperative buyers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against USDA livestock feed handling guidance documents, FDA Food Safety Modernization Act compliance filings, and ASTM F963 testing accreditation records. Trade customs data, textile industry association reports, and state-level agricultural extension service publications provided quantitative triangulation against bottom-up facility procurement surveys and top-down market sizing across product type, material, end user, and application dimensions.
Sensitivity analysis across polymer price volatility scenarios and PFAS regulatory timeline assumptions framed the analytical approach over the projection horizon. Segmentation modeling captured product type differentiation between mesh slow-feed, durable ballistic nylon, standard polyester, and cotton variant tiers; material grade stratification; end user archetypes spanning hobbyist equine owners, professional ranchers, and commercial facility managers; and application settings from stable feeding through transportation and show preparation. CAGRs derived from replacement cycle economics, facility consolidation patterns, and regulatory compliance adoption curves specific to Kentucky and Texas breeding corridor density.
Material uncertainties — EPA PFAS restriction finalization timing, recycled polyester feedstock certification availability, and ASTM F963 testing laboratory capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pace and supply chain adaptation capacity without claiming predictive precision on specific policy effective dates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
North America Silo Bags Market