
 Africa Agricultural Film Market | 2026-2036
Africa Agricultural Film Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Agricultural Film Market Outlook
The capital-intensity gap between integrated resin producers and regional converters is collapsing as polymer supply localizes. Berry Global leverages backward integration into polyethylene resin to sustain margin structures across North African distribution networks. Gundle Plastics Group anchors its position through Gauteng-based manufacturing scale that dominates South African silage film supply. Armando Alvarez competes via specialized five-layer coextrusion lines serving Moroccan greenhouse exporters.
Africa agricultural film denotes thermoplastic sheeting, typically 15-200 microns in thickness, manufactured through blown film extrusion of polyethylene resins with UV stabilizers and anti-drip additives to modify microclimate conditions for crop production. Mulch film leads volume across the continent's open-field tomato and maize belts, while biodegradable polymer formulations represent the fastest-expanding material category as Kenyan and Rwandan regulators restrict conventional polyethylene burial. Greenhouse film commands premium pricing in Ethiopia's flower export zones where optical clarity and thermal retention properties directly affect rose stem quality and auction grades.
South Africa's National Regulator for Compulsory Specifications enforces SABS standards for agricultural film photodegradation rates, while Kenya's National Environment Management Authority implements extended producer responsibility frameworks for post-harvest plastic recovery. The EU Green Deal's deforestation-free supply chain due diligence rules, applied to African horticultural exports, indirectly mandate traceable film inputs in certified greenhouse operations. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus for imported virgin resin versus recycled-content alternatives.
Market Dynamics
The capital-intensity gap between integrated resin producers and regional converters is collapsing as polymer supply localizes across North and East Africa. Berry Global leverages backward integration into polyethylene resin to sustain margin structures across North African distribution networks. Gundle Plastics Group anchors its position through Gauteng-based manufacturing scale that dominates South African silage film supply. Armando Alvarez competes via specialized five-layer coextrusion lines serving Moroccan greenhouse exporters.
Growth Catalysts
- EU Green Deal deforestation-free due diligence:Horticultural export certification requirements in Ethiopia and Kenya mandate traceable film inputs in certified greenhouse operations, pulling premium-grade greenhouse film demand.
- Biodegradable polymer formulations:Kenyan and Rwandan regulators restrict conventional polyethylene burial, accelerating substitution toward compostable mulch alternatives in open-field vegetable production.
- East African highland vegetable corridors:Greenhouse operators in Kenya and Ethiopia expand polyethylene film coverage to extend growing seasons for European export contracts.
Market Restraints
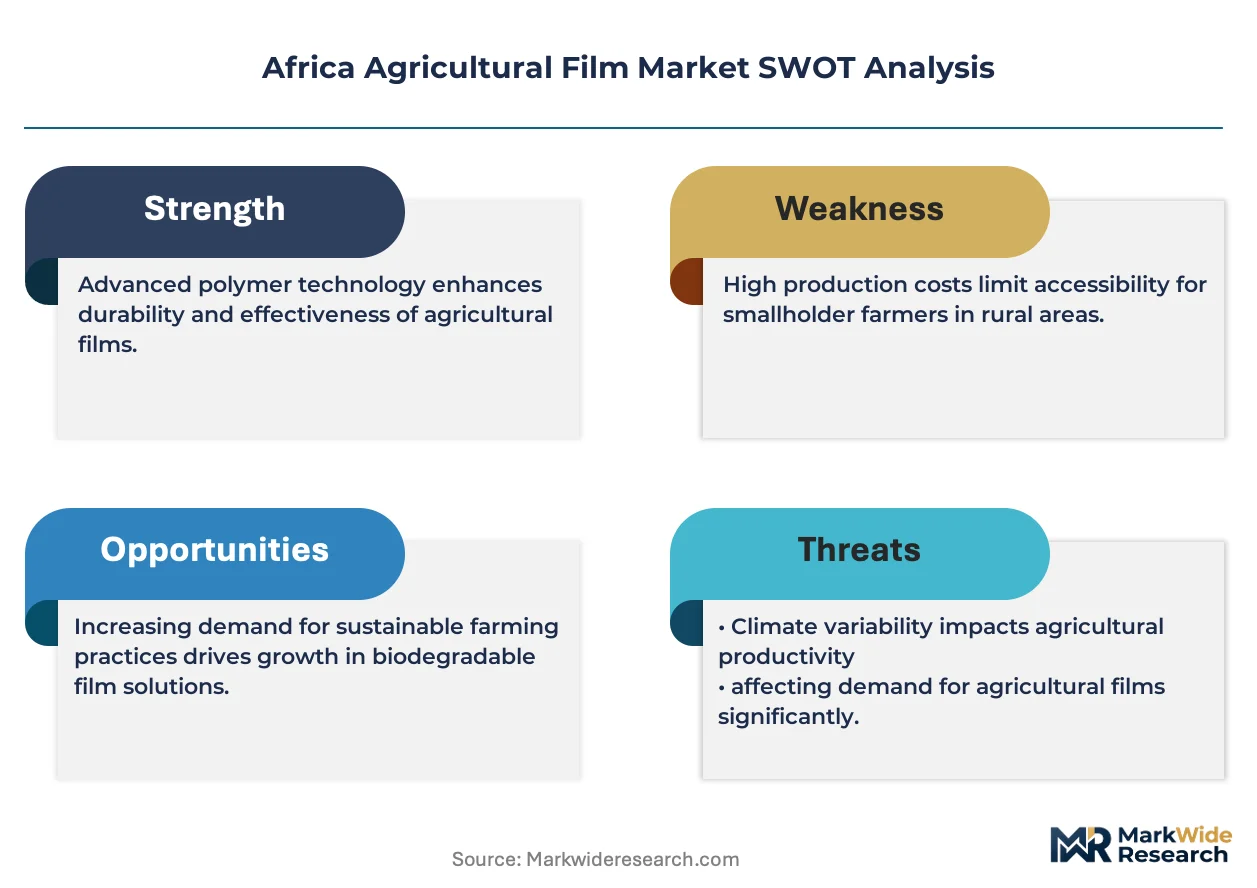
- Virgin resin import dependency:Most African converters rely on imported polyethylene pellets, exposing margin structures to freight cost volatility and currency fluctuation against the dollar.
- Extended producer responsibility compliance costs:Kenya's National Environment Management Authority implements post-harvest plastic recovery frameworks that raise operational overhead for smallholder-facing distributors.
- Photodegradation standard enforcement gaps:Inconsistent testing infrastructure across the continent creates quality arbitrage between SABS-compliant South African supply and informal imports.
Strategic Opportunities
- Rwanda's biodegradable mandate acceleration:The country's regulator is tightening restrictions on conventional polyethylene burial faster than regional peers, creating first-mover advantage for compostable film suppliers.
- Silage film penetration in dairy belts:South Africa's KwaZulu-Natal and Eastern Cape dairy clusters show underpenetrated mechanized forage preservation relative to European benchmarks.
- Anti-drip additive specialization:Ethiopian rose export zones require optical clarity and thermal retention properties that command premium pricing at auction.
Industry Challenges
- Five-layer coextrusion technician scarcity:Specialized blown film line operators are concentrated in Morocco and South Africa, constraining expansion timelines for East African greenfield projects.
- UV stabilizer formulation adaptation:High-altitude East African growing regions require customized additive packages that differ from coastal North African specifications, complicating pan-regional product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Agricultural Film Market |
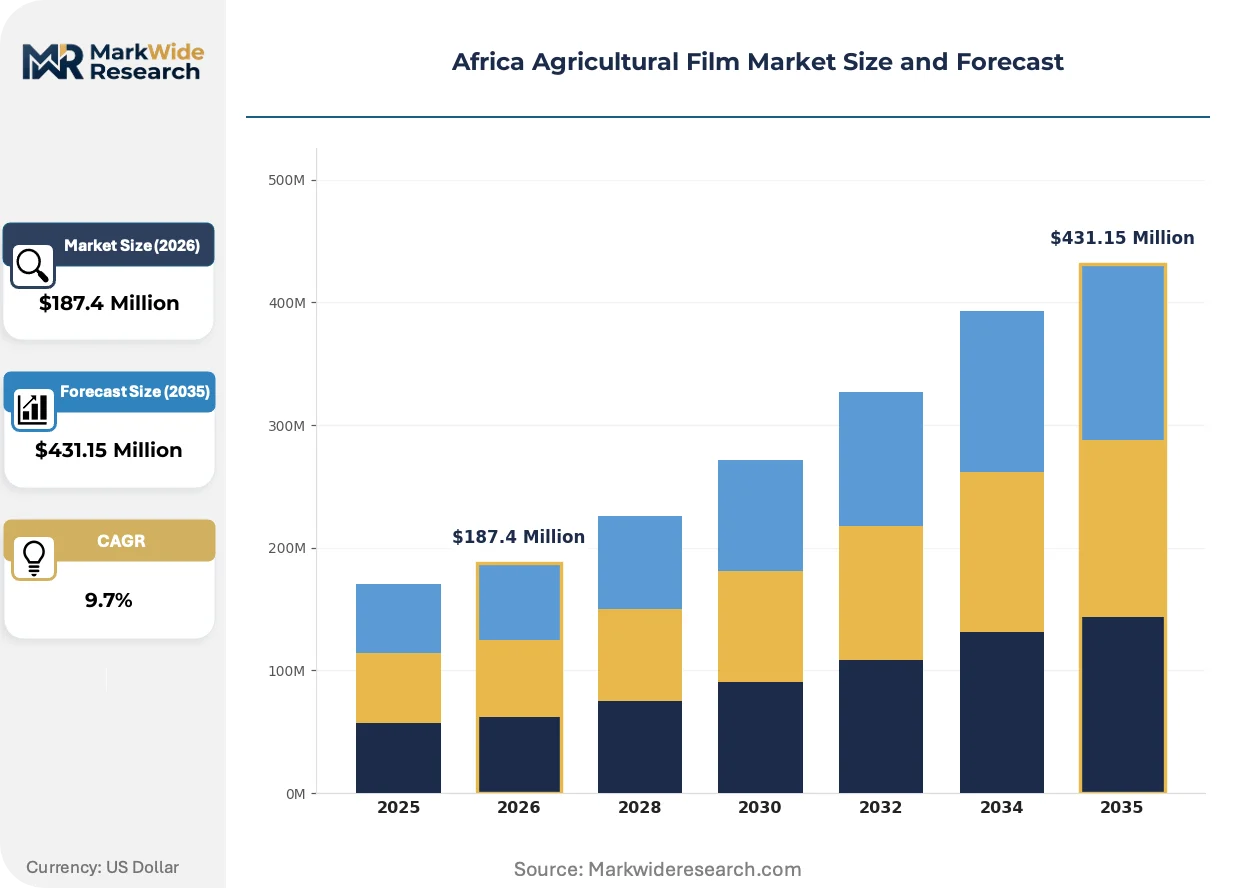
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mulch Film, Greenhouse Film, Silage Film, Stretch Film Material: Polyethylene, Polypropylene, Biodegradable Polymers, Polyvinyl Chloride Application: Crops, Greenhouses, Silage, Nurseries End User: Farmers, Agricultural Companies, Research Institutions, Distributors |
| Companies Covered | Berry Global, Inc., Armando Alvarez S.A., Ginegar Plastic Products Ltd., BASF SE, Mondi PLC, Trioworld, Gundle Plastics Group (PTY) Ltd, INDEVCO Group, RKW SE, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Agricultural Film Market Strategic Shifts
Material science convergence with regulatory pressure is compressing product development cycles across African agricultural film supply chains. Converters now face simultaneous demands for biodegradability certification, optical performance optimization, and cost parity with conventional polyethylene.
Nanoclay-reinforced polyethylene films are miniaturizing thermal barrier layers while maintaining mechanical durability in greenhouse applications. Ethiopian flower exporters and Kenyan vegetable cooperatives adopt these formulations to reduce heating fuel consumption during cold seasons. The technology is compressing energy cost structures for high-altitude greenhouse operators who previously relied on thicker conventional films.
Kenya's National Environment Management Authority implements extended producer responsibility frameworks that mandate post-harvest plastic recovery from farm gate to converter gate. This industrial consequence forces distributors to integrate reverse logistics capabilities or forfeit access to licensed horticultural export zones. Smallholder tomato and maize belts in the Rift Valley face the steepest compliance cost adjustments as informal collection networks formalize.
Export contract specifications now embed film traceability requirements that displace spot-market purchasing patterns among large greenhouse operators. Ethiopian rose auction houses and Kenyan bean packers increasingly require lot-level documentation of UV stabilizer content and resin origin. This behavioral shift concentrates procurement authority with integrated converters who control resin sourcing, squeezing independent traders in Addis Ababa and Nairobi distribution channels.
Africa Agricultural Film Market Segmentation
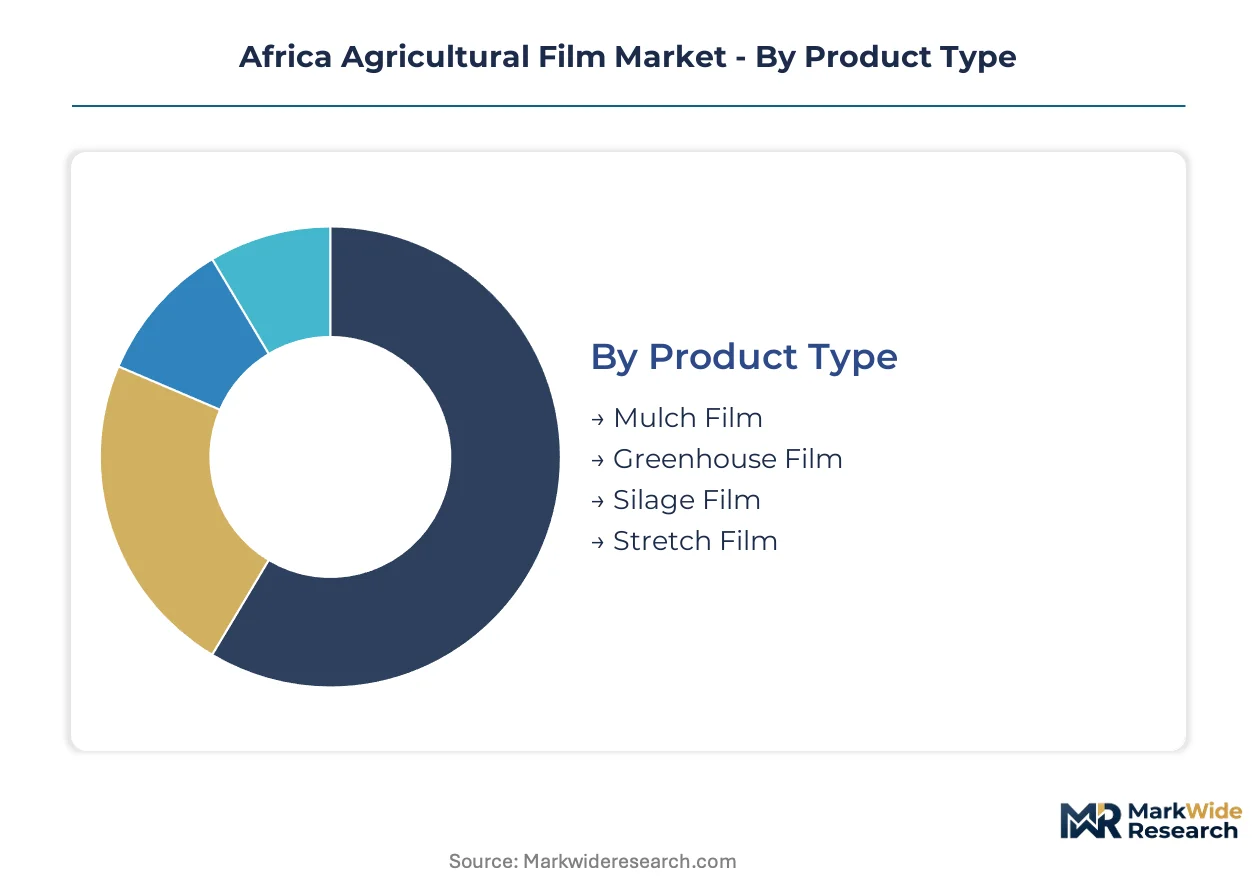
Agricultural film procurement patterns in Africa diverge sharply between export-oriented greenhouse operators and domestic food crop producers. Channel structures for mulch film run through informal trader networks in Kenya's Rift Valley, while greenhouse film flows via certified distributor agreements tied to EU export compliance.
Product Type:
Channel economics determine which film categories dominate specific supply routes. Silage film concentrates in South Africa's formal dairy cooperative procurement systems. Stretch film moves through packaging distributors serving Nairobi and Johannesburg logistics hubs.
- Mulch Film:Polyethylene sheeting 15-50 microns thick, typically black or transparent, suppresses weeds and moderates soil temperature for open-field tomato and maize production. Demand clusters in Kenya's highland vegetable corridors where smallholders serve European export contracts through cooperative aggregation.
- Greenhouse Film:UV-stabilized polyethylene 150-200 microns with anti-drip additives, engineered for optical clarity and thermal retention in controlled environment agriculture. Ethiopian rose export zones in the Rift Valley specify these formulations for auction-grade stem quality, with procurement tied to EU Green Deal traceability requirements.
- Silage Film:High-tack polyethylene sheets for anaerobic forage preservation in South Africa's KwaZulu-Natal and Eastern Cape dairy belts.
- Stretch Film:Linear low-density polyethylene for palletized horticultural produce transport through Durban and Mombasa port corridors.
By volume, Mulch Film leads across African open-field vegetable belts. By growth pace, Greenhouse Film is climbing the fastest on export certification pull.
Material:
Cost tier structures separate commodity polyethylene from premium biodegradable alternatives. Virgin resin import exposure compresses margins at the standard tier while regulatory mandates in East Africa create pricing power for compostable formulations.
- Polyethylene:Linear low-density and low-density grades dominate blown film extrusion for 80% of African agricultural film tonnage. South African converters leverage Gauteng-based manufacturing scale to supply domestic silage demand, though all rely on imported pellets exposed to dollar freight volatility.
- Biodegradable Polymers:Starch-based and polylactic acid formulations certified for compostable burial, responding to Kenyan and Rwandan regulatory restrictions on conventional polyethylene soil disposal. Rwanda's accelerated mandate timeline creates first-mover pricing premiums for compliant suppliers.
- Polypropylene:Higher stiffness and temperature resistance for specialized nursery applications and thermal blankets in Morocco's Atlas Mountain vegetable zones.
- Polyvinyl Chloride:Limited use in rigid cloche and tunnel structures where chemical resistance priorities override flexibility requirements.
Polyethylene captures the greatest volume share. Biodegradable Polymers are expanding most quickly on regulatory substitution mandates.
Application:
Customer maturity varies sharply across application segments. Silage preservation requires mechanized forage handling infrastructure concentrated in South Africa, while nursery propagation demands technical knowledge scarce outside Morocco and Kenya's central highlands.
- Crops:Mulch film deployment for soil moisture retention and weed suppression across rain-fed and irrigated open-field systems. Nigeria's northern tomato belts and Tanzania's southern maize corridors represent underpenetrated expansion zones relative to Kenyan adoption rates.
- Greenhouses:Controlled environment film structures for year-round production of high-value vegetables and cut flowers. Ethiopia's flower export zones and Kenya's bean packers now require lot-level film documentation for EU deforestation-free supply chain compliance.
- Silage:Anaerobic storage systems for dairy and beef operations, with South Africa's commercial feedlots driving regional demand concentration.
- Nurseries:Propagation tunnels and seedling protection films serving commercial vegetable transplant operations.
Crops application leads by installed film area. Greenhouses application shows the steepest expansion trajectory on export horticulture investment.
End User:
Procurement authority concentrates differently across user types. Agricultural Companies control greenhouse film specification through integrated export operations, while Distributors face rising compliance overhead from Kenya's extended producer responsibility frameworks.
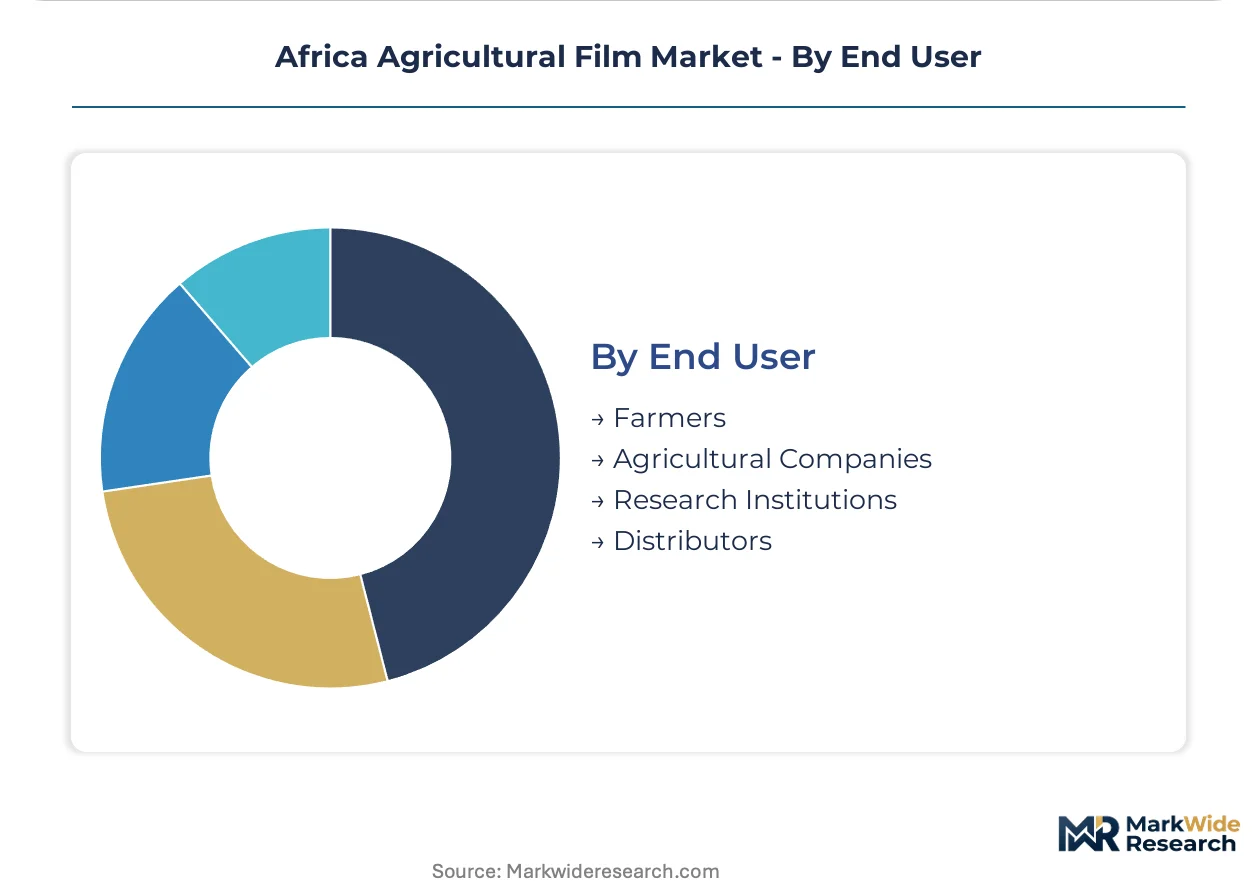
- Farmers:Smallholder tomato and maize producers in Kenya's Rift Valley and Ethiopia's Central Highlands purchase mulch film through cooperative aggregation or informal trader networks. Price sensitivity dominates purchasing decisions, with quality arbitrage between SABS-compliant South African supply and informal imports.
- Agricultural Companies:Integrated greenhouse operators and export packers in Ethiopia's rose zones and Kenya's French bean corridors. These entities specify five-layer coextrusion films with documented UV stabilizer content and resin origin for EU auction house compliance.
- Research Institutions:Limited volume through agricultural extension services and university trial programs testing biodegradable formulations.
- Distributors:Channel intermediaries facing formalization pressure from Kenya's National Environment Management Authority post-harvest plastic recovery mandates.
Farmers represent the largest user base by transaction count. Agricultural Companies are gaining share fastest on procurement authority concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across African agricultural film markets. Ethiopian rose exporters absorb premium pricing for optical-grade greenhouse films, while Kenyan smallholders in the Rift Valley drive hard bargains on mulch film through cooperative aggregation. South African dairy cooperatives occupy a middle tier, balancing silage film performance requirements against feedlot margin pressures.
South Africa
KwaZulu-Natal and Eastern Cape dairy clusters anchor regional silage film consumption through mechanized forage preservation systems. The National Regulator for Compulsory Specifications enforces SABS photodegradation standards that quality-screen imports at Durban port. Gauteng-based manufacturing scale dominates domestic supply, though converters remain exposed to dollar-denominated virgin resin freight costs.
Kenya
Highland vegetable corridors serving European bean and pea export contracts pull premium greenhouse film specifications. The National Environment Management Authority implements extended producer responsibility frameworks that mandate post-harvest plastic recovery from farm gate to converter gate. Rift Valley tomato belts face steepest compliance cost adjustments as informal collection networks formalize.
Ethiopia
Flower export zones in the Central Highlands specify five-layer coextrusion films with documented UV stabilizer content for EU auction house compliance. The Ethiopian Horticulture Development Agency coordinates greenhouse certification aligned with EU Green Deal deforestation-free supply chain due diligence. Addis Ababa distribution channels concentrate procurement authority with integrated converters who control resin sourcing.
Morocco
Atlas Mountain vegetable zones and coastal greenhouse belts generate specialized demand for thermal retention films with anti-drip additive packages. The country's national environmental regulator enforces plastic waste management rules for agricultural inputs that tighten compliance timelines for imported film. Casablanca-Rabat corridor converters serve export-oriented tomato and berry packers with five-layer coextrusion capabilities.
Rwanda
Accelerated biodegradable mandate timelines create first-mover pricing premiums for compostable mulch film suppliers serving open-field vegetable cooperatives. The national environment management authority restricts conventional polyethylene burial faster than regional peers, forcing substitution toward starch-based formulations. Kigali-based distribution networks integrate reverse logistics capabilities to maintain licensed horticultural export zone access.
Africa Agricultural Film Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across African agricultural film supply chains. Integrated resin producers leverage backward integration into polyethylene manufacturing to sustain margin structures, while regional converters compete on localized distribution reach and regulatory compliance capabilities. Three archetypes dominate: multinational integrated players with captive resin supply, regional manufacturing specialists with Gauteng or Casablanca-based scale, and niche technology providers focused on biodegradable formulations or five-layer coextrusion precision. Competitive moves concentrate on geographic expansion into East African highland corridors and portfolio diversification toward compostable alternatives as Kenyan and Rwandan regulators tighten burial restrictions.
Among multinational integrated players, Berry Global, Inc. represents the archetype of resin-backed margin sustainability across North African distribution networks. Regional manufacturing specialists include Gundle Plastics Group (PTY) Ltd, which exemplifies Gauteng-based scale concentration in South African silage film supply. Armando Alvarez S.A. occupies a position among specialized coextrusion technology providers serving Moroccan greenhouse export corridors with precision-formulated optical clarity films.
| Leading Market Players |
|---|
| Berry Global, Inc. |
| Armando Alvarez S.A. |
| Ginegar Plastic Products Ltd. |
| BASF SE |
| Mondi PLC |
| Trioworld |
| Gundle Plastics Group (PTY) Ltd |
| INDEVCO Group |
| RKW SE |
| Others |
Value Chain & Pricing Dynamics
Ninety-day polyethylene pellet inventory cycles at Mombasa and Durban ports compress margin buffers for regional converters while amplifying pricing power for integrated resin producers with captive supply. This lead-time exposure concentrates procurement authority among distributors who can pre-position stock ahead of currency devaluation cycles.
Pricing Analysis
After-sales revenue from technical support contracts and additive formulation customization drives lifetime value for five-layer coextrusion equipment suppliers. Three-tier pricing structure across premium, standard, and economy levels separates SABS-compliant South African supply from informal imports and certified EU-traceable greenhouse grades. Price differentiation rests on UV stabilizer documentation and anti-drip additive precision. Cost compression in the standard tier intensifies because Kenyan extended producer responsibility compliance raises operational overhead. Smallholder cooperatives in Kenya's Rift Valley exhibit highest price sensitivity; Ethiopian rose exporters show lowest.
Supply Chain Analysis
Container availability constraints on Asia-South Africa trade lanes amplify inbound logistics costs for virgin resin shipments. Geographic supply concentrates in Saudi Arabia, South Korea, and Singapore for polyethylene pellet feedstock. Raw material dependencies draw from ethylene monomer, UV stabilizer masterbatch, and anti-drip additive formulations. Single-source vulnerability runs through narrow five-layer coextrusion technician pools concentrated in Morocco and South Africa. Distribution runs through certified distributor agreements for greenhouse film and informal trader networks for mulch film.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized blown film line operators capable of five-layer coextrusion precision represent the scarcest capability layer, constraining expansion timelines for East African greenfield projects and compressing margins for operators without in-house technician development programs.
For Market Incumbents: Compound market position through backward integration into polyethylene resin production and captive UV stabilizer formulation capabilities. Defend against biodegradable polymer substitution by accelerating compostable certification timelines ahead of Rwandan regulatory tightening. Prioritize capacity addition in Ethiopia's Central Highlands to capture EU Green Deal traceability premiums. For New Entrants and Emerging Players: Differentiate on biodegradable polymer formulations certified for compostable burial under Kenyan and Rwandan mandates. White-space targets include Rwanda's open-field vegetable cooperatives facing accelerated polyethylene burial restrictions and Nigeria's underpenetrated northern tomato belts. Go-to-market through cooperative aggregation channels with reverse logistics integration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underexploited agricultural film divisions lacking East African distribution presence. Long-term viability hinges on regulatory compliance infrastructure rather than commodity resin access. Acquisition target archetype: regional converters with established five-layer coextrusion lines and certified greenhouse film supply relationships. Signal to watch: Kenyan National Environment Management Authority enforcement intensity against informal collection networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Berry Global's captive polyethylene supply insulates margin structures from freight volatility. |
| Biodegradable Certification Acceleration | Compostable mulch formulations capture Rwandan regulatory substitution premiums ahead of peers. |
| Five-Layer Coextrusion Capacity Expansion | Specialized optical clarity films command auction-grade pricing in Ethiopian rose export zones. |
| Reverse Logistics Network Integration | Kenya's extended producer responsibility mandates require farm-gate-to-converter-gate collection capabilities. |
| UV Stabilizer Formulation Customization | High-altitude East African specifications differ from coastal North African additive packages. |
Study Parameters
A spread of perspectives from greenhouse operations managers, polymer procurement leads at regional converters, Kenyan cooperative aggregation officers, and Ethiopian horticulture export certification specialists converged on the working assumptions. Primary interview insights combined with secondary validation from customs and trade data, SABS and NEMA regulatory filings, and SEC disclosures from listed packaging conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, material grade, application segment, and end-user category dimensions.
Segmentation dimensions modeled include film thickness tier, additive formulation complexity, certification level, regional regulatory cluster, and export market orientation. CAGRs were derived from trend extrapolation of polyethylene resin localization patterns and biodegradable mandate enforcement trajectories. Industry-specific forecast inputs incorporated EU Green Deal deforestation-free supply chain due diligence implementation timelines and Kenyan extended producer responsibility compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained polyethylene resin import dependency and stable EU horticultural export demand would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and currency fluctuation patterns. Practitioners should keep alternative scenarios live as Rwandan biodegradable mandate acceleration and carbon border adjustment mechanism scope expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Coco Coir Market