
 Silo Bags Market | 2026-2036
Silo Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Silo Bags Market Outlook
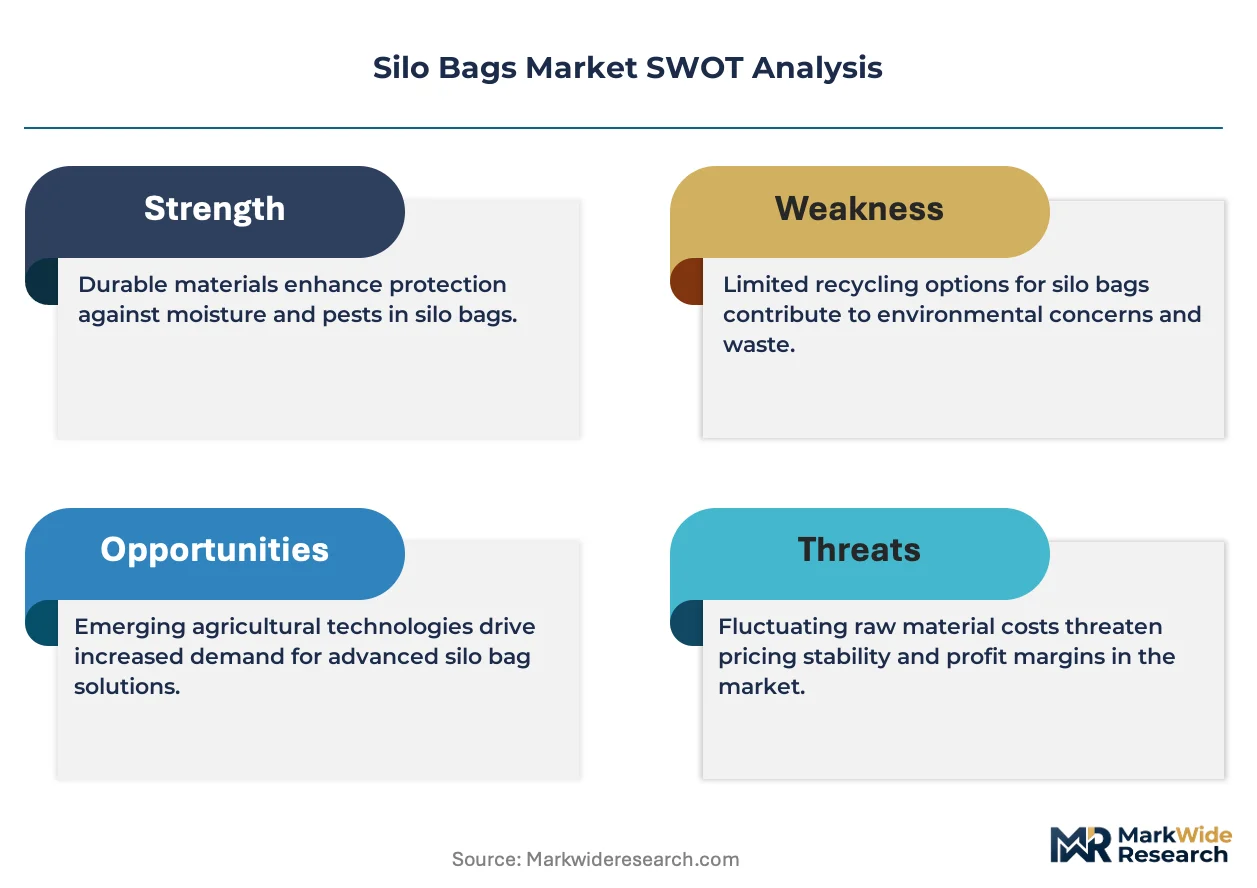
Polypropylene is repositioning traditional polyethylene formulations in silo bag construction by offering superior puncture resistance at equivalent film gauges. Berry Global leverages captive resin compounding to control input costs across North American grain corridors. RKW Group anchors European supply through dedicated blown-film lines calibrated to EFSA migration limits. IPESA Silo dominates Latin American deployment with localized manufacturing in Argentina's Santa Fe province.
Silo bags are cylindrical, hermetically sealable storage vessels manufactured from multi-layer coextruded polyethylene or polypropylene films, typically 230-280 microns thick, designed for anaerobic preservation of bulk agricultural commodities. Low-density polyethylene remains the baseline material for oxygen barrier applications, while composite laminates command premium positioning where extended storage exceeds twelve months. Agriculture absorbs the dominant volume share, yet biomass applications are expanding fastest as anaerobic digestion facilities scale across European biogas networks. Direct sales channels capture institutional procurement from cooperatives, though distributor networks penetrate fragmented smallholder markets where technical installation support determines adoption.
FDA migration thresholds govern polyethylene contact with food-grade grain in the United States, while ECHA REACH restricts phthalate plasticizer content in European-manufactured films. Brazil's ANVISA alignment with Mercosur technical standards streamlines cross-border supply from Argentine producers. India's BIS certification requirements for plastic grain storage create compliance friction for imported products. Stakeholders must monitor regulatory divergence between regional polymer standards and emerging biodegradability mandates that could disrupt incumbent material specifications.
Market Dynamics
Polypropylene film technology is displacing incumbent polyethylene formulations across grain storage applications, forcing resin suppliers and converters to recalibrate compounding lines and barrier specifications simultaneously.
Growth Catalysts
- Argentina's on-farm storage expansion:Farmers in Buenos Aires and Santa Fe provinces are installing permanent silo bag infrastructure to bypass congested elevator networks and capture post-harvest price premiums.
- REACH additive restrictions:ECHA compliance mandates for phthalate-free plasticizers are accelerating migration-compliant film development, creating first-mover advantages for certified European manufacturers.
- Biogas feedstock demand:Anaerobic digestion facilities across Germany and Denmark are sourcing ensiled biomass in silo bags, opening non-agricultural volume channels.
Market Restraints
- Polyethylene resin concentration:Gulf Coast petrochemical complexes supply the majority of LDPE feedstock, exposing converters to hurricane-related supply disruptions and price spikes.
- BIS certification friction:India's mandatory Bureau of Indian Standards testing for plastic grain storage creates 6-12 month product approval timelines that deter rapid market entry.
- Mechanical aeration substitution:Permanent steel silos with active ventilation systems compete for capital expenditure allocations among large-scale cooperative buyers.
Strategic Opportunities
- Ukrainian infrastructure reconstruction:War-damaged grain handling facilities present greenfield demand for mobile storage solutions as Black Sea export corridors stabilize.
- UV-stabilized biodegradable films:Convergence of oxo-degradable additives with conventional coextrusion lines addresses emerging French and Italian single-use plastic restrictions.
- Direct-to-farm e-commerce channels:Agricultural input platforms in Brazil's Mato Grosso are bundling silo bags with seed and fertilizer procurement, compressing traditional distributor margins.
Industry Challenges
- Installation technician scarcity:Proper hermetic sealing requires trained crews, and labor pools in remote grain belts lack standardized certification programs.
- Multi-layer extrusion capex intensity:Seven-layer blown film lines capable of oxygen barrier specifications require capital commitments that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silo Bags Market |
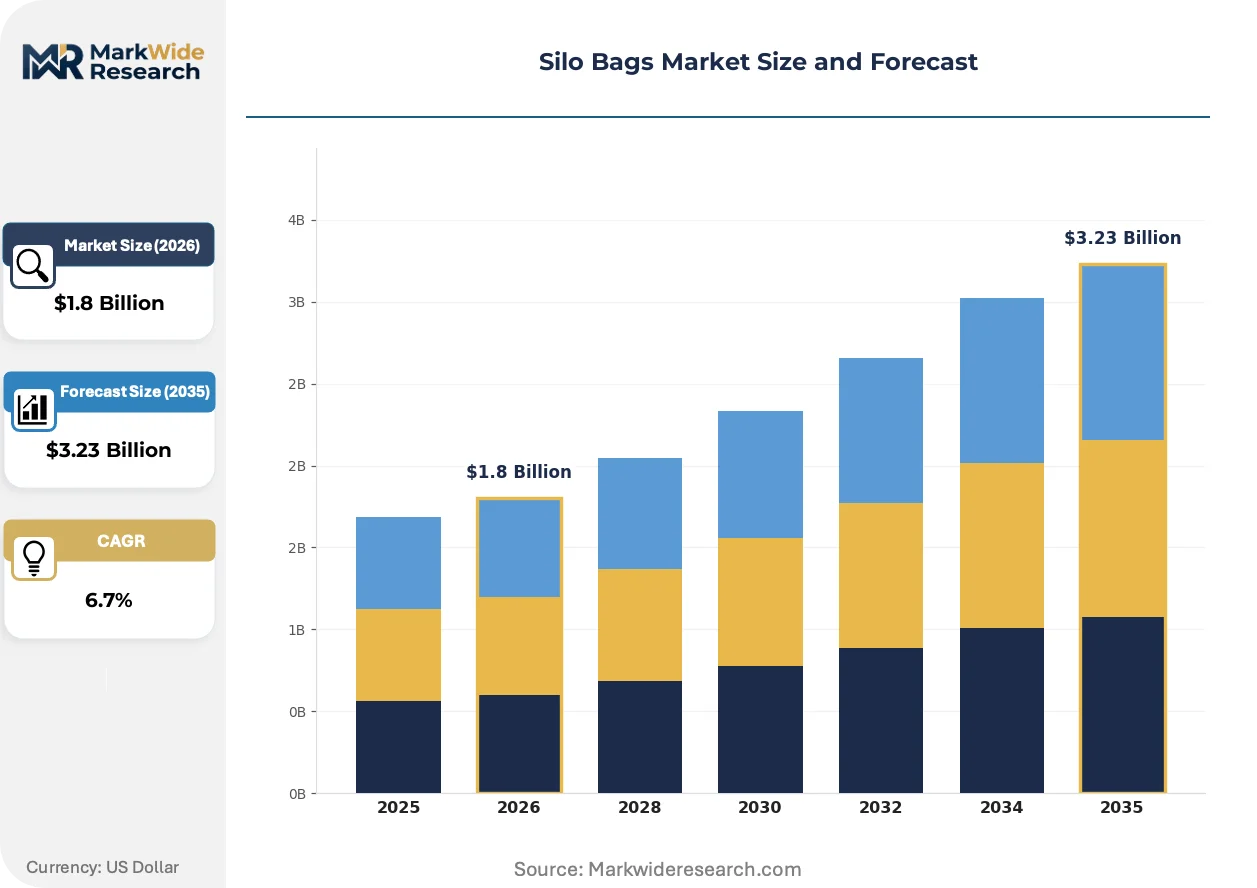
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Density Polyethylene, High-Density Polyethylene, Polypropylene, Composite Materials End Use Industry: Agriculture, Food Processing, Biomass, Livestock Feed Capacity: 50 kg, 100 kg, 250 kg, 500 kg Distribution Channel: Direct Sales, Retail Sales, Online Sales, Distributors |
| Companies Covered | Berry Global, RKW Group, IPESA Silo, Apiesse S.r.l., Böck Silosysteme GmbH, GrainPro, Plastar, Euro Bagging, GreenPro Ventures Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silo Bags Market Strategic Shifts
Material science breakthroughs and regulatory fragmentation are simultaneously expanding performance boundaries and compliance complexity across silo bag manufacturing.
Multi-layer coextrusion is converging with nanoclay barrier technologies to extend grain preservation windows beyond eighteen months. Large-scale farming cooperatives in Brazil and Argentina are specifying these advanced laminates for soybean and corn storage. The technology is converging with traditional polyethylene formulations, compressing the premium gap between standard and extended-duration storage solutions.
ECHA REACH restrictions on phthalate plasticizers are forcing reformulation of polyethylene film additives across European manufacturing. Compounders must validate migration limits under EFSA food contact protocols before commercial deployment. Smallholder-oriented distributors in Poland and Romania are delaying new product introductions until certification costs amortize across sufficient volume.
Cooperative procurement consortia are consolidating smallholder demand into volume tenders that bypass traditional agricultural supply houses. This purchasing concentration is compressing distributor margins and favoring manufacturers with direct technical service capabilities. The pattern is most visible across Argentina's Santa Fe and Córdoba grain belts where producer associations negotiate collective storage infrastructure investments.
Silo Bags Market Segmentation
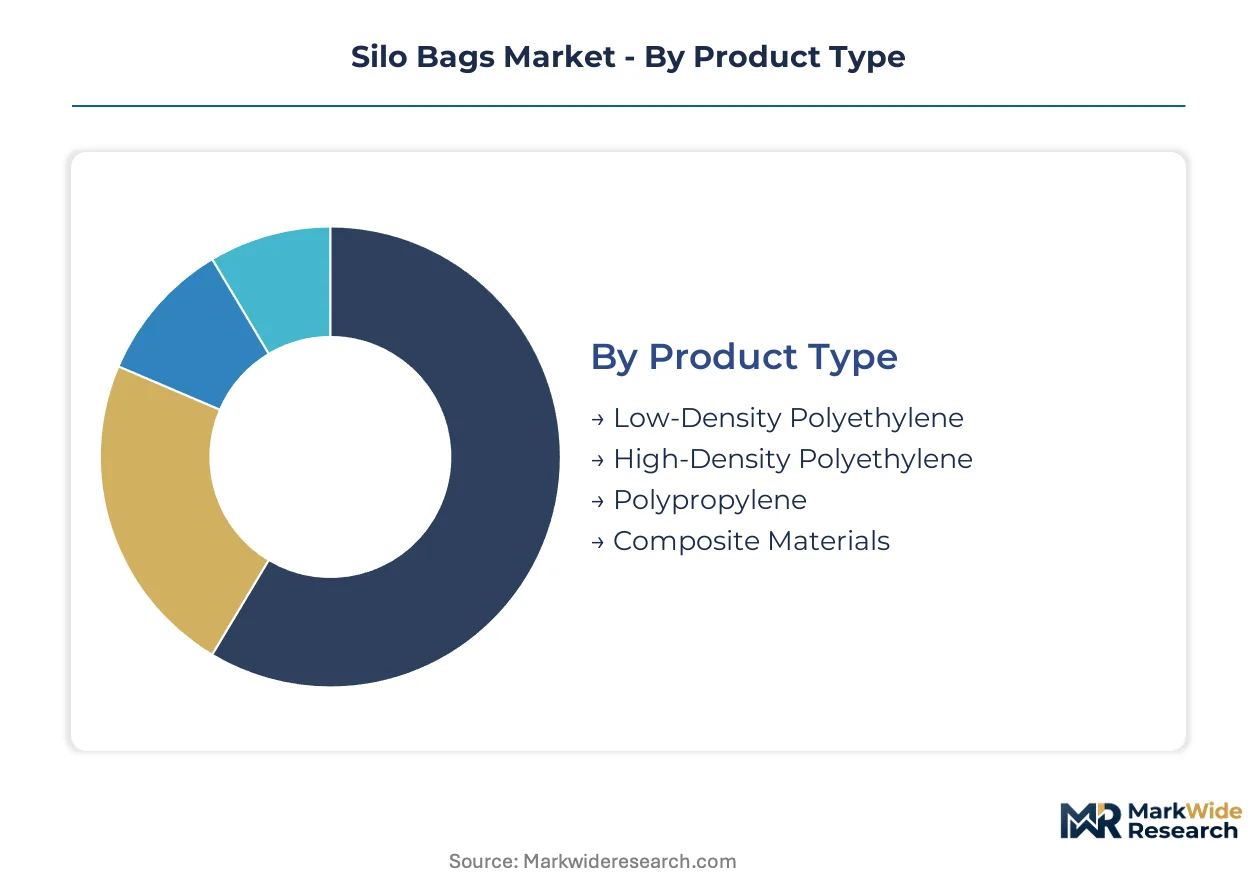
Material specification and end-use application define procurement patterns across silo bag markets. Buyers select formulations based on storage duration, commodity type, and regulatory compliance requirements in target deployment regions.
Product Type:
Polypropylene formulations are displacing legacy polyethylene specifications as farmers and cooperatives upgrade storage infrastructure for extended-duration grain preservation.
- Polypropylene:Superior puncture resistance at equivalent film gauges enables thinner-wall construction without compromising hermetic integrity. Argentine soybean producers in Santa Fe province specify polypropylene for on-farm storage exceeding twelve months, bypassing congested elevator networks during harvest price troughs.
- Low-Density Polyethylene:Baseline oxygen barrier performance maintains cost-positioned volume across standard-duration grain storage applications. Brazilian corn handlers in Mato Grosso deploy LDPE formulations for six-month storage cycles where capital constraints limit material upgrade investment.
- High-Density Polyethylene:Stiffer film characteristics suit automated filling equipment in large-scale cooperative operations.
- Composite Materials:Multi-layer laminates with nanoclay barriers command premium positioning for eighteen-month preservation windows.
Volume placements concentrate in Low-Density Polyethylene; the faster expansion belongs to Polypropylene.
End Use Industry:
Application-specific durability requirements create distinct specification tiers across commodity handling workflows.
- Agriculture:Dominant volume channel encompassing grain, oilseed, and pulse storage across temperate and subtropical production belts. Argentine wheat and corn producers deploy silo bags as permanent infrastructure, while Brazilian operators treat them as seasonal overflow capacity during record harvests.
- Biomass:Anaerobic digestion feedstock preservation represents the steepest expansion trajectory. German and Danish biogas facilities source ensiled agricultural residues in UV-stabilized bags, creating non-food volume channels with distinct EFSA migration compliance requirements.
- Food Processing:Intermediate storage for milled products and ingredient stocks prior to packaging line integration.
- Livestock Feed:On-farm ensiling of forage crops and compound feed storage in remote pasture operations.
Procurement scale favors Agriculture; margin expansion is concentrating in Biomass.
Capacity:
Equipment compatibility and labor availability constrain optimal bag sizing decisions across farm scales.
- 250 kg:Standard specification for mechanized handling in cooperative procurement networks. Argentine producer associations in Córdoba specify this capacity for collective tendering that aggregates smallholder demand into volume contracts.
- 500 kg:Large-scale operations with dedicated filling equipment and trained installation crews. Brazilian grain traders in Mato Grosso deploy 500 kg units for commercial soybean storage where permanent steel silo construction lags production growth.
- 50 kg:Manual handling applications in remote smallholder contexts with limited mechanization.
- 100 kg:Intermediate specification for semi-mechanized operations upgrading from manual systems.
Contracting activity clusters at 250 kg; the steepest demand climb is at 500 kg.
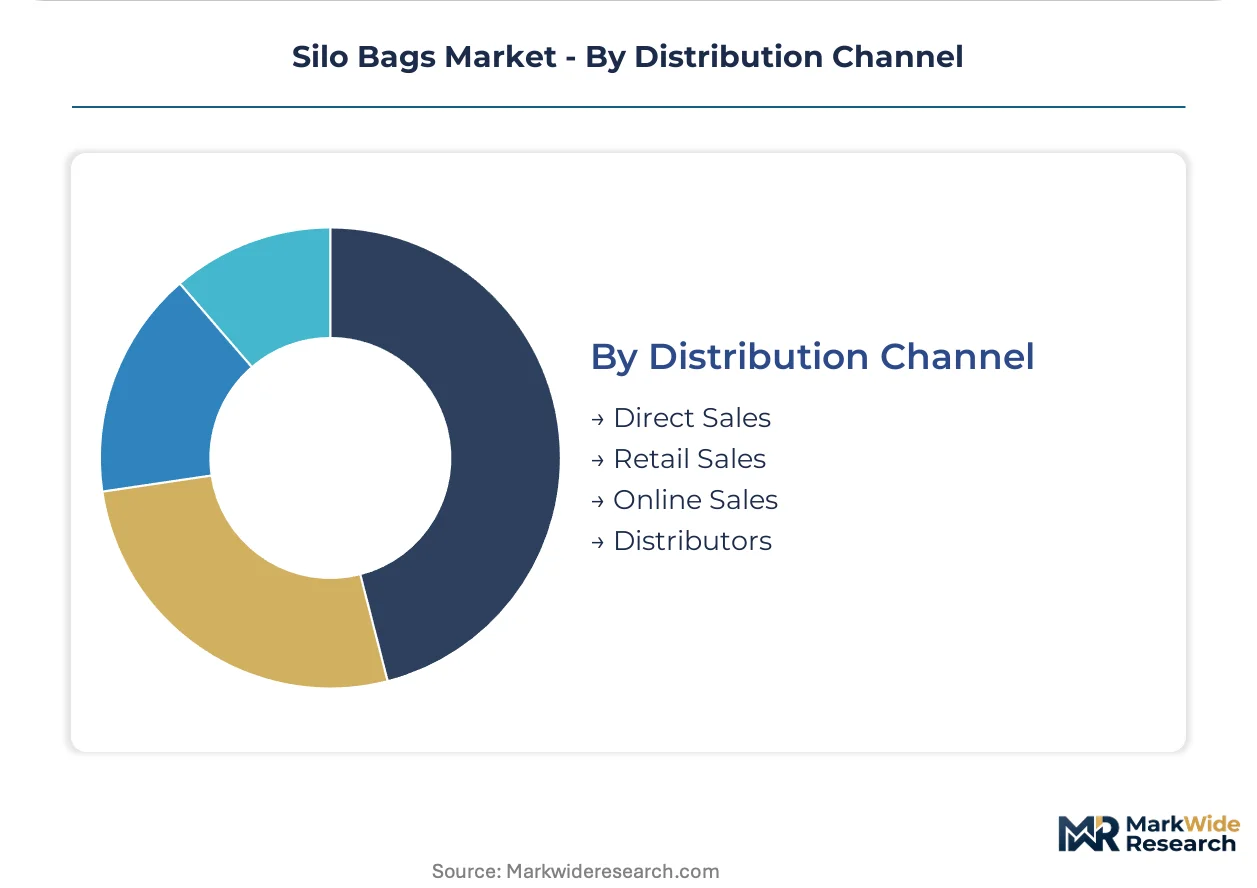
Distribution Channel:
Technical service requirements and buyer scale determine channel selection across fragmented agricultural supply chains.
- Direct Sales:Institutional procurement from cooperatives and large farming enterprises with dedicated agronomy staff. Berry Global and RKW Group maintain direct technical service teams for oxygen barrier specification validation at customer sites.
- Distributors:Fragmented smallholder penetration depends on localized installation support and credit terms. Polish and Romanian agricultural supply houses delay new product introductions until ECHA REACH certification costs amortize across sufficient regional volume.
- Retail Sales:Counter-stock availability for emergency replacement and small-volume farm supply.
- Online Sales:Emerging bundling with seed and fertilizer procurement through agricultural input platforms in Brazil's Mato Grosso.
Revenue concentration sits with Direct Sales; channel expansion is fastest through Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt drives regional concentration through tax incentives for on-farm storage infrastructure. Argentine producers in Santa Fe province bypass congested elevator networks using permanent silo bag installations.
Argentina
Farmers in Buenos Aires and Santa Fe provinces are expanding permanent on-farm storage to capture post-harvest price premiums and reduce losses. ANVISA alignment with Mercosur technical standards streamlines cross-border supply chains. The Santa Fe industrial corridor hosts localized manufacturing operations serving domestic and Brazilian export demand.
Brazil
Soybean and corn handlers in Mato Grosso deploy silo bags as seasonal overflow capacity where permanent steel silo construction lags production growth. ANVISA regulations govern plastic contact with food-grade grain under Mercosur harmonization. Agricultural input platforms in Mato Grosso are bundling silo bags with seed and fertilizer procurement through direct-to-farm e-commerce channels.
Germany
Anaerobic digestion facilities across northern Germany source ensiled biomass in UV-stabilized silo bags, creating non-agricultural volume channels. ECHA REACH restrictions on phthalate plasticizers mandate migration-compliant film development under EFSA protocols. The Lower Saxony biogas network concentrates demand for extended-duration preservation solutions.
United States
Grain cooperatives across the Corn Belt specify oxygen barrier films for extended storage cycles. FDA migration thresholds govern polyethylene contact with food-grade grain under federal food safety protocols. Gulf Coast petrochemical complexes supply LDPE feedstock, exposing converters to hurricane-related supply disruptions.
India
Bureau of Indian Standards certification requirements for plastic grain storage create compliance friction for imported products. BIS testing mandates generate six-to-twelve month product approval timelines that deter rapid market entry. The Punjab-Haryana wheat belt represents latent demand as smallholders upgrade from traditional storage methods.
Silo Bags Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated resin compounders controlling input costs while regional fabricators compete on installation service density. The vendor base organizes around three archetypes: captive resin producers with blown-film capacity, dedicated agricultural film specialists, and diversified packaging converters leveraging existing extrusion assets. Consolidation pressure concentrates among mid-tier converters lacking seven-layer coextrusion capability. Strategic moves center on backward integration into resin compounding and geographic expansion through distributor acquisition.
Among North American integrated producers, Berry Global exemplifies the captive supply archetype through control of resin formulation and film extrusion. RKW Group anchors European positioning with dedicated blown-film lines calibrated to EFSA migration limits. IPESA Silo represents the regional specialist model through Argentine manufacturing proximity to Mato Grosso demand.
| Leading Market Players |
|---|
| Berry Global |
| RKW Group |
| IPESA Silo |
| Apiesse S.r.l. |
| Böck Silosysteme GmbH |
| GrainPro |
| Plastar |
| Euro Bagging |
| GreenPro Ventures Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
ECHA REACH phthalate restrictions gate qualified supply for European silo bag procurement, limiting premium-tier pricing access to converters with validated migration-compliant film formulations. This regulatory filter concentrates pricing power among certified manufacturers while forcing non-compliant competitors toward discount positioning or market exit.
Pricing Analysis
Short lead-time premiums dominate Argentine and Brazilian procurement, where harvest-season demand spikes reward immediate availability with margin capture. Three-tier pricing structure across premium nanoclay barrier laminates, standard polypropylene formulations, and economy-grade low-density polyethylene separates extended-duration storage specifications from seasonal overflow applications. Cost compression in economy LDPE tiers is intensifying because Gulf Coast resin supply volatility exposes converters to margin squeeze. Smallholder distributors in Eastern Europe exhibit highest price sensitivity due to delayed ECHA REACH certification cost amortization, while German biogas facilities demonstrate lowest sensitivity given anaerobic digestion feedstock preservation requirements.
Supply Chain Analysis
Polyethylene resin supply rests on Gulf Coast petrochemical complexes, South Korean specialty film producers, and Saudi Arabian feedstock exporters. Raw material dependencies center on low-density polyethylene pellets, polypropylene homopolymer grades, and UV-stabilizer additive packages. Single-source vulnerability concentrates in hurricane-exposed Texas-Louisiana production corridors where weather-related disruptions cascade through converter inventory cycles. Distribution runs through direct technical service teams for cooperative procurement and fragmented agricultural supply houses for smallholder penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seven-layer coextrusion capacity scarcity props pricing across premium barrier specifications, creating durable margin structures for qualified converters. This supply constraint rewards early certification investment and limits price-based competition in extended-duration storage segments.
For Market Incumbents: Cement defensive positioning through captive resin compounding in North American grain corridors and dedicated blown-film line calibration to EFSA migration limits in European manufacturing. Threat of mechanical aeration substitution by permanent steel silos demands channel control reinforcement through direct technical service density. Capacity addition in Argentina's Santa Fe province anchors Latin American supply proximity to Mato Grosso demand expansion. For New Entrants and Emerging Players: Begin with Ukrainian infrastructure reconstruction demand for mobile storage solutions as Black Sea export corridors stabilize, bypassing entrenched cooperative procurement relationships in mature markets. Most penetrable segment sits in Indian smallholder markets where BIS certification friction has deterred rapid incumbent entry. Go-to-market angle should bundle installation technician training with product supply to address standardized certification program gaps. For Investors and Strategic Acquirers: First-mover ECHA REACH certification completion by mid-tier converters is the leading indicator that margin compression in economy tiers will accelerate competitive consolidation. Long-term viability frames around five-to-ten year biogas feedstock demand expansion and anaerobic digestion facility scaling across Northern European networks. Acquisition target archetype: regional fabricators with installation service density lacking seven-layer coextrusion capability. Signal to watch: cooperative procurement consortia volume tender consolidation in Argentina's Córdoba grain belt.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive supply control insulates input cost volatility across North American grain corridors. |
| UV-Stabilized Biodegradable Film Development | Oxo-degradable additive convergence addresses French and Italian single-use plastic restriction enforcement. |
| Direct-to-Farm E-Commerce Channel Launch | Brazilian agricultural input platforms in Mato Grosso compress traditional distributor margins through bundling. |
| Installation Technician Certification Program | Standardized training pools address hermetic sealing labor scarcity in remote grain belts. |
| EFSA Migration Limit Compliance Investment | RKW Group's dedicated blown-film calibration secures European premium positioning under REACH restrictions. |
Study Parameters
Independent corroboration across converter plant managers, cooperative procurement leads, agricultural distribution channel partners, and biogas facility operations directors underwrites the qualitative findings. Primary interviews with resin compounders and blown-film technical directors combined with secondary validation from customs and trade data, ECHA REACH substance registration databases, SEC 10-K filings of integrated packaging producers, and ANVISA Mercosur technical standard harmonization documents. Bottom-up volume aggregation across material specifications and top-down market sizing triangulation ensure cross-verified output integrity.
Rate-of-change decomposition across the projection horizon segments expansion by material type, end-use application, capacity specification, and distribution channel. The analytical framework models polypropylene displacement trajectories, biomass application growth curves, and cooperative procurement consolidation patterns. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points and capacity addition timelines. Industry-specific forecast inputs include EFSA migration limit implementation schedules and BIS certification approval pipeline durations.
Hurricane-related Gulf Coast resin supply disruptions, ECHA REACH additive restriction scope expansion, and Indian BIS certification timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regional polymer standard divergence and emerging biodegradability mandate adoption curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Farming Sacks and Totes Market