
 Animal Feeding Equipment Market | 2026-2036
Animal Feeding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feeding Equipment Market Intelligence
The EU Green Deal's Farm to Fork Strategy is consolidating demand for precision feeding systems that cut methane emissions and nutrient runoff. Big Dutchman leverages its integrated house engineering to dominate turnkey automated feeding lines across European dairy operations. Lely sustains technology leadership in robotic feed pushers and sensor-driven ration optimization. AGCO Corporation anchors North American distribution through its extensive dealer network serving large-scale cattle feedlots.
Animal feeding equipment comprises mechanical and automated systems designed to store, convey, distribute, and monitor feed rations for livestock and aquaculture, typically engineered with stainless steel contact surfaces, variable-speed augers, and programmable logic controllers that manage batch weights within two-percent accuracy. Feeding Systems leads equipment type adoption as dairy farms replace stationary troughs with traveling hopper and pipeline networks that cut labor hours. Precision Feeding technology captures the fastest expansion trajectory as sensor-based intake monitoring and algorithm-driven ration adjustment command premium pricing. Ruminant applications occupy the largest animal type share due to the capital intensity of total mixed ration preparation in commercial dairy and beef operations.
The European Commission's F-Gas Regulation and CE machinery directives shape equipment design standards for motors and refrigeration in feed storage systems, while the EPA's Clean Water Act and OSHA grain handling standards govern US manufacturing and on-farm installation protocols. ISO 22000 feed safety management certifications increasingly gate market access for exporters serving integrated protein companies. Stakeholders must weigh automation capex against labor arbitrage curves and regulatory compliance timelines when sizing feed system investments.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing capital deployment timelines for dairy cooperatives, forcing equipment buyers to prioritize methane-reduction metrics alongside labor savings in automated feeding system procurement.
Growth Catalysts
- EU F-Gas Regulation:Mandatory refrigerant phase-down in feed storage cooling systems is accelerating retrofit demand across Dutch and Danish dairy operations.
- Precision livestock farming:Sensor-based intake monitoring is pulling capital from stationary troughs into algorithm-driven ration systems that cut nutrient runoff.
- German dairy consolidation:Cooperative mergers in Lower Saxony are bundling procurement for turnkey automated feeding lines, concentrating order volume.
Market Restraints
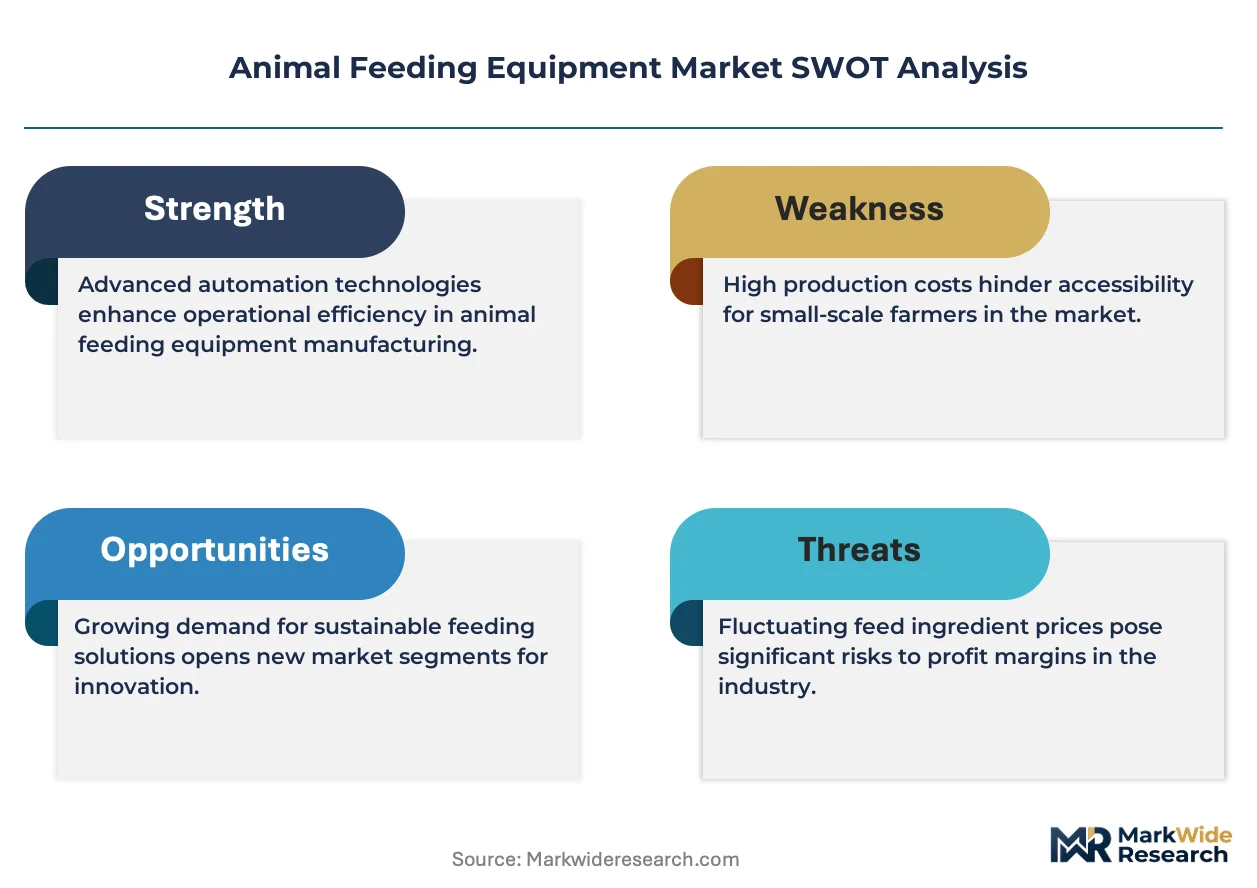
- Stainless steel price volatility:Feed contact surface specifications tie equipment margins to nickel and chromium commodity swings.
- CE machinery directive compliance costs:Variable-speed auger and PLC certification timelines stretch 14-18 months for non-EU manufacturers.
- Manual feeding labor pools:Eastern European seasonal workers remain cost-competitive against automation in sub-200-head dairy operations.
Strategic Opportunities
- Polish dairy modernization:EU cohesion funds are unlocking automated feeding installations in Masovian and Greater Poland voivodeships.
- ISO 22000 certification gates:Integrated protein companies are restricting supplier lists to feed safety management certified equipment vendors.
- Robotic feed pusher + milking robot convergence:Shared sensor infrastructure is creating bundled capex efficiency for technology adopters.
Industry Challenges
- Mechatronics technician scarcity:PLC programming and auger maintenance skill gaps constrain post-installation service capacity in rural equipment dealerships.
- Batch weight calibration complexity:Two-percent accuracy specifications require specialized commissioning that delays farm operational handover.
- Legacy trough integration:Retrofit projects face concrete infrastructure modification costs that erode automation ROI calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feeding Equipment Market |
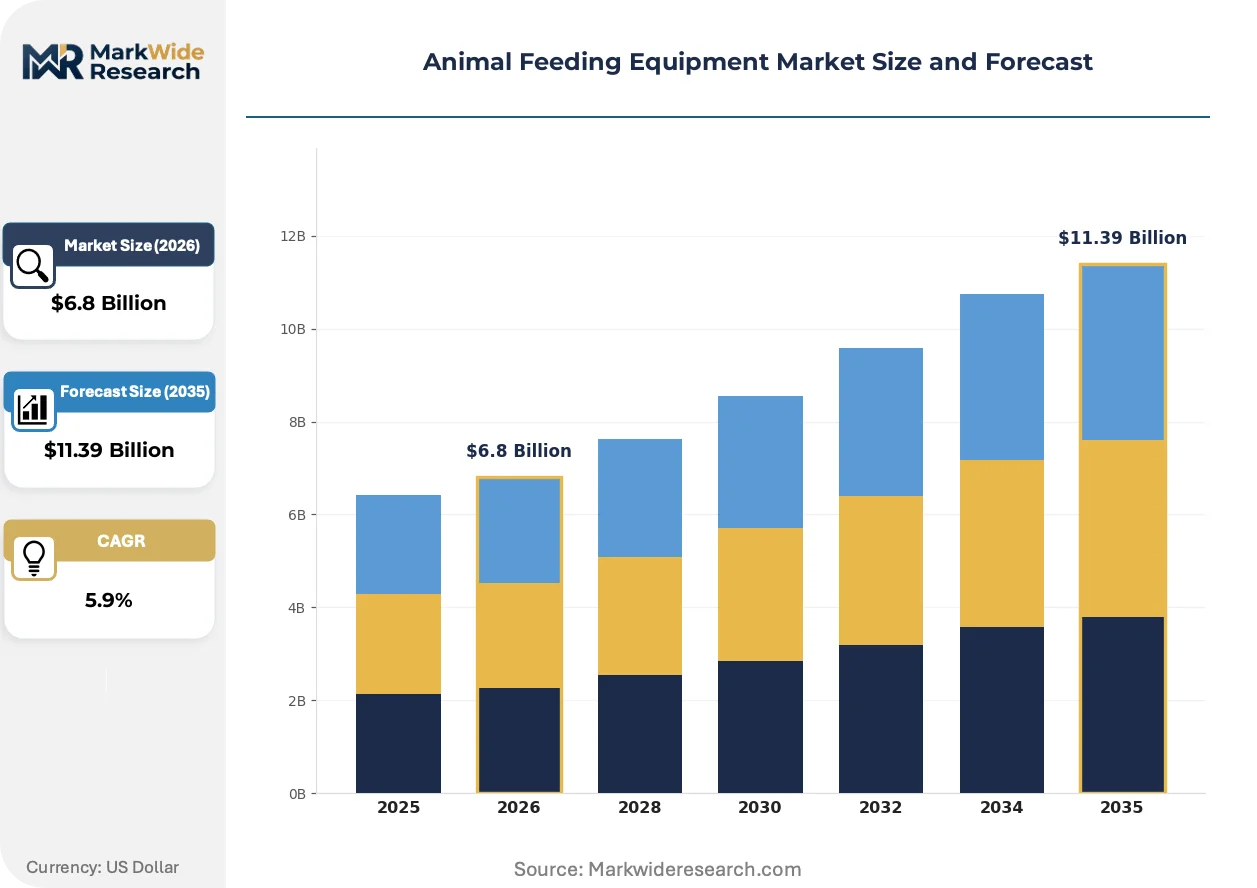
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Feed Mixers, Feeding Systems, Feeders, Feed Conveyors, Waterers Animal Type: Ruminants, Poultry, Swine, Aquatic Species, Equine End User: Livestock Farms, Poultry Farms, Hatcheries, Aquaculture Units, Breeding Facilities Technology: Automatic Feeding, Manual Feeding, Precision Feeding, Sensor-Based Systems, Mechanical Feeding |
| Companies Covered | Big Dutchman, Lely, AGCO Corporation, VDL Agrotech, Trioliet, GEA Group, KUHN S.A., Rovibec Agrisolutions, DeLaval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feeding Equipment Market Strategic Shifts & Innovations
Automation architecture is migrating from standalone feeding units toward integrated house engineering systems that synchronize feed delivery with ventilation, milking, and manure handling.
Computer vision-based feed intake monitoring is automating individual animal ration tracking in commercial dairy barns. Large-scale operations in the Netherlands are deploying camera arrays above feed bunks to replace manual consumption logging. This technology is automating the labor-intensive data collection layer that previously constrained precision nutrition adoption.
The EU Green Deal's Farm to Fork Strategy is mandating feed efficiency transparency across the livestock value chain. Equipment manufacturers must now document energy consumption and methane reduction potential in technical specifications. German and Danish dairy cooperatives are prioritizing vendors with verified environmental performance data in tender evaluations.
Cooperative procurement consortia are consolidating equipment specification power across multi-farm networks. Traditional dealer-direct sales models face displacement from centralized tender processes run by dairy associations. This pattern concentrates most visibly in the Netherlands, where FrieslandCampina-aligned farms are standardizing on interoperable feeding system architectures.
Animal Feeding Equipment Market Segmentation
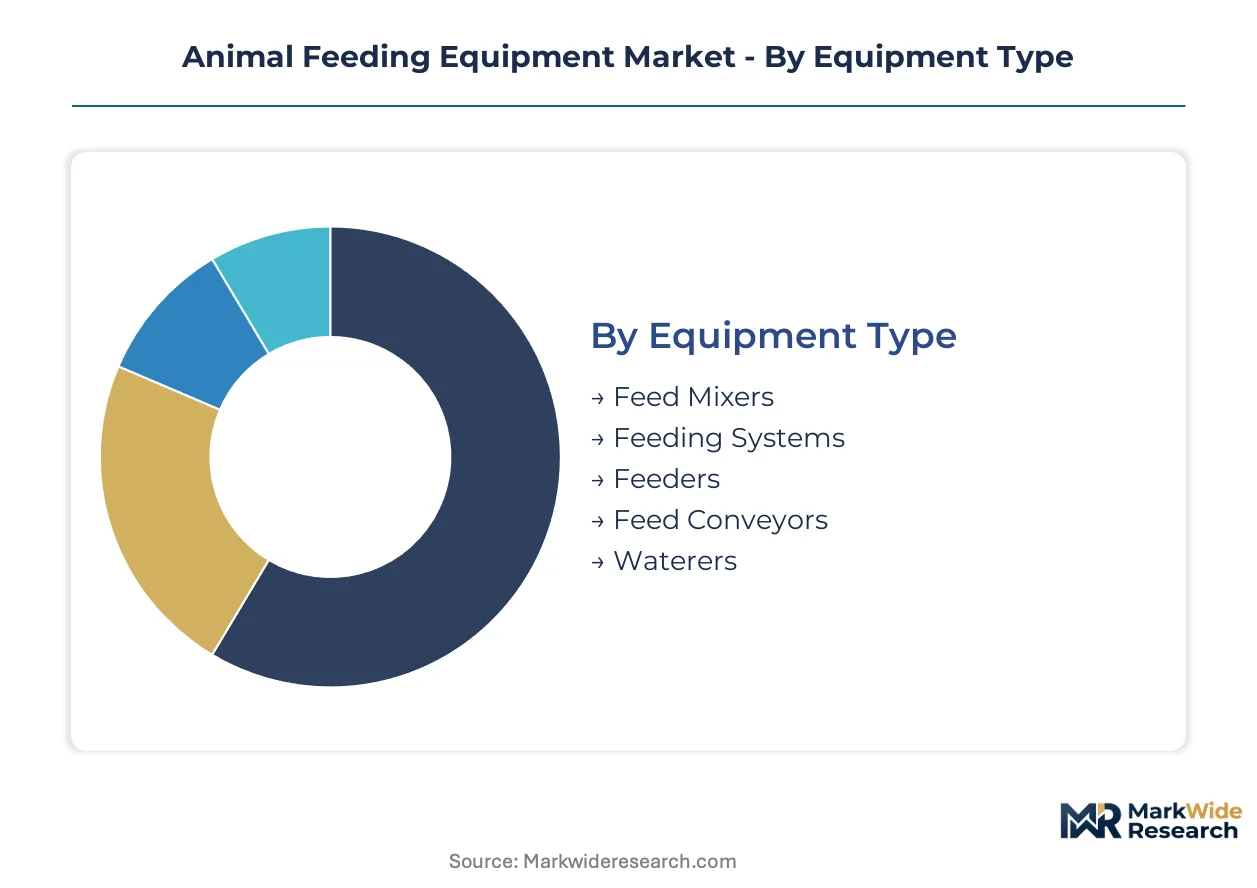
Equipment buyers in dairy, poultry, and aquaculture operations prioritize different automation levels, feed handling capacities, and regulatory compliance features when selecting feeding systems. Segmentation reveals how capital deployment concentrates across mechanized trough networks versus precision sensor arrays, with each category carrying distinct margin structures and service attachment rates.
Equipment Type:
Stainless steel contact surfaces and variable-speed auger specifications differentiate capital intensity across mechanical versus automated feed handling architectures.
- Feed Mixers:Stationary and mobile TMR preparation units with horizontal or vertical auger configurations process fibrous rations for commercial dairy operations. Dutch cooperatives in Friesland and North Brabant are consolidating procurement for high-capacity mixer wagons that cut labor hours in 500-plus head operations.
- Feeding Systems:Integrated traveling hopper and pipeline networks replace stationary troughs with automated delivery schedules programmed through PLCs. German dairy mergers in Lower Saxony are bundling tender specifications for turnkey system installations that synchronize with milking parlor workflows.
- Feeders:Individual stall-mounted dispensers and group feeding stations manage controlled portions across pen configurations. Polish livestock farms in Masovian Voivodeship are deploying gravity-fed and electronically gated units under EU cohesion fund modernization programs.
- Feed Conveyors:Chain, belt, and auger mechanisms transport bulk feed from storage silos to distribution points. Danish pork operations favor enclosed conveyor designs that meet F-Gas Regulation standards for reduced particulate emissions.
- Waterers:Nipple, cup, and trough configurations deliver controlled water access across species-specific consumption patterns. Broiler operations in the Netherlands specify antimicrobial contact surfaces to satisfy EU Green Deal hygiene transparency requirements.
Mature deployment sits with Feed Mixers in established dairy regions. Newer deployment is concentrated in integrated Feeding Systems that bundle feed delivery with environmental controls.
Animal Type:
Digestive physiology and housing density determine equipment scale, with ruminant operations demanding the highest capital allocation per animal unit.
- Ruminants:Cattle, sheep, and goat feeding equipment handles high-fiber total mixed rations through heavy-duty augers and extended retention systems. Commercial dairy barns in Denmark prioritize methane-reduction metrics in automated feeding procurement under Farm to Fork Strategy compliance timelines.
- Poultry:Layer and broiler operations utilize chain feeders, pan systems, and nipple drinkers designed for high-density housing. German poultry farms are retrofitting sensor-based intake monitoring to document feed conversion ratios for integrated protein company contracts.
- Swine:Wet-dry feeders, electronic sow feeding stations, and automated liquid feeding systems manage precision nutrient delivery. Polish pork producers in Greater Poland Voivodeship are expanding automated installations to meet ISO 22000 certification gates set by slaughterhouse buyers.
- Aquatic Species:Pond, cage, and recirculating aquaculture systems demand specialized pellet dispensers with water-quality integration. Dutch aquaculture units are deploying algorithm-driven ration systems that cut nutrient runoff into sensitive watersheds.
- Equine:Slow feeders, hay nets, and automated grain dispensers serve breeding and training facilities with lower throughput requirements. Breeding facilities in Germany favor programmable units that maintain consistent schedules across extended boarding operations.
Volume concentration anchors Ruminant applications. Technology premiums are climbing fastest in Aquatic Species systems where environmental compliance drives sensor integration.
End User:
Operational scale and integration into protein supply chains shape specification requirements across independent farms versus corporate-owned facilities.
- Livestock Farms:Dairy and beef cattle operations deploy the full equipment spectrum from manual troughs to integrated automated lines. Consolidated cooperatives in the Netherlands are standardizing on interoperable architectures that reduce dealer service complexity.
- Poultry Farms:Layer and broiler houses prioritize high-speed feed delivery with minimal labor intervention across 50,000-plus bird complexes. Danish poultry integrators require documented energy consumption data in tender evaluations under EU Green Deal transparency mandates.
- Hatcheries:Specialized chick feeding systems provide controlled nutrient access during critical early development windows. German hatchery operators specify precision dosing equipment to maintain genetic line performance benchmarks.
- Aquaculture Units:Fish and shellfish farms deploy floating, submerged, and land-based feeding systems with remote monitoring capabilities. Coastal operations in the Netherlands are adopting computer vision-based intake tracking to replace manual consumption logging.
- Breeding Facilities:Genetic improvement centers demand individualized ration control and detailed intake records for pedigree validation. Equine breeding operations in Lower Saxony specify programmable dispensers that maintain nutritional consistency across gestation cycles.
Procurement scale concentrates in Poultry Farms. Technology experimentation is expanding most quickly in Aquaculture Units where labor arbitrage curves favor automation earliest.
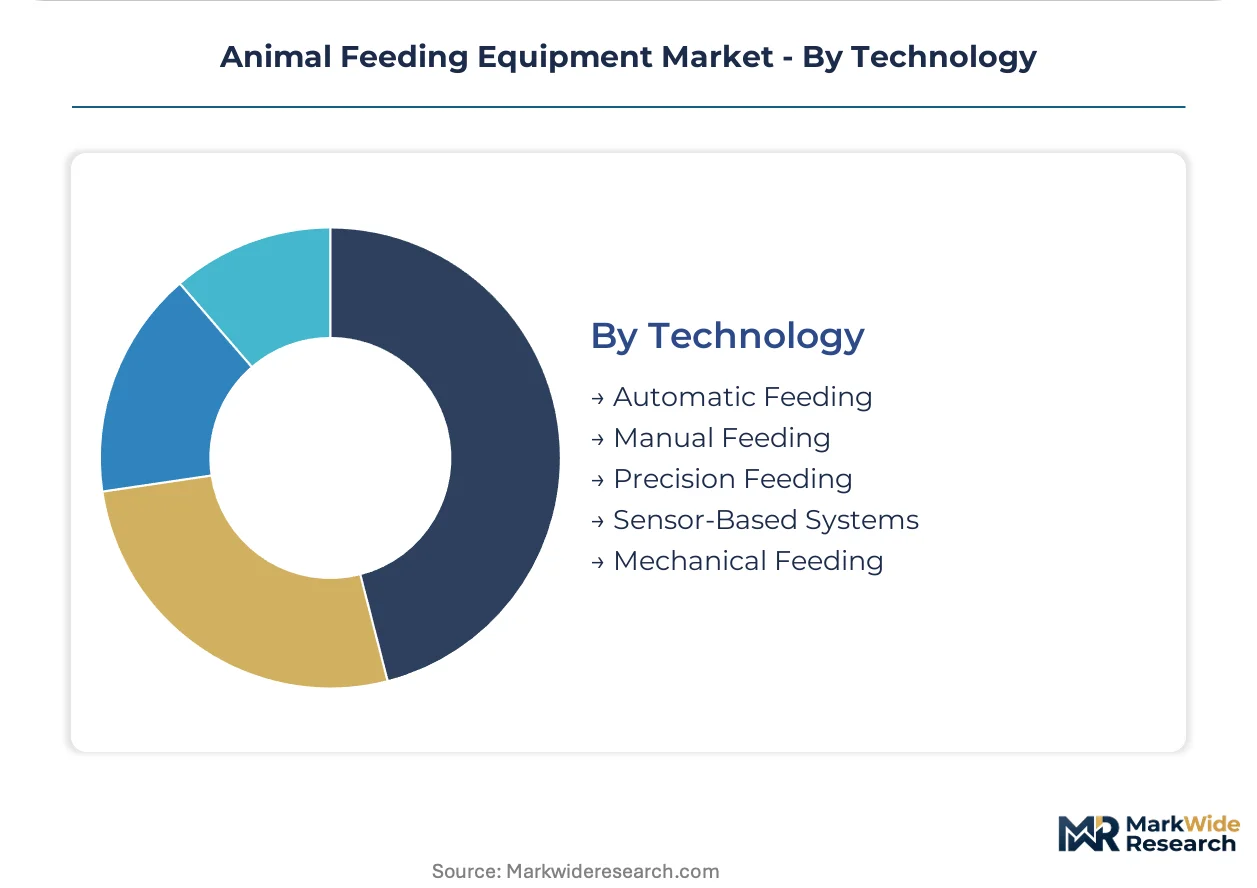
Technology:
Control system sophistication determines pricing tiers, with mechanical systems occupying entry positions and sensor-integrated platforms commanding premium positioning.
- Automatic Feeding:Timer- and weight-triggered dispensers execute pre-programmed delivery schedules without real-time adjustment. German dairy operations are migrating from basic automatic units toward sensor-integrated platforms that respond to actual consumption patterns.
- Manual Feeding:Hand-fed troughs and portable carts persist in sub-200-head operations where Eastern European seasonal labor maintains cost competitiveness. Polish family farms in rural voivodeships continue specifying manual equipment under constrained capital budgets.
- Precision Feeding:Algorithm-driven ration adjustment based on production stage, body condition, and environmental factors optimizes feed conversion. Dutch dairy cooperatives are prioritizing precision platforms that document methane reduction potential for Farm to Fork Strategy compliance.
- Sensor-Based Systems:Intake monitoring arrays, weight platforms, and RFID-linked dispensers track individual animal consumption in real time. Commercial operations in Denmark are deploying camera arrays above feed bunks to automate data collection previously constrained by labor availability.
- Mechanical Feeding:Gravity-fed, chain-driven, and auger-based systems without electronic control provide basic feed distribution. Entry-level pork operations in Poland specify mechanical conveyors under EU cohesion fund programs that prioritize capital efficiency over automation.
Installed base dominance rests with Mechanical Feeding in price-sensitive segments. Steepest expansion trajectory belongs to Sensor-Based Systems where data infrastructure convergence creates bundled efficiency with milking robots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FrieslandCampina's cooperative network in North Brabant drives procurement standardization across Dutch dairy operations, compressing vendor selection timelines for automated feeding installations.
Germany
Cooperative mergers in Lower Saxony are bundling tender specifications for turnkey feeding lines that synchronize with milking parlor workflows. The country's national agricultural regulator enforces CE machinery directive compliance for variable-speed auger and PLC certification. Bavarian equipment fabricators in Nuremberg-Munich corridor are scaling production capacity for precision livestock farming exports.
Netherlands
Dairy cooperatives in Friesland and North Brabant are expanding automated feeding system procurement under methane-reduction procurement mandates. The EU Green Deal's Farm to Fork Strategy tightens feed efficiency standards for livestock equipment tender evaluations. Wageningen University's research cluster is validating sensor-based intake monitoring systems for commercial barn deployment.
Denmark
Commercial dairy barns prioritize methane-reduction metrics in automated feeding procurement under Farm to Fork Strategy compliance timelines. The country's national environmental agency enforces F-Gas Regulation standards for feed storage cooling system retrofits. Aarhus University's precision agriculture hub is field-testing computer vision arrays for automated consumption logging.
Poland
EU cohesion funds are unlocking automated feeding installations in Masovian and Greater Poland voivodeships for dairy and pork modernization. The country's national agricultural development agency administers rural equipment subsidy programs under cohesion policy frameworks. Poznan-based machinery distributors are building service capacity for precision feeding system commissioning.
United States
Large-scale cattle feedlots in Texas Panhandle and Nebraska Sandhills are deploying automated ration preparation systems to cut labor hours. The EPA's Clean Water Act and OSHA grain handling standards govern manufacturing and on-farm installation protocols. California Central Valley dairy operations are retrofitting sensor-based platforms to document environmental compliance for processor contracts.
Animal Feeding Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration depth, with sensor-integrated precision feeding platforms commanding pricing multiples over mechanical conveyors. The vendor base organizes into three strategic archetypes: integrated house engineering specialists, robotic automation pure-plays, and diversified agricultural machinery conglomerates. M&A activity concentrates on sensor technology tuck-ins, while geographic expansion targets Polish and Romanian dairy modernization corridors.
Within the integrated house engineering tier, Big Dutchman and VDL Agrotech exemplify turnkey system providers that bundle feeding lines with ventilation and manure handling infrastructure. Lely occupies a position among robotic automation pure-plays focused on feed pusher-milking robot convergence. AGCO Corporation anchors the diversified machinery conglomerate archetype with extensive North American distribution networks serving large-scale cattle operations.
| Leading Market Players |
|---|
| Big Dutchman |
| Lely |
| AGCO Corporation |
| VDL Agrotech |
| Trioliet |
| GEA Group |
| KUHN S.A. |
| Rovibec Agrisolutions |
| DeLaval |
| Others |
Cost & Logistics Intelligence
Mechatronics technician concentration in Bavaria and Lower Saxony compresses labor-cost differentials between premium precision-feeding platforms and standard automated lines, widening pricing-tier spreads across German dairy cooperative procurement.
Pricing Analysis
Outcome-based pricing anchored to feed-conversion-ratio improvement commands premium positioning for sensor-integrated precision feeding platforms. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified algorithm-driven systems from CE-compliant automatic dispensers and basic mechanical conveyors. Pricing pressure stems from stainless steel commodity volatility eroding fabrication margins. Sub-200-head Polish dairy operations exhibit acute price sensitivity, while consolidated Dutch cooperatives prioritize methane-reduction documentation over unit cost.
Supply Chain Analysis
Workforce-availability constraints in Nuremberg-Munich corridor and Danish fabrication clusters limit production scaling for precision livestock farming components. Manufacturing concentrates in Germany, Denmark, and the Netherlands for PLC-integrated feeding systems. Supply chains draw from nickel and chromium feedstock for stainless steel contact surfaces, variable-speed auger motors, and sensor arrays. Single-source vulnerability sits with specialized PLC programming talent for batch-weight calibration. Distribution runs through cooperative procurement consortia displacing traditional dealer-direct models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: mechatronics technician scarcity props pricing for post-installation service contracts and extends commissioning timelines.
For Market Incumbents: To counter cooperative procurement consortia consolidating tender power, deepen backward integration into sensor manufacturing and secure captive PLC programming capacity in rural equipment dealerships. Prioritize ISO 22000 certification investment to gate integrated protein company supplier lists. For New Entrants and Emerging Players: Begin with Polish dairy modernization corridors under EU cohesion fund programs, where capital efficiency requirements favor mid-tier automated feeding systems over premium precision platforms. Target gravity-fed and electronically gated feeder deployments in Masovian Voivodeship through machinery distributor partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with robotic automation pure-plays given feed pusher-milking robot convergence creating bundled capex efficiency. Long-term viability favors sensor technology specialists with software-defined ration optimization capabilities. Watch Aarhus University and Wageningen University validation timelines for computer vision-based intake monitoring as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of intake monitoring arrays insulates margin from semiconductor supply volatility. |
| ISO 22000 Certification Program | Feed safety management certification gates supplier access to FrieslandCampina-aligned procurement networks. |
| Cooperative Procurement Consortium Partnership | Centralized tender processes in Lower Saxony concentrate order volume for turnkey system providers. |
| Mechatronics Technician Training Pipeline | Rural dealership service capacity expansion addresses post-installation commissioning bottlenecks. |
| Algorithm-Driven Ration Optimization Platform | Software subscription layers monetize methane-reduction documentation for EU Green Deal compliance. |
Research Approach
Independent corroboration across equipment procurement directors at Dutch dairy cooperatives, German machinery fabricators, and Polish agricultural development agency officials underwrites the qualitative findings. Primary fieldwork captured maintenance director perspectives at commercial dairy barns in Denmark, aftermarket service heads at Bavarian equipment dealerships, and OEM procurement teams at precision livestock farming technology providers. Secondary validation drew from EU F-Gas Regulation implementation reports, CE machinery directive compliance databases, and cohesion fund disbursement records. Bottom-up installation data triangulated against top-down protein company capital expenditure disclosures.
Rate-of-change decomposition across the analysis window segments volume trajectories by equipment type, animal physiology, technology sophistication, and regional regulatory cluster. Modeled dimensions span feeding system architecture, end-user scale tier, and environmental compliance intensity. CAGRs derive from equipment replacement cycle analysis and automation penetration curve fitting. Forecast inputs incorporate EU Green Deal Farm to Fork Strategy compliance timelines and labor arbitrage curves for Eastern European seasonal workers.
Stainless steel commodity volatility, mechatronics technician training pipeline failures, and F-Gas Regulation retrofit acceleration are the dominant revision risks. Forecasts reflect assumptions on cooperative merger momentum and precision livestock farming technology validation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Cattle Feeder Panels Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Hog Feeder Market