
 US Agro Textile Market | 2026-2036
US Agro Textile Market Size, Share, and Industry Trends Forecast 2026-2036
US Agro Textile Market Insights
Premium technical fabrics and commodity-grade covers is decoupling on performance specifications and pricing power. TenCate Geosynthetics leverages advanced polymer engineering to dominate erosion-control applications in high-value vineyards. Belton Industries, Inc. anchors its position through manufacturing scale in woven polypropylene for broad-acre row crops. Freudenberg Performance Materials differentiates via nonwoven expertise serving greenhouse operators with climate-responsive covers.
Agro textiles are engineered fabrics—typically woven, nonwoven, or knitted from synthetic polymers like polypropylene or natural fibers such as jute and coir—designed to perform specific agronomic functions including moisture retention, thermal regulation, and mechanical soil stabilization. Shade cloth commands durable margin pools in controlled-environment agriculture across Arizona and Texas, while mulch films face substitution pressure from biodegradable alternatives in organic-certified operations. Geotextiles sustain structural demand from USDA-funded watershed restoration projects, and crop covers expand fastest among berry producers seeking season extension in the Pacific Northwest.
USDA Natural Resources Conservation Service standards, EPA guidelines on agricultural plastics disposal, and ASTM D4751 geotextile testing protocols collectively shape product certification requirements and channel access. State-level plasticulture restrictions in California and New York are accelerating manufacturer investment in compostable material platforms. Stakeholders must monitor how evolving Extended Producer Responsibility frameworks alter cost structures for synthetic product lines.
Market Dynamics
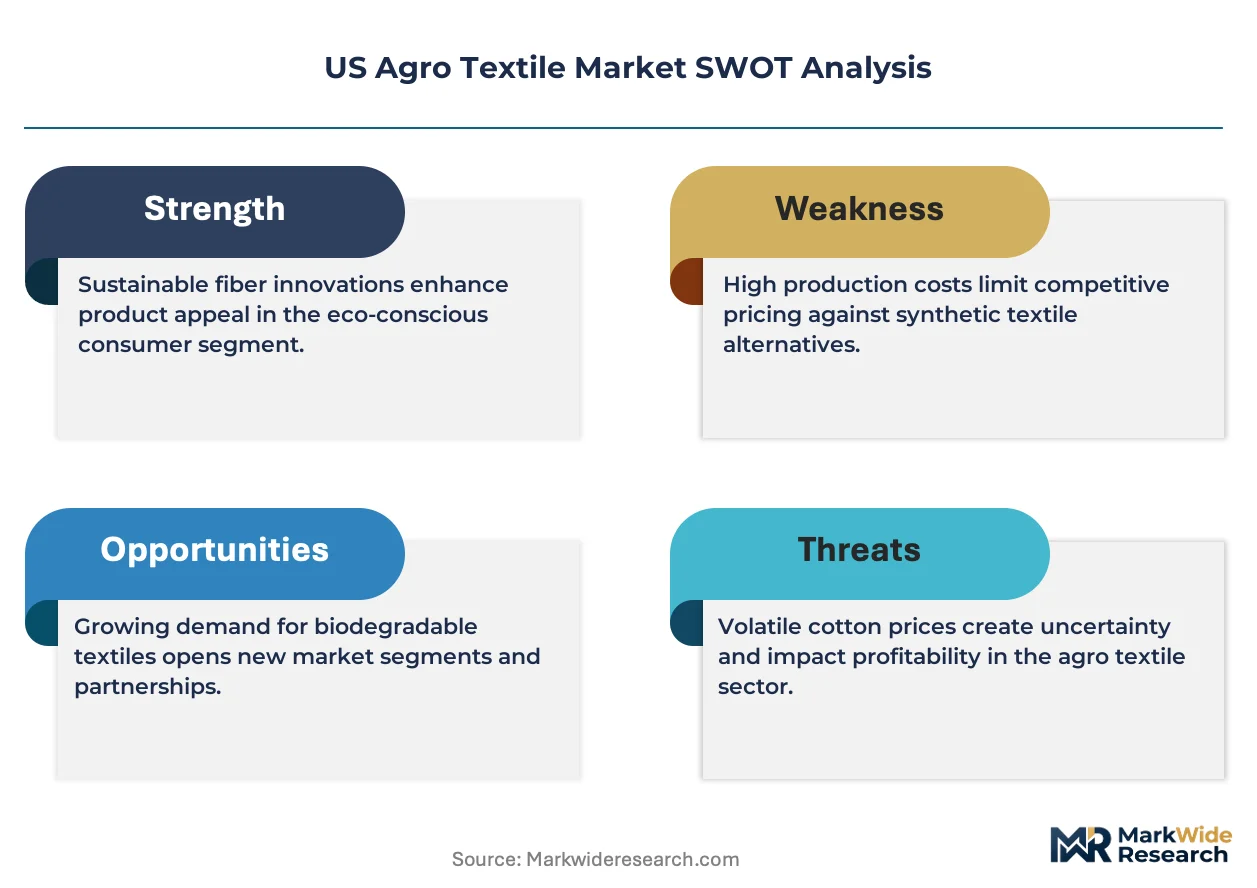
USDA conservation program funding and state-level plastic disposal mandates are forcing manufacturers to reconfigure material platforms around compostable polymers while specialty crop producers demand higher-performance climate-control fabrics.
Growth Catalysts
- USDA NRCS EQIP funding:Cost-share incentives for erosion-control installations on high-value vineyard slopes in California and Washington expand geotextile specification volumes.
- Controlled-environment agriculture expansion:Greenhouse operators across Arizona and Texas deploy advanced shade cloth systems to manage thermal stress and extend production windows.
- Biodegradable polymer breakthroughs:PLA and PBAT formulations meeting ASTM D6400 compostability standards unlock procurement access to organic-certified berry operations in the Pacific Northwest.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices tied to natural gas liquids expose manufacturers to margin compression without pass-through mechanisms.
- Single-supplier concentration for specialty additives:UV stabilizers and anti-fog coatings concentrate among three chemical producers, creating input bottlenecks.
- California SB 54 implementation friction:Extended Producer Responsibility reporting requirements impose compliance overhead on synthetic product lines without immediate biodegradable alternatives.
Strategic Opportunities
- Florida specialty crop underpenetration:Citrus and strawberry producers in the central ridge region show minimal adoption of precision crop covers relative to California benchmarks.
- USDA Climate-Smart Commodities grants:Funding pools for soil health practices create procurement channels for erosion-control geotextiles on corn-soy rotations in the Corn Belt.
- Sensor-fabric convergence:Integration of moisture and temperature monitoring into woven substrates enables subscription-based performance contracts for greenhouse operators.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with biodegradable material expertise command premium compensation and concentrate among coastal research clusters.
- ASTM D4751 certification timelines:Geotextile testing protocols require 12-18 month validation cycles that delay product launches for watershed restoration bids.
- Legacy equipment retooling costs:Conversion from conventional extrusion lines to biopolymer-compatible systems demands capital deployment without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Agro Textile Market |
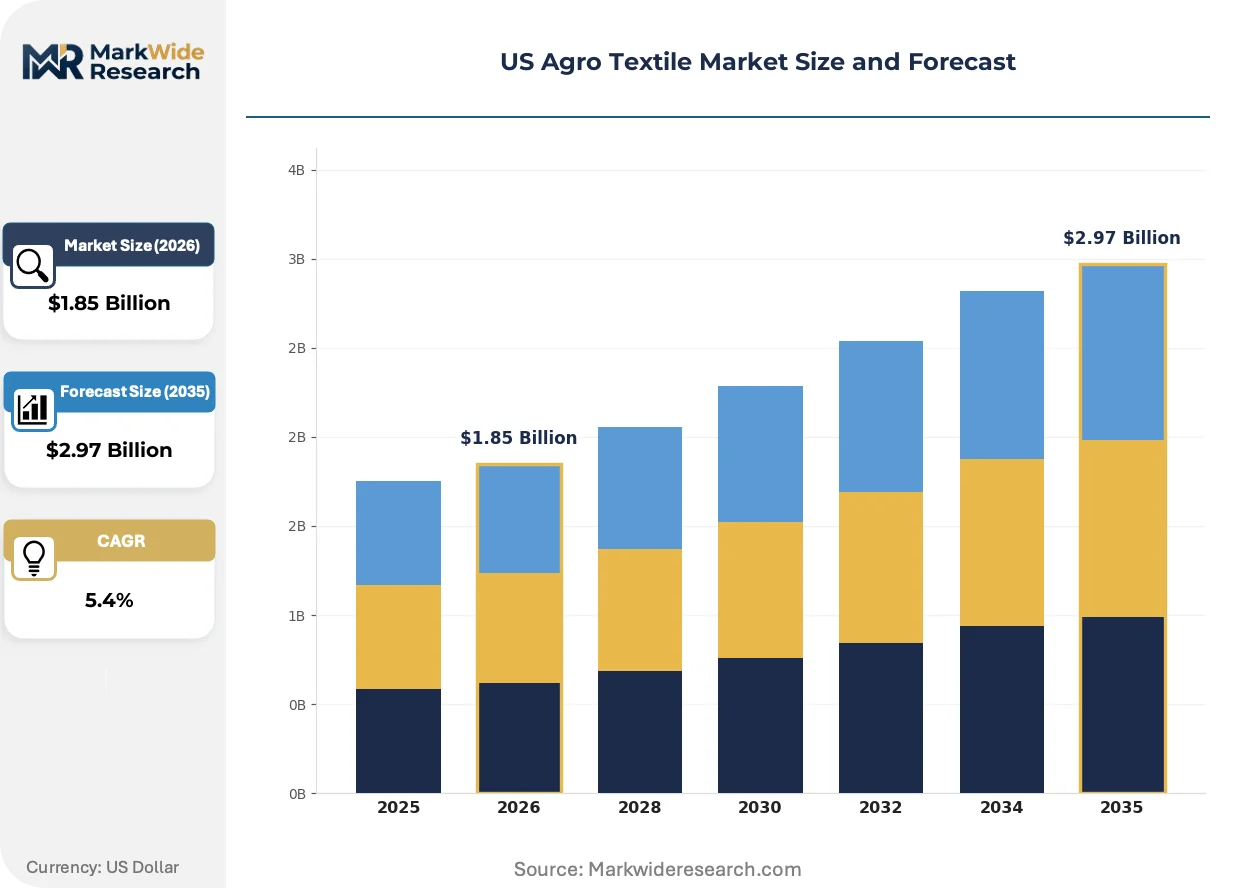
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextiles, Shade Cloth, Crop Covers, Mulch Films Material: Polypropylene, Polyester, Natural Fibers, PVC End User: Agricultural Producers, Greenhouses, Nurseries, Landscapers Application: Erosion Control, Weed Suppression, Soil Stabilization, Crop Protection |
| Companies Covered | TenCate Geosynthetics, Belton Industries, Inc., Mogul Co., Ltd., Dewitt, Freudenberg Performance Materials, Garware Technical Fibers Ltd., Beaulieu Technical Textiles, Ludvig Svensson, Siang May Pte Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Agro Textile Market Trends and Innovations
Material science advances and regulatory pressure on agricultural plastics disposal are converging to reshape product architectures, with manufacturers racing to certify compostable alternatives before state bans on conventional mulch films take effect.
Smart agro textiles incorporating conductive fiber networks and embedded sensors are integrating real-time soil moisture and canopy temperature data into automated irrigation systems. Large greenhouse operators in Texas and Arizona are piloting these fabrics at scale. The technology is integrating climate-control and data-collection functions into single substrate layers, compressing the traditional separation between physical covers and monitoring equipment.
EPA guidelines on agricultural plastics disposal and California's SB 54 Extended Producer Responsibility framework are mandating producer accountability for end-of-life material recovery. Manufacturers face redesign imperatives for disassembly and recycling compatibility. Biodegradable mulch film producers serving organic-certified operations in the Pacific Northwest and New York are accelerating ASTM D6400 certification to secure procurement eligibility.
Specialty crop buyers are consolidating vendor relationships around full-service contracts bundling fabric supply, installation, and seasonal removal. Greenhouse operators in the southeastern United States are displacing transactional purchasing with multi-year performance agreements. This pattern concentrates most visibly among berry producers in Florida and Georgia seeking guaranteed thermal management outcomes across variable spring conditions.
US Agro Textile Market Segmentation
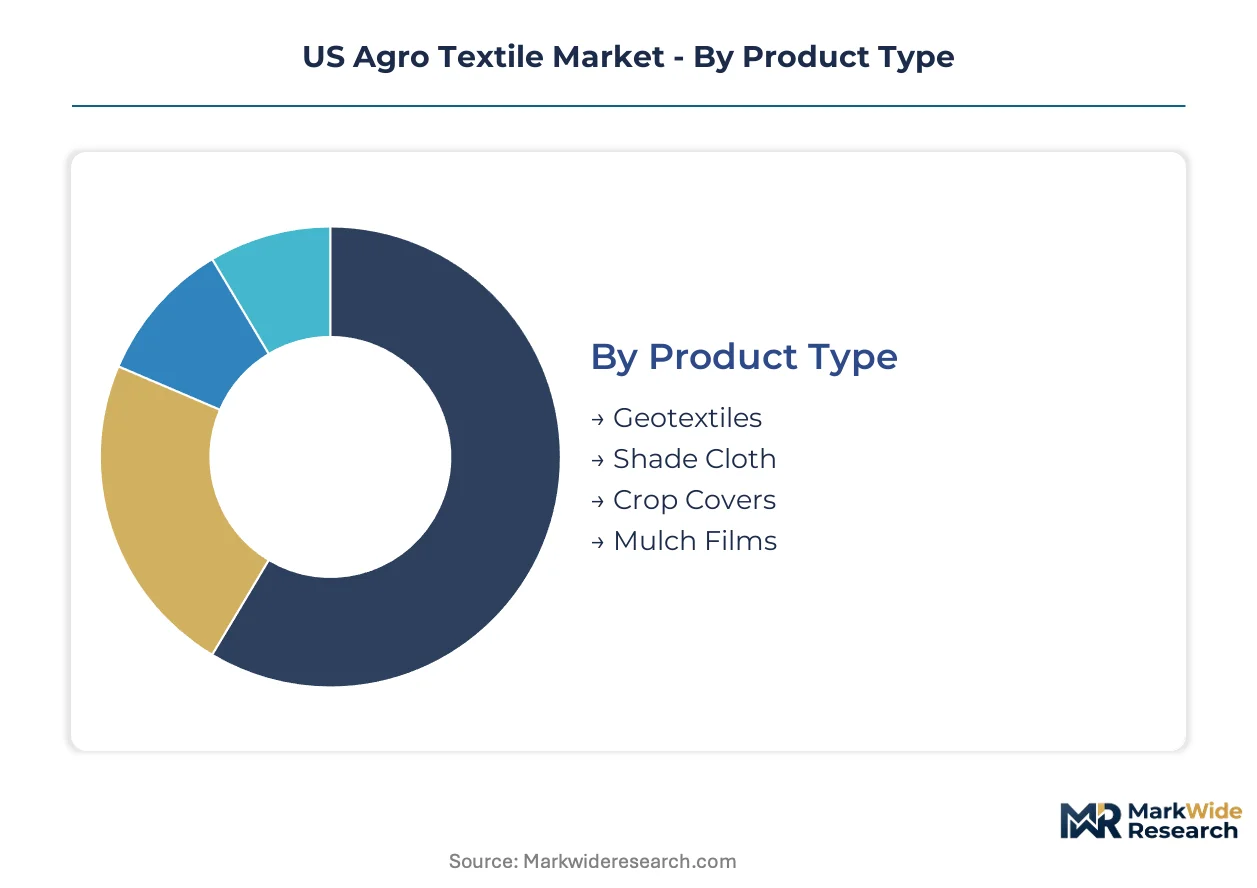
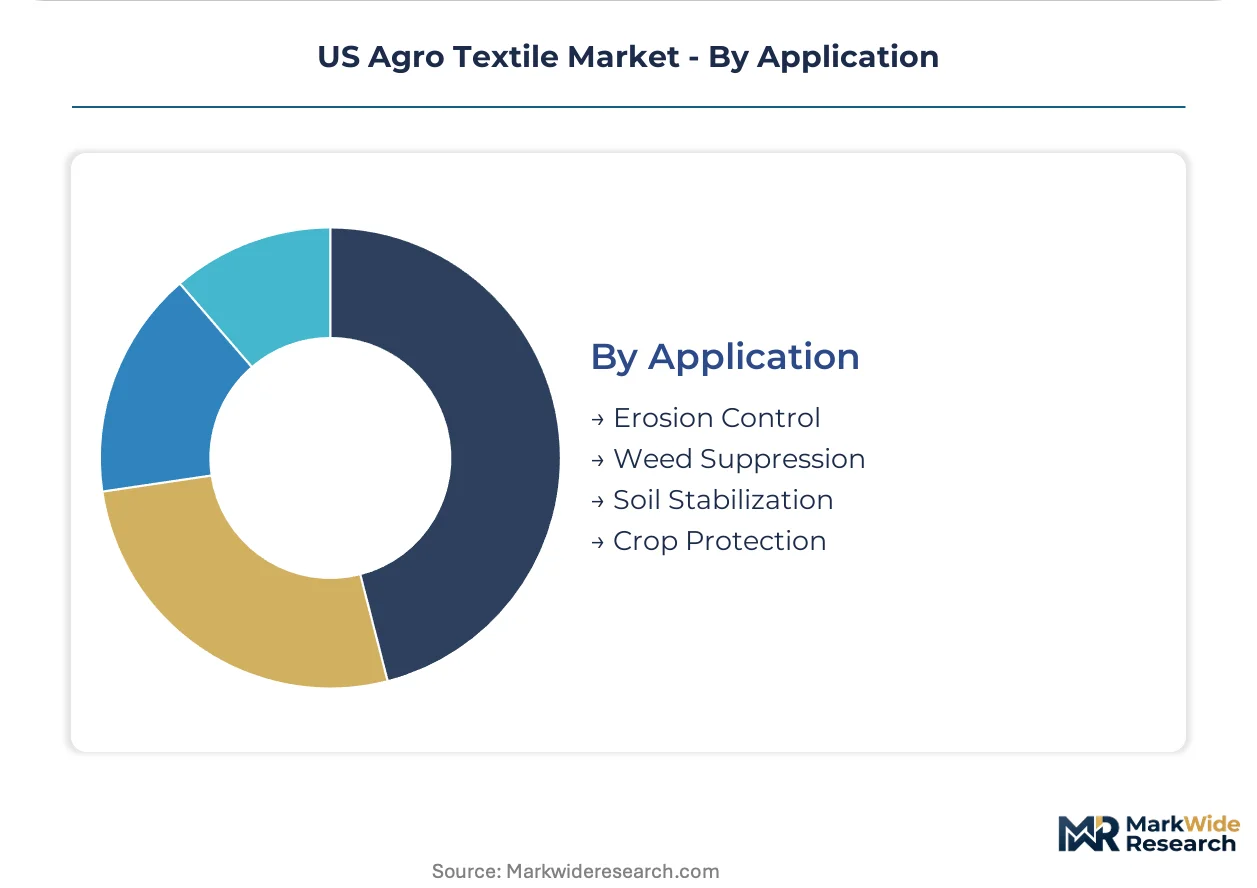
Agro textile procurement in the United States fragments across distinct performance tiers, with material specifications and end-use requirements driving vendor selection. USDA program eligibility and state-level disposal mandates further stratify specification patterns across product categories.
Product Type:
Supply concentration tilts toward manufacturers with extrusion capabilities in woven and nonwoven platforms, with specialty coating operations commanding premium positioning in climate-control applications.
- Geotextiles:Woven and nonwoven polypropylene fabrics engineered for tensile strength and permeability specifications under ASTM D4751 protocols. Demand concentrates in California vineyard erosion-control installations funded by USDA NRCS EQIP cost-share programs, with Washington State watershed restoration projects sustaining structural volumes.
- Shade Cloth:Knitted polyethylene or aluminum-laminated fabrics with calibrated shade percentages for thermal management. Greenhouse operators across Arizona and Texas deploy these systems most intensively, driven by extreme heat events and controlled-environment agriculture expansion.
- Crop Covers:Lightweight nonwoven fabrics for frost protection and season extension. Berry producers in the Pacific Northwest represent the primary demand cluster.
- Mulch Films:Biodegradable and conventional polyethylene sheeting for weed suppression and moisture retention. Organic-certified operations in California and New York are shifting procurement toward compostable PLA and PBAT formulations.
Geotextiles absorb the bulk of installed capacity; shade cloth is expanding most quickly.
Material:
Cost tier differentiation separates commodity polymer supply from specialty biodegradable platforms, with certification requirements creating procurement friction for emerging material categories.
- Polypropylene:Dominant synthetic polymer for woven geotextiles and crop covers, valued for UV resistance and mechanical durability. Petrochemical feedstock volatility exposes manufacturers to margin compression without price pass-through mechanisms.
- Polyester:Higher-tenacity fiber for geotextile applications requiring dimensional stability under load. Demand concentrates in structural soil stabilization projects.
- Natural Fibers:Jute and coir-based fabrics for biodegradable erosion control and organic-certified operations. USDA conservation program specifications increasingly favor these materials in sensitive watersheds.
- PVC:Coated fabrics for specialized greenhouse glazing and high-durability shade systems. Limited adoption due to disposal regulatory pressure.
Polypropylene commands the largest production footprint; natural fibers are climbing the fastest amid compostability mandates.
End User:
Customer type determines contract structure, with large greenhouse operators consolidating procurement around multi-year performance agreements while agricultural producers retain transactional purchasing patterns.
- Agricultural Producers:Broad-acre row crop and specialty crop operators specifying commodity-grade woven covers and mulch films. California and Florida citrus producers represent concentrated demand for frost protection fabrics.
- Greenhouses:Controlled-environment agriculture operators deploying advanced shade cloth and climate-responsive covers. Texas and Arizona facilities lead adoption of sensor-integrated fabric systems.
- Nurseries:Containerized plant operations requiring weed suppression geotextiles and seasonal crop covers. Southeastern United States concentration aligns with regional propagation industry scale.
- Landscapers:Commercial and residential erosion-control and turf stabilization applications. Demand ties to municipal infrastructure and housing development cycles.
Greenhouses concentrate the highest-value procurement; agricultural producers represent the deepest volume pool.
Application:
Application-specific certification requirements channel product development investment, with ASTM and USDA standards creating differentiated compliance burdens across functional categories.
- Erosion Control:Geotextile installations for slope stabilization and watershed protection. USDA NRCS funding priorities in California and Washington sustain specification volumes for high-performance woven fabrics.
- Weed Suppression:Mulch films and woven ground covers for organic and conventional operations. California SB 54 implementation is accelerating biodegradable material substitution.
- Soil Stabilization:Structural geotextile applications for embankment and roadway adjacent agriculture. Corn Belt drainage infrastructure projects generate intermittent demand spikes.
- Crop Protection:Insect barrier, frost protection, and thermal regulation covers. Berry producers in the Pacific Northwest and Florida drive season extension fabric adoption.
Erosion control anchors the most stable revenue base; crop protection applications are gaining share fastest amid climate variability pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley anchors US agro textile demand through its concentration of specialty crop production and USDA-funded conservation installations.
California
High-value vineyard erosion-control projects and strawberry plasticulture operations drive geotextile and mulch film procurement. State-level SB 54 Extended Producer Responsibility mandates accelerate manufacturer transitions toward compostable polymer platforms. Fresno and Monterey counties concentrate precision agriculture cover adoption among berry and vegetable producers.
Florida
Citrus frost protection and strawberry season extension applications sustain woven crop cover volumes across the central ridge region. State agricultural department cost-share programs subsidize precision cover installations for freeze mitigation. Polk and Hillsborough counties cluster nursery propagation operations demanding weed suppression geotextiles.
Texas
Controlled-environment agriculture expansion in the Rio Grande Valley and West Texas drives advanced shade cloth deployment for thermal stress management. USDA NRCS watershed restoration funding supports erosion-control fabric specifications in the Hill Country. El Paso and McAllen metropolitan areas anchor greenhouse operator procurement clusters.
Washington
Watershed restoration projects and vineyard slope stabilization sustain structural geotextile demand across the Columbia Basin and Yakima Valley. State Department of Ecology stormwater regulations mandate erosion-control installations for agricultural land disturbance. Walla Walla and Benton counties concentrate wine grape producer adoption of climate-responsive covers.
Arizona
Extreme heat events propel greenhouse shade cloth deployment across Maricopa and Pinal counties for controlled-environment vegetable production. Colorado River water scarcity pressures drive moisture retention fabric adoption among desert agriculture operators. Yuma County lettuce producers specify advanced thermal management covers for year-round production windows.
US Agro Textile Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct capability tiers. Integrated polymer extrusion and coating operations command procurement relationships with large greenhouse operators and USDA program administrators. Three strategic archetypes populate the vendor base: multinational technical textile conglomerates with geosynthetics divisions, regional woven fabric specialists serving commodity agriculture, and emerging biodegradable material platforms targeting organic-certified operations. Capacity expansion in biopolymer-compatible extrusion lines and strategic partnerships with conservation program administrators represent the dominant competitive moves reshaping channel access.
Within the multinational technical textile tier, TenCate Geosynthetics and Freudenberg Performance Materials exemplify integrated engineering capabilities spanning polymer formulation through finished fabric conversion. Belton Industries, Inc. anchors the regional woven specialist archetype with manufacturing scale concentrated in broad-acre row crop applications. These three entities occupy positions across distinct specification tiers, with technical performance requirements and certification compliance determining procurement eligibility rather than price competition alone.
| Leading Market Players |
|---|
| TenCate Geosynthetics |
| Belton Industries, Inc. |
| Mogul Co., Ltd. |
| Dewitt |
| Freudenberg Performance Materials |
| Garware Technical Fibers Ltd. |
| Beaulieu Technical Textiles |
| Ludvig Svensson |
| Siang May Pte Ltd. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into polymer formulation and extrusion operations anchors competitive position for domestic manufacturers serving USDA program channels, compressing cost structures for woven geotextiles while insulating against resin price volatility. This captive production capability concentrates pricing power among TenCate Geosynthetics and Freudenberg Performance Materials, which bundle certification compliance with fabric supply to greenhouse operators and conservation project administrators.
Pricing Analysis
Yield-guarantee contracts tie shade cloth pricing to thermal management outcomes in Arizona and Texas greenhouse operations, displacing per-square-meter transactional models. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated climate fabrics from commodity woven covers and basic polyethylene sheeting. Cost compression in commodity polypropylene tiers is intensifying because petrochemical feedstock volatility lacks pass-through mechanisms. Broad-acre row crop operators in the Corn Belt exhibit highest price sensitivity; large greenhouse operators in the Southeast prioritize performance guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from California SB 54 compliance officers and USDA NRCS program administrators mandate multi-supplier qualification for biodegradable mulch film procurement, fragmenting vendor concentration. Polypropylene resin draws from Gulf Coast petrochemical complexes and imported Asian feedstocks, while UV stabilizer and anti-fog additive supply rests on three specialty chemical producers. Single-source vulnerability in specialty additive channels creates input bottlenecks during peak conservation program bidding cycles. Distribution runs through agricultural cooperative networks and direct specification to large greenhouse operators, with regional fabric converters handling installation and seasonal removal services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's SB 54 Extended Producer Responsibility framework erects a compliance moat that favors incumbent manufacturers with capitalized biopolymer extrusion lines and ASTM D6400 certification infrastructure, raising barriers for speculative entrants lacking program administrator relationships.
For Market Incumbents: Anticipate biodegradable mulch film substitution pressure by accelerating PLA and PBAT formulation capacity ahead of state-level conventional plastic bans. Defensive consolidation through acquisition of regional woven fabric specialists in Florida and Georgia secures channel access to underpenetrated citrus and strawberry markets. Certification investment in USDA NRCS pre-approval status represents the priority lever for erosion-control specification capture.
For New Entrants and Emerging Players: Capture the Florida central ridge precision cover opportunity where adoption lags California benchmarks by specifying frost protection fabrics through state agricultural department cost-share programs. The most penetrable segment sits among citrus producers seeking freeze mitigation solutions without established vendor relationships. Direct specification to nursery propagation operations in Polk and Hillsborough counties bypasses incumbent greenhouse operator lock-in.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational technical textile conglomerates seeking biopolymer-compatible extrusion assets and USDA program administrator relationships. Long-term viability favors manufacturers with integrated formulation-through-fabric capabilities and conservation program eligibility rather than commodity converters exposed to resin price volatility. Watch for EPA agricultural plastics disposal guideline tightening as the inflection indicator accelerating compostable platform investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Extrusion Capacity Expansion | ASTM D6400 certification unlocks California and New York organic-certified procurement channels. |
| USDA NRCS Program Administrator Partnership | Pre-approved vendor status accelerates erosion-control specification capture in conservation-funded projects. |
| Sensor-Fabric Convergence Development | Integrated moisture monitoring enables subscription performance contracts with Texas greenhouse operators. |
| Regional Woven Fabric Specialist Acquisition | Florida and Georgia channel access penetrates underpenetrated citrus and strawberry markets. |
| Specialty Additive Supplier Diversification | Dual-sourcing UV stabilizers mitigates single-supplier concentration risk in peak bidding cycles. |
Research Methodology
Multi-period observation of USDA NRCS funding allocations, state-level plastic disposal mandate implementation timelines, and biodegradable polymer certification progress anchored the trend analysis, supplemented by interviews with polymer formulation chemists, greenhouse operations managers, conservation program administrators, and agricultural cooperative procurement directors. Secondary validation drew from EPA agricultural plastics disposal guidelines, California SB 54 regulatory filings, ASTM D4751 and D6400 testing protocols, and USDA EQIP cost-share distribution data. Bottom-up segment volume estimates triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting across product type, material composition, end-user category, and application function informed the analytical framework, with geotextile, shade cloth, crop cover, and mulch film categories modeled separately. CAGRs derived from installed base expansion rates, replacement cycle analysis, and program funding trajectory assumptions throughout the forecast period. Industry-specific inputs included petrochemical feedstock price correlation models, conservation program appropriation forecasting, and biodegradable polymer adoption curve parameters from organic-certified operations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA guideline evolution, state-level Extended Producer Responsibility implementation pace, and breakthrough biodegradable material performance validation. Deviation in California SB 54 enforcement severity or USDA conservation program appropriation levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Anti Wind Net Market