
 Agriculture Tire Market | 2026-2036
Agriculture Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Tire Market Analysis
Large-scale contract farming enterprises are reorganizing fleet replacement cycles, shifting from seasonal purchasing to multi-year tire procurement contracts. Michelin leverages its radial technology leadership to command premium positioning in North American row-crop applications. Bridgestone Corporation anchors its position through integrated distribution networks spanning farm cooperatives and OEM channels. Titan International, Inc. competes aggressively on price in the aftermarket replacement segment for aging harvester fleets.
Agriculture tires are reinforced rubber composite structures engineered to carry loads exceeding 10,000 kg while operating at inflation pressures as low as 0.8 bar to minimize soil compaction in cultivated fields. Radial tires now dominate original equipment fitment on tractors above 200 horsepower due to superior traction efficiency and reduced fuel consumption versus bias-ply constructions. Bias tires retain structural relevance in emerging markets where purchase price sensitivity outweighs total cost-of-ownership calculations for smallholder equipment. The extra-large size category is capturing margin concentration as manufacturers of 500+ horsepower tractors specify single-tire solutions for flotation applications.
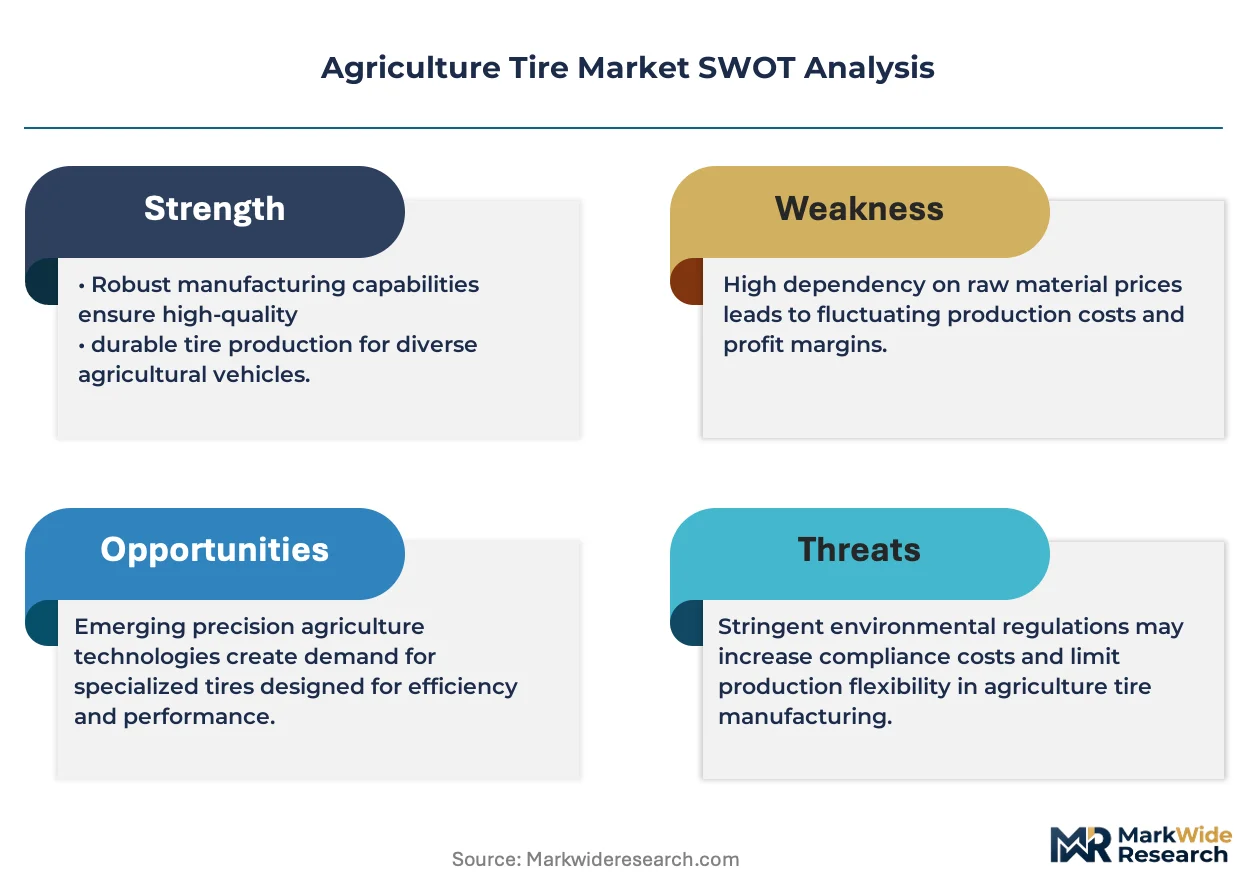
The EPA regulates tire rolling resistance labeling for agricultural equipment sold in the United States, while REACH compliance in Europe restricts certain rubber compounding chemicals used in tire manufacturing. India's BIS certification mandates minimum load-bearing standards for tires fitted to tractors receiving government subsidy under the PLI scheme. Stakeholders must monitor how evolving deforestation-linked sourcing requirements under the EU Green Deal reshape natural rubber supply chains and regional manufacturing footprints.
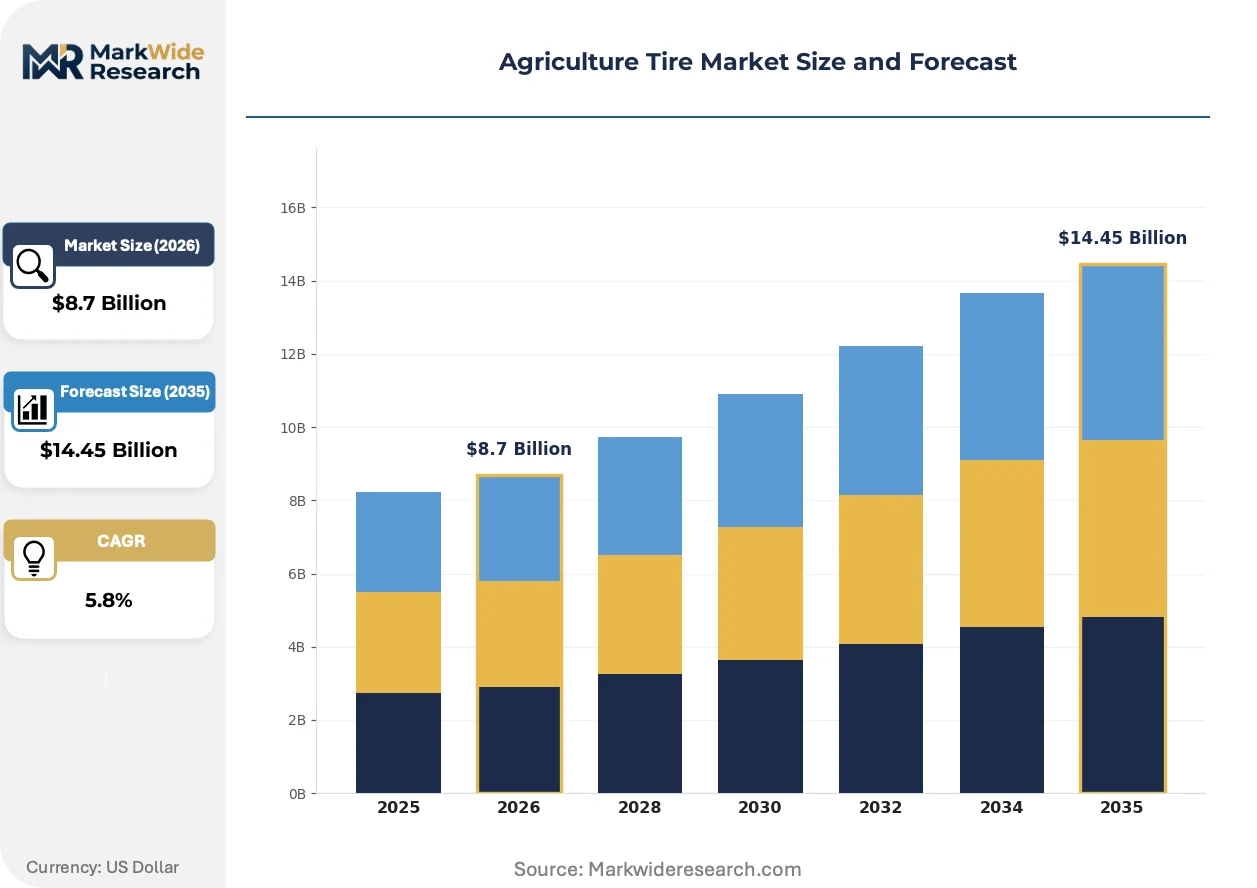
Market Dynamics
Radial tire technology is compressing bias-ply market share as commercial farm operators prioritize fuel efficiency metrics and soil compaction compliance under tightening environmental frameworks.
Growth Catalysts
- EU Green Deal soil compaction mandates:Low-pressure radial designs now dominate procurement specifications for tractors above 200 horsepower across European arable operations.
- Precision agriculture integration:Variable inflation systems paired with telematics enable real-time pressure adjustment based on field conditions and implement load.
- Brazil's Mato Grosso soybean belt:Large-scale contract farming enterprises are consolidating tire procurement into multi-year supply agreements with volume guarantees.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and deforestation-linked sourcing scrutiny compress margin predictability for compound formulations.
- REACH chemical restrictions:ECHA limitations on specific rubber processing aids force reformulation cycles that extend product development timelines.
- Steel cord supply concentration:Dependence on specialized tire-grade steel from concentrated metallurgical suppliers creates input bottleneck risk.
Strategic Opportunities
- India's Punjab-Haryana rice-wheat corridor:Government tractor subsidies under the PLI scheme accelerate fleet modernization and radial conversion among smallholder cooperatives.
- Single-tire flotation solutions:Extra-large diameter tires for 500+ horsepower tractors eliminate dual-wheel configurations and reduce soil contact pressure.
- Retreading service networks:Circular economy frameworks in the European Union create demand for certified remanufacturing services extending tire lifecycle value.
Industry Challenges
- Radial construction technician scarcity:Specialized curing and belt calibration expertise lags behind production capacity expansion in emerging manufacturing hubs.
- BIS certification timelines:Indian subsidy eligibility requires extended laboratory testing protocols that delay market entry for new tire specifications.
- Legacy bias-ply inventory absorption:Distribution channels face working capital strain from stranded stock as procurement pivots toward radial architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Tire Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Narrow Tires, Wide Tires End Use: Tractors, Harvesters, Sprayers, Planters Size: Small, Medium, Large, Extra Large Terrain Type: Field, Road, Wetland, Rocky |
| Companies Covered | Michelin, Bridgestone Corporation, Titan International, Inc., Continental AG, Trelleborg AB, Balkrishna Industries Limited, Apollo Tyres Ltd., Sumitomo Rubber Industries, Ltd., Firestone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Tire Market Emerging Trajectories
Active tread compounds and connected inflation systems are converging to transform tire performance from a passive component into an integrated farm management input. This shift redefines value capture along the supply chain.
Very high flexion (VF) technology enables 40% load capacity at equivalent pressure or 40% pressure reduction at equivalent load compared to standard radials. Large-scale row-crop operators in North America are specifying VF fitments on new tractor orders. This specification is displacing conventional radial designs in the premium original equipment channel.
EPA rolling resistance labeling requirements for agricultural equipment sold in the United States now mandate standardized test protocols and disclosure thresholds. Tire manufacturers must submit verified coefficient data to maintain distribution eligibility. The regulation most affects bias-ply producers serving price-sensitive aftermarket segments where efficiency metrics previously carried minimal weight.
Fleet managers are consolidating supplier relationships around integrated service contracts bundling tires, pressure monitoring hardware, and predictive replacement scheduling. Equipment dealers are capturing this value stream through captive financing arrangements and telematics-enabled performance guarantees. This consolidation is most visible in Brazil's mechanized soybean operations where downtime costs exceed tire price differentials by substantial margins.
Agriculture Tire Market Segmentation
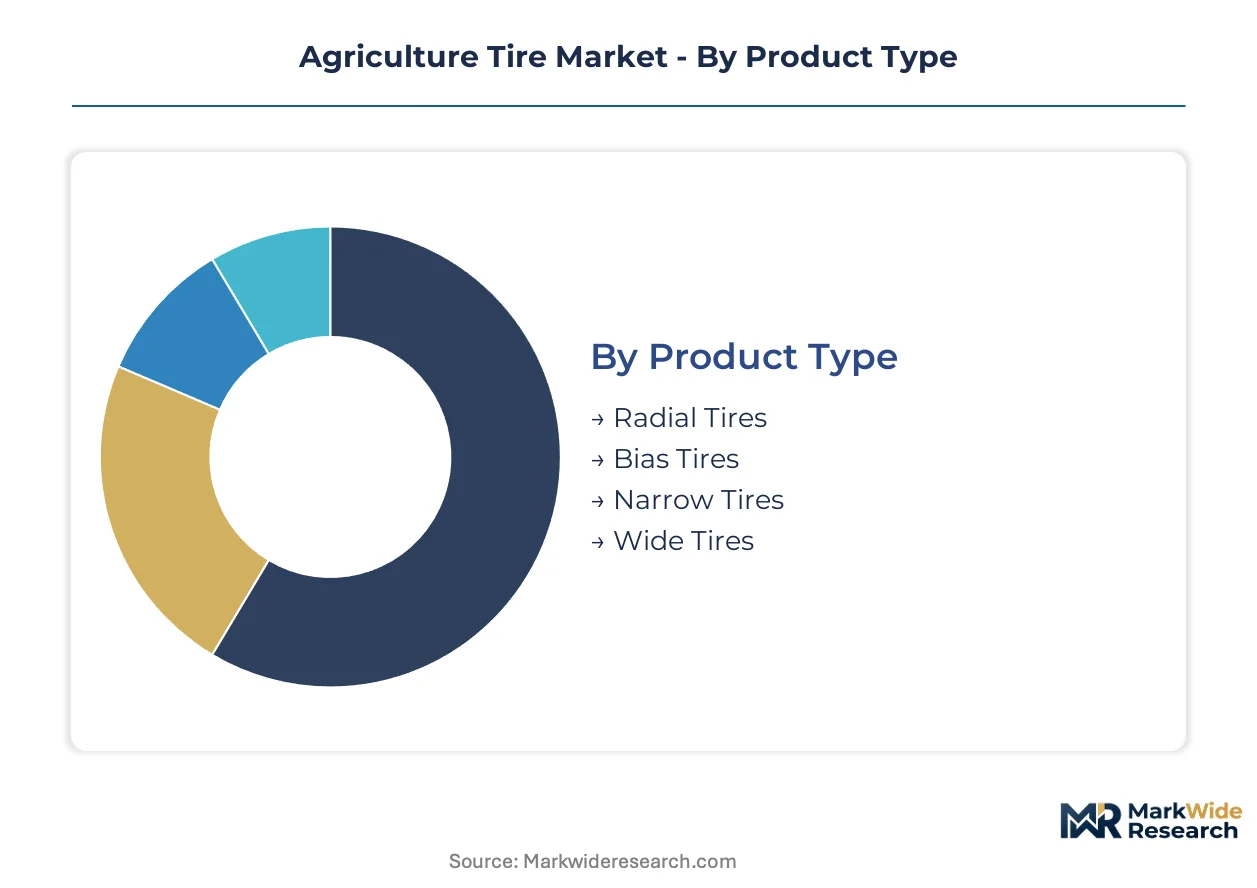
Segmentation in agriculture tires reveals how procurement priorities diverge between commercial farming operations and smallholder cooperatives. Technology choices, equipment horsepower ratings, and soil compaction compliance requirements create distinct demand pockets across product architectures and end-use applications.
Product Type:
Radial tire designs dominate export flows to North American and European commercial farms, while bias constructions retain domestic manufacturing concentration in India and Southeast Asian markets serving price-sensitive smallholders.
- Radial Tires:Steel-belted construction with flexible sidewalls enables 15-20% fuel efficiency gains versus bias alternatives. Demand concentrates in Brazil's Mato Grosso soybean belt where 300+ horsepower tractors require low-pressure flotation fitments to comply with EU Green Deal-linked sourcing standards for exported commodity crops.
- Bias Tires:Cross-ply nylon or polyester cord layers deliver lower unit costs but higher rolling resistance. Procurement persists in India's Punjab-Haryana rice-wheat corridor where government PLI scheme subsidies favor affordable replacement cycles for aging two-wheel tractor fleets.
- Narrow Tires:High-aspect-ratio designs minimize crop damage in row-crop cultivation with 30-inch or narrower spacing specifications.
- Wide Tires:Flotation footprints distribute load across larger surface areas for tillage operations in high-moisture soil conditions.
Radial tires hold the largest share; momentum sits with wide tires as 500+ horsepower tractor specifications proliferate.
End Use:
Equipment replacement cycles vary dramatically by application type, with harvester tires commanding premium pricing due to seasonal intensity and downtime sensitivity.
- Tractors:Original equipment fitment spans utility classes from 50 to 600+ horsepower. Row-crop specifications in Iowa and Illinois increasingly specify VF (very high flexion) technology for variable inflation management.
- Harvesters:Combine and forage harvester tires endure extreme load spikes during grain tank filling. Replacement demand concentrates in Ukraine's Black Sea grain corridor and Australia's wheat belt where harvest windows compress operational timelines.
- Sprayers:Self-propelled applicators require high-speed roading capability alongside field flotation, driving dual-compound tread designs.
- Planters:Precision seeding equipment demands minimal soil disturbance, favoring narrow-section tires with rounded shoulders.
Tractor tires generate the highest absolute volume; harvester applications deliver the steepest margin expansion.
Size:
Dimensional specifications track horsepower escalation trends, with extra-large categories capturing disproportionate value as single-tire flotation solutions displace dual-wheel configurations.
- Small:Rim diameters below 24 inches serve compact utility tractors and orchard equipment in Mediterranean specialty crop zones.
- Medium:24-to-38-inch rim sizes dominate emerging market smallholder fleets in Vietnam's Mekong Delta rice production.
- Large:38-to-54-inch specifications anchor mainstream row-crop and livestock operations across the US Corn Belt.
- Extra Large:Single tires exceeding 54 inches eliminate dual configurations on 500+ horsepower tractors. Adoption accelerates in Germany's Lower Saxony arable belt where soil compaction regulations under the EU Green Deal mandate minimum ground pressure thresholds.
Large sizes command current procurement volume; extra-large specifications are climbing the fastest as horsepower ratings escalate.
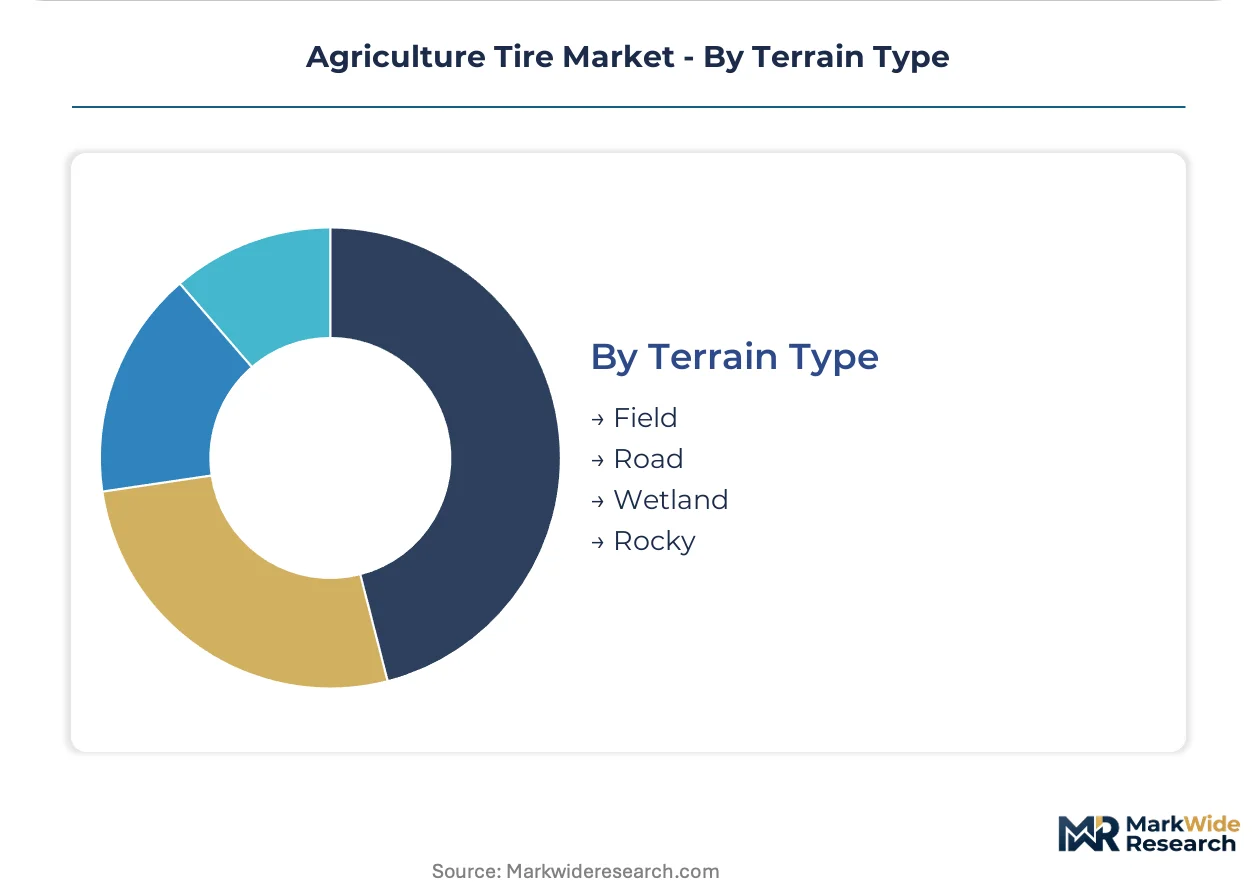
Terrain Type:
Tread pattern engineering diverges sharply between high-speed roading requirements and specialized traction needs in adverse field conditions.
- Field:Bar-lug or R-1 patterns optimize traction in dry cultivated soils. Specifications dominate North American spring planting and fall harvest seasons.
- Road:Ribbed designs minimize heat buildup and wear during transport between dispersed land parcels. Critical for Australian broadacre operations where equipment relocation distances exceed 50 kilometers.
- Wetland:Deep-lug R-2 patterns with self-cleaning tread geometry prevent mud packing in rice paddy and saturated clay conditions. Essential for Indonesia's Java irrigation districts.
- Rocky:Reinforced sidewalls and cut-resistant compounds protect against stubble puncture and stone damage in no-till systems.
Field tires retain the dominant installed base; wetland specifications are gaining share fastest as rice cultivation mechanizes in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt exports commodity crops to European Union buyers under EU Green Deal-linked sourcing standards. This trade-flow corridor shapes tire procurement specifications across South American agricultural operations.
United States
EPA rolling resistance labeling mandates now govern agricultural equipment tire specifications. Row-crop operators in Iowa and Illinois specify VF technology for variable inflation management. The Corn Belt anchors demand for large-diameter radial fitments on 300+ horsepower tractors.
Germany
Soil compaction thresholds under the EU Green Deal accelerate extra-large tire adoption. Lower Saxony's arable belt specifies single-tire flotation solutions for 500+ horsepower tractors. ECHA REACH compliance forces reformulation cycles for rubber processing aids.
Brazil
Large-scale contract farming enterprises consolidate procurement into multi-year supply agreements. ANVISA oversees agricultural equipment standards while export-linked sourcing requirements shape tire specifications. The Mato Grosso soybean belt drives demand for low-pressure radial designs.
India
BIS certification mandates minimum load-bearing standards for PLI scheme-subsidized tractors. Punjab-Haryana rice-wheat corridor operators favor affordable bias-ply replacement cycles. Government fleet modernization programs accelerate radial conversion among smallholder cooperatives.
China
Dual carbon goals and MIIT industrial policies reshape domestic tire manufacturing footprints. Shandong Peninsula producers supply emerging market smallholder segments with bias-ply constructions. GB standards govern agricultural machinery tire specifications for domestic equipment.
Agriculture Tire Market Vendor Landscape
Player mix skews toward diversified rubber conglomerates with integrated distribution networks. Consolidation around radial technology leadership creates tiered competitive positioning. Three archetypes dominate: premium technology specialists, integrated OEM-channel operators, and price-focused aftermarket suppliers. Capacity expansion in emerging manufacturing hubs and strategic partnerships for telematics integration represent the dominant competitive vectors.
Among diversified rubber conglomerates, Michelin and Bridgestone Corporation exemplify premium-tier positioning through radial technology leadership and integrated farm cooperative networks. Titan International, Inc. occupies the price-competitive aftermarket segment. Continental AG represents European engineering-focused positioning. Balkrishna Industries Limited and Apollo Tyres Ltd. anchor emerging market supply for bias-ply constructions. Trelleborg AB exemplifies specialized agricultural tire engineering.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Titan International, Inc. |
| Continental AG |
| Trelleborg AB |
| Balkrishna Industries Limited |
| Apollo Tyres Ltd. |
| Sumitomo Rubber Industries, Ltd. |
| Firestone |
| Others |
Supply Flow & Price Mechanics
Multi-year volume-guarantee contracts between Mato Grosso soybean operators and radial tire suppliers lock in both natural rubber feedstock access and price predictability across volatile commodity cycles. These arrangements transfer inventory carrying costs upstream while shielding commercial farms from spot-market spikes in steel cord and carbon black inputs.
Pricing Analysis
VF technology generation commands 25-35% premiums over standard radial architectures in North American original equipment channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Pricing pressure stems from REACH-mandated reformulation costs that compounders pass through to tire manufacturers. Smallholder cooperatives in India's Punjab-Haryana corridor exhibit highest price sensitivity, while EU Green Deal-compliant commercial operations absorb premiums for soil-compaction-certified fitments.
Supply Chain Analysis
Strategic stockpiling of natural rubber dominates procurement behavior among tier-one manufacturers buffering against Southeast Asian supply disruptions. Thailand, Indonesia, and Vietnam anchor raw material extraction; steel cord feeds from South Korean and Japanese metallurgical specialists. Supply chain risk concentrates in single-source dependency for tire-grade steel alloys. Distribution runs through farm cooperative networks and OEM captive channels rather than independent aftermarket wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal soil compaction mandates are compressing bias-ply market share faster than replacement cycle absorption rates, creating structural disruption for legacy inventory holders.
For Market Incumbents: Secure radial curing capacity expansion in emerging manufacturing hubs before technician scarcity hardens into production bottlenecks. Defend margin position through backward integration into natural rubber processing assets in Southeast Asia. Channel control via telematics-enabled service contracts locks out price-competitive aftermarket entrants in Brazil's mechanized soybean belt. For New Entrants and Emerging Players: Lead with retreading service network certification under EU circular economy frameworks, capturing stranded value in aging harvester fleets. Target India's smallholder cooperative segment with BIS-certified bias-ply replacements during PLI scheme fleet modernization waves. Go-to-market through equipment dealer captive financing arrangements rather than independent distribution. For Investors and Strategic Acquirers: Capital is best deployed toward specialized agricultural tire engineering firms with proven VF technology portfolios and existing OEM qualification status. Long-term viability hinges on regulatory compliance capability rather than scale economies alone. Watch for ECHA expansion of restricted substance lists as the inflection signal forcing accelerated reformulation investment.| Strategic Initiative | Industry Significance |
|---|---|
| VF Technology Scale-Up | Very high flexion capacity expansion captures premium OE specifications from John Deere and Case IH. |
| Natural Rubber Backward Integration | Upstream control over Southeast Asian plantations insulates margin from deforestation-linked sourcing scrutiny. |
| Telematics Partnership Development | Integration with precision agriculture platforms enables real-time pressure management service revenue streams. |
| Retreading Network Certification | EU circular economy compliance extends tire lifecycle value and defends against low-cost import competition. |
| India PLI Scheme Alignment | BIS certification investment unlocks government-subsidized tractor fleet replacement demand concentration. |
Methodological Framework
A spread of perspectives from tire manufacturing plant managers, farm cooperative procurement leads, OEM platform engineers, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation against customs trade data, SEC filings from diversified rubber conglomerates, and ANVISA agricultural equipment registration databases. Bottom-up volume triangulation across horsepower segments and top-down value reconciliation anchored the analytical framework.
Segmentation dimensions modeled span product architecture, equipment horsepower tier, end-use application intensity, and regional regulatory compliance cluster across the projection horizon. CAGRs derived from equipment fleet replacement cycle analysis and radial conversion penetration curves. Industry-specific forecast inputs include EU Green Deal implementation timelines and PLI scheme subsidy disbursement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained commodity crop pricing and stable Southeast Asian natural rubber harvests would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology adoption elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Cambodia Agricultural Machinery Market