
 Farming Sacks and Totes Market | 2026-2036
Farming Sacks and Totes Market Size, Share, and Industry Trends Forecast 2026-2036
Farming Sacks and Totes Market Foresight
A capital-intensity divergence between integrated multinationals and regional converters is rotating competitive dynamics across the farming sacks sector. Mondi Group leverages its pulp-to-packaging integration to control fiber input costs across European grain markets. LC Packaging International BV anchors its position through specialized FIBC engineering for agricultural cooperatives in the Netherlands and beyond. Berry Global Inc. competes on scale, sustaining high-volume polypropylene woven output for North American fertilizer distributors.
Farming sacks and totes constitute flexible intermediate bulk containers and smaller-format woven or non-woven bags engineered from polypropylene, cotton, jute, or polyester fibers, typically rated for loads between 25 kg and 2,000 kg and manufactured via circular weaving, lamination, and UV-stabilization processes to protect agricultural commodities during storage and transport. Woven polypropylene sacks dominate volume due to tear resistance and cost efficiency in grain handling, while bulk bags capture premium margin pools through multi-trip designs for fertilizer and feed applications. Cotton and jute materials occupy niche positions where biodegradability commands buyer preference among organic produce distributors and specialty crop cooperatives.
REACH compliance in Europe and FDA food-contact regulations in the United States shape material selection and migration testing protocols for agricultural packaging, while India's BIS certification mandates tensile strength and dimensional stability standards for domestic woven sack producers. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based material mandates as these regulatory vectors increasingly determine market access and product development priorities.
Market Dynamics
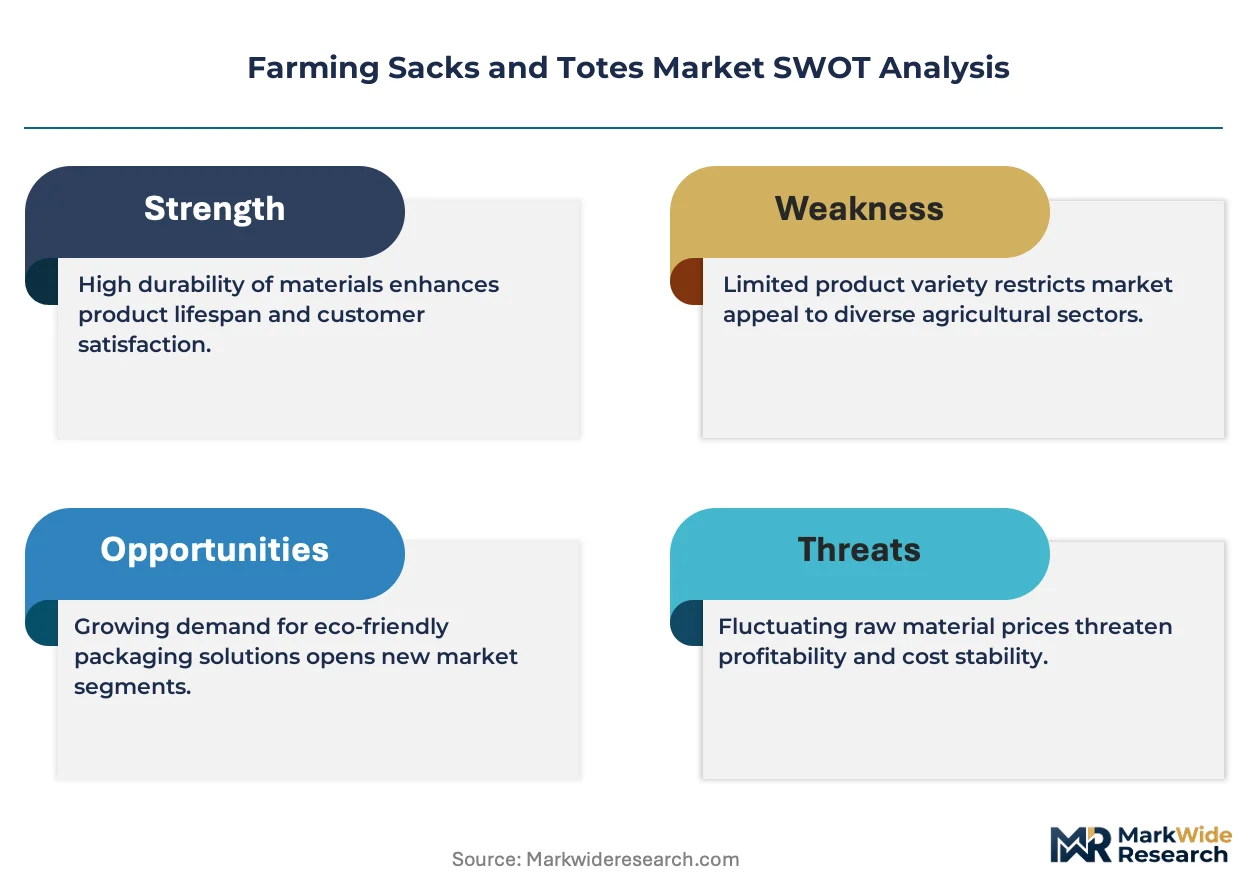
Polypropylene resin cost volatility and the EU Single-Use Plastics Directive are compressing converter margins while accelerating material substitution toward bio-based woven formats across European grain handling networks.
Growth Catalysts
- REACH chemical safety mandates:European fertilizer cooperatives now specify UV-stabilized, migration-tested woven sacks for agrochemical containment, creating specification premiums for compliant converters.
- Brazilian soybean belt mechanization:Mato Grosso grain elevators deploy automated bulk bag filling systems that standardize 1,000 kg FIBC formats across cooperative procurement.
- Multi-trip bulk bag engineering:Reinforced lifting loops and coated fabrics extend service life to 6-8 handling cycles, displacing single-use alternatives in North American feed distribution.
Market Restraints
- Propylene feedstock concentration:Gulf Coast petrochemical complexes supply 70% of North American resin, exposing converters to hurricane-related supply interruptions.
- Jute cultivation decline:Bangladeshi fiber output contraction limits biodegradable sack availability for organic certification holders seeking plastic alternatives.
- FDA food-contact migration thresholds:Extended testing timelines for polypropylene additives delay new product launches by 8-14 months for US grain exporters.
Strategic Opportunities
- Indian Punjab wheat corridor cold storage expansion:Government-backed grain silo construction creates demand for breathable woven sacks with moisture-wicking laminates.
- EU Green Deal bio-based content mandates:2030 targets for renewable feedstock incorporation incentivize PLA-coated polypropylene development.
- Direct-to-farm e-commerce channels:Agricultural input platforms bypass distributor networks, enabling private-label sack customization for 500+ kg seed deliveries.
Industry Challenges
- Circular weaving technician scarcity:European and North American loom operators require 18-24 month apprenticeships, constraining capacity expansion timelines.
- ISO 21898 FIBC certification complexity:Multi-trip validation protocols demand destructive testing budgets that mid-scale converters struggle to fund.
- Legacy ERP integration with track-and-trace systems:Batch-level RFID tagging for extended producer responsibility compliance requires warehouse management overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farming Sacks and Totes Market |
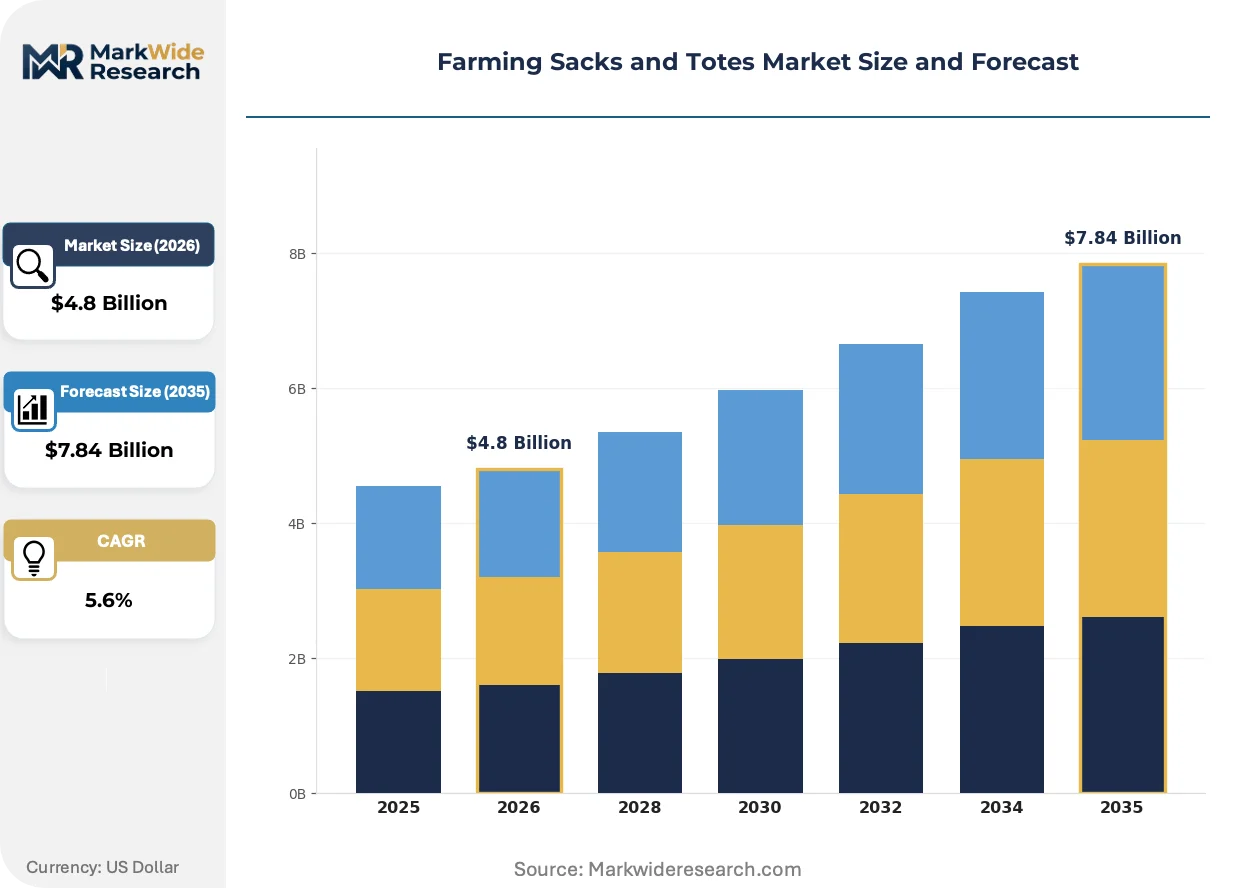
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Sacks, Non-Woven Sacks, Totes, Bulk Bags Material: Polypropylene, Cotton, Jute, Polyester Application: Agricultural Produce, Fertilizers, Grains, Feed End User: Farmers, Distributors, Retailers, Cooperatives |
| Companies Covered | Mondi Group, Berry Global Inc., Amcor plc, Sonoco Products Company, International Paper Company, LC Packaging International BV, ProAmpac LLC, Novolex Holdings, Segezha Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farming Sacks and Totes Market Shifts & Advancements
Material science advances and regulatory compliance automation are redefining competitive advantage in agricultural flexible packaging, with sustainability verification emerging as a non-negotiable procurement filter.
Co-extruded multilayer barrier films are miniaturizing oxygen transmission rates in grain storage applications. Premium seed distributors in Iowa and Illinois adopt these laminates for hybrid corn preservation. The technology is miniaturizing the performance gap between woven polypropylene and multi-wall paper sacks, compressing paper's remaining 12% share in moisture-sensitive segments.
REACH SVHC candidate list expansion forces reformulation of phthalate-based plasticizers in sack coatings. ECHA's 2024 update added three polymer additives common in agricultural packaging. European converters accelerate bio-based plasticizer substitution, with Dutch and German cooperatives now requiring full substance disclosure in supplier declarations.
Cooperative procurement consolidation restructures distributor relationships. Large Midwest grain elevators and Brazilian super-cooperatives negotiate multi-year sack supply agreements directly with integrated manufacturers. This behavior concentrates volume among three to four preferred suppliers per region, marginalizing independent regional converters in Iowa, Mato Grosso, and Punjab.
Farming Sacks and Totes Market Segmentation
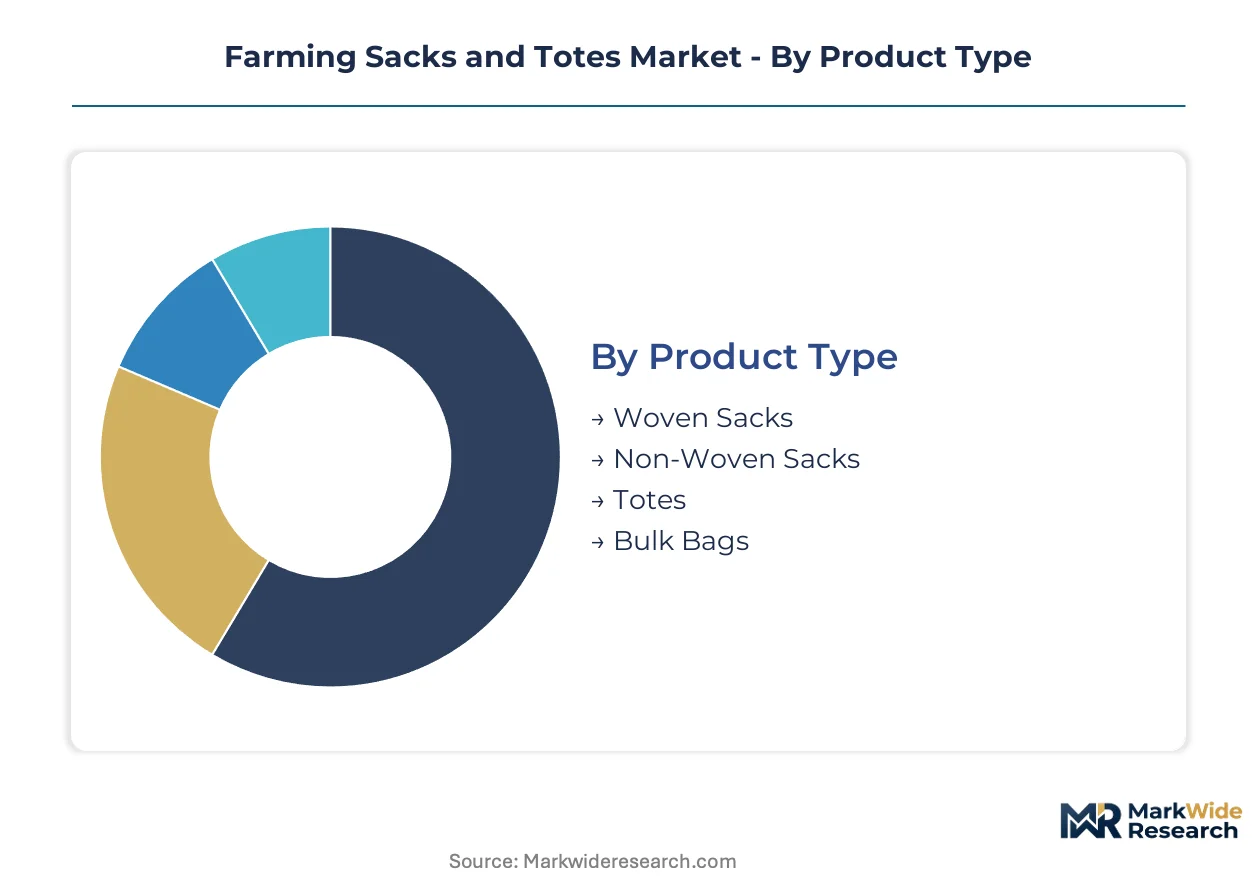
Farming sacks and totes traverse distinct procurement channels depending on format scale and buyer sophistication. Bulk bags flow through cooperative procurement desks while smaller woven sacks distribute via agricultural input retailers. Material selection and load rating determine which segments capture margin versus volume across grain belt logistics networks.
Product Type:
Woven sacks and bulk bags dominate cooperative procurement channels, while non-woven formats and totes concentrate in retail agricultural supply chains serving smaller-scale operations.
- Woven Sacks:Circular-woven polypropylene fabric rated for 25-50 kg loads, laminated for moisture resistance and UV-stabilized for outdoor storage. Brazilian soybean cooperatives in Mato Grosso standardize these for automated grain elevator filling systems. REACH-compliant coatings command specification premiums in European fertilizer handling.
- Bulk Bags:Flexible intermediate bulk containers engineered for 500-2,000 kg capacities with reinforced lifting loops and coated fabrics enabling 6-8 handling cycles. North American feed distributors deploy multi-trip designs to displace single-use alternatives. ISO 21898 certification complexity limits mid-scale converter participation.
- Non-Woven Sacks:Spunbond polypropylene structures for lightweight seed and produce protection, common in Indian Punjab retail channels.
- Totes:Semi-rigid portable containers for specialty crop transport, favored by organic produce distributors seeking biodegradable alternatives.
By volume, woven sacks lead. By growth pace, bulk bags are expanding most quickly.
Material:
Raw material cost tiers stratify converter margins, with petrochemical-derived fibers occupying high-volume positions and natural fibers capturing sustainability premiums at lower output scales.
- Polypropylene:Thermoplastic polymer dominating agricultural flexible packaging through tear resistance, chemical inertness, and cost efficiency. Gulf Coast petrochemical concentration exposes North American converters to hurricane-related supply interruptions. EU Single-Use Plastics Directive accelerates bio-based coating development.
- Jute:Lignocellulosic bast fiber from Corchorus plants, biodegradable and carbon-sequestering during cultivation. Bangladeshi output contraction limits availability for organic certification holders. Specialty crop cooperatives in India and Brazil absorb remaining supply at 40-60% cost premiums over synthetic alternatives.
- Cotton:Natural cellulose fiber for breathable storage applications in heritage grain preservation.
- Polyester:High-tenacity synthetic for heavy-duty lifting loop reinforcement in multi-trip bulk bags.
Polypropylene captures the volume base. Jute commands the steepest price escalation trajectory.
Application:
Commodity type dictates barrier specification intensity, with agrochemical containment requiring migration-tested laminates while grain storage prioritizes breathability.
- Grains:Wheat, corn, soybean, and rice handling drives woven sack standardization across elevator networks. Iowa and Illinois hybrid seed distributors adopt co-extruded multilayer barrier films for oxygen transmission rate miniaturization. Moisture-wicking laminates penetrate Indian Punjab government-backed silo construction.
- Fertilizers:Agrochemical containment demands UV-stabilized sacks with phthalate-free plasticizer coatings following ECHA SVHC list expansion. European cooperatives now mandate full substance disclosure in supplier declarations. FDA food-contact migration thresholds delay US exporter product launches.
- Agricultural Produce:Fresh vegetable and fruit transport requiring ventilation-optimized fabric structures.
- Feed:Compound animal nutrition distribution favoring multi-trip bulk bag economics in North American distributor networks.
Grains dominate tonnage throughput. Fertilizer specifications drive the fastest margin expansion.
End User:
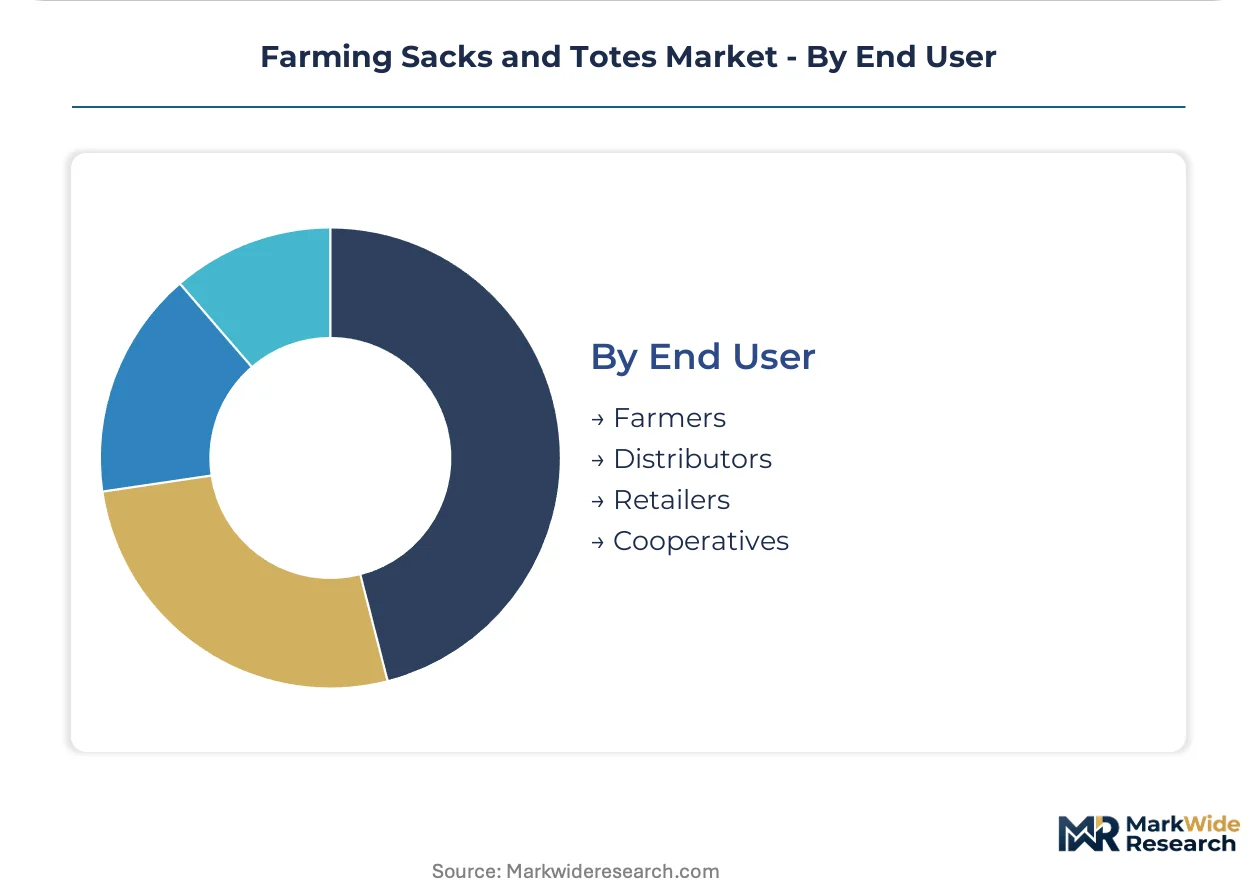
Buyer scale determines contract structure, with cooperatives negotiating multi-year direct agreements while farmers purchase through distributor markups.
- Cooperatives:Consolidated procurement entities standardizing formats across member farms to achieve logistics efficiency. Brazilian super-cooperatives and Midwest grain elevators concentrate volume among three to four preferred suppliers per region. Direct manufacturer relationships marginalize independent regional converters.
- Farmers:Individual agricultural operators purchasing through retail agricultural input channels or direct-to-farm e-commerce platforms bypassing distributor networks. Private-label sack customization emerges for 500+ kg seed deliveries through digital procurement.
- Distributors:Intermediary networks stocking standardized inventory for emergency replacement and small-lot fulfillment.
- Retailers:Farm supply stores serving hobby and mid-scale operations with pre-packaged sack assortments.
Cooperatives command the largest per-transaction volumes. Farmer-direct e-commerce channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across grain belts. Brazilian soybean cooperatives absorb premium multi-trip bulk bag costs for logistics efficiency, while Indian Punjab smallholders prioritize per-unit sack economy over durability specifications.
Brazil
Mato Grosso grain elevators drive automated FIBC filling system deployment across super-cooperative networks. ANVISA agrochemical containment regulations mandate UV-stabilized woven sack specifications for fertilizer handling. São Paulo-based converters supply laminated formats to the Cerrado soybean belt where mechanized handling dominates procurement.
United States
Iowa and Illinois hybrid seed distributors adopt co-extruded multilayer barrier films for oxygen transmission control in heritage grain preservation. FDA food-contact migration thresholds delay polypropylene additive launches by 8-14 months for grain exporters. Midwest elevator networks concentrate volume among three to four preferred suppliers per region.
India
Punjab wheat corridor cold storage expansion generates demand for breathable woven sacks with moisture-wicking laminates. BIS certification mandates tensile strength and dimensional stability standards for domestic woven sack producers. Gujarat textile clusters supply polypropylene fabric to northern grain handling networks.
Germany
REACH SVHC candidate list expansion forces reformulation of phthalate-based plasticizers in sack coatings. ECHA substance disclosure requirements now apply to agricultural packaging supplied to Dutch and German cooperatives. North Rhine-Westphalia chemical clusters develop bio-based plasticizer alternatives for compliant converters.
Netherlands
LC Packaging International BV anchors specialized FIBC engineering for agricultural cooperatives across domestic and export markets. EU Green Deal bio-based content mandates incentivize PLA-coated polypropylene development by 2030. Rotterdam logistics hubs distribute multi-trip bulk bags to European grain networks.
Farming Sacks and Totes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the farming sacks sector. Integrated multinationals with pulp-to-packaging or resin-to-fabric capabilities control input costs and specification premiums. Regional converters compete on responsiveness and customized short runs for cooperative procurement. The dominant competitive moves are backward integration into fiber or resin production and geographic expansion through distributor network consolidation.
Within the integrated multinational tier, Mondi Group and Berry Global Inc. represent contrasting scale-versus-specialization positions. Mondi leverages European pulp integration for fiber cost control across grain markets. Berry sustains high-volume polypropylene woven output for North American fertilizer distribution networks. LC Packaging International BV occupies a specialist position in cooperative-facing FIBC engineering.
| Leading Market Players |
|---|
| Mondi Group |
| Berry Global Inc. |
| Amcor plc |
| Sonoco Products Company |
| International Paper Company |
| LC Packaging International BV |
| ProAmpac LLC |
| Novolex Holdings |
| Segezha Group LLC |
| Others |
Supply & Pricing Matrix
Ninety-day polypropylene resin inventory cycles at Gulf Coast petrochemical complexes directly tether converter margin stability to hurricane-season supply interruption risk, concentrating pricing power among integrated multinationals with captive resin production while forcing regional weavers toward spot-market vulnerability.
Pricing Analysis
After-sales revenue from multi-trip bulk bag refurbishment and lifting-loop replacement services drives lifetime value capture for cooperative-facing manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 21898 certification grade and volume commitment scale, with European fertilizer cooperatives absorbing specification premiums for REACH-compliant coatings while Indian Punjab smallholders prioritize per-unit economy over durability. Pricing pressure stems from propylene feedstock volatility transmitted through Gulf Coast concentration, with margins tightening most acutely for mid-scale converters lacking backward integration into resin production.
Supply Chain Analysis
China and Saudi Arabia anchor global polypropylene resin production, with Bangladesh and India supplying residual jute fiber for biodegradable alternatives. Converter operations draw from circular weaving equipment concentrated in Germany and Italy, plus UV-stabilization chemical inputs from North Rhine-Westphalia clusters. Single-source vulnerability runs through Gulf Coast petrochemical complexes supplying North American weavers. Distribution runs through cooperative procurement desks for bulk bags and agricultural input retailers for smaller woven formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as direct-to-farm e-commerce channels bypass distributor networks, creating niches for specialized converters serving private-label seed delivery customization.
For Market Incumbents: Secure cooperative procurement relationships through multi-year volume commitments before Brazilian super-cooperatives and Midwest grain elevators finalize preferred supplier consolidation. Invest in ISO 21898 multi-trip certification to capture specification premiums displacing single-use alternatives. Backward integration into polypropylene resin production insulates margin compression from Gulf Coast supply interruption exposure. For New Entrants and Emerging Players: Anchor in Indian Punjab government-backed silo construction demand for breathable woven sacks with moisture-wicking laminates, where BIS-certified domestic producers face capacity constraints. Target organic produce distributors seeking jute alternatives amid Bangladeshi fiber output contraction. Pursue direct-to-farm e-commerce platform partnerships for 500+ kg seed delivery customization bypassing distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated packaging conglomerates seeking to divest non-core agricultural flexible packaging divisions amid pulp-to-packaging strategic refocusing. Five-to-ten year viability hinges on bio-based coating development capabilities aligned with EU Green Deal mandates. Monitor ECHA SVHC candidate list expansion velocity as inflection indicator for reformulation cost acceleration among coating-dependent converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Gulf Coast petrochemical concentration exposes non-integrated weavers to hurricane-related supply interruptions and margin volatility. |
| Multi-Trip Bulk Bag Certification Investment | ISO 21898 validation protocols enable specification premiums displacing single-use alternatives in North American feed distribution networks. |
| Bio-Based Coating Development Partnership | EU Green Deal mandates incentivize PLA-coated polypropylene engineering for compliant access to Dutch and German cooperative procurement. |
| Direct-to-Farm E-Commerce Channel Launch | Agricultural input platforms bypass distributor networks enabling private-label sack customization for specialized seed delivery volumes. |
| Circular Weaving Technician Apprenticeship Program | Eighteen-to-twenty-four month training timelines constrain European and North American capacity expansion without pipeline investment. |
Research Methodology
Cross-validation between cooperative procurement manager interviews and customs trade data anchors the qualitative findings on regional volume concentration. Primary fieldwork engaged woven sack plant managers, agricultural cooperative procurement leads, circular weaving equipment suppliers, and UV-stabilization chemical distributors across Brazil, the United States, India, Germany, and the Netherlands. Secondary validation drew from BIS certification registries, ECHA substance disclosure databases, ANVISA agrochemical containment filings, and SEC 10-K disclosures from integrated packaging multinationals. Bottom-up capacity modeling triangulated against top-down trade flow analysis.
Sensitivity analysis across propylene price scenarios and regulatory compliance cost trajectories frames the projection horizon. Segmentation dimensions modeled include product format scale, material fiber type, commodity application intensity, and buyer procurement channel structure. CAGRs derived from installed base growth rates and replacement cycle analysis, with grain handling mechanization indices and cold storage construction pipelines serving as industry-specific demand inputs.
Underlying assumptions cover REACH SVHC list stability, Bangladeshi jute cultivation recovery, and Gulf Coast petrochemical operational continuity, with deviation risk concentrated in ECHA regulatory acceleration and hurricane-season supply disruption frequency. Recalibration cycles align with material shifts in EU bio-based content mandate enforcement and Brazilian super-cooperative procurement consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
Agricultural Fabrics Market