
 Polymer Coated Urea Market | 2026-2036
Polymer Coated Urea Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Coated Urea Market Analytics
Specialty agronomy distribution is tilting toward direct farm advisory models that bundle polymer coated urea with soil testing services. Koch Agronomic Services leverages its controlled-release technology portfolio to dominate premium channels in North American corn production. Nutrien Ltd anchors broadacre supply through its retail network spanning seven countries. Haifa Group specializes in water-soluble and coated formulations for high-value horticulture segments.
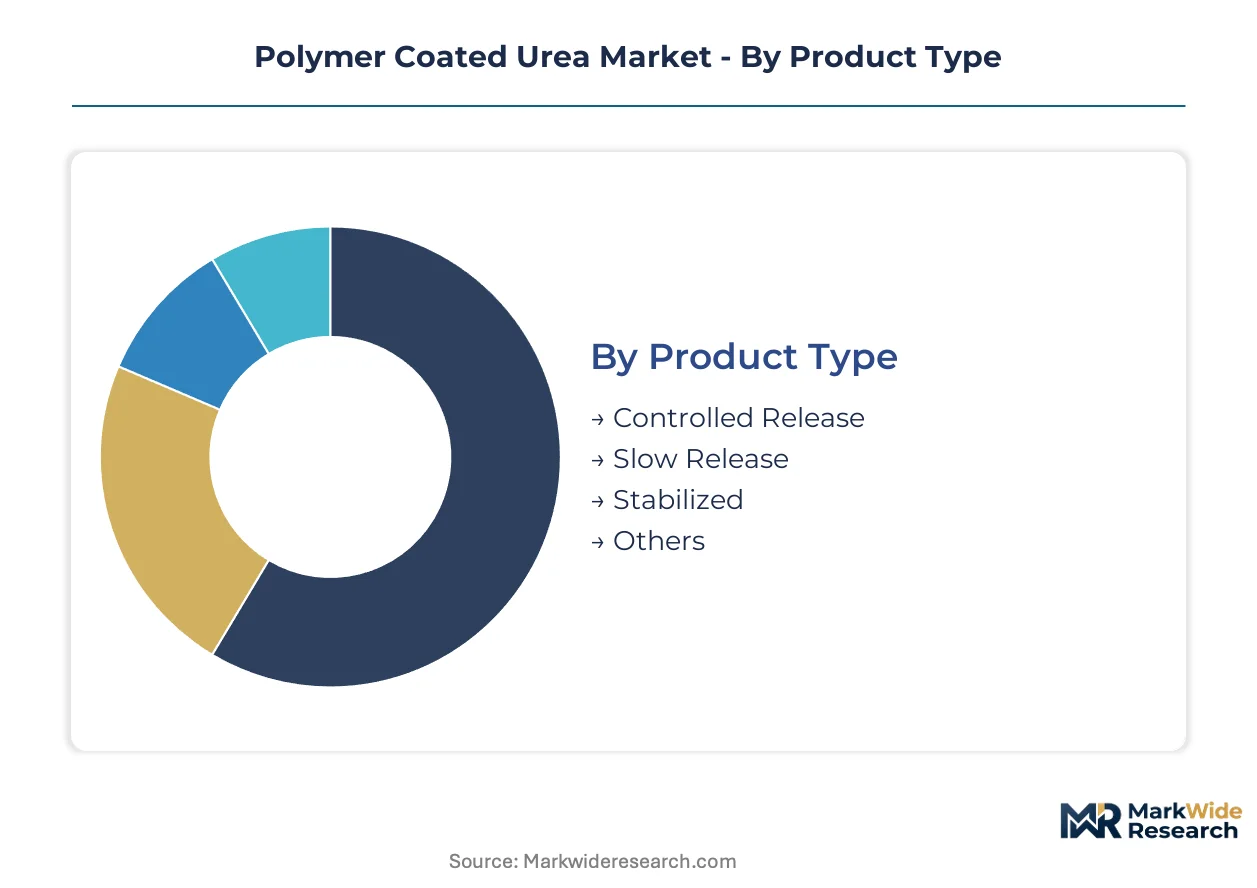
Polymer coated urea consists of urea granules encapsulated with sulfur-polymer or resin-based membranes that regulate nitrogen release through temperature-dependent diffusion, typically delivering nutrients over 45 to 180 days. The coating thickness and polymer composition determine release kinetics, enabling single-application programs that reduce labor and environmental losses. Controlled release formulations command the highest margin pools as growers pay premiums for predictable nutrient availability during critical crop stages. Slow release products occupy the volume-heavy mid-tier where sulfur-coated variants compete on cost against resin alternatives. Granular form dominates field crop applications while pelletized grades penetrate greenhouse and nursery channels.
The EPA regulates polymer coated urea as a fertilizer product under TSCA while state-level nutrient management plans in Maryland and Ohio restrict application timing and rates. REACH compliance in Europe governs polymer coating chemistries and their environmental fate assessments. Stakeholders must monitor evolving carbon intensity scoring for fertilizer production as buyers begin linking procurement decisions to Scope 3 emissions accounting.
Market Dynamics
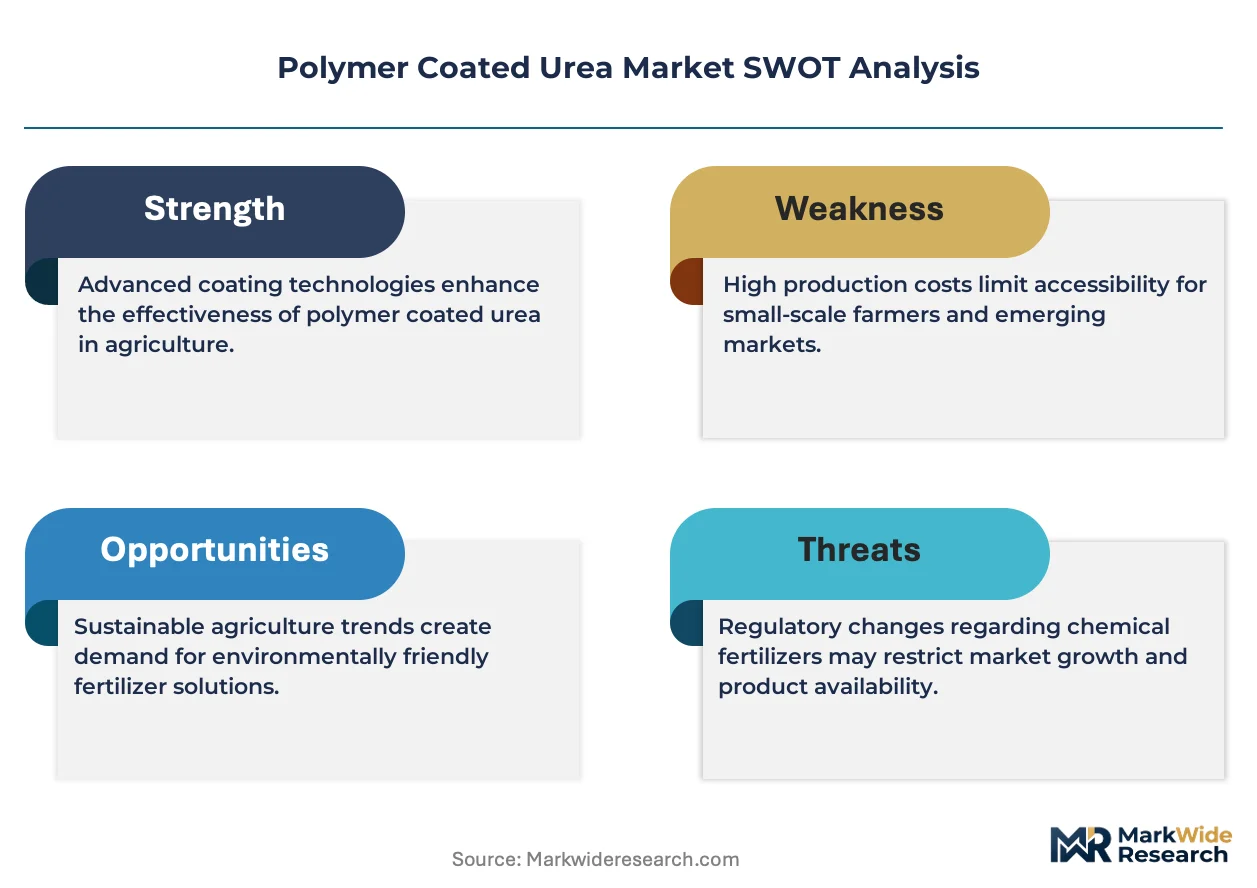
The EU Fertilizing Products Regulation is forcing manufacturers to revalidate coating chemistries under stricter biodegradability criteria, compressing product development timelines while opening premium positioning for compliant formulations. This regulatory pivot is concentrating competitive advantage among firms with in-house polymer synthesis capabilities.
Growth Catalysts
- Precision Agriculture Integration:Variable-rate application systems in North American grain farming are creating pull for controlled-release nitrogen that synchronizes nutrient availability with crop sensor data.
- EU Green Deal Carbon Accounting:The CSRD disclosure requirements are pushing food processors to source fertilizers with verified Scope 3 emissions reductions, favoring coated urea over conventional alternatives.
- Water-Soluble Polymer Advances:New coating materials derived from biomass feedstocks are enabling biodegradability claims that satisfy emerging eco-label standards in horticulture channels.
Market Restraints
- Feedstock Cost Volatility:Natural gas price swings directly impact urea base material costs, compressing margin buffers for coating operations without long-term supply contracts.
- Technical Performance Limits:Existing sulfur-polymer membranes exhibit temperature sensitivity that limits reliability in tropical climates with extreme diurnal variation.
- Substitution Pressure:Nitrification inhibitors applied to conventional urea offer comparable nitrogen use efficiency gains at lower per-hectare cost in price-sensitive broadacre segments.
Strategic Opportunities
- Underpenetrated Pastoral Zones:New Zealand dairy operations present white space for controlled-release formulations that reduce nitrate leaching under intensive grazing systems.
- Carbon Credit Monetization:Voluntary carbon market protocols for agricultural emissions reductions are creating revenue stacking opportunities for farmers adopting enhanced-efficiency fertilizers.
- Drone Application Compatibility:Pelletized coating grades formulated for aerial dispersal are opening channel access to service providers deploying precision spraying fleets.
Industry Challenges
- Formulation Talent Scarcity:The specialized knowledge required for polymer rheology and release kinetics modeling is concentrated among a narrow cohort of agricultural chemists.
- Registration Timeline Compression:REACH dossier preparation for novel coating substances demands 18-24 month regulatory investment before market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Coated Urea Market |
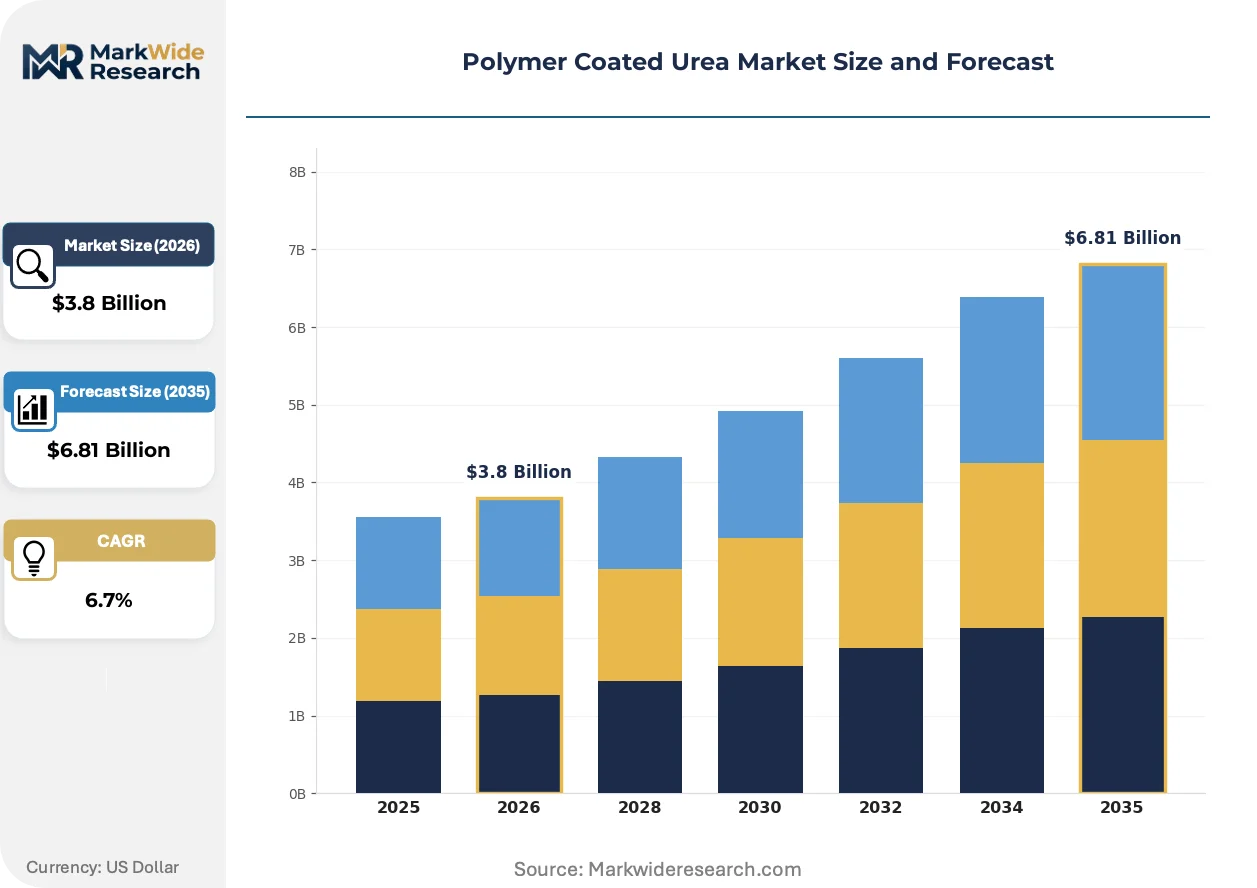
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controlled Release, Slow Release, Stabilized, Others End Use Industry: Agriculture, Horticulture, Turf Management, Landscaping Application: Fertilizers, Plant Nutrition, Soil Improvement, Crop Protection Form: Granular, Pelletized, Liquid, Coated |
| Companies Covered | Koch Agronomic Services LLC, J.R. Simplot Company, Nutrien Ltd, Compo Expert GmbH, Haifa Group, BASF SE, ICL Specialty Fertilizers Ltd, The Mosaic Company, Yara International ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Coated Urea Market Evolving Landscape
Coating technology is hybridizing with digital agriculture infrastructure, creating demand for products that integrate with farm management software rather than functioning as standalone inputs. This convergence is reshaping how manufacturers structure technical service offerings.
Biodegradable polymer coatings derived from polylactic acid and polyhydroxyalkanoates are hybridizing with conventional sulfur-matrix formulations to balance release control with soil microbial breakdown. Specialty crop producers in California's Central Valley are piloting these hybrid materials for permanent tree crops where residual polymer accumulation poses long-term soil health concerns. The technology is hybridizing competitive positioning by enabling premium pricing for products that satisfy both performance and sustainability procurement criteria.
The EPA is tightening enforcement of state nutrient management plans under the Clean Water Act, particularly in Chesapeake Bay watershed states where application timing windows are narrowing. This regulatory pressure is accelerating grower migration toward single-application controlled-release programs that comply with restricted fall nitrogen bans. Corn-soybean operations in Maryland and Ohio are responding by consolidating purchases through agronomy retailers offering compliance-certified product bundles.
Buyer concentration among large-scale farming cooperatives is consolidating procurement decisions for polymer coated urea into centralized purchasing agreements that emphasize total cost of ownership over unit price. Independent agronomy retailers are losing share to vertically integrated supply chains that bundle soil testing, prescription maps, and controlled-release products into annual service contracts. This consolidation is most pronounced in Brazil's Mato Grosso soybean belt where production-scale farms command volume-based pricing leverage.
Polymer Coated Urea Market Segmentation
Segmentation in polymer coated urea reveals distinct margin architectures and customer loyalty patterns across formulation technologies and application contexts. Each category carries unique inventory velocity and technical service requirements that reshape go-to-market economics for manufacturers.
Product Type:
Cycle times vary sharply across this category, with controlled release formulations commanding extended sales cycles due to trial protocols while sulfur-coated variants turn inventory rapidly through commodity channels.
- Controlled Release:Resin or polymer-encapsulated granules regulate nitrogen diffusion through temperature-responsive membranes, typically spanning 60 to 180 days. Corn-soybean operations in Iowa and Illinois pay premiums for single-application programs that eliminate split-nitrogen passes and comply with fall application bans.
- Slow Release:Sulfur-coated urea dominates volume through lower unit costs and established distribution, though temperature sensitivity limits reliability in tropical zones with extreme diurnal swings. Brazilian Cerrado soybean growers increasingly specify sulfur-polymer hybrids that balance cost with performance consistency.
- Stabilized:Nitrification inhibitor blends extend urea efficiency without full encapsulation, competing on per-hectare cost in price-sensitive broadacre segments.
- Others:Emerging bio-based coatings and hybrid formulations occupy niche positioning in specialty crop channels.
Controlled Release anchors the volume base while Slow Release gains share at the steepest rate through sulfur-polymer hybridization.
End Use Industry:
Margin tiers separate this category, with horticulture and turf commanding 40-60% premiums over agricultural bulk sales due to formulation precision and technical support intensity.
- Agriculture:Field crop production consumes the majority of polymer coated urea tonnage, with North American grain operations and Brazilian soybean farms driving specification toward controlled-release programs that synchronize with precision planting equipment.
- Horticulture:Greenhouse and nursery operations demand pelletized grades with exact release curves for containerized production, with California Central Valley permanent crop growers piloting biodegradable hybrid coatings to address residual polymer accumulation concerns.
- Turf Management:Golf course and sports field maintenance requires predictable color response without surge growth, favoring resin-based formulations with tight release coefficient variation.
- Landscaping:Municipal and commercial grounds maintenance represents emerging volume through contract specifications emphasizing reduced application frequency and runoff compliance.
Agriculture anchors the volume base while Horticulture climbs the fastest on biodegradable coating premiums.
Application:
Customer concentration patterns differentiate this category, with fertilizer blending operations purchasing at scale while crop protection integrators seek bundled formulation partnerships.
- Fertilizers:Direct application as primary nitrogen source dominates tonnage, with bulk blenders specifying coating grades compatible with existing handling equipment and regional climate profiles.
- Plant Nutrition:Foliar and fertigation-compatible formulations serve high-value specialty crops through water-soluble coating technologies that Haifa Group and comparable specialists commercialize.
- Soil Improvement:Long-term structural amendments incorporate slow-release nitrogen to support microbial community establishment in degraded or sandy soils.
- Crop Protection:Co-encapsulation with fungicides or biostimulants represents emerging integrated product architecture, though registration complexity limits current commercialization.
Fertilizers anchors the volume base while Plant Nutrition expands most quickly on specialty crop premiumization.
Form:
Equipment compatibility and handling characteristics segment this category, with granular formulations optimized for ground spreaders and pelletized grades engineered for aerial application systems.
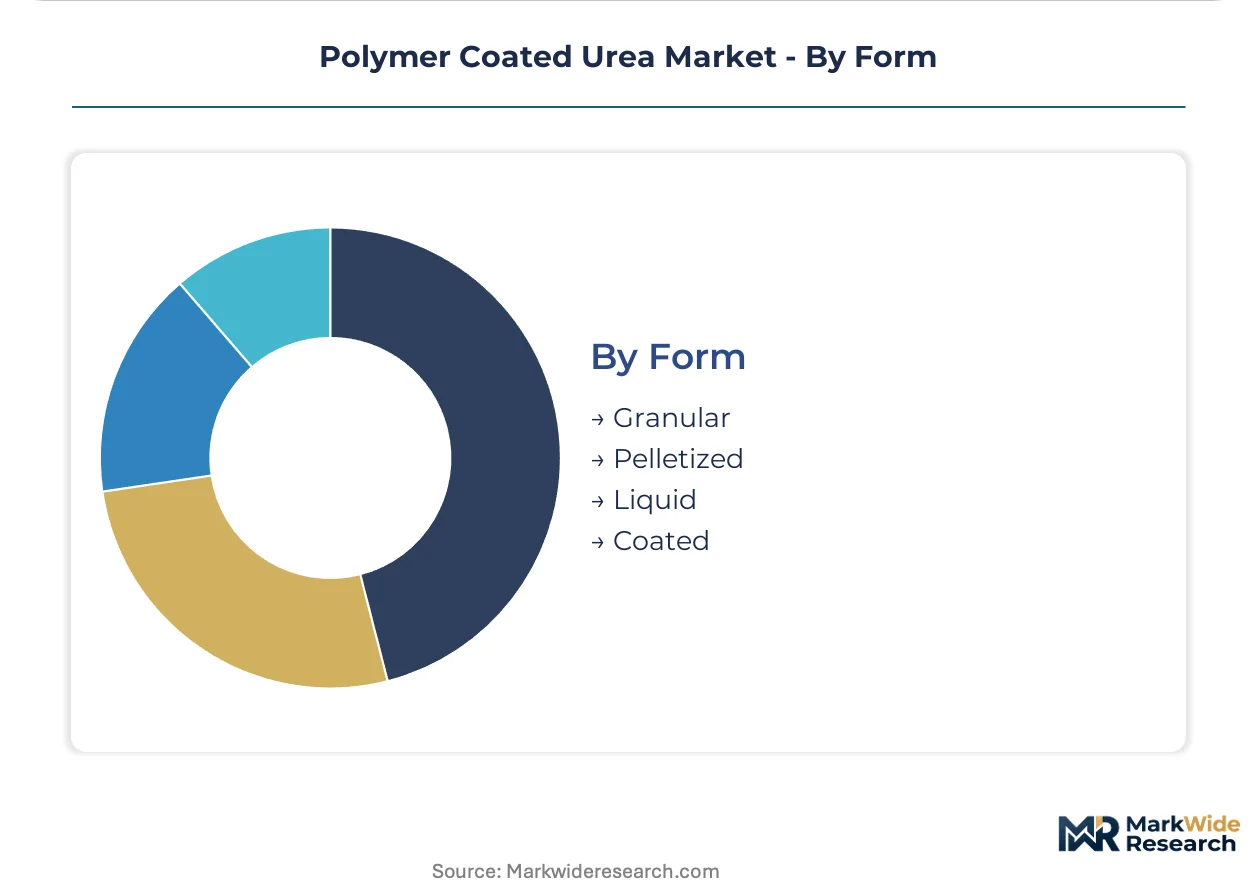
- Granular:Standard field-grade particles calibrated for spinner spreaders and air seeders dominate agricultural volume, with sizing distributions tuned to regional equipment specifications.
- Pelletized:Uniform density spheres enable precision drone dispersal and greenhouse metering systems, with Brazilian Mato Grosso service providers driving uptake for aerial application fleets.
- Liquid:Suspension concentrates and emulsified coatings serve fertigation networks and hydroponic operations through compatible injection systems.
- Coated:Value-added finished products with proprietary coating layers command premium positioning through performance guarantees and technical service bundling.
Granular anchors the volume base while Pelletized shows the steepest expansion trajectory on drone application adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Iowa and Illinois corn-soybean belts, while Brazilian Cerrado operations extract volume discounts through cooperative purchasing leverage. This asymmetry reshapes manufacturer go-to-market economics across both hemispheres.
United States
Variable-rate application systems in Iowa and Illinois grain operations drive specification toward controlled-release formulations that synchronize with crop sensor data. The EPA enforces state nutrient management plans under the Clean Water Act, particularly narrowing fall nitrogen application windows in Chesapeake Bay watershed states. Corn-soybean operations in Maryland and Ohio consolidate purchases through compliance-certified agronomy retailers.
Brazil
Soybean production in Mato Grosso commands volume-based pricing leverage through centralized cooperative purchasing agreements. ANVISA oversees fertilizer product registration while state-level environmental agencies in Goiás and Mato Grosso do Sul tighten runoff monitoring protocols. Aerial application service providers in the Cerrado belt drive uptake of pelletized coating grades engineered for drone dispersal compatibility.
Germany
Potato and sugar beet operations in Lower Saxony specify sulfur-polymer hybrids that balance cost with performance consistency under variable spring temperatures. REACH compliance governs coating chemistry dossiers through ECHA, compressing product development timelines for novel biodegradable formulations. Industrial clusters around Cologne and Leverkusen concentrate polymer synthesis capabilities serving specialty crop channels across the EU.
China
Intensive vegetable production in Shandong and Hebei provinces generates demand for water-soluble coating technologies compatible with fertigation infrastructure. The Ministry of Ecology and Environment tightens carbon intensity scoring for fertilizer production under dual carbon goals. Manufacturing concentration in the Yangtze River Delta supplies both domestic horticulture segments and export markets across Southeast Asia.
Australia
Winter cereal operations in New South Wales and Victoria trial controlled-release programs to reduce nitrate leaching under variable rainfall patterns. The country's national agricultural regulator oversees fertilizer quality standards while state-level environmental protection agencies in Queensland monitor Great Barrier Reef catchment runoff. Permanent crop growers in the Murray-Darling Basin pilot biodegradable hybrid coatings to address residual polymer accumulation in long-term orchard soils.
Polymer Coated Urea Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in coating chemistry and release-kinetics modeling. The vendor base organizes around three strategic archetypes: multinational agrochemical conglomerates with retail distribution networks, specialty fertilizer formulators with polymer synthesis capabilities, and regional blenders serving commodity broadacre channels. Dominant competitive moves include backward integration into polymer raw material production and technology licensing partnerships that accelerate registration timelines in regulated markets.
Among North American platform integrators, Koch Agronomic Services LLC and Nutrien Ltd anchor the premium and volume tiers respectively. Haifa Group exemplifies the specialty formulator archetype with concentrated positioning in water-soluble and coated technologies. European players including BASF SE and Yara International ASA leverage REACH-compliant chemistry portfolios to defend positioning in sustainability-driven procurement channels.
| Leading Market Players |
|---|
| Koch Agronomic Services LLC |
| J.R. Simplot Company |
| Nutrien Ltd |
| Compo Expert GmbH |
| Haifa Group |
| BASF SE |
| ICL Specialty Fertilizers Ltd |
| The Mosaic Company |
| Yara International ASA |
| Others |
Value Network & Pricing Analysis
Natural gas price volatility acts as the dominant risk vector, compressing margin buffers for coating operations while simultaneously widening spreads between sulfur-coated economy tiers and resin-based premium formulations. This feedstock exposure forces manufacturers to structure long-term supply contracts or captive production arrangements that reshape competitive positioning across value chain tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order controlled-release formulations from standard sulfur-coated bulk grades. Pricing stratifies across premium, standard, and economy tiers based on coating chemistry complexity and release duration guarantees. Cost compression in the sulfur-coated segment is intensifying as nitrification inhibitor blends erode share in price-sensitive broadacre channels. Brazilian cooperative buyers exhibit highest price sensitivity through centralized procurement leverage, while Iowa corn operations pay least attention to unit cost when single-application compliance benefits are bundled.
Supply Chain Analysis
Upstream urea feedstock draws from concentrated natural gas processing clusters in the United States, Russia, and the Middle East. Polymer coating materials rest on sulfur supply from petroleum refining byproducts and resin precursors from petrochemical complexes. Single-source vulnerability concentrates in specialty polymer additives where German and Belgian chemical clusters dominate REACH-compliant production. Distribution runs through agronomy retail networks that bundle soil testing, prescription mapping, and controlled-release products into annual service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymer coated urea market rewards firms possessing integrated polymer synthesis capabilities and regulatory dossier expertise, assets concentrated among a narrow cohort of agricultural chemists. Manufacturers without in-house coating chemistry development face compressed timelines and elevated registration costs.
For Market Incumbents: Insulate premium positioning by accelerating backward integration into biodegradable polymer feedstocks and securing REACH dossier precedents ahead of EU Fertilizing Products Regulation enforcement. Koch Agronomic Services and comparable platform integrators should lock in exclusive distribution agreements with precision agriculture service providers before channel consolidation hardens. Threat substitution from nitrification inhibitor blends demands response through performance guarantee bundling that commodity competitors cannot replicate.
For New Entrants and Emerging Players: New Zealand dairy operations present the most penetrable white space, with controlled-release nitrogen adoption lagging behind North American and Brazilian benchmarks despite comparable environmental compliance pressures. Australian winter cereal regions offer secondary entry through biodegradable hybrid coatings addressing permanent crop residual accumulation concerns. A drone-application compatibility positioning opens channel access to aerial service providers in Brazil's Mato Grosso without requiring established retail infrastructure.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors firms with captive polymer synthesis and pre-validated REACH dossiers. Long-term viability across the analysis window hinges on carbon intensity scoring capabilities that satisfy Scope 3 procurement criteria from food processors. Acquisition targets should demonstrate in-house coating chemistry development rather than toll manufacturing arrangements. The signal to watch is CSRD disclosure adoption rates among European food processors, which will accelerate premium fertilizer sourcing decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive supply of biodegradable coating materials reduces REACH registration timeline exposure. |
| REACH Dossier Pre-validation | Early compliance with EU Fertilizing Products Regulation secures premium channel access before competitors. |
| Precision Agriculture Partnership | Integration with variable-rate application systems in Iowa and Illinois locks in specification pull. |
| Drone-Compatible Formulation Development | Pelletized grades engineered for aerial dispersal open Brazilian service provider channels. |
| Carbon Intensity Certification Program | Verified Scope 3 emissions reductions satisfy CSRD-linked procurement from European food processors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer coating chemists, agronomy retail procurement directors, precision agriculture service providers, and regulatory affairs specialists; and secondary validation through customs trade databases, EPA nutrient management plan filings, ECHA REACH dossier repositories, and SEC 10-K disclosures from listed fertilizer manufacturers. Bottom-up triangulation against top-down market sizing ensured segmentation integrity across formulation technologies and regional demand clusters.
Forecast inputs incorporated coating chemistry adoption curves, regulatory timeline compression effects, and precision agriculture equipment penetration rates across the projection horizon. Segmentation modeling spanned release mechanism type, end-use crop category, application equipment compatibility, and regional compliance framework intensity. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-validation against historical nitrogen use efficiency improvement trajectories and fertilizer price elasticity patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed manufacturers or unexpected EU regulatory acceleration would shift outcomes beyond modeled ranges. Cross-checking against customs export data and agronomy retail inventory velocity metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
North America Fertilizers Market
Fertilizers
France Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Soil Conditioners Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market