
 Global Agriculture Nets Market | 2026-2036
Global Agriculture Nets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agriculture Nets Market Foresight
High-density polyethylene is shifting toward bio-based and recycled feedstocks as virgin resin costs pressure net manufacturers across Asia and Europe. Ginegar Plastic Products Ltd. leverages vertical integration from polymer extrusion to finished shade nets, sustaining margin control across Israel and export markets. Berry Global Inc. competes through scale in North American agricultural film and netting, while Garware Technical Fibres Limited anchors Indian subcontinent supply with specialized UV-stabilized formulations for tropical climates.
Agriculture nets are woven or knitted textile barriers engineered from UV-stabilized polymers with mesh counts ranging from 10 to 50 threads per centimeter, designed to modulate solar radiation, exclude pests, or dissipate kinetic energy from hail and wind. Shade nets command the largest product volume globally due to their deployment across greenhouse cultivation and nursery operations, while insect nets capture accelerating growth as integrated pest management protocols tighten chemical restrictions across the European Union and Southeast Asia. Anti-hail nets concentrate margin pools in Mediterranean and East Asian fruit-growing belts where crop value density justifies premium installation costs.
The European Chemicals Agency enforces REACH substance restrictions on phthalate plasticizers and heavy-metal stabilizers used in PVC-coated fibers, redirecting formulation R&D toward polyethylene and polypropylene alternatives. China's Ministry of Ecology and Environment applies dual carbon goals to petrochemical-intensive manufacturing, pressuring domestic net producers to adopt lower-emission extrusion processes. Stakeholders must monitor evolving polymer recycling mandates and carbon border adjustment mechanisms to secure long-term market access across regulated jurisdictions.
Market Dynamics
Polymer feedstock volatility and regulatory pressure on virgin plastics are compressing net manufacturer margins while forcing rapid formulation pivots toward circular material streams.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon coolants in protected cultivation accelerates passive climate control via shade nets in Spanish and Italian greenhouse belts.
- Shandong Province cluster density:China's intensive horticulture concentration generates bulk procurement volumes that sustain dedicated extrusion lines and specialized distributor networks.
- High-value crop expansion:Avocado and blueberry cultivation in Peru and Chile drives anti-hail net installations where per-hectare crop value justifies premium protection spend.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing swings directly compress polyethylene resin margins for net extruders without long-term supply contracts.
- REACH compliance burden:ECHA substance restrictions on legacy plasticizers force complete formulation overhauls, extending R&D timelines and certification costs.
- Mechanical hail suppression:Cloud seeding and anti-hail rocket systems in Georgia and Azerbaijan compete for farmer protection budgets in stone fruit regions.
Strategic Opportunities
- India's PLI scheme for technical textiles:Production-linked incentives for specialty fiber manufacturing attract net producers to Gujarat and Tamil Nadu manufacturing zones.
- IoT-integrated climate monitoring:Sensor-embedded shade nets enabling real-time humidity and light adjustment command pricing premiums in Dutch high-tech greenhouses.
- Recyclable mono-material designs:Single-polymer constructions compatible with existing PE film recycling streams unlock circular economy positioning in German retail channels.
Industry Challenges
- UV stabilization formulation expertise:Shortage of polymer chemists experienced in tropical climate stabilization creates bottlenecks for Southeast Asian market entry.
- Multi-jurisdiction certification overlap:Divergent testing protocols between ECHA REACH, China's GB standards, and USDA biobased labeling fragment compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agriculture Nets Market |
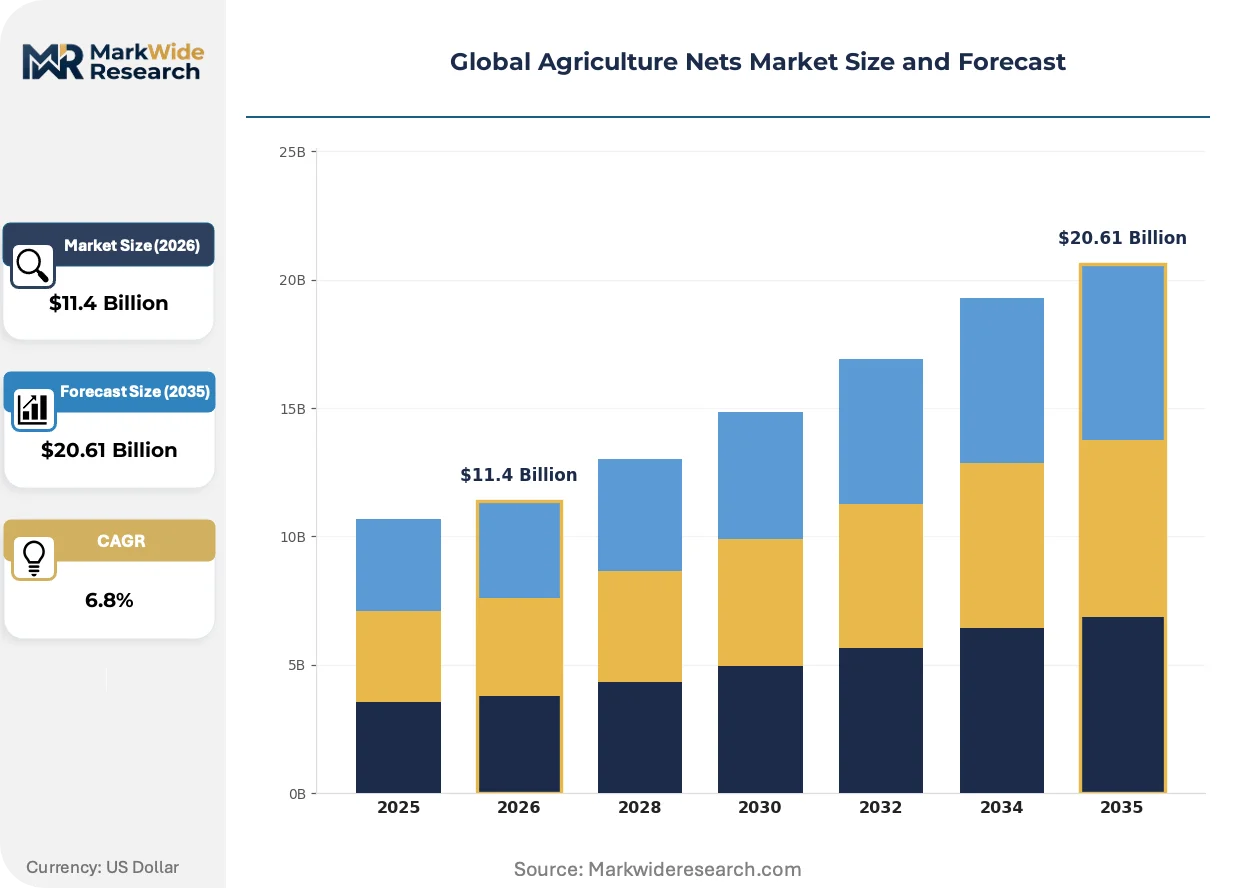
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shade Nets, Insect Nets, Bird Protection Nets, Windbreak Nets, Anti-hail Nets Material: Polyethylene, Nylon, Polyester, Polypropylene, PVC-Coated Fibers Application: Greenhouse Cultivation, Crop Protection, Livestock Shelter, Soil Erosion Control, Aquaculture Farming End User: Commercial Farms, Nurseries, Agricultural Cooperatives, Research Institutions |
| Companies Covered | Ginegar Plastic Products Ltd., Berry Global Inc., Garware Technical Fibres Limited, Thrace Group, Belton Industries, Inc., Diatex, Arrigoni S.p.A, SRF Limited, Polysack Plastic Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agriculture Nets Market Shifts & Advancements
Material science advances and digital integration are redefining net functionality beyond passive barriers toward active crop management systems.
Mono-material high-density polyethylene constructions with enhanced recyclability are overtaking multi-layer composite designs in European commercial greenhouse procurement. Dutch and Belgian growers now specify pure-stream compatible nets to satisfy retailer circularity audits and avoid polymer separation costs at end-of-life.
China's Ministry of Ecology and Environment dual carbon goals are forcing domestic extruders to adopt electric melting and renewable-powered production lines. Shandong-based manufacturers face emissions intensity caps that favor smaller-scale, distributed extrusion over centralized petrochemical-integrated facilities.
Direct contracting between greenhouse operators and specialized net fabricators is compressing traditional agricultural distributor margins in Israel and Spain. Large Mediterranean cooperatives now negotiate custom mesh specifications and installation services separately from generic input suppliers.
Global Agriculture Nets Market Segmentation
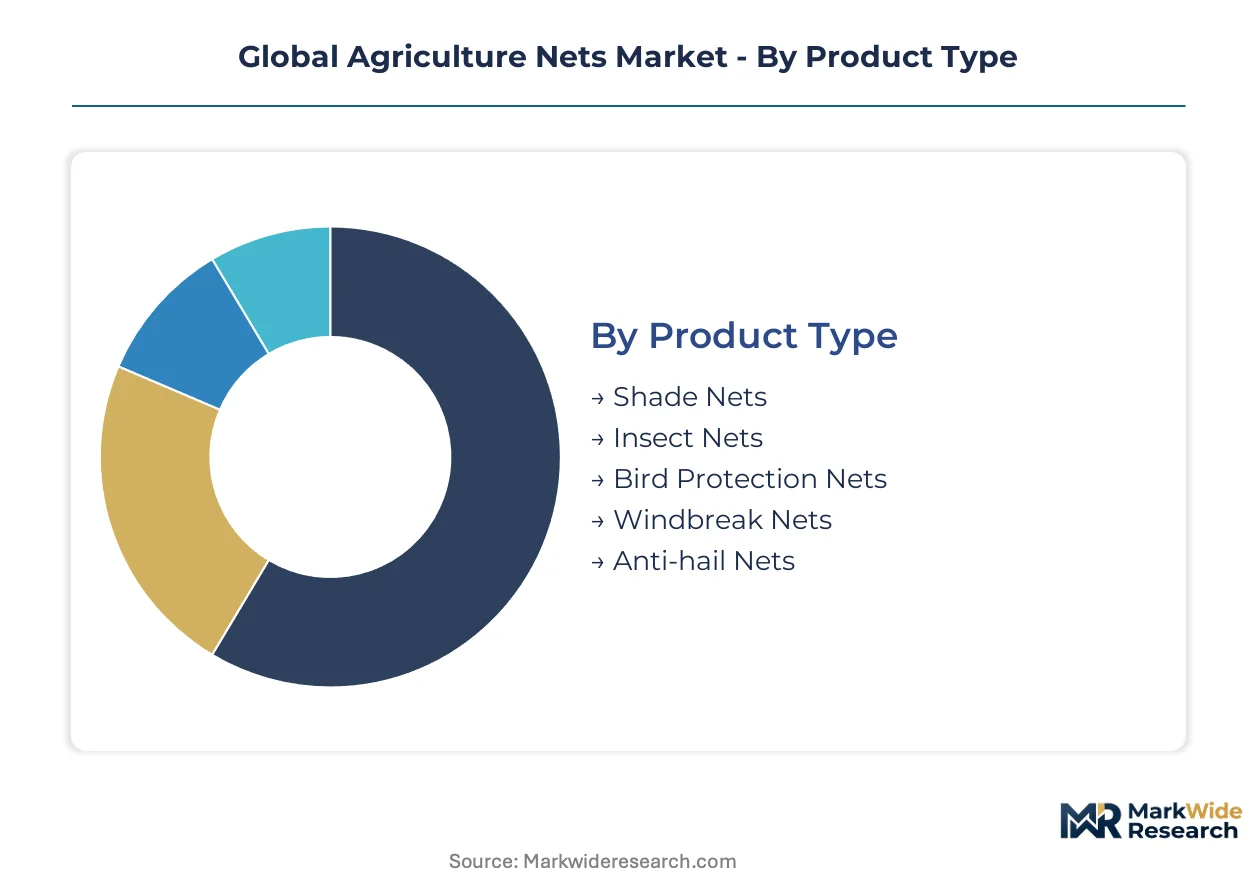
Agriculture nets serve heterogeneous operational requirements spanning passive climate modulation to active pest exclusion. Mesh specifications, polymer selection, and installation geometry vary sharply across protected cultivation versus open-field deployment, driving distinct procurement patterns among greenhouse operators and fruit cooperatives.
Product Type:
Customization intensity spans from commodity shade cloth to engineered anti-hail systems with terrain-specific anchoring protocols.
- Shade Nets:Woven or knitted HDPE fabrics with shade factors from 30% to 90% block photosynthetically active radiation while permitting air circulation. Dutch greenhouse operators in Westland municipality specify custom spectral filtering variants to optimize tomato and pepper yields under supplemental LED regimes.
- Insect Nets:Fine mesh barriers with apertures below 0.6 millimeters physically exclude thrips, whiteflies, and aphid vectors. Spanish Almería greenhouse complexes deploy these nets under EU sustainable use directive pressure to reduce pesticide dependency in pepper and cucumber export production.
- Bird Protection Nets:Lightweight polyethylene grids prevent avian damage in vineyard and orchard applications.
- Windbreak Nets:Permeable barriers reduce wind velocity to protect delicate crop structures and reduce evapotranspiration stress.
- Anti-hail Nets:High-tenacity monofilament constructions dissipate hailstone kinetic energy across Chilean Central Valley pome fruit operations where crop insurance premiums justify capital-intensive protection infrastructure.
Leading the category by volume: Shade Nets. Expanding most quickly: Insect Nets.
Material:
Cost tier stratification separates commodity polyethylene from specialized formulations commanding formulation premiums.
- Polyethylene:UV-stabilized high-density and linear low-density grades dominate commercial procurement due to favorable strength-to-weight ratios and established recycling infrastructure. Israeli manufacturers leverage captive polymer extrusion to control input costs across Mediterranean export markets.
- Nylon:Polyamide constructions offer superior abrasion resistance and elastic recovery for tensioned installations. Italian vineyard netting in Piedmont and Tuscany utilizes nylon for durability across multiple harvest cycles.
- Polyester:Higher modulus fibers maintain dimensional stability under mechanical load.
- Polypropylene:Lower density alternative for temporary seasonal applications.
- PVC-Coated Fibers:Legacy constructions face ECHA REACH substance restrictions on phthalate plasticizers and heavy-metal stabilizers, accelerating displacement by uncoated polyethylene alternatives in regulated European markets.
Dominant by procurement tonnage: Polyethylene. Facing steepest regulatory pressure: PVC-Coated Fibers.
Application:
Volume concentration clusters in protected cultivation while emerging uses diversify end-market exposure.
- Greenhouse Cultivation:Integrated netting systems for climate modulation, pest exclusion, and structural protection. China's Shandong province horticulture belt generates concentrated demand for multi-functional net installations serving year-round vegetable production.
- Crop Protection:Open-field deployment against hail, wind, and avian predation. Peruvian Ica Valley blueberry operations install anti-hail infrastructure to secure export-grade fruit quality for North American winter markets.
- Livestock Shelter:Shade and wind protection for intensive animal husbandry operations.
- Soil Erosion Control:Geotextile netting stabilizes slopes and retains topsoil in vulnerable watersheds.
- Aquaculture Farming:Predator exclusion and debris filtration for coastal and inland fish farming systems.
Greatest installed base: Greenhouse Cultivation. Gaining share fastest: Crop Protection.
End User:
Customer scale determines specification complexity and service bundling requirements.
- Commercial Farms:Large-scale operations with dedicated procurement teams negotiating custom mesh specifications and installation services. Spanish Murcian tomato cooperatives contract directly with specialized fabricators, bypassing traditional agricultural input distributors.
- Nurseries:Propagation-focused operations requiring precise microclimate control for juvenile plant stock.
- Agricultural Cooperatives:Pooled purchasing power enables collective negotiation of standardized net specifications across member holdings.
- Research Institutions:Specialized requirements for controlled environment agriculture trials and breeding programs.
Primary demand source: Commercial Farms. Procurement sophistication climbing fastest: Agricultural Cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong province concentrates the world's densest horticulture net procurement, while Mediterranean and South American fruit belts drive premium anti-hail installations. Regulatory divergence across ECHA REACH, China's MEE dual carbon goals, and India's PLI scheme is fragmenting compliance pathways for multinational suppliers.
China
Shandong province's greenhouse clusters generate bulk polyethylene net demand for year-round vegetable cultivation. The Ministry of Ecology and Environment enforces dual carbon goals that pressure extruders to adopt electric melting and renewable-powered production lines. Weifang and Qingdao host distributed manufacturing zones where smaller-scale facilities outcompete centralized petrochemical-integrated plants on emissions intensity.
Spain
Almería's greenhouse complexes deploy insect nets under EU sustainable use directive pressure to reduce pesticide dependency in pepper and cucumber exports. The F-Gas Regulation accelerates passive climate control adoption via shade nets across Murcian tomato cooperatives. Valencia and Catalonia concentrate anti-hail infrastructure investment where crop insurance premiums justify capital-intensive protection.
Israel
Advanced greenhouse operators in the Arava and Jordan Valley regions specify custom spectral filtering shade nets for optimized tomato and pepper yields. The national regulator enforces stringent UV-stabilization standards for tropical climate durability. Netanya-based fabricators leverage backward integration from polymer extrusion to finished products, sustaining margin control across Mediterranean export markets.
India
Gujarat and Tamil Nadu manufacturing zones attract net producers through the PLI scheme for technical textiles. SRF Limited and Garware Technical Fibres anchor domestic supply with specialized UV-stabilized formulations for tropical agriculture. Maharashtra's Nashik district vineyards and Karnataka's grape belts drive bird protection and hail net demand where per-hectare crop value justifies premium spend.
Chile
Central Valley pome fruit and blueberry operations install high-tenacity anti-hail nets to secure export-grade fruit quality for North American winter markets. The O'Higgins and Maule regions concentrate protected cultivation infrastructure where crop value density supports capital-intensive protection systems. Domestic distributors face margin compression as large cooperatives negotiate directly with specialized fabricators for custom mesh specifications.
Global Agriculture Nets Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated producers controlling premium greenhouse specifications while commodity extruders serve open-field crop protection. The vendor base organizes around three archetypes: captive polymer producers with backward integration into resin supply, specialized fabricators focused on custom mesh engineering, and regional distributors with installation service bundling. Dominant competitive moves include capacity expansion in India's PLI-eligible zones and strategic partnerships between European net producers and Dutch greenhouse technology integrators.
Among Israel-based specialists, Ginegar Plastic Products Ltd. exemplifies the vertically integrated archetype with control from polymer extrusion through finished shade net production. Berry Global Inc. represents scale-driven North American positioning across agricultural film and netting categories. Garware Technical Fibres Limited anchors Indian subcontinent supply with technical fiber specialization for tropical climate applications. These three occupy distinct competitive positions without direct segment overlap, reducing price-based confrontation.
| Leading Market Players |
|---|
| Ginegar Plastic Products Ltd. |
| Berry Global Inc. |
| Garware Technical Fibres Limited |
| Thrace Group |
| Belton Industries, Inc. |
| Diatex |
| Arrigoni S.p.A |
| SRF Limited |
| Polysack Plastic Industries Ltd. |
| Others |
Supply & Pricing Matrix
Backward integration into polymer extrusion anchors both supply security and pricing power for Israeli and Indian net manufacturers facing volatile ethylene feedstock markets. Captive resin production insulates Ginegar and Garware Technical Fibres from naphtha-linked margin swings while enabling custom UV-stabilization formulations that command specification premiums in Mediterranean and tropical export markets.
Pricing Analysis
Volume concentrates in commodity shade nets while margin pools accrue to engineered anti-hail and insect net specifications. Three-tier pricing structure across premium, standard, and economy levels separates custom spectral-filtering greenhouse installations from bulk Shandong procurement. Price differentiation hinges on UV-stabilization grade and REACH certification status. Cost compression in standard-grade polyethylene is intensifying because China's MEE emissions caps raise electricity-intensive extrusion costs. Agricultural cooperatives in Spain and Chile exhibit highest price sensitivity, while Dutch high-tech greenhouse operators prioritize performance over unit cost.
Supply Chain Analysis
Container freight volatility from Asia to Mediterranean ports directly shapes landed cost competitiveness for Chinese and Indian exporters. Raw material sourcing concentrates in Saudi Arabia, South Korea, and Singapore for virgin polyethylene resin, with recycled feedstock emerging from German and Dutch collection streams. The supply chain rests on naphtha-cracker output tied to crude oil benchmarks, creating margin vulnerability during petrochemical cycle downturns. Single-source vulnerability concentrates in Shandong-based weaving equipment suppliers. Distribution runs through specialized agricultural input distributors in Israel and Spain, though direct contracting is compressing their role.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as polymer feedstock volatility and REACH compliance costs reward control over resin formulation and extrusion. Players capturing upstream polymer production or downstream installation services are consolidating margin pools that fragment among pure-play fabricators.
For Market Incumbents: Acquire tropical-climate UV-stabilization formulation expertise to defend Southeast Asian market access against emerging Indian competitors. Secure long-term ethylene supply contracts or captive cracker relationships to insulate margin from naphtha volatility. Invest in mono-material recyclable designs to preempt E circularity mandates and capture Dutch retailer specification premiums. For New Entrants and Emerging Players: Enter via India's PLI-eligible technical textile zones in Gujarat and Tamil Nadu, where production-linked incentives offset capital intensity for extrusion capacity. Target Chilean and Peruvian anti-hail net installations where per-hectare crop value justifies premium pricing and direct cooperative contracting bypasses established distributor relationships. Lead with IoT-embedded climate monitoring nets to differentiate from commodity shade cloth suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to agricultural film conglomerates seeking greenhouse technology integration, with IPO viability contingent on demonstrating circular material streams. Acquisition targets should display captive polymer extrusion, REACH-compliant formulation libraries, or installed base in high-value crop protection segments. Watch for inflection when China's MEE enforcement accelerates domestic capacity consolidation, creating distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Ginegar's captive resin supply insulates margin from naphtha volatility in Mediterranean markets. |
| Mono-Material Recyclable Design Certification | Pure-stream PE constructions unlock Dutch retailer circularity audits and avoid polymer separation costs. |
| IoT-Enabled Climate Monitoring Net Deployment | Sensor-embedded shade nets command pricing premiums in Westland municipality high-tech greenhouses. |
| PLI Zone Manufacturing Capacity Buildout | India's technical textile incentives attract extrusion investment to Gujarat and Tamil Nadu. |
| Direct Cooperative Contracting Model | Spanish Murcian tomato cooperatives bypass distributors to negotiate custom mesh specifications directly. |
Research Methodology
Document review covered customs trade data for polyethylene net exports, ECHA REACH substance restriction filings, and Chinese MEE emissions intensity disclosures, complemented by interviews with greenhouse operations managers, agricultural cooperative procurement leads, polymer extrusion plant engineers, and specialized net fabricator technical directors. Secondary validation drew from SEC filings of listed agricultural film producers, Israeli and Indian technical textile association capacity surveys, and Dutch greenhouse technology integrator procurement specifications. Bottom-up demand modeling triangulated against top-down polymer consumption estimates.
Segment-level value and volume trajectories emerged from disaggregating procurement patterns across shade, insect, and anti-hail net categories, with mesh specification, polymer grade, and installation geometry serving as core segmentation dimensions. CAGRs were derived from curve-fitting historical polyethylene resin price elasticities against observed net procurement volumes. Industry-specific inputs included Shandong province greenhouse cluster expansion rates, EU F-Gas Regulation implementation timelines, and India's PLI scheme disbursement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crude oil price spikes, abrupt REACH substance bans, or mechanical hail suppression technology breakthroughs in stone fruit regions. Forecasts reflect assumptions about regulatory enforcement continuity, polymer recycling infrastructure buildout, and cooperative purchasing consolidation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Horticulture Film Market