
 Biodegradable Mulch Film Market | 2026-2036
Biodegradable Mulch Film Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Mulch Film Market Analysis
The price-performance gap between premium certified compostable films and commodity-grade starch blends is hardening as buyers face sharper trade-offs between soil clearance speed and per-acre cost. BASF SE leverages its polymer chemistry depth to sustain higher-margin PBAT formulations, while Novamont anchors European supply through integrated biorefinery operations in Italy. Kingfa Science & Technology competes on manufacturing scale from its base in China, extending cost advantages across Asia-Pacific distribution channels.
Biodegradable mulch film comprises soil-degradable polymer sheets, typically 10–50 microns thick, engineered to suppress weeds, retain soil moisture, and thermally regulate crop beds before fragmenting into microbially digestible residues within a single growing season. Starch-based formulations currently dominate volume shipments due to lower raw material costs, though PBAT blends command premium positioning where complete biodegradation within 180 days is contractually specified. Agricultural crop applications generate the largest revenue pool, while greenhouse deployment represents the fastest-expanding segment as controlled-environment operators seek to eliminate plastic retrieval labor.
The EU's REACH framework and F-Gas Regulation constrain conventional polyethylene mulch circulation, while the USDA's BioPreferred program and state-level organics standards in California shape North American procurement criteria. China's GB standards for degradable plastics, administered by SAMR, mandate specific biodegradation thresholds that filter import eligibility. Stakeholders must monitor evolving compostability certification requirements across multiple jurisdictions to avoid product disqualification at the tender stage.
Market Dynamics
The EU's F-Gas Regulation and Green Deal frameworks are compressing disposal pathways for conventional polyethylene mulch, redirecting procurement budgets toward certified soil-biodegradable alternatives and rewiring competitive advantage around polymer chemistry depth.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on conventional plastic mulch disposal in Spain's Almería and Murcia horticulture belts are accelerating contract specifications for soil-biodegradable films.
- Controlled-environment agriculture:Greenhouse operators across commercial vegetable farming are eliminating plastic retrieval labor through single-season biodegradable deployment.
- PBAT blend formulations:Advanced polymer chemistry enabling complete soil clearance within 180 days is commanding premium positioning in intensive crop applications.
Market Restraints
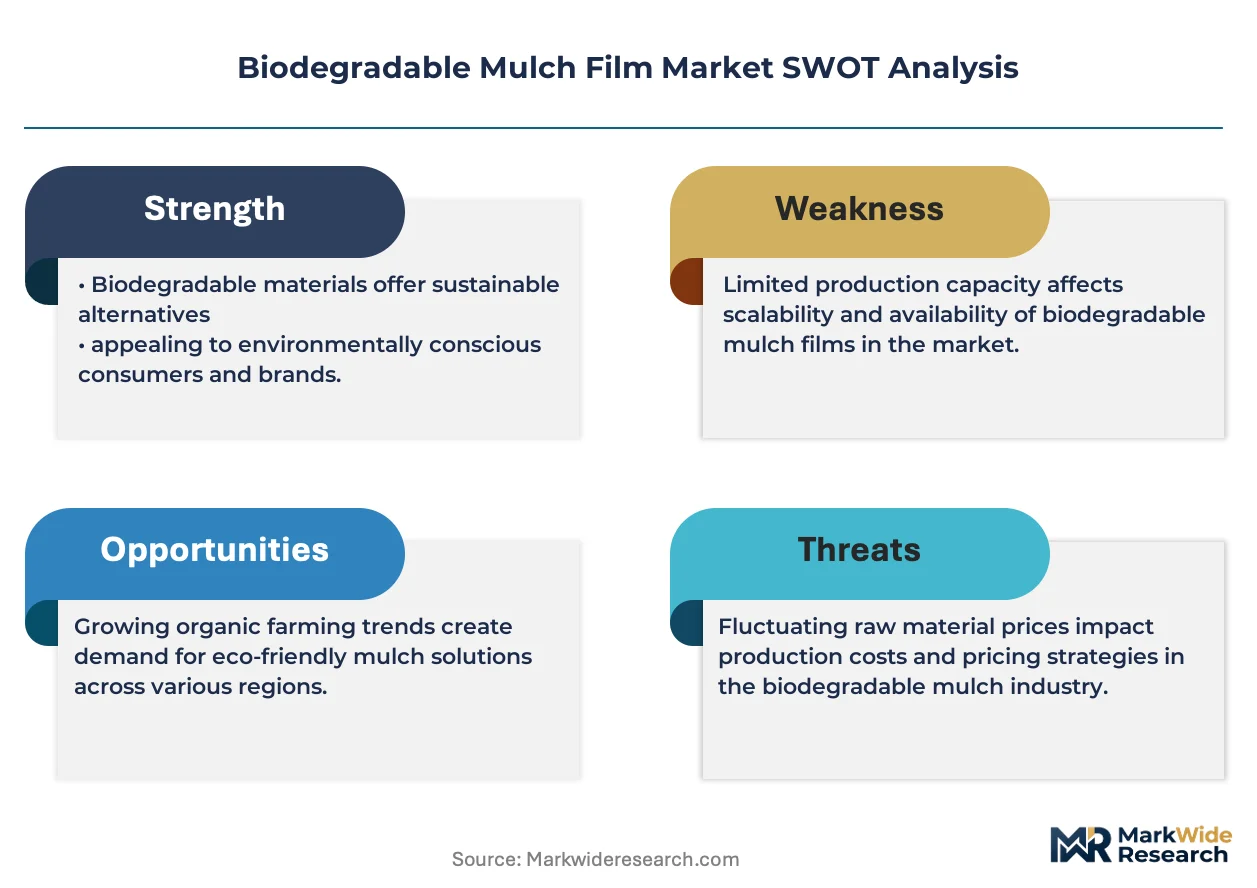
- Raw material cost volatility:Starch feedstock prices fluctuate with agricultural commodity cycles, compressing margins on volume-grade formulations.
- Supply concentration risk:Integrated biorefinery operations in Italy anchor European PBAT supply, creating geographic single-point vulnerability.
- Technical limitation:Degradation rate variability across soil pH and moisture conditions limits contractual performance guarantees in temperate climates.
Strategic Opportunities
- Underpenetrated geography:China's GB standards for degradable plastics, administered by SAMR, are filtering import eligibility and creating captive demand for domestic manufacturers.
- Emerging application:Orchard and vineyard permanent crop systems represent untapped demand as operators seek to eliminate perennial plastic accumulation.
- Technology convergence:Integration of precision agriculture sensors with biodegradable film deployment is enabling variable-rate mulching in row-crop operations.
Industry Challenges
- Certification timeline compression:Multiple jurisdictions' evolving compostability standards require parallel testing protocols, extending product qualification cycles.
- Soil microbiology expertise gap:Agronomists capable of predicting field-specific degradation performance remain scarce across commercial extension services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Mulch Film Market |
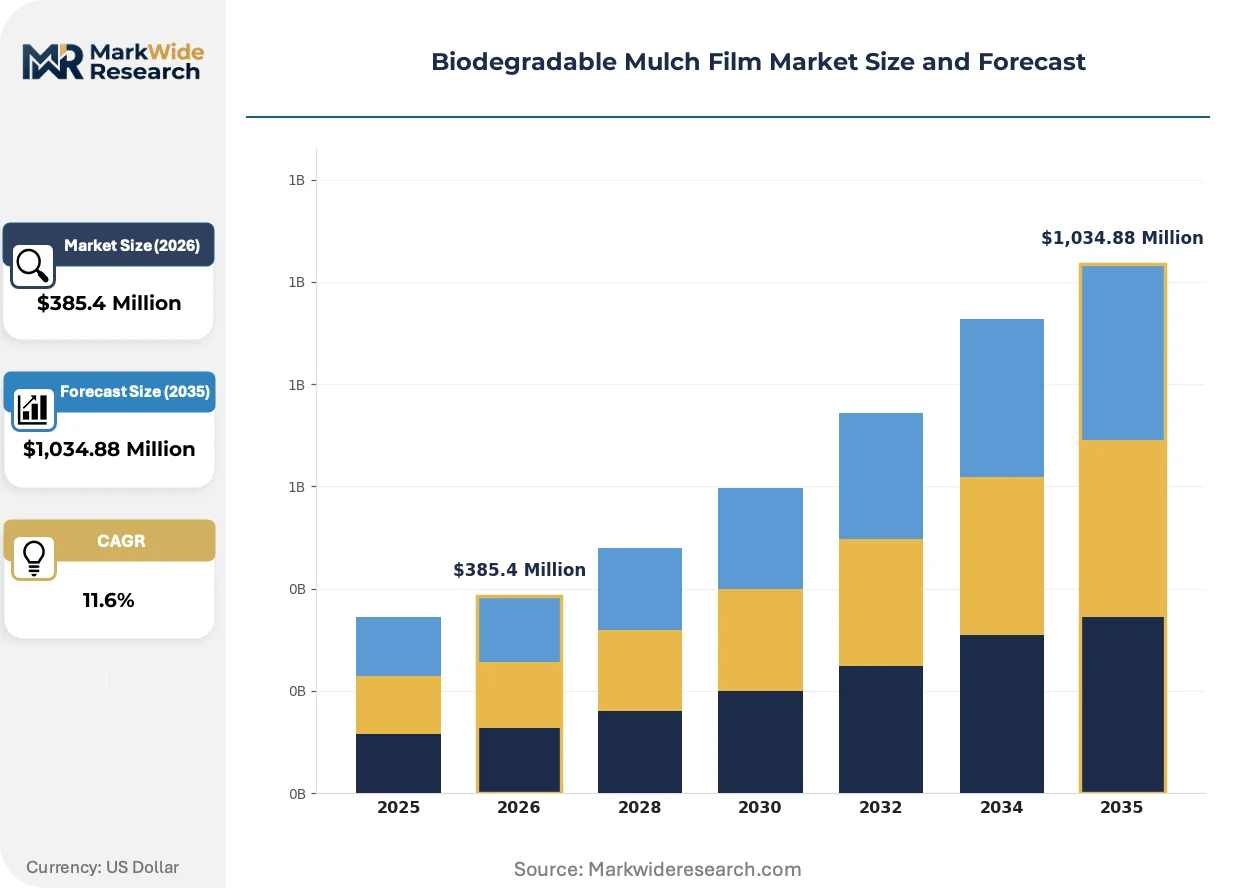
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,034.88 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PBAT, Starch-Based, Others Application: Agricultural Crops, Horticultural Plants, Landscaping, Greenhouse End User: Farmers, Nurseries, Garden Centers, Landscape Contractors Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | BioBag International, Armando Alvarez Group, BASF SE, Mondi plc, Organix Solutions, Novamont, Kingfa Science & Technology, Toray Industries, RKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Mulch Film Market Emerging Trajectories
Active reformulation of polymer architectures and tightening regulatory thresholds are compressing product lifecycles and rewarding manufacturers with integrated biopolymer production capabilities.
Multilayer coextrusion technology is integrating PBAT with lignocellulosic fillers to balance mechanical durability during the growing season with accelerated microbial digestion post-harvest. Large-scale vegetable producers in California's Central Valley are piloting these structures for high-value row crops. This convergence is integrating performance specifications previously segmented across premium and standard tiers.
REACH framework amendments are extending substance restriction lists to cover persistent microplastic residues from incomplete mulch degradation. Formulators serving the European market are reformulating additive packages to preempt authorization withdrawals. Spain's intensive horticulture sector is absorbing compliance costs fastest due to proximity to regulatory enforcement capacity.
Direct contracting between film manufacturers and organized grower cooperatives is displacing distributor-mediated procurement in high-volume vegetable production regions. This channel compression eliminates margin stacking and enables customized formulation development. The pattern is most visible in Italy's Po Valley tomato processing belt and the Netherlands' greenhouse clusters.
Biodegradable Mulch Film Market Segmentation
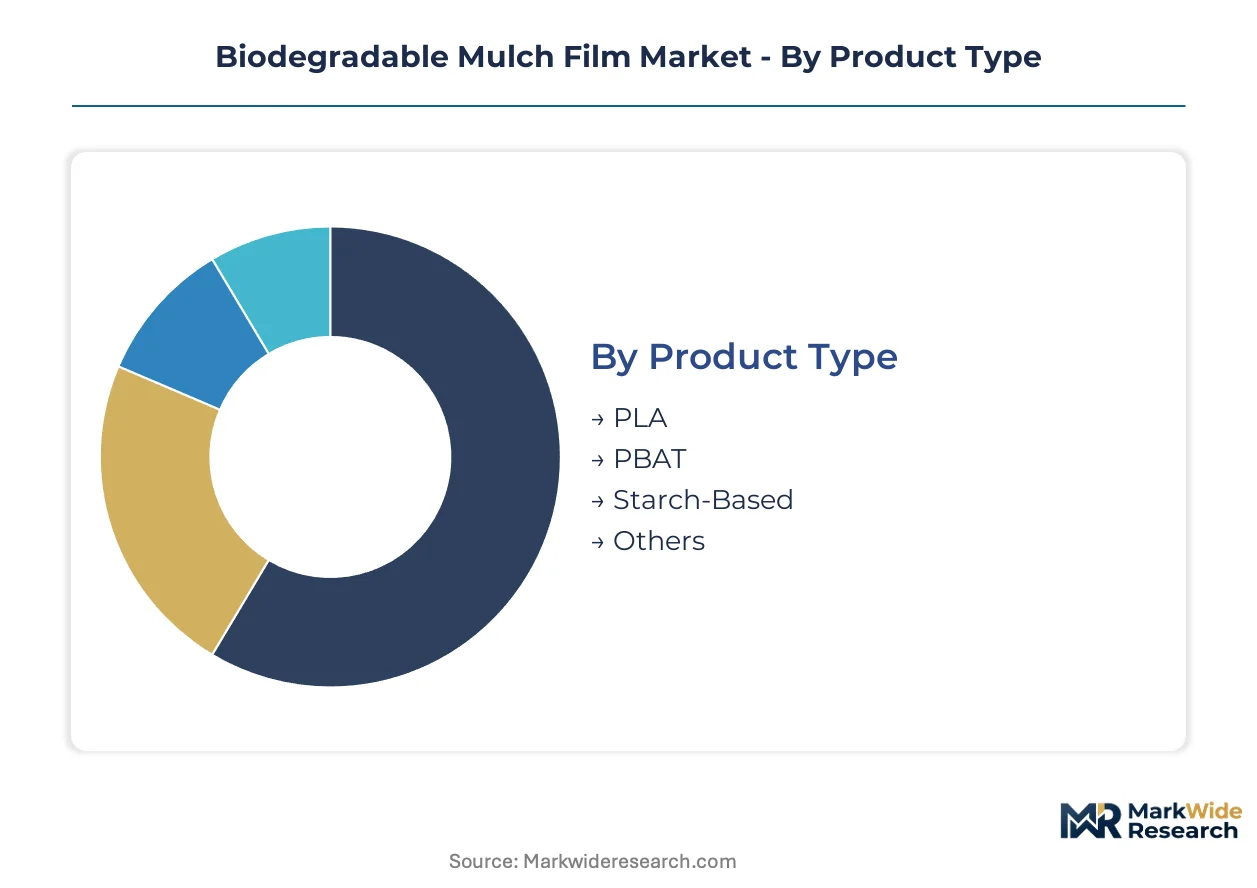
Segmentation in the biodegradable mulch film market determines polymer selection, pricing tiers, and degradation performance guarantees. Buyers navigate trade-offs between soil clearance speed, mechanical durability, and per-acre material costs across distinct application environments.
Product Type:
Upgrade cycles from commodity starch blends to certified compostable polymers are compressing as EU F-Gas Regulation enforcement tightens disposal pathways for conventional polyethylene alternatives.
- PBAT:Polybutylene adipate terephthalate delivers complete soil biodegradation within 180 days through ester bond hydrolysis followed by microbial mineralization. Spain's Almería horticulture belt specifies PBAT blends for high-value greenhouse vegetables where rapid field clearance eliminates retrieval labor costs.
- Starch-Based:Thermoplastic starch formulations leverage abundant agricultural feedstocks to achieve the lowest per-kilogram material cost. Volume demand concentrates in open-field vegetable operations across China's Shandong and Hebei provinces where GB standards mandate degradability thresholds.
- PLA:Polylactic acid requires industrial composting infrastructure for complete breakdown, limiting deployment to regions with centralized collection systems.
- Others:PBS and PHA biopolymers serve niche applications requiring specific degradation rate profiles or marine biodegradability certification.
Volume placements concentrate in Starch-Based formulations; the faster expansion belongs to PBAT.
Application:
Cost tier differentiation separates premium greenhouse deployment from economy-grade open-field coverage based on labor substitution value and crop price realization.
- Greenhouse:Controlled-environment operators eliminate plastic retrieval labor entirely through single-season biodegradable deployment. The Netherlands' Westland cluster and Italy's Po Valley tomato belt absorb premium pricing for films integrating PBAT with lignocellulosic fillers.
- Agricultural Crops:Large-scale row-crop producers in California's Central Valley pilot multilayer coextrusion structures for high-value vegetables, balancing mechanical durability with post-harvest microbial digestion.
- Horticultural Plants:Nursery operations prioritize weed suppression and moisture retention in container stock production.
- Landscaping:Municipal and commercial landscape contractors specify slower-degrading formulations for ornamental bed establishment.
Revenue concentration sits with Agricultural Crops; Greenhouse applications are climbing the fastest as controlled-environment agriculture expands.
End User:
Customer type determines procurement channel structure, with organized cooperatives displacing distributor-mediated supply in high-volume production regions.
- Farmers:Commercial vegetable producers drive specification development through direct contracting with film manufacturers, compressing margin stacking in Italy's tomato processing belt and Spain's Murcia horticulture zone.
- Nurseries:Container stock operators require consistent degradation rates across variable substrate pH conditions.
- Garden Centers:Retail-oriented demand favors pre-cut sheet formats for consumer garden applications.
- Landscape Contractors:Commercial landscaping specifies thicker gauges for erosion control and perennial bed establishment.
Procurement volume aggregates through Farmers; Nurseries represent the steepest expansion trajectory as permanent crop systems adopt biodegradable alternatives.
Thickness:
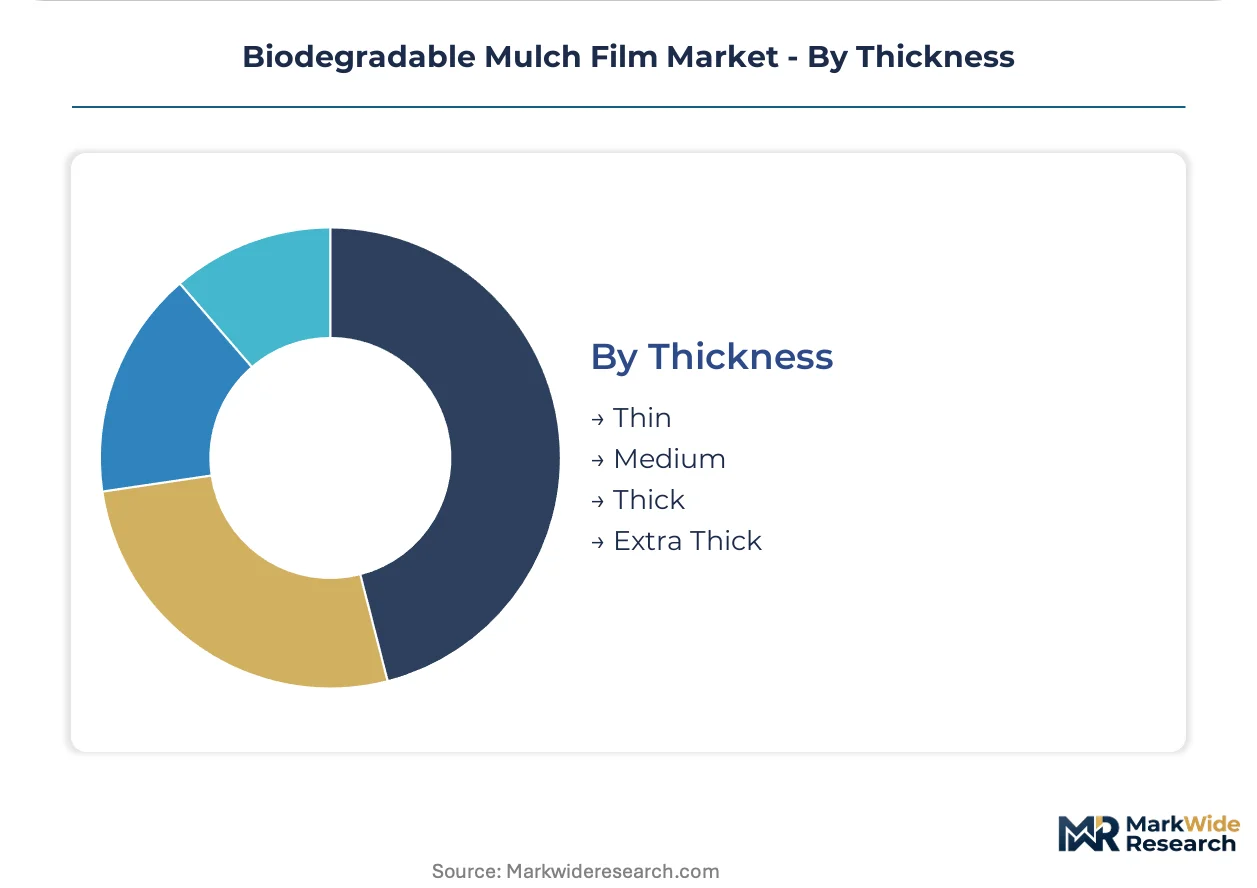
Supply concentration in medium-gauge extrusion capacity shapes availability for standard vegetable production while thin and thick variants serve specialized mechanical requirements.
- Medium:15-25 micron films balance puncture resistance with material economy for standard row-crop applications. China's Kingfa Science & Technology anchors manufacturing scale for this specification across Asia-Pacific distribution channels.
- Thin:10-15 micron gauges reduce per-acre material cost for short-season crops with minimal mechanical stress exposure.
- Thick:25-40 micron structures serve high-wind environments and mechanical cultivation systems requiring enhanced tear resistance.
- Extra Thick:40-50 micron specifications target orchard and vineyard permanent crop systems where multi-season durability intersects with eventual biodegradation requirements.
Production gravity centers on Medium gauges; Extra Thick formulations are gaining share fastest as orchard operators seek to eliminate perennial plastic accumulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almería's greenhouse belt drives European specification development for soil-biodegradable films, while China's Shandong province anchors Asia-Pacific manufacturing scale. Regulatory enforcement intensity and feedstock proximity are rewiring regional competitive advantage.
Spain
Intensive horticulture operators in Murcia and Almería specify PBAT blends for high-value greenhouse vegetables. The EU F-Gas Regulation tightens disposal pathways for conventional polyethylene, redirecting procurement budgets toward certified soil-biodegradable alternatives. Field clearance speed determines contract awards as labor costs rise.
China
GB standards administered by SAMR mandate specific biodegradation thresholds that filter import eligibility. Kingfa Science & Technology leverages manufacturing scale from its Guangdong base to serve Shandong and Hebei vegetable belts. Domestic producers capture captive demand created by technical barrier compliance.
Italy
Po Valley tomato processors contract directly with film manufacturers, eliminating distributor margin stacking. Novamont's integrated biorefinery operations in Terni anchor European PBAT supply. Direct channel compression enables customized formulation development for high-volume cooperatives.
United States
California's Central Valley pilots multilayer coextrusion structures for high-value row crops. The USDA BioPreferred program and state-level organics standards shape procurement criteria. Large-scale vegetable producers absorb premium pricing for rapid field clearance.
Netherlands
Westland greenhouse clusters eliminate plastic retrieval labor through single-season biodegradable deployment. REACH framework amendments extend substance restrictions to persistent microplastic residues. Operators specify lignocellulosic filler integration for mechanical durability.
Biodegradable Mulch Film Market Vendor Landscape
Premium-margin players sit above commodity-margin players across polymer chemistry depth and certification tier. The vendor base stratifies into integrated biopolymer producers, specialized compounders, and regional extrusion specialists. Three archetypes dominate: European chemical conglomerates with captive resin production, Asian scale manufacturers leveraging feedstock proximity, and agricultural film specialists with grower-direct channel relationships. Capacity expansion and direct contracting with organized cooperatives constitute the dominant competitive moves.
Within the integrated biopolymer tier, BASF SE and Novamont exemplify European chemical depth through captive PBAT formulation capabilities. Kingfa Science & Technology represents Asian manufacturing scale, leveraging Guangdong-based production to serve domestic vegetable belts and export channels. These three anchors illustrate how regional feedstock access and regulatory proximity determine margin capture.
| Leading Market Players |
|---|
| BioBag International |
| Armando Alvarez Group |
| BASF SE |
| Mondi plc |
| Organix Solutions |
| Novamont |
| Kingfa Science & Technology |
| Toray Industries |
| RKW Group |
| Others |
Supply Flow & Price Mechanics
Starch feedstock costs fluctuate with agricultural commodity cycles, transmitting volatility from corn and potato processors through to volume-grade film pricing tiers, while PBAT resin premiums reflect integrated biorefinery scarcity in Europe.
Pricing Analysis
Yield-based pricing anchors premium tiers, with greenhouse operators in Spain's Almería belt paying premiums tied to labor elimination value rather than resin cost-plus structures. Three-tier pricing separates certified compostable PBAT blends from commodity starch formulations and transitional PLA alternatives. Price differentiation rests on biodegradation speed certification and soil clearance guarantees. Cost compression in starch-based tiers is intensifying because Chinese manufacturers leverage feedstock proximity, while greenhouse operators show lowest price sensitivity due to retrieval labor substitution math.
Supply Chain Analysis
Regional distribution centers in Guangdong, Terni, and Ludwigshafen anchor hub-and-spoke patterns for Asia-Pacific, European, and North American demand clusters respectively. Manufacturing concentrates in China, Italy, and Germany, with PBAT resin production drawing from adipic acid and butanediol feedstocks. Supply chain risk centers on single-source vulnerability for European PBAT supply anchored in Novamont's Terni biorefinery. Distribution runs through direct contracting with organized grower cooperatives displacing traditional distributor layers in high-volume vegetable belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with PBAT resin production capability determining margin capture as feedstock proximity becomes the decisive upstream lever.
For Market Incumbents: Cement polymer chemistry depth through captive PBAT formulation capabilities, mirroring BASF's Ludwigshafen integration model. Expand manufacturing footprint in China's Shandong vegetable belt to counter Kingfa's domestic scale advantage. Certification investment in SAMR GB standard compliance is essential to defend position against emerging domestic Chinese compounders. For New Entrants and Emerging Players: Enter via orchard and vineyard permanent crop systems in California's Central Valley, where multi-season durability requirements create specification gaps incumbent starch specialists cannot fill. Target extra-thick gauge segments where mechanical cultivation compatibility commands premium positioning. Partner with precision agriculture sensor providers to bundle variable-rate deployment services. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap agricultural film specialists with grower-direct channel relationships in Italy's Po Valley or Spain's Murcia zone, where channel compression has already eliminated distributor margin stacking. Long-term viability hinges on biorefinery integration or backward control over adipic acid supply. Watch SAMR enforcement intensity on GB standard compliance as the inflection signal for Chinese market access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PBAT Resin | Captive supply of butanediol and adipic acid insulates margin from petrochemical volatility. |
| Direct Grower Cooperative Contracting | Eliminates distributor margin stacking in Italy's tomato processing belt and Spain's greenhouse clusters. |
| Multilayer Coextrusion Technology Investment | Integrates lignocellulosic fillers with PBAT for mechanical durability in California's Central Valley pilots. |
| SAMR GB Standard Certification Program | Filters import eligibility and creates captive demand for compliant domestic manufacturers in China. |
| Precision Agriculture Sensor Partnership | Enables variable-rate mulching bundled with biodegradable film deployment in row-crop operations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with polymer chemists at biorefinery operators, procurement leads at Spanish greenhouse cooperatives, technical agronomists at Italian tomato processors, and distribution channel managers across European agricultural supply networks. Secondary sources included ECHA REACH substance restriction updates, SAMR GB standard technical specifications, USDA BioPreferred program criteria, and customs import data for degradable plastic film classifications. Bottom-up volume estimates from extrusion capacity utilization triangulated against top-down demand aggregation from vegetable acreage coverage rates.
Data-stream reconciliation across shipment volumes, resin price indices, and acreage deployment surveys informed the analytical framework over the projection horizon. Segmentation dimensions modeled included polymer chemistry tier, application environment, thickness specification, and regional regulatory cluster. CAGRs derived from slope-log regression on normalized shipment data, stress-tested against EU F-Gas Regulation enforcement timelines and SAMR standard implementation phases. Industry-specific inputs incorporated soil microbiology degradation rate studies and greenhouse labor cost substitution elasticities.
Revisions become necessary when EU REACH amendments extend microplastic restrictions, SAMR adjusts GB biodegradation thresholds, or starch feedstock prices spike beyond historical volatility bands. Forecasts reflect assumptions about regulatory enforcement continuity and polymer formulation stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
South America Agricultural Films Market