
 Coco Coir Market | 2026-2036
Coco Coir Market Size, Share, and Industry Trends Forecast 2026-2036
Coco Coir Market Intelligence
Mechanized fiber extraction is fragmenting traditional supply chains across South Asia. Universal Coco Indonesia leverages automated washing and buffering lines to serve European horticulture buyers with consistent pH-stabilized coir pith. Lanka Coco Products anchors premium geotextile output through Sri Lankan coastal mills with direct port access to Middle Eastern erosion control projects. Fibredust LLC competes on compressed brick packaging innovation, reducing ocean freight cube by 40 percent for North American greenhouse distributors.
Coco coir comprises the fibrous mesocarp tissue surrounding coconut husks, typically containing 33-43 percent lignin and 0.25-0.50 millimeter fiber diameters after retting and defibering; manufacturers process this material into substrates, geotextiles, and mulch products that improve soil aeration and water retention in commercial agriculture. Coir pith commands the largest revenue pool due to its dominance in hydroponic tomato and pepper propagation across Dutch, Mexican, and Australian glasshouse operations. Coir geotextiles represent the fastest-expanding application segment, driven by coastal embankment projects in Bangladesh and Vietnam where biodegradable matting replaces synthetic alternatives before monsoon cycles.
EU REACH compliance and F-Gas Regulation phase-downs are redirecting peat-dependent growers toward certified coir substrates with documented heavy metal thresholds and salt content below 1.5 millisiemens per centimeter. India's BIS quality marks and export inspection protocols from the Coconut Development Board govern fiber grading for international shipment, while Indonesia's national standards authority mandates moisture caps to prevent container mold during transoceanic transit. Stakeholders must monitor evolving soil amendment labeling requirements across target jurisdictions before committing to regional distribution partnerships.
Market Dynamics
Mechanized fiber extraction in South Indian processing clusters is compressing lead times and flattening traditional supplier hierarchies, forcing established traders to reposition as quality-certification intermediaries rather than volume aggregators.
Growth Catalysts
- EU Green Deal soil health guidelines:Dutch and Spanish hydroponic operators are accelerating peat-to-coir substitution, creating certified substrate demand with documented heavy metal thresholds.
- Coir geotextile adoption:Bangladesh and Vietnam coastal embankment projects are specifying biodegradable matting for monsoon-cycle erosion control, displacing synthetic alternatives.
- Automated washing and buffering lines:Indonesian processors are achieving consistent pH stabilization, unlocking European horticulture contracts previously reserved for Sri Lankan and Indian suppliers.
Market Restraints
- Input cost volatility:Coconut husk supply fluctuates with Kerala and Tamil Nadu monsoon patterns, creating raw material uncertainty for fiber extraction mills.
- Supply concentration risk:South Indian processing clusters around Pollachi and Tiruchengode dominate export-grade coir pith, creating geographic single-point vulnerability.
- Regulatory friction:EU REACH compliance documentation requirements impose testing costs that exclude smaller Sri Lankan and Indonesian processors from premium substrate tiers.
Strategic Opportunities
- Underpenetrated Mexican glasshouse sector:Tomato and pepper propagation facilities are expanding coir substrate trials as water-stressed agriculture intensifies.
- Technology convergence:Compressed brick packaging innovation combined with automated buffering is reducing ocean freight cube and enabling direct-to-grower distribution.
- Australian horticulture expansion:Protected cropping investments in Victoria and Queensland are sourcing pH-stabilized coir pith for year-round vegetable production.
Industry Challenges
- Skill gap in mechanized grading:Traditional manual fiber sorters lack training for automated extraction line operation, constraining throughput scaling in Tamil Nadu mills.
- Certification timeline compression:BIS quality mark acquisition and Coconut Development Board export inspection protocols create 8-12 week shipment delays for new market entrants.
- Supply chain reconfiguration friction:Port congestion at Colombo and Tuticorin is forcing Middle Eastern geotextile buyers to qualify alternative Indonesian suppliers with unproven logistics reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coco Coir Market |
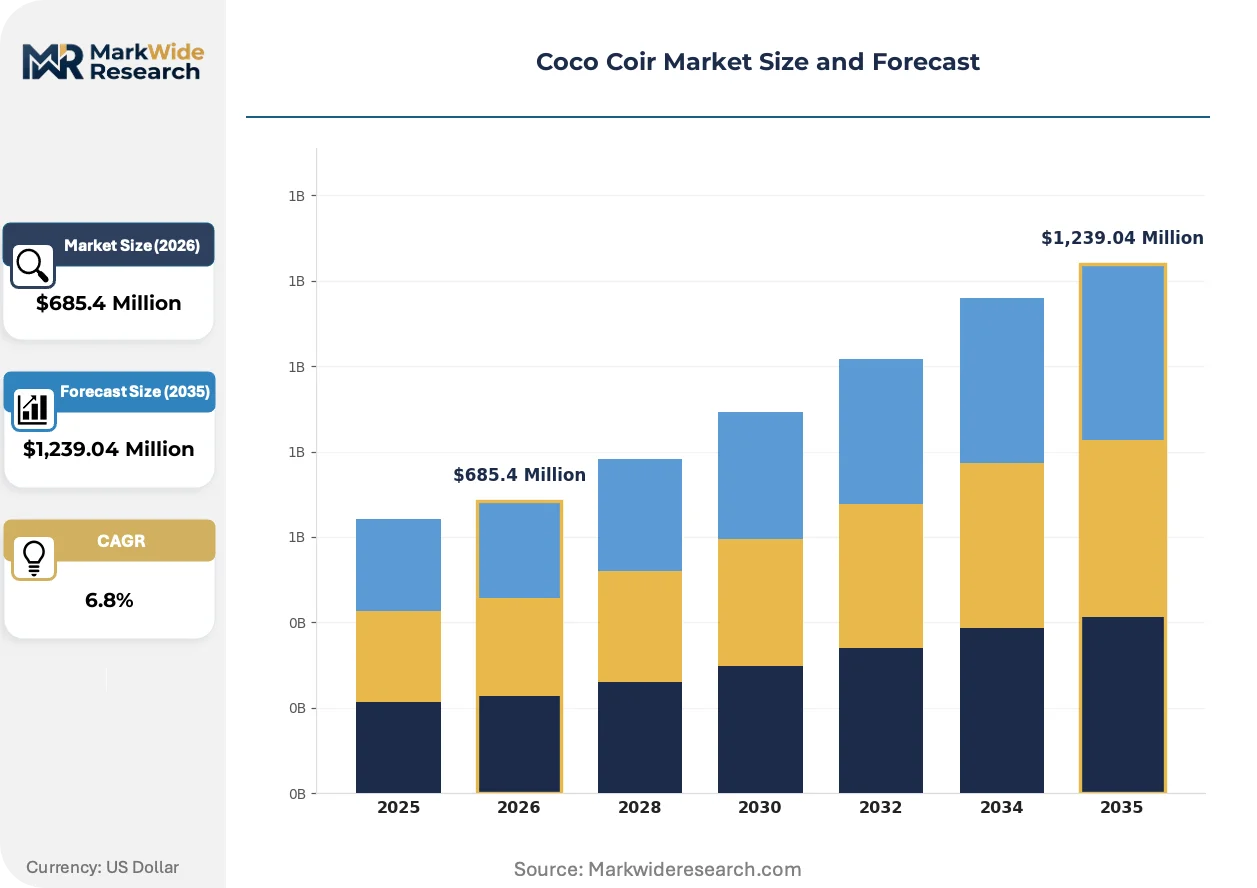
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coir Fiber, Coir Pith, Coir Geotextiles, Coir Mulch Application: Agriculture, Horticulture, Erosion Control, Soil Amendments Form: Bricks, Bales, Loose, Mats End User: Farmers, Landscapers, Garden Centers, Retailers |
| Companies Covered | Universal Coco Indonesia, Keppel Corporation, Pilipinas Ecofiber Corporation, Lima Group, Carib Agro Industries, Fibredust LLC, Bali Coco, EcoCoir Pvt. Ltd., Lanka Coco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coco Coir Market Strategic Shifts & Innovations
Processing automation and regulatory compliance convergence are redefining competitive advantage in coir substrate supply, compressing the value captured by traditional trading intermediaries.
Continuous automated washing and buffering systems are rendering obsolete batch-based manual retting operations that previously dominated South Indian export supply. Dutch hydroponic distributors now specify pH-stabilized coir pith with electrical conductivity below 1.5 millisiemens per centimeter, disqualifying traditional suppliers lacking inline quality control. This technology compression is consolidating contract allocation toward processors with captive laboratory certification capacity.
EU F-Gas Regulation phase-downs are redirecting peat-dependent greenhouse operators toward documented low-carbon substrates with verifiable supply chain footprints. The industrial consequence is mandatory heavy metal testing and salt content documentation for all substrate shipments entering Dutch, Belgian, and German horticulture markets. Spanish Almería glasshouse operations are responding fastest, requiring suppliers to pre-certify entire production lots before vessel loading.
Direct procurement from processing mills is displacing layered distributor networks that historically aggregated smallholder output across Kerala and Tamil Nadu. Large North American greenhouse operators are establishing annual volume contracts with Indonesian automated processors, bypassing traditional Colombo-based traders. This channel compression is most visible in California and Arizona protected agriculture, where distributors now function as logistics coordinators rather than price-setting intermediaries.
Coco Coir Market Segmentation
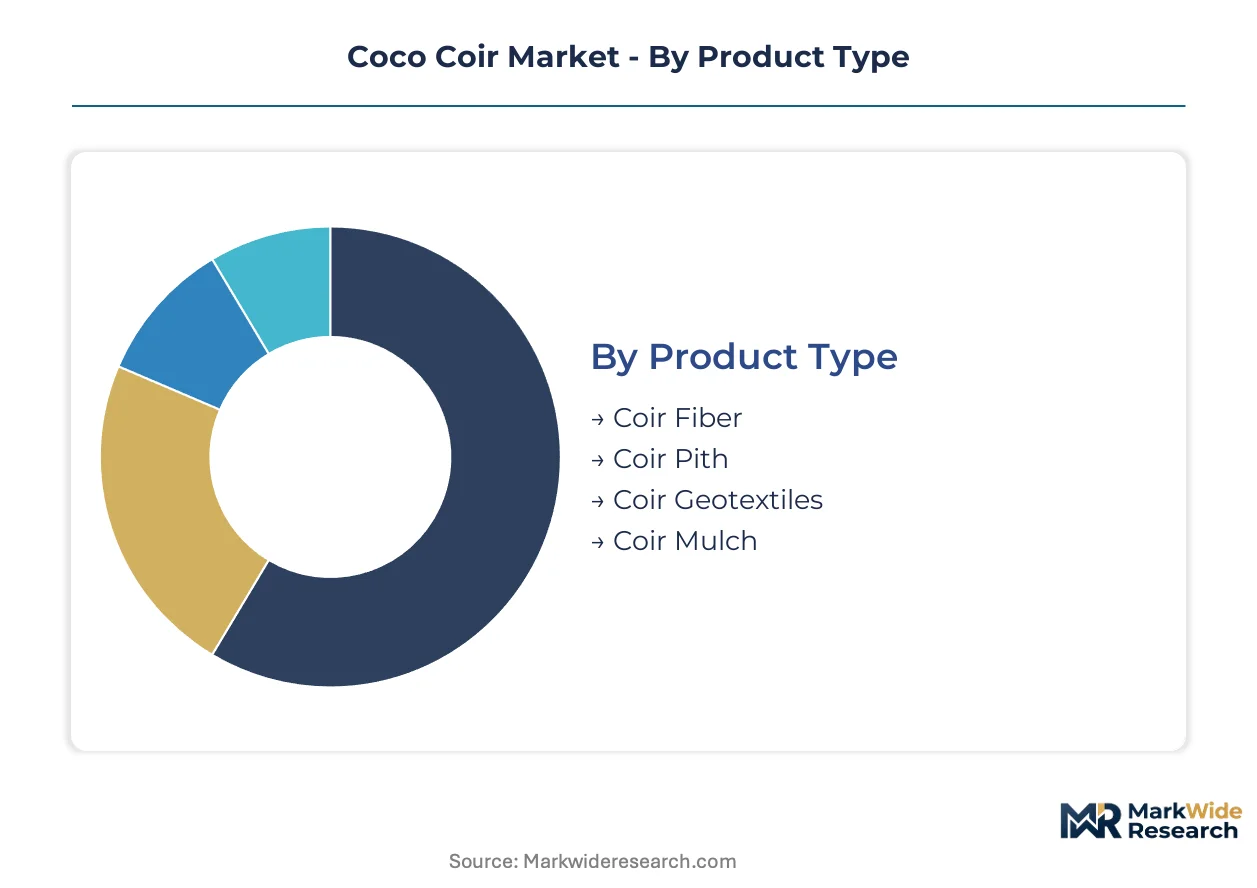
Coco coir processors configure output specifications around four intersecting dimensions: material composition determines functional performance, application context dictates certification requirements, physical form shapes logistics economics, and end-user channel determines packaging and pricing structures.
Product Type:
Material composition spans the full functional spectrum from structural reinforcement to water retention media.
- Coir Pith:Fine-grained spongy material comprising 33-43 percent lignin with exceptional water retention capacity of 8-10 times dry weight. Dutch and Spanish hydroponic greenhouse operators specify pH-stabilized grades with electrical conductivity below 1.5 millisiemens per centimeter for tomato and pepper propagation substrates.
- Coir Geotextiles:Woven or non-woven matting fabricated from long coir fibers with 0.25-0.50 millimeter diameters after retting. Bangladesh and Vietnam coastal embankment projects specify biodegradable variants for monsoon-cycle erosion control, displacing synthetic polypropylene alternatives.
- Coir Fiber:Extracted mesocarp tissue retaining high tensile strength and natural resistance to saltwater degradation. Demand concentrates in brush and mattress manufacturing across domestic Indian and Sri Lankan markets.
- Coir Mulch:Shredded husk material applied as surface ground cover. Landscapers in water-stressed Australian horticulture regions specify mulching grades for moisture conservation in protected cropping operations.
The dominant share belongs to coir pith, while coir geotextiles are closing the gap fastest.
Application:
End-use contexts range from intensive commercial production systems to civil engineering infrastructure.
- Horticulture:Controlled-environment agriculture in glasshouse operations demands buffered substrates with documented heavy metal thresholds under EU REACH compliance. Mexican and Australian protected cropping facilities are expanding coir substrate trials as peat substitution accelerates.
- Erosion Control:Coastal and riverbank stabilization projects specify biodegradable matting with 2-5 year degradation timelines. Middle Eastern buyers source directly from Sri Lankan coastal mills with port access to Red Sea and Persian Gulf destinations.
- Agriculture:Open-field soil amendment applications utilize lower-grade coir pith for structure improvement in sandy or compacted soils. Indian smallholder operations represent the volume base for unprocessed material.
- Soil Amendments:Blended products combining coir pith with composted organic matter target home gardening and landscaping channels. Retail packaging in compressed brick format reduces distribution cube by 40 percent.
Horticulture commands the largest revenue pool, with erosion control expanding most quickly on infrastructure investment cycles.
Form:
Physical configuration directly determines freight economics and end-user handling requirements.
- Bricks:Compressed blocks with 5:1 expansion ratio upon hydration. North American greenhouse distributors specify 5-kilogram bricks for containerized ocean freight efficiency and automated greenhouse expansion systems.
- Bales:High-density wrapped units for large-scale agricultural and erosion control projects. Port congestion at Colombo and Tuticorin is forcing Middle Eastern geotextile buyers to qualify alternative Indonesian suppliers with unproven logistics reliability for bale handling.
- Loose:Uncompressed pith or fiber for immediate application without hydration delay. Bulk loose shipments dominate domestic Indian and Sri Lankan supply chains where transport distances remain short.
- Mats:Pre-formed rolls or sheets for erosion control and landscaping applications. Vietnamese coastal embankment contractors specify rolled mat dimensions for mechanical deployment on slope stabilization projects.
Bricks dominate export trade on freight efficiency, while mats gain share fastest on civil engineering specification.
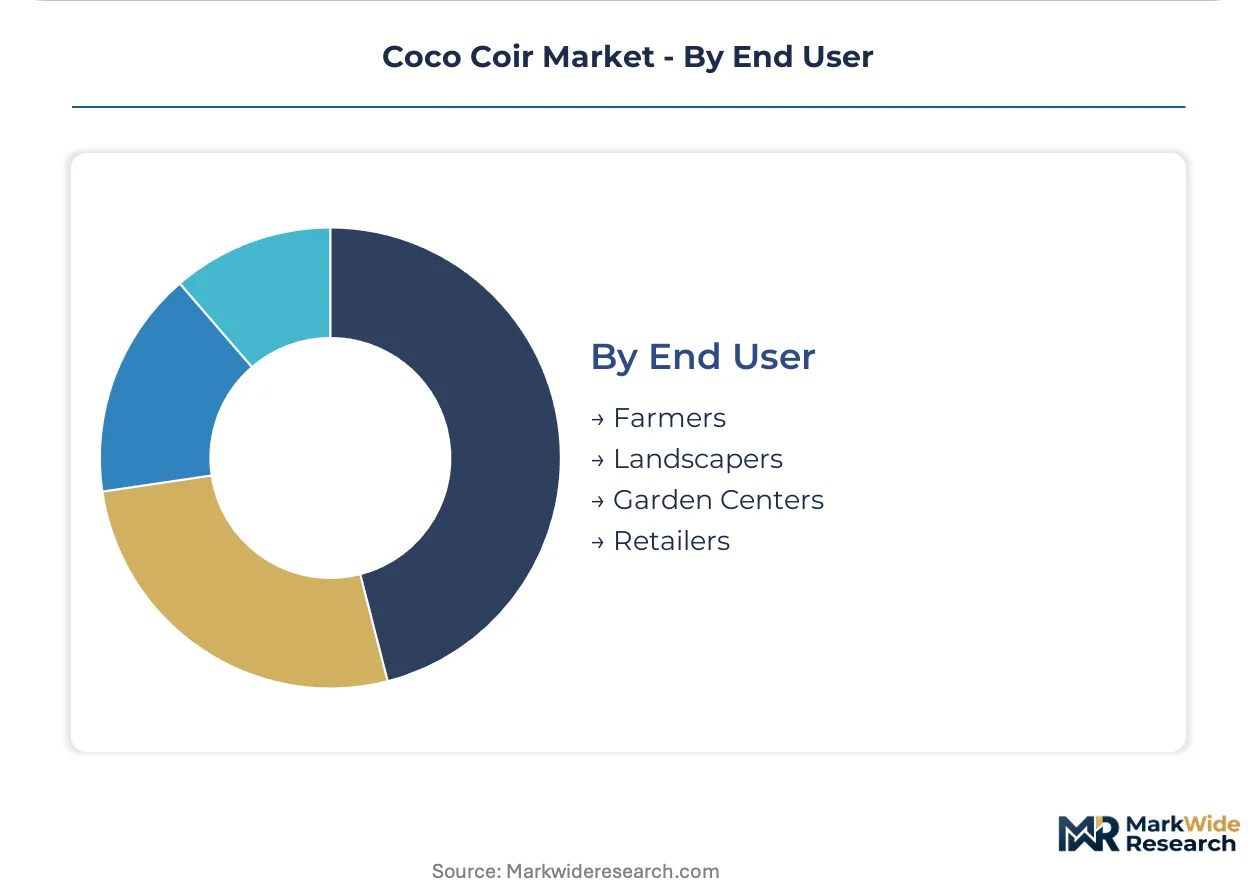
End User:
Channel structure fragments across institutional procurement and retail distribution with divergent service requirements.
- Garden Centers:Retail outlets serving home gardening and landscaping markets. California and Arizona protected agriculture distributors now function as logistics coordinators rather than price-setting intermediaries for direct mill procurement.
- Farmers:Commercial agricultural operations purchasing bulk substrate for open-field or greenhouse production. Water-stressed agriculture intensification in Mexico is driving coir substrate trials among tomato and pepper growers.
- Landscapers:Professional installation contractors specifying erosion control and ground cover materials. Australian Victoria and Queensland protected cropping investments source pH-stabilized coir pith for year-round vegetable production.
- Retailers:Mass-market chains distributing consumer-packaged coir products. Compressed brick packaging innovation enables shelf-ready formats for North American home improvement stores.
Garden centers capture the dominant volume, with landscapers climbing the fastest on infrastructure and erosion control project awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch and Spanish hydroponic greenhouse operators anchor substrate demand, while South Asian processors supply raw material. EU regulatory pressure on peat alternatives redirects procurement toward certified coir sources. Indian, Indonesian, and Sri Lankan clusters compete on automation and certification compliance.
Netherlands
Glasshouse tomato and pepper propagation drives pH-stabilized coir pith consumption. EU F-Gas Regulation phase-downs redirect peat-dependent growers toward documented low-carbon substrates with verifiable supply chain footprints. Westland municipality clusters host distributors specifying electrical conductivity below 1.5 millisiemens per centimeter.
Spain
Almería protected agriculture expands coir substrate trials as water-stressed agriculture intensifies. EU Green Deal soil health guidelines mandate heavy metal testing and salt content documentation for substrate shipments entering horticulture markets. Murcia and Valencia processing depots pre-certify production lots before vessel loading.
India
Pollachi and Tiruchengode mechanized fiber extraction mills displace traditional manual methods. BIS quality marks and Coconut Development Board export inspection protocols govern fiber grading for international shipment. Tamil Nadu processing clusters dominate export-grade coir pith, creating geographic concentration vulnerability.
Indonesia
Automated washing and buffering lines achieve consistent pH stabilization for European horticulture contracts. National standards authority mandates moisture caps to prevent container mold during transoceanic transit. Universal Coco Indonesia leverages automated infrastructure to serve buyers previously reserved for Sri Lankan and Indian suppliers.
Sri Lanka
Coastal mills with direct port access supply Middle Eastern erosion control projects with premium geotextile output. Colombo port congestion forces buyers to qualify alternative Indonesian suppliers with unproven logistics reliability. Lanka Coco Products anchors biodegradable matting production for Bangladesh and Vietnam coastal embankment specifications.
Coco Coir Market Key Industry Players
Channel-controlling players compete with product-specialist players across substrate and geotextile segments. The vendor base organizes around three archetypes: automated processors with captive laboratory certification, coastal mills with direct port access for civil engineering buyers, and packaging innovators compressing ocean freight economics. Consolidation pressures favor processors with integrated quality control over traditional trading intermediaries. Dominant competitive moves include backward integration into fiber extraction and geographic expansion through direct annual volume contracts with North American greenhouse operators.
Among Indonesian automated processors, Universal Coco Indonesia occupies a position exemplifying pH-stabilization capability for European horticulture entry. Fibredust LLC represents the packaging innovation archetype, with compressed brick formats reducing distribution cube for North American channels. Lanka Coco Products anchors the coastal mill specialization, sitting within the geotextile tier serving Middle Eastern erosion control procurement. These three entities illustrate the strategic divergence between substrate certification, logistics efficiency, and civil engineering material supply.
| Leading Market Players |
|---|
| Universal Coco Indonesia |
| Keppel Corporation |
| Pilipinas Ecofiber Corporation |
| Lima Group |
| Carib Agro Industries |
| Fibredust LLC |
| Bali Coco |
| EcoCoir Pvt. Ltd. |
| Lanka Coco Products |
| Others |
Cost & Logistics Intelligence
Tuticorin-Colombo freight corridors compress landed costs for European horticulture buyers while amplifying price spreads between certified and uncertified coir pith grades. Supply concentration across Tamil Nadu processing clusters grants automated mills pricing power over traditional traders, forcing downstream distributors to absorb margin compression or cede volume to direct procurement channels.
Pricing Analysis
Cost-plus contracts with coconut husk indexation dominate procurement agreements between Indian fiber extraction mills and Dutch greenhouse distributors. Price differentiation rests on BIS certification tier and electrical conductivity testing below 1.5 millisiemens per centimeter, with premium grades commanding substantial spreads over standard pith. Pricing pressure stems from Indonesian automated processors entering European contracts with compressed brick packaging that reduces ocean freight cube. Mexican glasshouse operators exhibit highest price sensitivity due to nascent peat substitution trials, while Dutch Westland clusters prioritize certification compliance over unit cost.
Supply Chain Analysis
Upstream coconut husk availability fluctuates with Kerala and Tamil Nadu monsoon patterns, creating raw material uncertainty for fiber extraction operations. Supply concentrates in India, Indonesia, and Sri Lanka, with mechanized processing capacity expanding fastest in Indonesian clusters. The chain draws from agricultural waste streams, shipping logistics, and laboratory certification infrastructure. Single-source vulnerability persists around Pollachi and Tiruchengode export-grade coir pith production. Distribution runs through layered networks of Colombo-based traders, direct mill contracts, and North American greenhouse distributors functioning as logistics coordinators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EU REACH compliance and F-Gas Regulation phase-downs create switching costs that entrench certified processors. Network effects concentrate around laboratory certification capacity and direct annual volume contracts with greenhouse operators.
For Market Incumbents: Entrench position through captive laboratory certification investment and backward integration into mechanized fiber extraction. Threats emerge from Indonesian automated processors with compressed brick packaging innovation. Priority levers include securing annual volume contracts with North American greenhouse operators and pre-certifying production lots before vessel loading to Spanish Almería operations.
For New Entrants and Emerging Players: Mexican glasshouse tomato and pepper propagation facilities offer accessible entry points for pH-stabilized coir pith trials. Australian Victoria and Queensland protected cropping investments present secondary white-space opportunities. Go-to-market execution should emphasize direct mill procurement relationships bypassing traditional Colombo-based trader networks, coupled with automated washing and buffering line investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underutilized coconut processing assets. Long-term viability centers on regulatory entrenchment through certification infrastructure rather than commodity volume scale. Acquisition archetypes include coastal mills with direct port access for Middle Eastern geotextile buyers and automated processors with inline quality control. Signal to monitor: acceleration of EU soil health guideline enforcement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Extraction | Captive husk supply from Kerala and Tamil Nadu clusters insulates against monsoon-driven input volatility. |
| Automated Washing and Buffering Line Deployment | Inline pH stabilization unlocks Dutch and Spanish greenhouse contracts requiring REACH-compliant documentation. |
| Compressed Brick Packaging Innovation | 40 percent ocean freight cube reduction enables competitive positioning in North American distributor channels. |
| Direct Annual Volume Contracting | Bypassing Colombo trader networks captures margin compression from channel consolidation in California and Arizona. |
| Coastal Mill Port Access Qualification | Direct loading at Tuticorin and Colombo secures Middle Eastern geotextile procurement from erosion control contractors. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs records, Coconut Development Board export statistics, and EU REACH compliance registries. Primary interviews engaged fiber extraction mill operators, Dutch greenhouse procurement directors, Indonesian automated processing engineers, and Sri Lankan coastal mill logistics coordinators. Secondary validation drew from BIS quality mark databases, FAO coconut production statistics, and horticulture trade association substrate specifications. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional demand clusters.
Forecast inputs incorporate material composition segmentation, certification tier penetration curves, and freight corridor cost dynamics across the projection horizon. The analytical framework models coir pith, geotextile, fiber, and mulch segments intersecting with horticulture, erosion control, and agriculture applications. CAGRs derive from regression analysis against peat substitution rates, EU regulatory enforcement intensity, and protected cropping investment cycles. Industry-specific variables include monsoon pattern correlation with husk supply, automated processing capacity buildout timelines, and geotextile specification adoption in Bangladesh and Vietnam coastal embankment projects.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indonesian automated processors or accelerated EU soil health guideline implementation would shift outcomes substantially. Cross-checking against Coconut Development Board export inspection protocol volumes and Dutch greenhouse operator substrate switching surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Farming Sacks and Totes Market