
 Europe Agricultural Films Market | 2026-2036
Europe Agricultural Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Films Market Foresight
Buyer concentration among large greenhouse operators and agricultural cooperatives is recalibrating procurement volumes across Europe. Trioplast AB leverages its Nordic manufacturing base to sustain supply contracts with scale-dependent horticulture clusters. Berry Global anchors its position through multi-material extrusion capabilities that serve diverse climatic zones. RKW Group competes via specialized silage and mulch film formulations tailored to continental crop rotations.
Europe agricultural films are polymer-based flexible sheeting, typically 20–200 microns thick, manufactured through blown film extrusion of polyethylene grades or biodegradable alternatives, designed to modify microclimate, suppress weeds, or preserve forage moisture. Their primary purpose spans soil temperature management, crop protection, and post-harvest storage across open-field and controlled-environment systems. Mulching films and greenhouse films represent the dominant product categories, with silage films capturing margin pools linked to seasonal dairy-forage cycles. LDPE and LLDPE material grades lead volume throughput, though EVA copolymers gain traction in high-transmittance greenhouse applications where light diffusion directly affects yield.
EMA, ECHA, and the EU Green Deal collectively shape polymer composition rules, recyclability mandates, and carbon-accounting thresholds for film producers serving European agriculture. REACH compliance and emerging CSRD reporting obligations now extend liability upstream to resin sourcing decisions. Stakeholders must monitor how biodegradability certification standards evolve alongside mechanical recycling infrastructure investments.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing polymer formulation cycles across European agricultural film supply chains, forcing resin suppliers and extruders to synchronize product development with tightening carbon-accounting thresholds.
Growth Catalysts
- REACH compliance mandates:ECHA substance restrictions on persistent microplastics are accelerating certified biodegradable film adoption among Dutch and Spanish greenhouse operators.
- Protected cultivation expansion:Intensive horticulture clusters in Italy and the Netherlands are scaling film-intensive greenhouse systems to secure year-round vegetable supply.
- EVA copolymer diffusion:High-transmittance greenhouse films incorporating ethylene-vinyl acetate are displacing standard LDPE in premium tomato and pepper operations.
Market Restraints
- Naphtha feedstock volatility:European polyethylene resin costs track Brent crude movements, compressing extruder margins during energy price spikes.
- Mechanical recycling infrastructure gaps:Collection and reprocessing capacity for agricultural film waste remains concentrated in Germany and France, leaving southern European markets underserved.
- Biodegradability certification fragmentation:Divergent national standards for soil-biodegradable mulch films create compliance friction for cross-border suppliers.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian open-field vegetable operations remain below western European mulch film adoption rates, presenting volume expansion potential.
- CSRD reporting obligations:Corporate Sustainability Reporting Directive requirements are creating premium demand for carbon-accounted film supply chains among large agricultural cooperatives.
- Silage film seasonality arbitrage:Dairy-forage cycles in Ireland and Denmark create predictable demand spikes that specialized formulations can capture.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists capable of balancing biodegradability, mechanical strength, and cost constraints command premium compensation across European extrusion operations.
- Legacy equipment retrofit costs:Blown film lines optimized for conventional polyethylene require capital-intensive modifications to process starch-based or PLA alternative resins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Films Market |
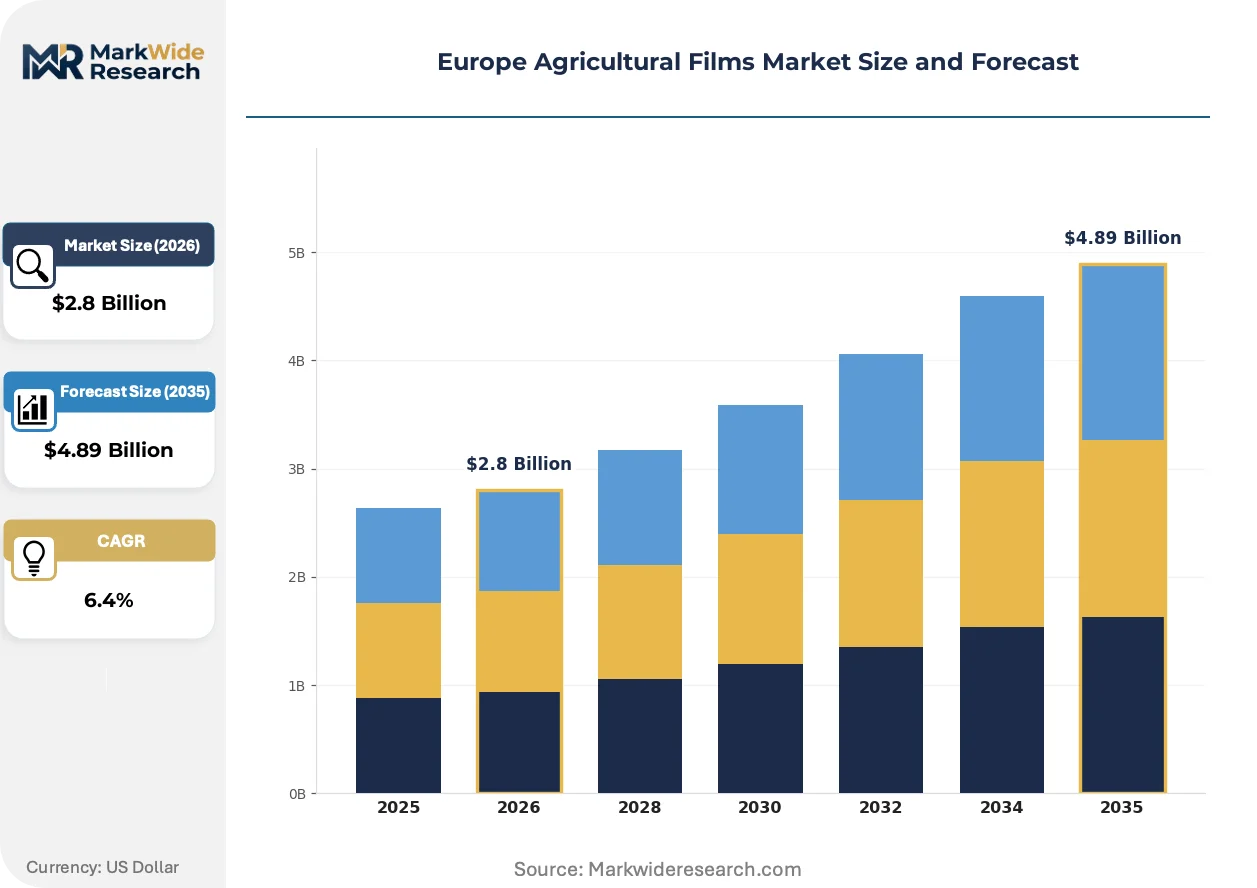
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mulching Films, Greenhouse Films, Silage Films, Seed Films Material: LDPE, LLDPE, HDPE, EVA Application: Agricultural Production, Horticulture, Aquaculture, Commodities Storage End User: Farmers, Greenhouse Operators, Agricultural Cooperatives, Distributors |
| Companies Covered | Trioplast AB, Novamont S.P.A, Ab Rani Plast Oy, Coveris, Groupe Barbier, Berry Global, Polifilm GmbH, Plastika Kritis, RKW Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Films Market Shifts & Advancements
Multilayer coextrusion architectures and sensor-integrated films are actively reconfiguring how European growers manage microclimate variables, shifting competitive advantage toward materials science capabilities.
Multilayer barrier films incorporating ethylene-vinyl alcohol interlayers are modularizing greenhouse cladding systems. Large-scale tomato producers in Almeria and Westland are adopting these structures to reduce heating energy consumption. The technology is modularizing supplier relationships, enabling growers to source functional layers from specialized converters rather than integrated polymer houses.
The EU F-Gas Regulation phase-down schedule is compressing demand for fluorinated polymer films in high-value greenhouse applications. ECHA restrictions on per- and polyfluoroalkyl substances are accelerating non-fluorinated alternative development. Dutch greenhouse technology providers are responding fastest, integrating fluorine-free films into their turnkey system offerings.
Cooperative procurement consortia are consolidating film purchasing decisions across regional horticulture clusters. Small-scale Spanish and Italian growers are aggregating volumes through agricultural cooperatives to secure price tiers previously reserved for multinational greenhouse operators. This concentration is most visible in Murcia and Sicily, where cooperative buying groups now represent over half of regional mulch film demand.
Europe Agricultural Films Market Segmentation
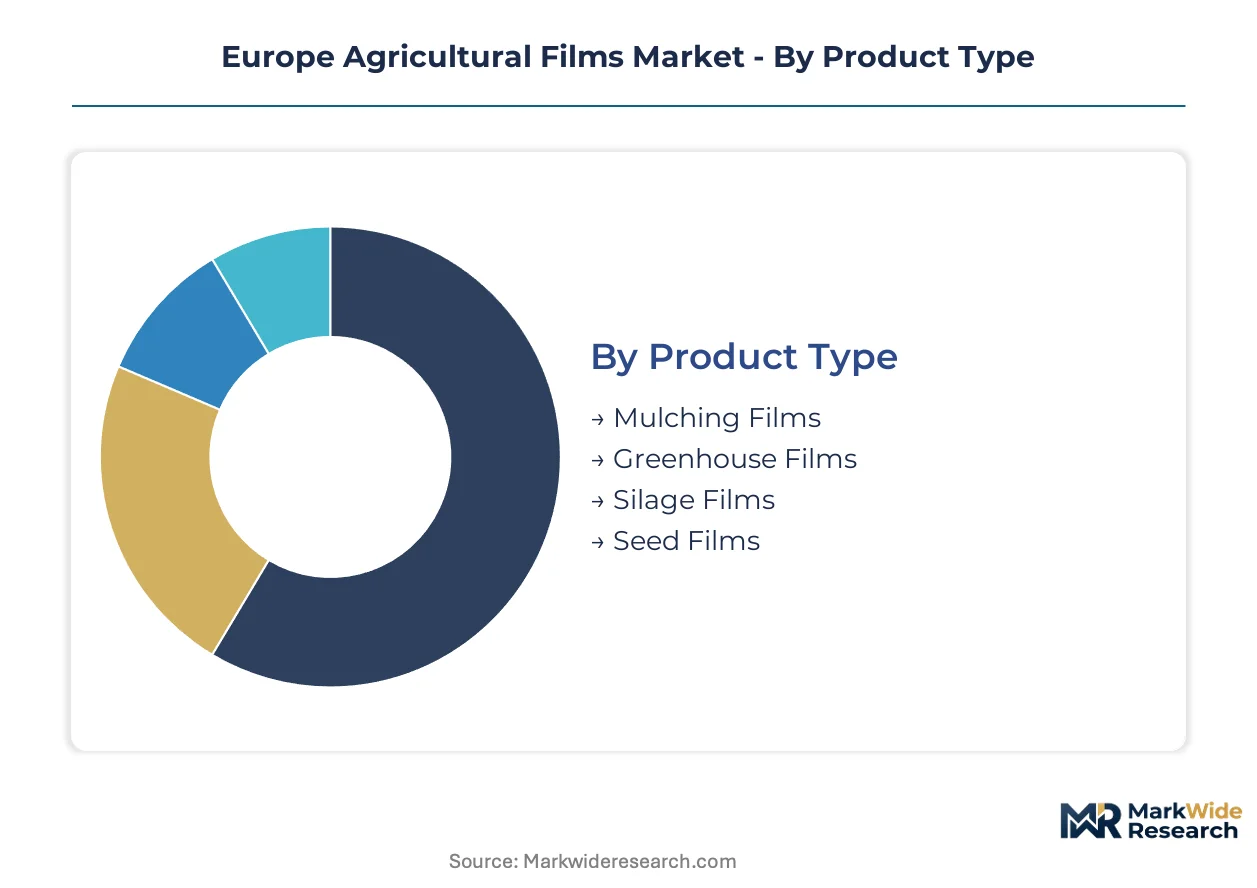
Segmentation in European agricultural films reveals how polymer specifications, application intensity, and buyer scale interact to determine margin capture. Understanding these layers exposes where formulation investments concentrate and which customer configurations command premium supply relationships.
Product Type:
Integration depth varies sharply across product categories, with some films functioning as standalone soil-covering systems while others embed within complex greenhouse infrastructure.
- Mulching Films:Thin polyethylene sheeting, typically 15-30 microns, laid directly over soil to suppress weeds and retain moisture. Demand concentrates in Spanish open-field vegetable operations around Murcia and Almeria, where strawberry and melon growers face ECHA pressure to shift from conventional to soil-biodegradable grades.
- Greenhouse Films:Multilayer coextruded structures, 80-200 microns, cladding tunnel and glasshouse frames to modify internal climate. Dutch Westland horticulture clusters anchor adoption, with operators integrating these films into energy-efficient heating systems to meet EU Green Deal carbon thresholds.
- Silage Films:Black or green polyethylene wraps, 25-50 microns, preserving forage moisture for dairy feed. Irish and Danish agricultural cooperatives drive seasonal procurement spikes tied to grass harvest cycles.
- Seed Films:Biodegradable carrier substrates embedding seeds and nutrients for precision planting. Italian rice paddies in the Po Valley represent emerging adoption territory for water-seeding applications.
Mulching films lead volumes today; greenhouse films are gaining share fastest.
Material:
Cost tier differentiation separates commodity polyethylene grades from specialty copolymers commanding formulation premiums.
- LDPE:Low-density polyethylene resin processed through blown film extrusion, offering flexibility and optical clarity at moderate cost. Remains the default specification for Spanish and Italian mulch film buyers prioritizing unit economics over performance margins.
- LLDPE:Linear low-density polyethylene with superior puncture resistance and drawdown properties. Dominates silage film formulations across Irish dairy cooperatives where mechanical durability during wrapping operations determines field performance.
- HDPE:High-density polyethylene providing stiffness and chemical resistance in thinner gauges. Captures niche demand in aquaculture pond liners and commodity storage tarpaulins where dimensional stability outweighs flexibility requirements.
- EVA:Ethylene-vinyl acetate copolymer incorporating 5-15% vinyl acetate content for enhanced light transmission and thermal retention. Dutch greenhouse operators specify EVA-rich formulations for premium tomato and pepper cultivation where photon management directly correlates with yield.
LDPE and LLDPE together anchor volume throughput; EVA is climbing the fastest as protected cultivation intensifies.
Application:
Customer type concentration shapes procurement patterns, with integrated operators demanding technical support that fragmented buyers cannot access.
- Agricultural Production:Open-field crop cultivation deploying mulch films and soil solarization sheeting. Polish and Romanian vegetable growers represent underpenetrated expansion territory relative to western European adoption baselines.
- Horticulture:Intensive protected cultivation of high-value vegetables, ornamentals, and soft fruit. Netherlands and Spain concentrate greenhouse film demand, with Almeria alone accounting for substantial European tomato supply under polymer cladding.
- Aquaculture:Pond lining and tank containment systems for fish and shellfish farming. Greek and Turkish coastal operations deploy HDPE geomembranes, though this application sits at the periphery of core agricultural film demand.
- Commodities Storage:Grain and forage protection through silage films and temporary shelter sheeting. Seasonal dairy-forage cycles in Denmark and Ireland create predictable demand architecture for specialized formulations.
Horticulture commands the steepest expansion trajectory; agricultural production retains the broadest installed base.
End User:
Procurement scale determines pricing tier access and technical service intensity, fragmenting the customer base across operational configurations.
- Farmers:Individual owner-operators managing open-field acreage with limited capital equipment. Italian and Spanish smallholders increasingly aggregate through cooperative structures to access volume pricing previously reserved for industrial-scale buyers.
- Greenhouse Operators:Specialized protected cultivation enterprises running multi-hectare glasshouse or tunnel complexes. Dutch Westland and Venlo clusters represent the most sophisticated specification demand, with operators integrating film selection into climate control system design.
- Agricultural Cooperatives:Member-owned purchasing consortia consolidating input procurement across regional grower bases. Murcia and Sicilian cooperatives now represent majority regional mulch film demand, reshaping supplier relationship economics.
- Distributors:Agricultural supply intermediaries stocking film inventories for downstream resale. German and French distribution networks maintain the most developed mechanical recycling collection infrastructure, extending producer responsibility compliance upstream.
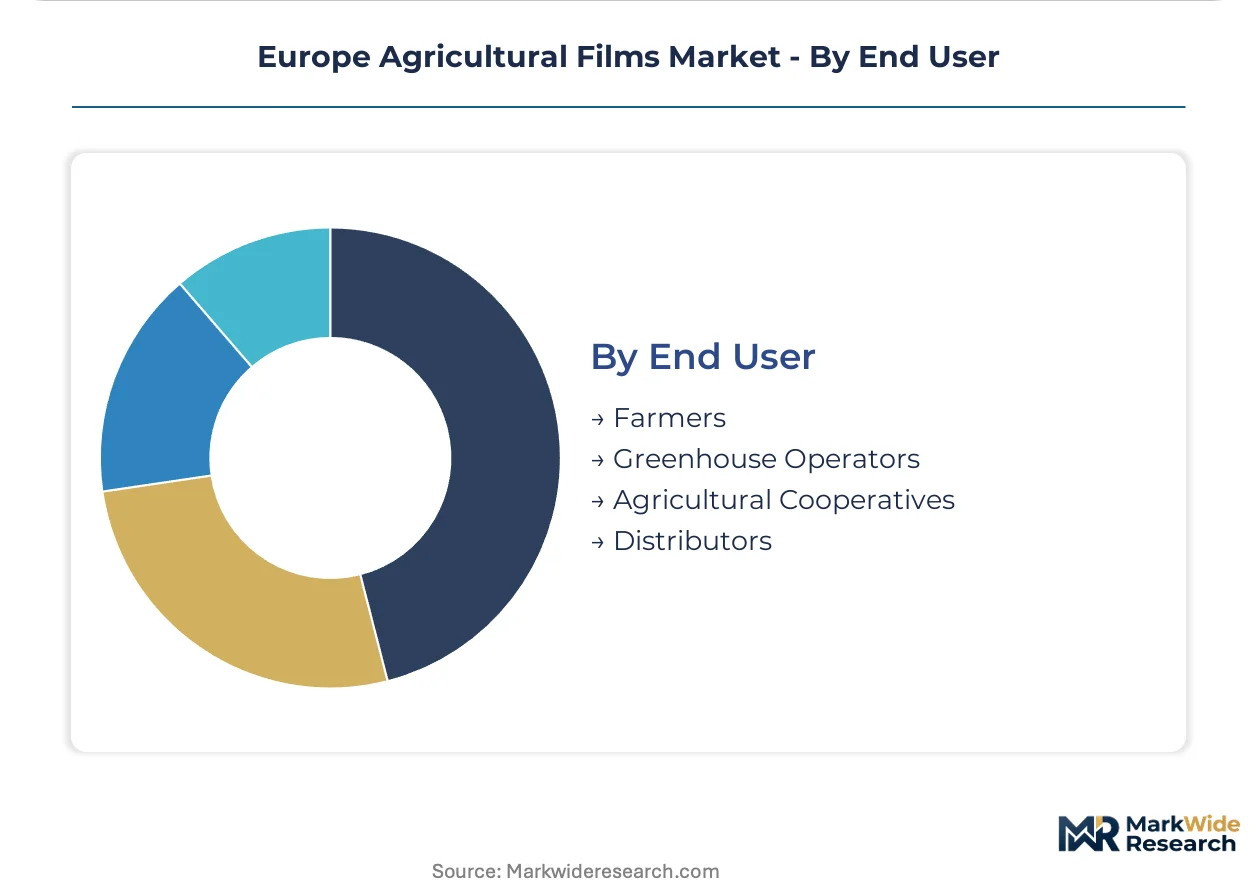
Agricultural cooperatives are expanding their share fastest; farmers remain the numerically dominant category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain concentrates more greenhouse film demand than any other European country, while the Netherlands commands premium formulation specifications despite smaller acreage under polymer cladding.
Spain
Almería and Murcia host the continent's densest concentration of plasticulture infrastructure, with strawberry and tomato growers driving mulch film procurement volumes. ECHA restrictions on persistent microplastics are accelerating the shift from conventional polyethylene to certified soil-biodegradable alternatives in open-field vegetable operations. The southeastern horticulture belt now accounts for the majority of Spanish agricultural film consumption.
Netherlands
Westland and Venlo greenhouse clusters specify EVA-rich multilayer films for premium tomato and pepper cultivation where photon management correlates directly with yield outcomes. The EU Green Deal carbon-accounting thresholds are integrating film selection into climate control system design decisions. Dutch operators are replacing fluorinated polymer films with fluorine-free alternatives ahead of F-Gas Regulation phase-down schedules.
Italy
Po Valley rice paddies and Sicilian cooperative purchasing groups are expanding seed film and mulch film adoption respectively. REACH compliance mandates are reshaping resin sourcing decisions for extruders serving Italian agricultural markets. Murcia-style cooperative procurement consortia in Sicily now represent majority regional demand, aggregating smallholder volumes into price tiers previously reserved for industrial-scale buyers.
Poland
Open-field vegetable operations in central and eastern regions remain below western European mulch film penetration rates, presenting volume expansion potential for standard LDPE formulations. National implementation of EU packaging and packaging waste directives is beginning to extend producer responsibility frameworks to agricultural film waste streams. The Masovian and Łódź voivodeships concentrate emerging protected cultivation investment.
Ireland
Dairy-forage cycles drive seasonal silage film procurement spikes that specialized LLDPE formulations target. Agricultural cooperatives consolidate input purchasing across regional grower bases, reshaping supplier relationship economics. The southeastern grassland belt dominates film consumption timing tied to predictable grass harvest windows.
Europe Agricultural Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across European agricultural film supply chains. The vendor base organizes into three tiers: integrated polymer houses with multi-material extrusion capabilities, regional converters serving specific climatic zones, and biodegradable formulation specialists aligned with ECHA compliance trajectories. M&A activity concentrates on acquiring regional distribution networks, while capacity expansion targets eastern European underpenetration zones.
Among Nordic manufacturing anchors, Trioplast AB exemplifies scale-dependent supply relationships with large greenhouse operators and agricultural cooperatives. Berry Global occupies a position representing multi-material extrusion capabilities that serve diverse European climatic zones. RKW Group sits within the specialized formulation tier, with its corporate structure suggesting focus on tailored product development rather than commodity volume throughput.
| Leading Market Players |
|---|
| Trioplast AB |
| Novamont S.P.A |
| Ab Rani Plast Oy |
| Coveris |
| Groupe Barbier |
| Berry Global |
| Polifilm GmbH |
| Plastika Kritis |
| RKW Group |
| Others |
Supply & Pricing Matrix
Polymer formulation chemists concentrated in Germany's Rhine-Ruhr industrial corridor command premium compensation that widens pricing spreads between commodity LDPE mulch films and specialty EVA greenhouse formulations. Labor-cost differentials between Nordic extrusion operations and southern European converters feed directly into tiered pricing structures that Dutch greenhouse operators navigate when specifying multilayer cladding systems.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for standard mulch film grades, compressing margins for commodity LDPE producers while EVA-rich formulations retain pricing power. Three-tier pricing structure across premium, standard, and economy levels separates certified biodegradable mulch films from conventional polyethylene and unbranded regional imports. Cost compression in commodity grades is intensifying because naphtha feedstock volatility tracks Brent crude movements. Smallholder farmers in Sicily and Murcia exhibit the highest price sensitivity, whereas Dutch Westland greenhouse operators prioritize photon management performance over unit economics.
Supply Chain Analysis
Direct-to-greenhouse-operator channels handle hyperscale buyer demand from Dutch Westland and Almeria clusters, while agricultural cooperative consortia aggregate fragmented smallholder volumes in Italy and Spain. Resin supply concentrates in Germany, Belgium, and the Netherlands, with naphtha crackers along the ARA corridor feeding blown film extrusion across northern Europe. Raw material dependencies rest on Brent-linked polyethylene grades, ethylene-vinyl acetate copolymers, and emerging starch-based biopolymer alternatives. Single-source vulnerability to Russian naphtha supply disruptions poses structural risk for continental extruders. Distribution runs through German and French agricultural supply networks with the most developed mechanical recycling collection infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe agricultural films market functions as a stable compounder, with EU Green Deal carbon-accounting thresholds and F-Gas Regulation phase-downs creating durable demand tailwinds for compliant formulation suppliers.
For Market Incumbents: Deepen backward integration into biopolymer resin sourcing to secure supply chains for certified soil-biodegradable grades as ECHA microplastic restrictions tighten. Expand technical service capabilities for Dutch greenhouse operators integrating film selection into climate control system design, defending against specialized converters offering modular functional layers.
For New Entrants and Emerging Players: Agricultural cooperative purchasing consortia in Sicily and Murcia offer the most penetrable channel structure for volume aggregation without direct competition against integrated polymer houses. Target Polish and Romanian open-field vegetable operations with standard LDPE mulch film offerings, leveraging underpenetration relative to western European adoption baselines. Pursue go-to-market partnerships with regional distributors possessing mechanical recycling collection infrastructure.
For Investors and Strategic Acquirers: Specialized biodegradable formulation specialists are the most active acquirer category in this space, with diversified conglomerates seeking ECHA-aligned capabilities. The market supports long-term viability through regulatory-driven replacement cycles rather than discretionary capital expenditure. Acquisition targets should demonstrate proven certification pathways for soil-biodegradable grades. Monitor F-Gas Regulation implementation velocity as the key inflection signal for fluorine-free film demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Resin Sourcing | Secures supply chains for ECHA-compliant soil-biodegradable formulations ahead of microplastic restrictions. |
| Multilayer Coextrusion Capacity Expansion | Enables Dutch greenhouse operators to reduce heating energy consumption through advanced barrier films. |
| Cooperative Procurement Consortium Partnerships | Aggregates smallholder volumes in Sicily and Murcia into price tiers previously reserved for industrial buyers. |
| Fluorine-Free Formulation Development | Aligns product portfolios with EU F-Gas Regulation phase-down schedules ahead of compliance deadlines. |
| Mechanical Recycling Infrastructure Investment | Extends producer responsibility compliance through German and French distribution network partnerships. |
Research Methodology
Bottom-up horticulture application modeling reconciled against top-down resin supply tracking forms the analytical core of this study. Primary interviews with blown film extrusion plant managers, agricultural cooperative procurement leads, Dutch greenhouse technology providers, and ECHA regulatory affairs specialists were validated against secondary sources including EU customs trade data, Cefic polymer production reports, and REACH substance restriction filings. The approach triangulates demand-side consumption patterns with supply-side capacity utilization across Nordic and continental European manufacturing bases.
Input-output matrices connect polymer grade specifications to end-use application intensity across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, application intensity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of protected cultivation expansion rates and biodegradable substitution curves. Industry-specific forecast inputs incorporate EU Green Deal carbon threshold implementation timelines and F-Gas Regulation phase-down schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biodegradability certification standard fragmentation and mechanical recycling infrastructure buildout pace. Forecasts reflect documented assumptions regarding regulatory implementation velocity and feedstock cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
North America Agricultural Films Market