
 Monkeypox Treatment Market | 2026-2036
Monkeypox Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Monkeypox Treatment Market Foresight
Modular vaccine-plus-antiviral bundling is restructuring procurement decisions for public health agencies and hospital systems. SIGA Technologies specializes in oral antiviral supply for orthopoxvirus indications. Bavarian Nordic dominates live-virus vaccine production at manufacturing scale. Emergent BioSolutions anchors biodefense contracting relationships with domestic preparedness agencies.
Monkeypox treatment encompasses pharmaceutical and biological interventions targeting orthopoxvirus infection, including tecovirimat capsules requiring specific weight-based dosing regimens and JYNNEOS vaccines administered via subcutaneous or intradermal routes for pre- and post-exposure prophylaxis. Antivirals and vaccines capture the dominant share of product-type revenue, with monoclonal antibodies representing an emerging pipeline category for treatment-resistant cases. Hospital and outpatient clinic settings absorb the majority of administered doses, while home care channels expand for stable patients completing oral tecovirimat courses.
The FDA's emergency use authorization framework and the CDC's stockpile allocation protocols shape product demand cycles and distribution priorities for manufacturers. WHO prequalification pathways govern access for lower-income national immunization programs seeking vaccine procurement. Stakeholders must monitor regulatory label expansions and post-market surveillance commitments that determine commercial runway for pipeline assets.
Market Dynamics
Federal stockpile contracting protocols are compressing procurement cycles and binding hospital systems to multi-year antiviral and vaccine commitments, reshaping manufacturer revenue visibility and inventory planning horizons.
Growth Catalysts
- Strategic National Stockpile Mandates:US federal procurement directives require health systems to maintain 90-day orthopoxvirus countermeasure reserves, anchoring baseline demand for tecovirimat and JYNNEOS doses.
- Intradermal Dosing Protocols:CDC label expansions enabling intradermal JYNNEOS administration are stretching limited vaccine supply fivefold, accelerating dose availability for outbreak response.
- Biodefense Funding Authorization:Project BioShield reauthorization directs sustained appropriations toward orthopoxvirus medical countermeasure development, de-risking pipeline investment for developers.
Market Restraints
- Live-Virus Manufacturing Bottlenecks:Bavarian Nordic's Copenhagen facility remains the sole qualified JYNNEOS production site, creating single-source dependency for global vaccine supply.
- Cold Chain Infrastructure Gaps:Ultra-cold storage requirements for vaccine stability exclude primary care clinics and rural health posts from direct procurement channels.
- Weight-Based Dosing Complexity:Tecovirimat's 600mg threshold for adult patients complicates pediatric protocols and requires pharmacy compounding capabilities absent in smaller facilities.
Strategic Opportunities
- Sub-Saharan Africa Access Programs:WHO prequalification pathways for monkeypox vaccines could unlock Gavi and national immunization program procurement for endemic countries.
- Oral Antiviral Home Care:Tecovirimat's oral bioavailability enables 14-day home treatment courses, expanding channel access beyond infusion-capable hospital settings.
- Monoclonal Antibody Pipelines:Chimeric and humanized antibody candidates targeting conserved orthopoxvirus epitopes address treatment-resistant cases and immunocompromised populations.
Industry Challenges
- Post-Market Surveillance Burden:FDA Risk Evaluation and Mitigation Strategy requirements for tecovirimat mandate prescriber certification and patient registry enrollment, slowing clinical uptake.
- Batch Release Testing Delays:Live-virus vaccine lots require 6-8 week sterility and potency verification cycles, constraining rapid surge capacity during outbreak escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monkeypox Treatment Market |
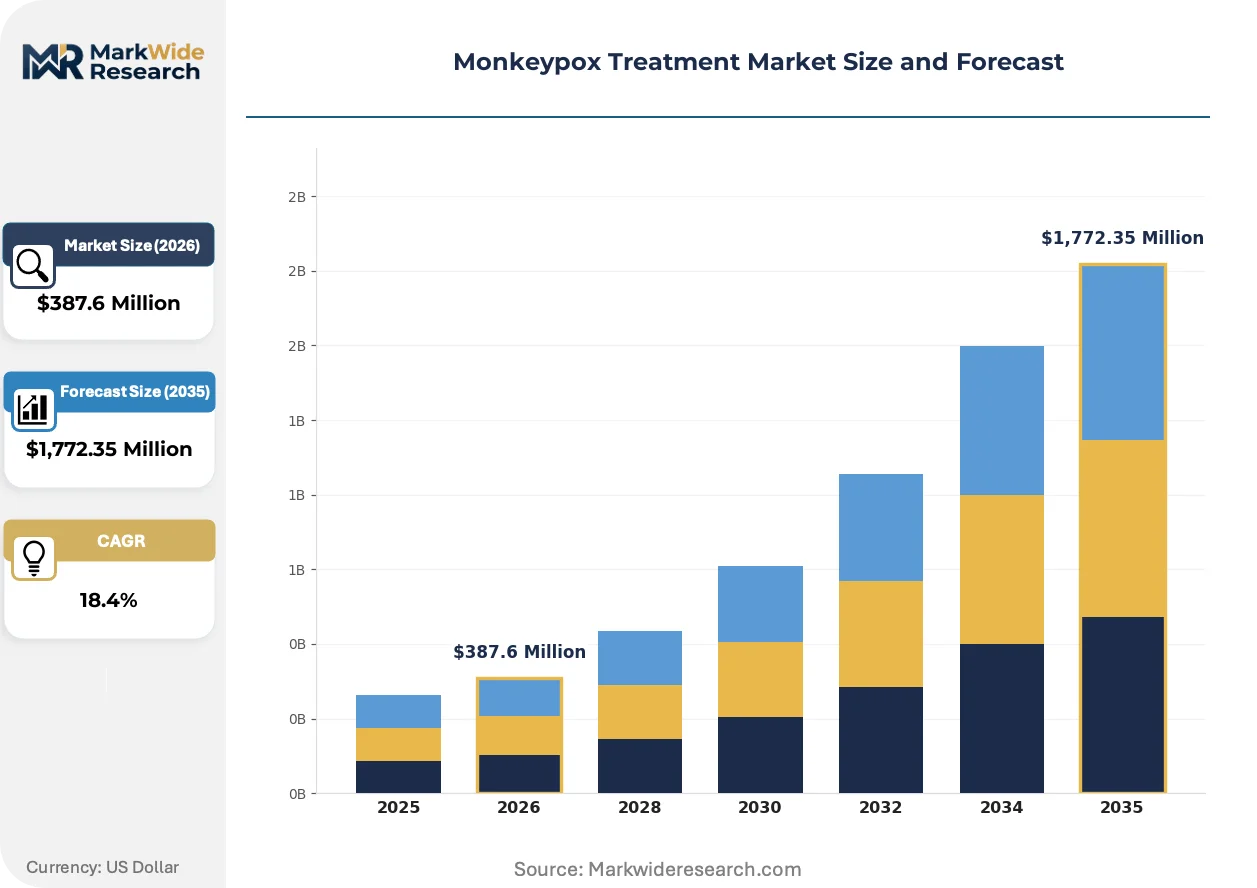
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Vaccines, Monoclonal Antibodies, Supportive Care Treatment Setting: Outpatient Clinics, Hospitals, Home Care, Emergency Services Administration Route: Oral, Intravenous, Intramuscular, Subcutaneous Patient Demographic: Children, Adults, Immunocompromised, Healthcare Workers |
| Companies Covered | SIGA Technologies, Chimerix, Bavarian Nordic, Emergent BioSolutions, Gilead Sciences, Tonix Pharmaceuticals Holding Corp., Sanofi, Moderna, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monkeypox Treatment Market Shifts & Advancements
Orthopoxvirus countermeasure development is converging on platform technologies that compress manufacturing timelines and enable rapid strain adaptation, while procurement models shift toward stockpile-centric contracting.
Messenger RNA vaccine platforms are unifying antigen design flexibility with accelerated production scale-up. BARDA-funded developers are advancing mRNA orthopoxvirus candidates through Phase 1/2 trials, targeting 100-day response timelines from sequence identification to commercial lot release. This technology is unifying pandemic preparedness architectures across US, European, and Asian health security agencies.
Project BioShield procurement mechanisms are restructuring biodefense contracting toward multi-year, multi-product agreements. HHS Office of the Assistant Secretary for Preparedness and Response now bundles antiviral, vaccine, and diagnostic acquisitions into single-vendor relationships, compressing vendor management overhead. Small and mid-cap developers face capital requirements to compete for these consolidated awards.
Hospital systems are consolidating monkeypox treatment capacity into designated referral centers with specialized isolation infrastructure. This concentration displaces distributed outpatient administration, centralizing tecovirimat dispensing and JYNNEOS vaccination into academic medical centers and county health departments. California, New York, and Illinois have each designated 8-12 hub facilities for complex case management.
Monkeypox Treatment Market Segmentation
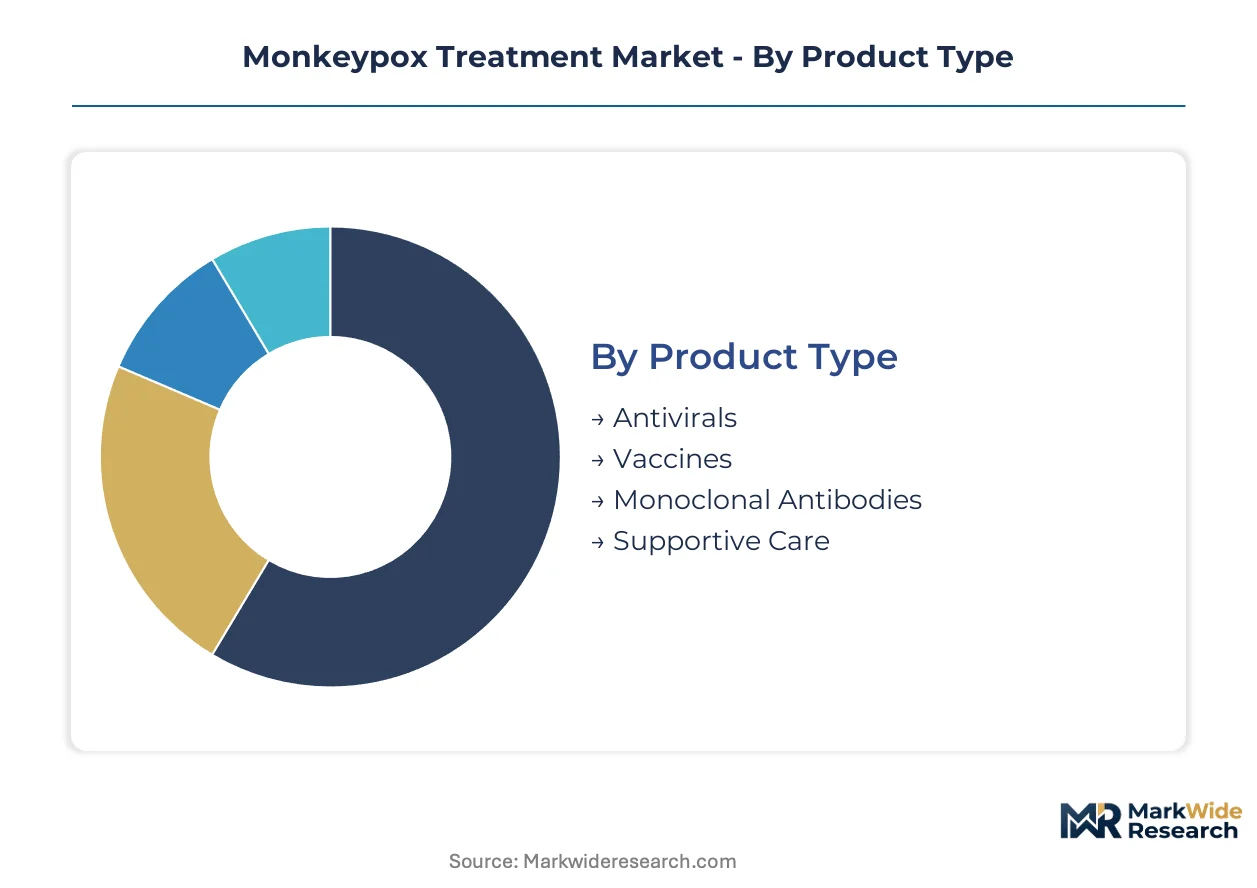
Orthopoxvirus countermeasures fragment across four intersecting dimensions that determine procurement patterns, reimbursement pathways, and inventory allocation. Product type and treatment setting together govern federal stockpile contracting structures, while administration route and patient demographic shape clinical deployment protocols and dosing complexity.
Product Type:
Volume procurement anchors antiviral and vaccine categories through strategic national stockpile mandates, while premium positioning concentrates in emerging biologics targeting treatment-resistant populations.
- Antivirals:Oral tecovirimat capsules dominate administered courses through weight-based dosing regimens spanning 14-day treatment windows. US federal contracts with SIGA Technologies anchor procurement volumes, with hospital systems maintaining 90-day reserves under CDC stockpile protocols.
- Vaccines:Live-virus JYNNEOS formulations from Bavarian Nordic's Copenhagen facility capture pre- and post-exposure prophylaxis demand. Intradermal administration protocols are stretching limited supply fivefold, accelerating dose availability across outbreak response networks.
- Monoclonal Antibodies:Chimeric and humanized candidates target conserved orthopoxvirus epitopes for immunocompromised patients failing standard antiviral therapy. BARDA-funded developers are advancing pipeline assets through Phase 1/2 trials.
- Supportive Care:Symptom management protocols including hydration, pain control, and secondary infection prophylaxis complement direct-acting antivirals in severe case management.
Mature deployment sits with Antivirals. Newer deployment is concentrated in Monoclonal Antibodies.
Treatment Setting:
Cost tier stratification separates capital-intensive isolation infrastructure from distributed outpatient administration, with reimbursement rates diverging sharply across facility types.
- Hospitals:Academic medical centers and designated referral hubs manage severe cases requiring intravenous access and specialized isolation infrastructure. California, New York, and Illinois have each designated 8-12 hub facilities for complex case management.
- Outpatient Clinics:County health departments and primary care networks administer JYNNEOS vaccination and stable tecovirimat dispensing. Cold chain infrastructure gaps exclude smaller facilities from vaccine procurement channels.
- Home Care:Oral tecovirimat bioavailability enables 14-day home treatment courses for stable patients, expanding channel access beyond infusion-capable settings.
- Emergency Services:Pre-hospital protocols for suspected orthopoxvirus exposure focus on isolation precautions and rapid transport to designated referral centers.
Revenue concentration clusters in Hospitals. Steepest expansion trajectory is emerging in Home Care.
Administration Route:
Application logic separates self-administered oral regimens from clinician-dependent parenteral delivery, with training requirements and error risk profiles driving route selection.
- Oral:Tecovirimat capsules enable outpatient treatment completion without infusion infrastructure. Weight-based dosing thresholds complicate pediatric protocols.
- Intravenous:Reserved for severe cases with gastrointestinal absorption impairment or rapid clinical deterioration requiring inpatient monitoring.
- Intramuscular:Traditional JYNNEOS administration consumes fivefold more antigen per dose compared to intradermal alternatives.
- Subcutaneous:Standard JYNNEOS delivery route with established immunogenicity profiles in pre- and post-exposure prophylaxis.
Dominant utilization tracks Oral administration. Intramuscular volumes are contracting fastest as intradermal protocols displace standard delivery.
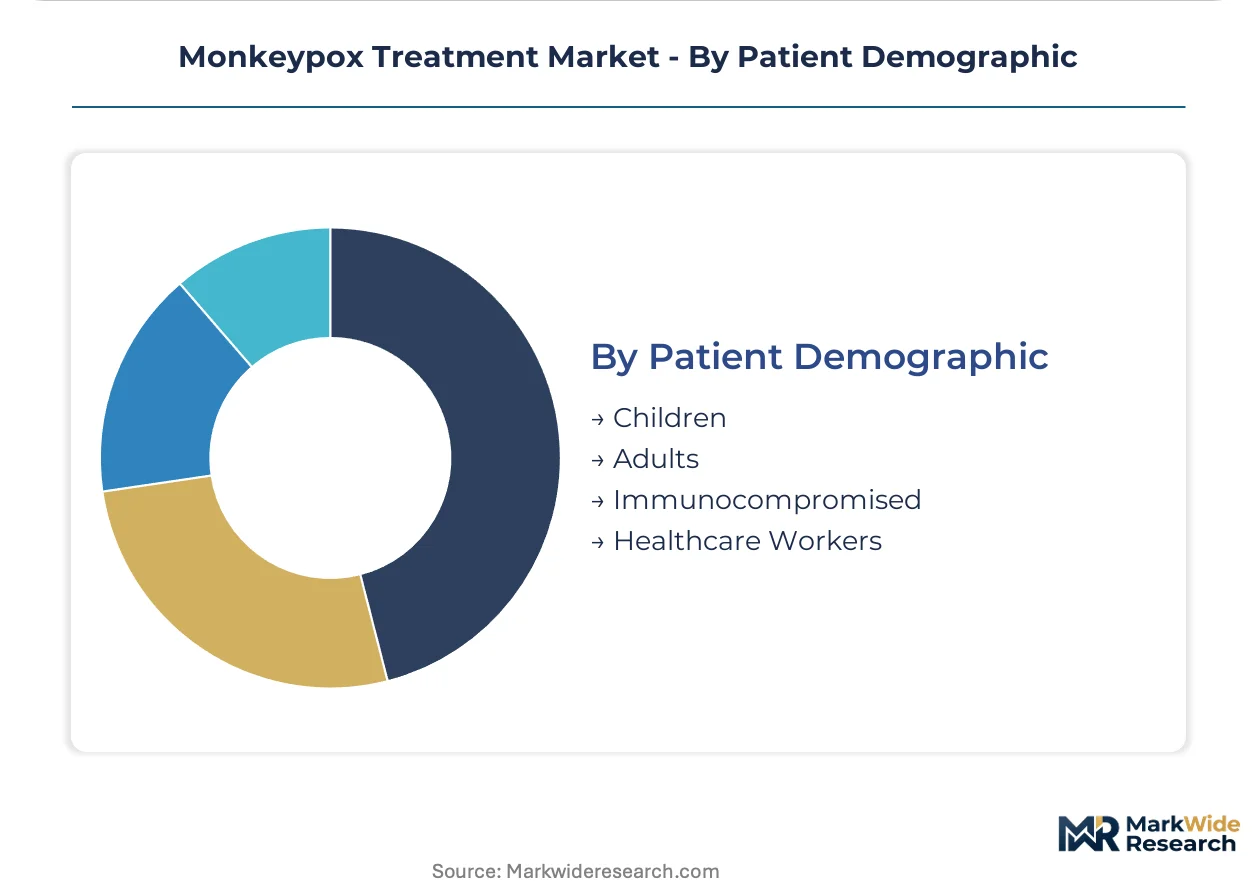
Patient Demographic:
Customer type segmentation separates institutional procurement for occupational protection from individual therapeutic need, with risk stratification protocols determining priority access.
- Adults:Primary population for tecovirimat treatment and JYNNEOS prophylaxis, with dosing protocols optimized for patients above 40kg body weight.
- Healthcare Workers:Occupational exposure protocols mandate pre-positioned vaccine stockpiles and rapid post-exposure prophylaxis access through hospital occupational health departments.
- Immunocompromised:HIV-positive and transplant recipient populations experience prolonged viral shedding and severe disease courses, driving demand for monoclonal antibody alternatives.
- Children:Pediatric dosing requires pharmacy compounding capabilities absent in smaller facilities, concentrating treatment capacity in academic medical centers.
Procurement scale favors Adults. Immunocompromised populations are gaining share fastest as label expansions address treatment-resistant indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BioSecure Valley tax-incentive zones in Maryland and North Carolina are concentrating federal biodefense contracting infrastructure, anchoring orthopoxvirus countermeasure procurement clusters.
United States
Federal stockpile mandates drive procurement volumes through HHS Project BioShield contracts. The FDA's emergency use authorization pathways compress development timelines for developers. Maryland's BioSecure Valley corridor hosts SIGA Technologies and Emergent BioSolutions facilities serving strategic national stockpile orders.
Denmark
Bavarian Nordic's Copenhagen manufacturing campus remains the sole qualified JYNNEOS production site for global vaccine supply. The Danish Medicines Agency coordinates batch release testing with EMA centralized procedures. The capital region anchors live-virus vaccine manufacturing capacity for European and international procurement.
Germany
Paul-Ehrlich-Institut oversight governs orthopoxvirus vaccine importation and distribution across federal states. The country's national pharmaceutical regulator maintains stringent cold chain verification for Bavarian Nordic product entry. Berlin and Frankfurt health authorities coordinate hub-and-spoke distribution to designated treatment centers.
United Kingdom
UK Health Security Agency stockpile protocols mandate 90-day antiviral reserves for NHS trusts. The MHRA's conditional marketing authorization framework enables rapid tecovirimat access during outbreak escalation. London and Manchester academic medical centers concentrate isolation infrastructure for complex case management.
Nigeria
Endemic transmission patterns sustain baseline demand for supportive care and investigational antiviral access. WHO prequalification pathways could unlock Gavi procurement for national immunization program integration. Lagos and Abuja treatment centers participate in clinical trial networks for pipeline monoclonal antibody candidates.
Monkeypox Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across orthopoxvirus countermeasure supply. The market structure concentrates around biodefense contractors with established federal procurement relationships and emerging platform-technology developers. Three archetypes dominate: live-virus vaccine manufacturers with sole-source production assets, oral antiviral specialists with stockpile-anchored revenue streams, and mRNA platform developers targeting rapid-response capabilities. Competitive moves center on multi-year federal contracting consolidation and manufacturing capacity expansion for surge preparedness.
Within the biodefense contracting tier, SIGA Technologies and Emergent BioSolutions exemplify pure-play specialists with established ASPR relationships. Bavarian Nordic occupies a position as the live-virus vaccine anchor with single-site global supply responsibility. These three entities represent distinct strategic positions: oral antiviral stockpile dependency, multi-product biodefense bundling, and sole-source manufacturing scale respectively.
| Leading Market Players |
|---|
| SIGA Technologies |
| Chimerix |
| Bavarian Nordic |
| Emergent BioSolutions |
| Gilead Sciences |
| Tonix Pharmaceuticals Holding Corp. |
| Sanofi |
| Moderna |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
FDA emergency use authorization pathways gate both qualified supply and premium-tier pricing access for orthopoxvirus countermeasures, binding manufacturers to REMS compliance costs that stratify market participation.
Pricing Analysis
Margin tightening in federal stockpile contracting reflects multi-year bundling mandates from HHS ASPR that compress vendor overhead recovery. Pricing stratifies across biodefense-anchored premium tiers, standard hospital procurement, and economy access programs for endemic countries. Certification tier and volume scale drive price differentiation, with Project BioShield-qualified suppliers commanding substantial premiums over investigational alternatives. Pediatric compounding requirements and cold chain infrastructure costs accelerate cost-down pressure on standard-dose formulations.
Supply Chain Analysis
EMA centralized batch release procedures gate European market entry for live-virus vaccines manufactured at Bavarian Nordic's Copenhagen facility. Geographic supply concentrates in Denmark for JYNNEOS production, the United States for tecovirimat formulation, and emerging mRNA capacity across BARDA-funded domestic sites. Raw material dependencies include embryonated chicken eggs for live-virus propagation, specialized lipid nanoparticles for mRNA platforms, and active pharmaceutical ingredients sourced from Indian and Chinese API manufacturers. Single-source manufacturing vulnerability for global vaccine supply creates structural exposure. Distribution runs through designated referral hubs and county health departments under CDC allocation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodefense contracting consolidation has triggered a vertical-integration race, with players pursuing upstream manufacturing capacity and downstream channel control to secure multi-year ASPR awards.
For Market Incumbents: Acquire Copenhagen-equivalent live-virus manufacturing assets or mRNA platform capabilities to reduce sole-source dependency exposure. Secure 90-day stockpile reserve commitments from state health departments to anchor revenue visibility against emerging platform competitors. FDA label expansion investments and pediatric protocol development defend positioning against monoclonal antibody substitutes. For New Entrants and Emerging Players: Begin with WHO prequalification pathway navigation for Gavi and national immunization program access in endemic African markets. Target home care channel expansion for oral antiviral completion courses, leveraging tecovirimat's bioavailability advantages over infusion-dependent alternatives. Partner with designated referral hub pharmacies for dispensing network placement. For Investors and Strategic Acquirers: BARDA funding authorization shifts are the leading indicator that mRNA platform developers will capture procurement share from live-virus incumbents. Long-term viability rests on manufacturing surge capacity and regulatory qualification speed rather than single-product revenue concentration. Acquisition targets should demonstrate dual-use biodefense platform architectures with pandemic preparedness applicability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Bavarian Nordic's Copenhagen facility expansion addresses single-source vulnerability for global JYNNEOS supply. |
| Regulatory Approval Pathway | FDA emergency use authorization compresses development timelines for orthopoxvirus mRNA vaccine candidates. |
| Pipeline Diversification | Monoclonal antibody advancement targets immunocompromised patients failing standard antiviral therapy protocols. |
| Long-term Supply Agreement | Project BioShield multi-year contracting anchors revenue visibility for SIGA Technologies and Emergent BioSolutions. |
| Geographic Expansion | WHO prequalification unlocks Gavi procurement for endemic country national immunization program integration. |
Research Methodology
Independent corroboration across hospital procurement managers, regulatory affairs leads, biodefense contracting officers, and formulary directors underwrites the qualitative findings. Primary fieldwork combined with FDA filings, EMA centralized procedure records, ClinicalTrials.gov entries, and CDC stockpile allocation protocols enables bottom-up and top-down triangulation. Secondary validation draws from HHS ASPR procurement disclosures, BARDA funding announcements, and WHO prequalification status updates.
Comparable-period anchoring to historical outbreak response cycles and stockpile replenishment waves structures the forecast window. Segmentation modeling spans product type, treatment setting, administration route, and patient demographic dimensions across the projection horizon. CAGRs derive from procurement volume trajectories, label expansion timelines, and manufacturing capacity buildout schedules. Forecast inputs incorporate federal funding authorization patterns and intradermal dosing protocol adoption curves.
Regulatory approval delays, manufacturing batch release bottlenecks, and funding authorization lapses are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in Project BioShield reauthorization status or WHO prequalification pathway acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market