
 Cysticercosis (Taeniasis) Treatment Market | 2026-2036
Cysticercosis (Taeniasis) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cysticercosis (Taeniasis) Treatment Market Outlook
Aftermarket service revenue for patient monitoring and relapse management is reshaping how pharmaceutical margins accumulate in neglected tropical disease portfolios. Merck & Co., Inc. anchors its position through manufacturing scale for albendazole supply chains. GlaxoSmithKline leverages decades of praziquantel production expertise across endemic markets. Bayer competes on quality certification and regulatory dossier breadth.
Cysticercosis (Taeniasis) Treatment encompasses pharmacological intervention against tissue and intestinal larval cestode infections, primarily deploying benzimidazole and pyrazinoisoquinoline compounds that disrupt parasite glucose uptake and calcium homeostasis. The therapy targets neurocysticercosis, the leading preventable cause of acquired epilepsy in low-resource settings, alongside intestinal taeniasis elimination. Oral delivery mode dominates volume due to programmatic suitability for mass drug administration, while intravenous formulations command premium positioning in severe neurocysticercosis requiring hospitalization. Neurocysticercosis therapy area carries the highest clinical urgency and reimbursement complexity, whereas taeniasis represents the larger addressable population for preventive chemotherapy campaigns.
FDA and WHO prequalification standards shape product registration pathways and procurement eligibility for endemic country tenders. EPA guidelines on pharmaceutical manufacturing effluent constrain production site location decisions, while national regulators in endemic markets enforce bioequivalence requirements for generic albendazole and praziquantel entrants. Stakeholders must monitor how WHO neglected tropical disease roadmap revisions and domestic essential medicine list updates redirect public procurement volumes across formulation and delivery categories.
Market Dynamics
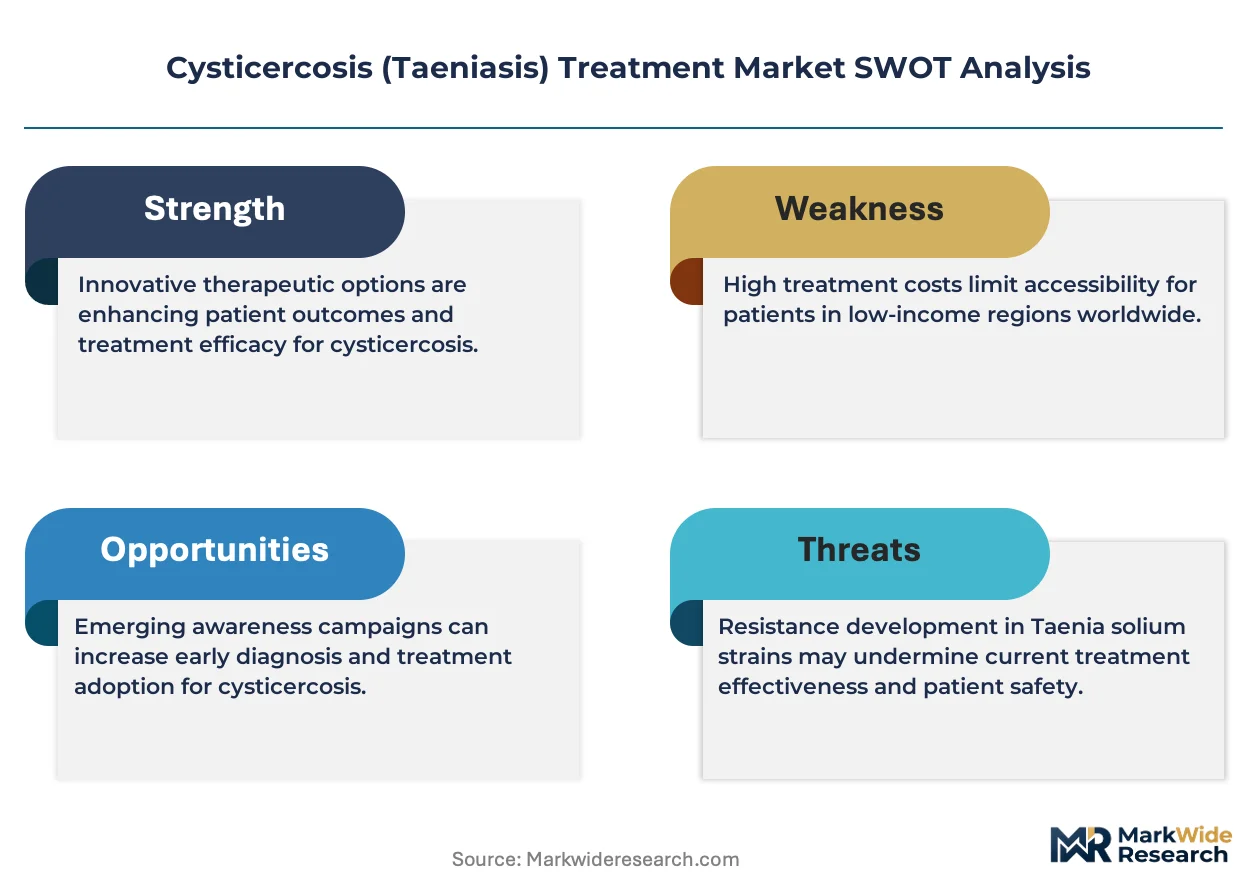
WHO neglected tropical disease roadmap revisions are redirecting public procurement volumes toward mass drug administration formulations, compressing margins for originator manufacturers while expanding generic albendazole and praziquantel tender participation.
Growth Catalysts
- Brazilian national deworming campaigns:SUS procurement expansion for school-based albendazole distribution is creating predictable volume commitments for qualified suppliers.
- WHO prequalification pathway:Accelerated regulatory review for generic pyrazinoisoquinoline compounds is reducing time-to-tender eligibility for emerging market manufacturers.
- Neuroimaging access expansion:CT and MRI deployment in Peruvian and Mexican public hospitals is improving neurocysticercosis case detection and treatment initiation rates.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for benzimidazoles clusters in Chinese and Indian chemical manufacturing zones, creating single-source vulnerability.
- Reimbursement complexity:Neurocysticercosis hospitalization costs often exceed public insurance caps in low-resource settings, forcing out-of-pocket payment or treatment abandonment.
- Diagnostic substitution:Serological testing for taeniasis faces displacement by stool microscopy in cost-constrained primary care settings, limiting confirmed case identification.
Strategic Opportunities
- Fixed-dose combination development:Albendazole-praziquantel co-formulation for simultaneous intestinal and tissue-stage coverage addresses programmatic efficiency gaps in Ecuadorian and Bolivian control programs.
- Epilepsy integration:Neurocysticercosis treatment embedded within national epilepsy control frameworks in Colombia and Honduras opens hospital pharmacy access beyond parasitology silos.
- Subcutaneous formulation innovation:Long-acting injectable benzimidazole depots for veterinary-human interface management target peri-urban pig-raising communities in Guatemala and El Salvador.
Industry Challenges
- Bioequivalence study capacity:Contract research organization availability for fasting-fed pharmacokinetic trials in endemic populations remains limited, delaying generic dossier submission.
- Cold chain fragmentation:Temperature-sensitive praziquantel suspension distribution to remote Andean and Central American highland clinics requires last-mile infrastructure investment beyond pharmaceutical manufacturer control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cysticercosis (Taeniasis) Treatment Market |
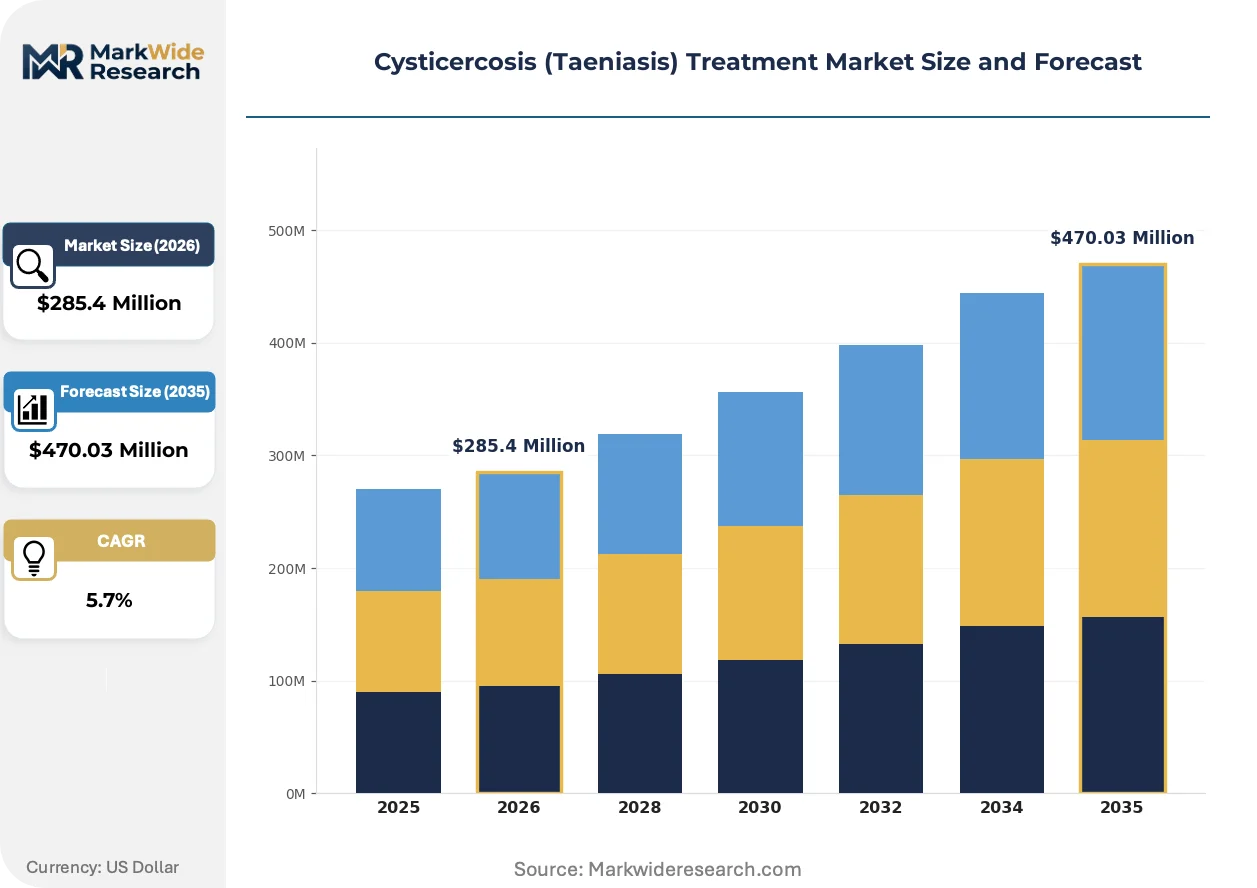
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Praziquantel, Albendazole, Oxamniquine, Niclosamide Therapy Area: Neurocysticercosis, Taeniasis, Subcutaneous Cysticercosis, Muscular Cysticercosis End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Delivery Mode: Oral, Intravenous, Intramuscular, Subcutaneous |
| Companies Covered | GlaxoSmithKline, Bayer, Cipla, Pfizer Inc, Merck & Co., Inc., Amedra Pharmaceuticals, Ranbaxy, Taj Pharmaceuticals, Lupin Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cysticercosis (Taeniasis) Treatment Market Strategic Shifts
Point-of-care diagnostic deployment and formulation stability improvements are compressing the interval between symptom presentation and effective therapy initiation in resource-limited settings.
Lyophilized praziquantel oral disintegrating tablets eliminate the water requirement for administration in field conditions. Ministries of health in Madagascar and Mozambique are piloting these formulations within community-directed treatment platforms. This technology is rendering obsolete the need for direct observed therapy in school-based deworming programs.
EPA pharmaceutical manufacturing effluent guidelines are constraining production site location decisions for benzimidazole API synthesis. Facilities in the US and EU face higher compliance capital requirements than Asian competitors. Generic manufacturers are responding by consolidating fermentation and synthesis operations in Indian pharmaceutical clusters with integrated effluent treatment infrastructure.
Hospital procurement consolidation across Latin American public health systems is shifting purchasing authority from individual facility pharmacists to centralized ministry tenders. Group purchasing organizations in Mexico and Colombia now negotiate multi-year albendazole supply agreements. This concentration is most visible in neurocysticercosis treatment categories where hospital pharmacy budgets merge with national epilepsy program allocations.
Cysticercosis (Taeniasis) Treatment Market Segmentation
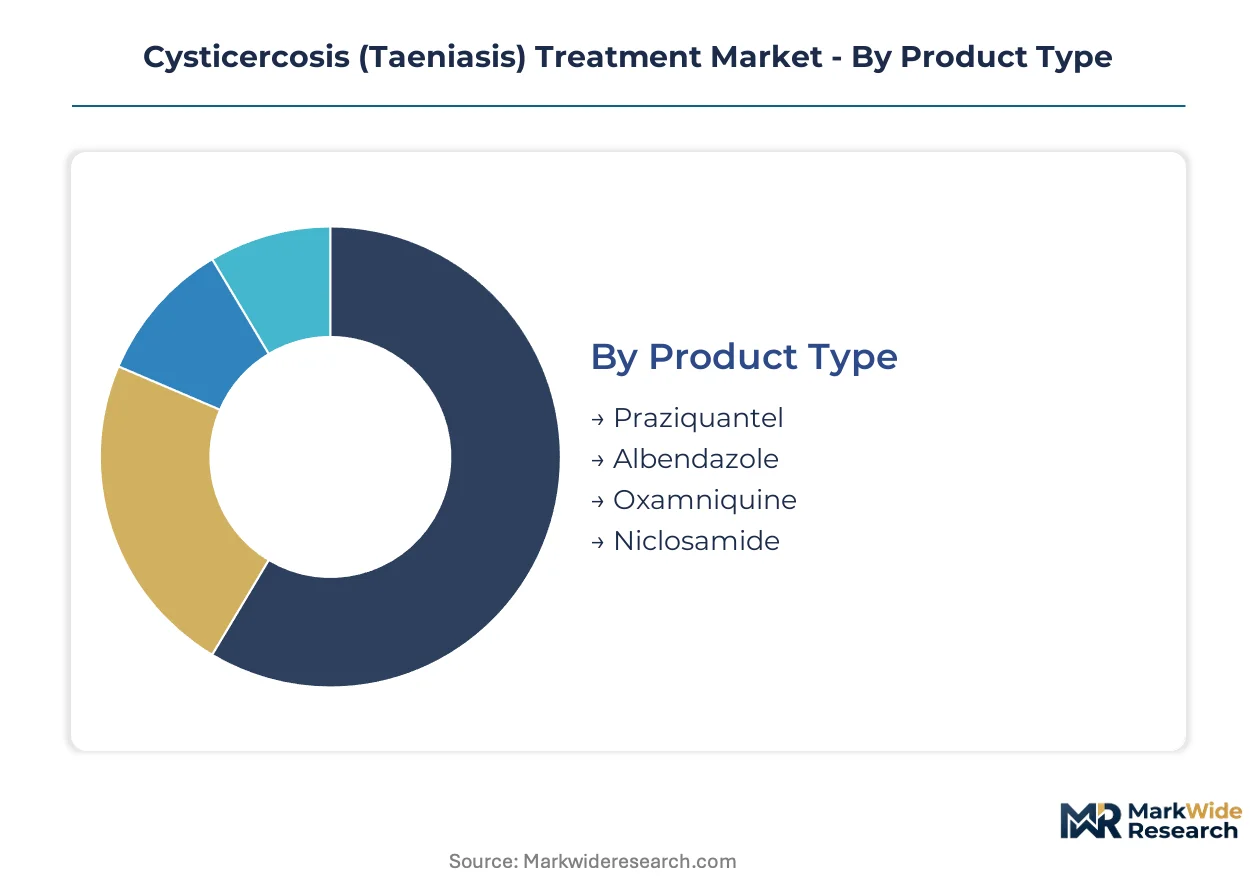
Therapeutic segmentation in cysticercosis treatment determines procurement channel selection, margin structure, and regulatory pathway complexity. Mass drug administration programs favor oral formulations with extended ambient stability, while hospital-based neurocysticercosis therapy commands specialized delivery infrastructure and reimbursement negotiation.
Product Type:
After-sales service intensity concentrates in praziquantel and albendazole supply chains, where WHO prequalification maintenance and cold chain compliance generate recurring vendor obligations.
- Praziquantel:Pyrazinoisoquinoline compound disrupting parasite calcium homeostasis through voltage-gated channel modulation. Brazilian SUS tenders and Ecuadorian national deworming campaigns drive volume concentration, with temperature-sensitive suspension formulations requiring last-mile infrastructure investment.
- Albendazole:Benzimidazole prodrug inhibiting microtubule polymerization and glucose uptake in larval cestodes. Mexican public hospital procurement for neurocysticercosis epilepsy co-management concentrates demand, though API supply clustering in Indian and Chinese chemical zones creates single-source vulnerability.
- Oxamniquine:Tetrahydroquinoline derivative with schistosomicidal cross-utility in select Latin American formularies.
- Niclosamide:Salicylanilide compound relegated to secondary intestinal taeniasis indications in cost-constrained primary care settings.
By volume, albendazole leads through school-based distribution scale. By growth pace, praziquantel is expanding most quickly via neurocysticercosis hospital pharmacy access.
Therapy Area:
Cost tier stratification separates acute hospital-managed conditions from community-delivered preventive chemotherapy, with reimbursement complexity escalating across the severity gradient.
- Neurocysticercosis:Central nervous system larval invasion presenting as acquired epilepsy, hydrocephalus, or intracranial hypertension. Colombian and Honduran national epilepsy control frameworks embed treatment within neurology service reimbursement, expanding hospital pharmacy access beyond parasitology silos.
- Taeniasis:Intestinal adult tapeworm colonization targeted by mass drug administration for transmission interruption. Peruvian and Bolivian school-based deworming campaigns generate the largest addressable population, though diagnostic substitution by stool microscopy limits confirmed case identification.
- Subcutaneous Cysticercosis:Palpable nodular presentations managed in Guatemalan and Salvadoran peri-urban clinics with pig-raising interface exposure.
- Muscular Cysticercosis:Skeletal muscle parenchymal involvement requiring imaging confirmation in secondary care settings.
By patient volume, taeniasis dominates through preventive chemotherapy reach. By clinical urgency and reimbursement rate, neurocysticercosis commands priority positioning.
End User:
Customer type determines procurement authority concentration, with centralized ministry tenders displacing individual facility purchasing across Latin American public health systems.
- Hospitals:Tertiary care centers managing severe neurocysticercosis with CT and MRI diagnostic capacity. Mexican and Colombian group purchasing organizations negotiate multi-year supply agreements merging pharmacy budgets with national epilepsy program allocations.
- Clinics:Primary and secondary care facilities handling uncomplicated taeniasis and subcutaneous presentations. Madagascar and Mozambique community-directed treatment platforms pilot lyophilized oral disintegrating tablets eliminating water requirements.
- Homecare:Self-administered oral regimens in school-based deworming with direct observed therapy substitution.
- Ambulatory Surgical Centers:Limited role for subcutaneous nodule excision in specialized dermatology or general surgery settings.
By procurement value, hospitals concentrate spending through neurocysticercosis hospitalization bundling. By treatment episode count, clinics process the majority of taeniasis encounters.
Delivery Mode:
Supply concentration in oral formulation manufacturing reflects programmatic suitability for mass drug administration, while parenteral production clusters in hospital-contracted sterile facilities.
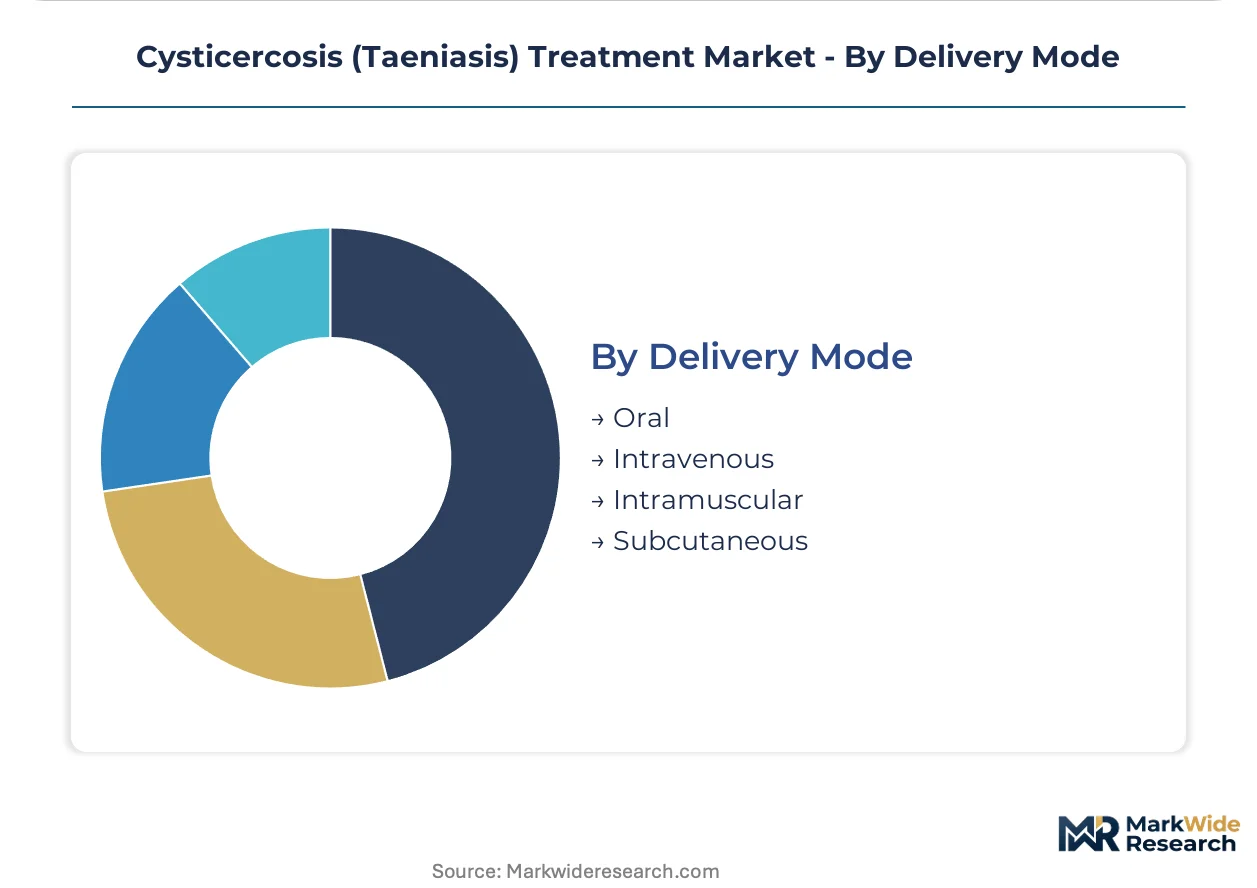
- Oral:Tablet and suspension presentations dominating volume through programmatic deployability. Albendazole chewable tablets and praziquantel 600mg scored tablets comprise standard WHO essential medicine list configurations for school-based distribution.
- Intravenous:Hospital-administered benzimidazole and praziquantel formulations for severe neurocysticercosis requiring inpatient management and seizure control.
- Intramuscular:Limited application in resource-constrained settings lacking intravenous access infrastructure.
- Subcutaneous:Experimental long-acting benzimidazole depots under development for veterinary-human interface management in peri-urban pig-raising communities.
By dose volume, oral formulations capture overwhelming share through mass drug administration scale. By innovation investment intensity, subcutaneous depot development shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian public health procurement diverges markedly from Mexican hospital-centric purchasing, with the former emphasizing school-based mass distribution while the latter concentrates neurocysticercosis therapy within tertiary epilepsy services. Peruvian and Bolivian campaigns prioritize intestinal taeniasis interruption through community platforms. Southeast Asian national programs in Madagascar and Mozambique pilot field-adapted formulations eliminating cold chain dependencies.
Brazil
SUS procurement expansion for school-based albendazole distribution generates predictable volume commitments for qualified suppliers. ANVISA bioequivalence requirements shape generic tender eligibility for benzimidazole entrants. São Paulo and Minas Gerais pharmaceutical clusters house formulation facilities serving the national deworming calendar.
Mexico
Group purchasing organizations negotiate multi-year supply agreements merging hospital pharmacy budgets with national epilepsy program allocations. COFEPRIS regulatory pathways align with WHO prequalification standards for praziquantel registration. Mexico City metropolitan hospitals concentrate neurocysticercosis diagnostic capacity through CT and MRI deployment.
Peru
Neuroimaging access expansion in public hospitals improves case detection and treatment initiation rates for central nervous system larval invasion. The Ministry of Health integrates cysticercosis therapy within regional epilepsy control frameworks. Lima and Arequipa medical centers anchor specialized neurology service reimbursement.
Ecuador
National deworming campaigns generate demand for fixed-dose combination development addressing simultaneous intestinal and tissue-stage coverage. The national pharmaceutical regulator enforces stability requirements for field-deployable formulations. Quito-based procurement authorities coordinate Andean highland distribution overcoming cold chain fragmentation.
Madagascar
Community-directed treatment platforms pilot lyophilized praziquantel oral disintegrating tablets eliminating water requirements for administration. Ministry of health programs substitute direct observed therapy with self-administered regimens in remote clinic settings. Antananarivo pharmaceutical distribution hubs manage last-mile infrastructure to highland communities.
Cysticercosis (Taeniasis) Treatment Market Competitive Environment
Capability concentration sits with originator manufacturers holding decades of production expertise; scale advantage sits with emerging market generic houses exploiting API supply clustering in Asian chemical zones. The vendor base stratifies across three tiers: multinational pharmaceutical corporations with WHO prequalification maintenance infrastructure, mid-cap national champions capturing domestic tender share, and specialized generic exporters competing on bioequivalence dossier speed. Dominant competitive moves include backward integration into benzimidazole fermentation capacity and strategic partnerships with endemic country ministries for multi-year supply agreements.
Within the originator tier, Merck & Co., Inc. and GlaxoSmithKline occupy positions anchored by manufacturing scale and regulatory dossier breadth respectively. Among emerging market generic houses, Cipla and Lupin Pharmaceuticals, Inc. exemplify the mid-cap national champion archetype competing on WHO prequalification pathway navigation. Bayer represents the quality-certification-focused competitor leveraging regulatory dossier breadth across endemic markets.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Bayer |
| Cipla |
| Pfizer Inc |
| Merck & Co., Inc. |
| Amedra Pharmaceuticals |
| Ranbaxy |
| Taj Pharmaceuticals |
| Lupin Pharmaceuticals, Inc. |
| Others |
Value Chain & Pricing Dynamics
Indian and Chinese chemical manufacturing zones concentrate benzimidazole and pyrazinoisoquinoline API production, anchoring margin capture downstream with originator manufacturers holding WHO prequalification infrastructure while generic houses compete on bioequivalence dossier speed. This upstream clustering shapes pricing power across tender-driven procurement channels in endemic Latin American and Southeast Asian markets.
Pricing Analysis
Long-term offtake agreements dominate public procurement, with Brazilian SUS and Mexican group purchasing organizations locking multi-year supply commitments for albendazole and praziquantel. Three-tier pricing structure across WHO-prequalified originators, mid-cap national champions, and specialized generic exporters reflects certification grade and cold chain compliance bundling. Cost compression in standard oral formulations intensifies as Indian pharmaceutical clusters expand fermentation capacity. Price sensitivity concentrates in school-based deworming programs, while neurocysticercosis hospital procurement shows greater tolerance for premium positioning.
Supply Chain Analysis
Contract manufacturing for benzimidazole APIs clusters in Hyderabad and Ahmedabad pharmaceutical corridors, with pyrazinoisoquinoline synthesis concentrated in Zhejiang and Jiangsu chemical zones. Active pharmaceutical ingredient production draws from imidazole and isoquinoline feedstocks, with praziquantel precursors resting on specialized alkaloid derivatives. Single-source vulnerability in Chinese API intermediates creates exposure to environmental regulatory enforcement. Distribution runs through ministry-coordinated cold chain networks to Andean highland clinics and remote Southeast Asian health posts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent pharmaceutical manufacturers face substitution pressure from emerging market generic houses accelerating WHO prequalification timelines, requiring defensive positioning around manufacturing scale and regulatory dossier maintenance.
For Market Incumbents: Entrench manufacturing scale advantage through backward integration into benzimidazole fermentation capacity in Indian pharmaceutical clusters. Prioritize WHO prequalification maintenance infrastructure to defend tender eligibility against emerging generic entrants compressing margins through accelerated bioequivalence pathways. For New Entrants and Emerging Players: Pursue fixed-dose combination development for albendazole-praziquantel co-formulation targeting Ecuadorian and Bolivian national deworming campaigns. Community-directed treatment platforms in Madagascar and Mozambique offer the most penetrable entry point, with lyophilized oral disintegrating tablet technology providing differentiation against incumbent suspension formulations. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap national champions with established ANVISA or COFEPRIS regulatory pathways and existing ministry tender relationships. Long-term viability hinges on consolidation resilience against API supply concentration in Asian chemical zones. Watch for WHO neglected tropical disease roadmap revisions redirecting procurement volumes as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Fermentation | Captive benzimidazole supply secures margin against Indian and Chinese chemical zone volatility. |
| WHO Prequalification Pathway Navigation | Accelerated regulatory review unlocks Brazilian SUS and Colombian ministry tender eligibility. |
| Fixed-Dose Combination Development | Albendazole-praziquantel co-formulation addresses programmatic efficiency gaps in Andean control programs. |
| Cold Chain Infrastructure Partnership | Last-mile temperature-controlled distribution reaches remote highland clinics beyond manufacturer direct control. |
| Epilepsy Program Integration | Neurocysticercosis therapy embedded within Colombian and Honduran national epilepsy frameworks expands hospital pharmacy access. |
Study Parameters
Initial hypotheses were tested against primary input from pharmaceutical procurement managers at Brazilian and Mexican ministry health programs, regulatory affairs leads at WHO-prequalified manufacturers, and hospital pharmacy directors managing neurocysticercosis therapy. These perspectives were refined through secondary validation against FDA filings, ANVISA bioequivalence determinations, COFEPRIS registration databases, and WHO prequalification lists. Bottom-up tender volume aggregation and top-down epidemiological burden estimation were triangulated to establish market sizing.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, therapy area, end user, and delivery mode. CAGRs were derived from epidemiological trend projections and procurement calendar commitments. Forecast inputs incorporated school-based deworming campaign scale-ups, neuroimaging deployment trajectories in Peruvian and Mexican public hospitals, and API supply capacity expansion in Indian pharmaceutical clusters.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by emerging market generic houses or disruptive formulation innovation from contract research organizations would shift outcomes. Epidemiological surveillance data volatility and ministry budget reallocation risks could revise projections. Quarterly review of WHO neglected tropical disease roadmap implementation and national essential medicine list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Morquio Syndrome Treatment Market