
 Global Fabry Disease Treatment Market | 2026-2036
Global Fabry Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fabry Disease Treatment Market Foresight
Specialty pharmacy distribution for orphan biologics is fragmenting as manufacturers build direct-to-clinic channels alongside traditional wholesalers. Sanofi Genzyme dominates legacy enzyme replacement supply through established infusion center networks. Amicus Therapeutics differentiates via oral pharmacological chaperone technology that reduces clinic dependency. Takeda Pharmaceuticals extends its rare disease footprint through global logistics platforms that bypass conventional distribution tiers.
Fabry disease treatment encompasses therapeutic interventions targeting alpha-galactosidase A deficiency, including recombinant enzyme infusions, small-molecule chaperones, and emerging gene editing platforms designed to clear globotriaosylceramide accumulation from vascular endothelium and renal tissue. Intravenous enzyme replacement therapy anchors current clinical practice with established long-term efficacy data in cardiac and renal endpoints, while gene therapy represents the fastest-expanding segment as lentiviral and AAV vector programs advance through registrational trials. Oral tablet formulations for pharmacological chaperones command premium positioning in patient populations with amenable mutations, creating distinct margin pools separate from infusion-dependent protocols.
FDA orphan drug exclusivity provisions and EMA's PRIME designation for rare disease therapies shape development economics by compressing regulatory timelines and extending market protection. Japan's PMDA Sakigake pathway accelerates local approval for innovative Fabry therapies, creating parallel access tracks distinct from Western frameworks. Stakeholders must monitor gene therapy durability data and payer willingness to shift from chronic infusion reimbursement toward one-time curative pricing constructs.
Market Dynamics
Gene therapy durability data is compressing development timelines as sponsors negotiate curative pricing constructs against chronic infusion reimbursement frameworks, forcing payers to recalculate lifetime cost models for Fabry disease management.
Growth Catalysts
- EMA PRIME Designation:Accelerated assessment pathways compress regulatory review periods for novel Fabry therapies, shortening time-to-market for sponsors with breakthrough status.
- Oral Pharmacological Chaperones:Tablet formulations reduce clinic dependency and expand addressable populations with amenable GLA mutations beyond infusion-capable patients.
- Japan's Sakigake Pathway:PMDA's early approval framework creates parallel access tracks for innovative therapies, rewarding first-in-class development with priority review benefits.
Market Restraints
- Plasma-Derived Enzyme Supply Concentration:Legacy recombinant production relies on bioreactor capacity concentrated in Belgium and the United States, creating geographic vulnerability to manufacturing disruptions.
- FDA Orphan Exclusivity Duration:Seven-year market protection limits biosimilar entry but also constrains price competition that could expand patient access in underpenetrated markets.
- Infusion Center Infrastructure Gaps:Rural and secondary urban areas lack certified administration sites, restricting therapy delivery to metropolitan clusters with established nephrology and genetics programs.
Strategic Opportunities
- Direct-to-Clinic Distribution:Manufacturers bypassing wholesale tiers capture margin and improve cold-chain control for temperature-sensitive biologics.
- Home Infusion Protocols:Subcutaneous enzyme formulations and nursing networks enable administration outside hospital settings, reducing facility overhead and patient travel burden.
- Germany's Orphan Drug Reimbursement:AMNOG's early benefit assessment framework provides rapid price negotiation pathways for ultra-rare conditions with demonstrated clinical value.
Industry Challenges
- Gene Therapy Vector Manufacturing Scale-Up:AAV and lentiviral production requires specialized facilities with limited global capacity, constraining supply for registrational trials and commercial launch.
- Mutation-Specific Prescreening Complexity:Pharmacological chaperone eligibility demands GLA genotype testing infrastructure that fragments prescribing decisions across academic medical centers and community specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fabry Disease Treatment Market |
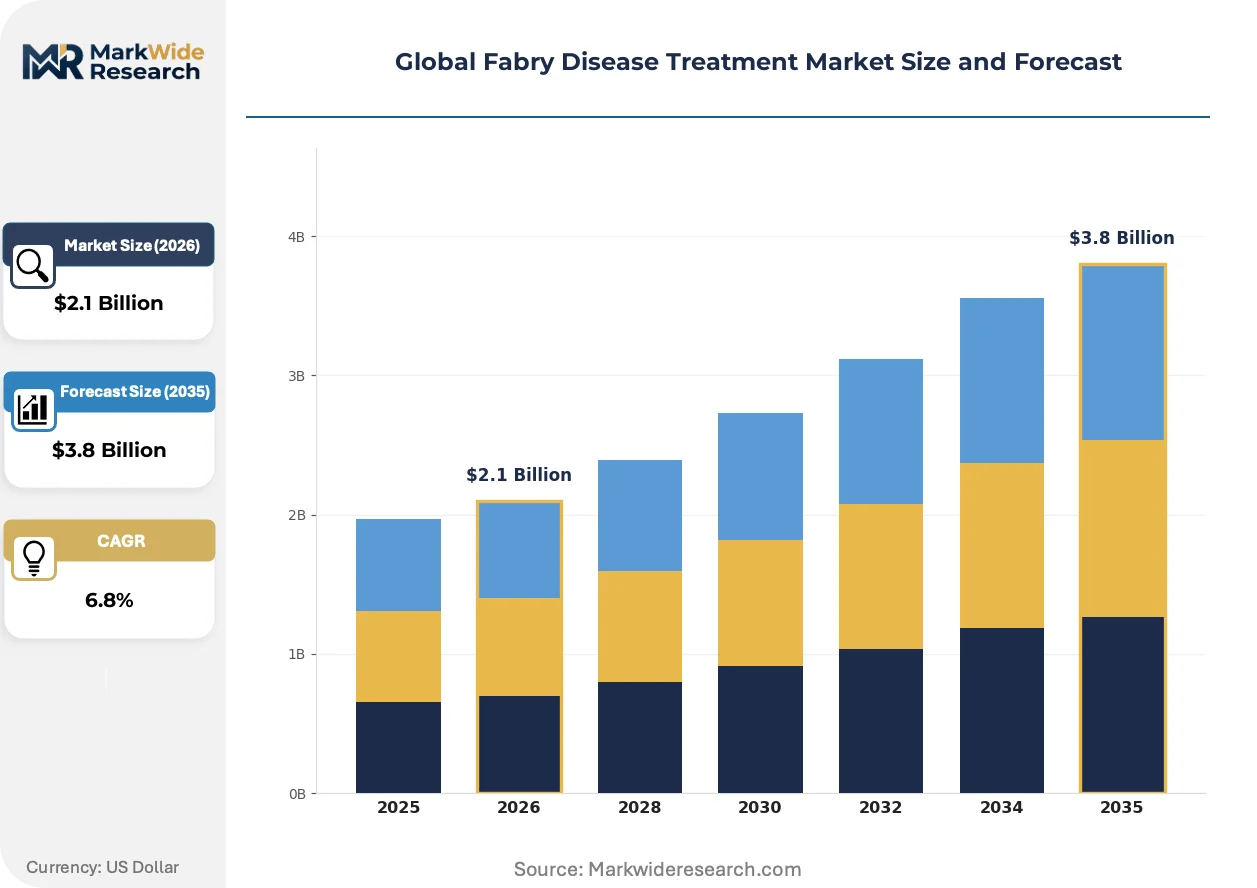
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Enzyme Replacement Therapy, Pharmacological Chaperones, Substrate Reduction Therapy, Gene Therapy Dosage Form: Intravenous Infusion, Oral Tablets, Injectable Solutions, Sublingual Films Route of Administration: Intravenous, Oral, Subcutaneous, Intramuscular End User: Specialty Clinics, Research Institutes, Home Healthcare Providers, Genetic Counseling Centers |
| Companies Covered | Sanofi Genzyme, Amicus Therapeutics, Takeda Pharmaceuticals, JCR Pharmaceuticals, Protalix BioTherapeutics, Chiesi Farmaceutici, ISU Abxis, Idorsia Pharmaceuticals, Green Cross Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fabry Disease Treatment Market Shifts & Advancements
Digital biomarker platforms and decentralized trial models are compressing evidence-generation cycles, enabling sponsors to demonstrate treatment effects with smaller patient populations than traditional renal and cardiac endpoint studies required.
AAV-mediated gene transfer is digitizing patient monitoring workflows through implantable or wearable devices that track enzyme expression and substrate clearance in real time. Academic medical centers in Boston and Munich are piloting these integrated systems for post-infusion surveillance. The technology is digitizing the transition from episodic clinic visits to continuous remote monitoring, reducing site burden while capturing richer longitudinal data.
REACH's extended safety data requirements for novel biologics are extending development timelines for European submissions, particularly for gene therapies with limited long-term follow-up. Sponsors are responding by front-loading European patient exposure in Phase II expansion cohorts to satisfy EMA's cumulative safety database expectations before formal filing.
Specialty pharmacy networks are fragmenting as manufacturers establish captive distribution arms that control inventory allocation and patient onboarding. Traditional wholesalers are losing share in orphan biologics as Sanofi Genzyme, Amicus Therapeutics, and Takeda Pharmaceuticals build direct relationships with infusion centers and hospital pharmacies. This channel shift is most pronounced in the United States and Germany, where payer concentration enables centralized contracting with limited distribution networks.
Global Fabry Disease Treatment Market Segmentation
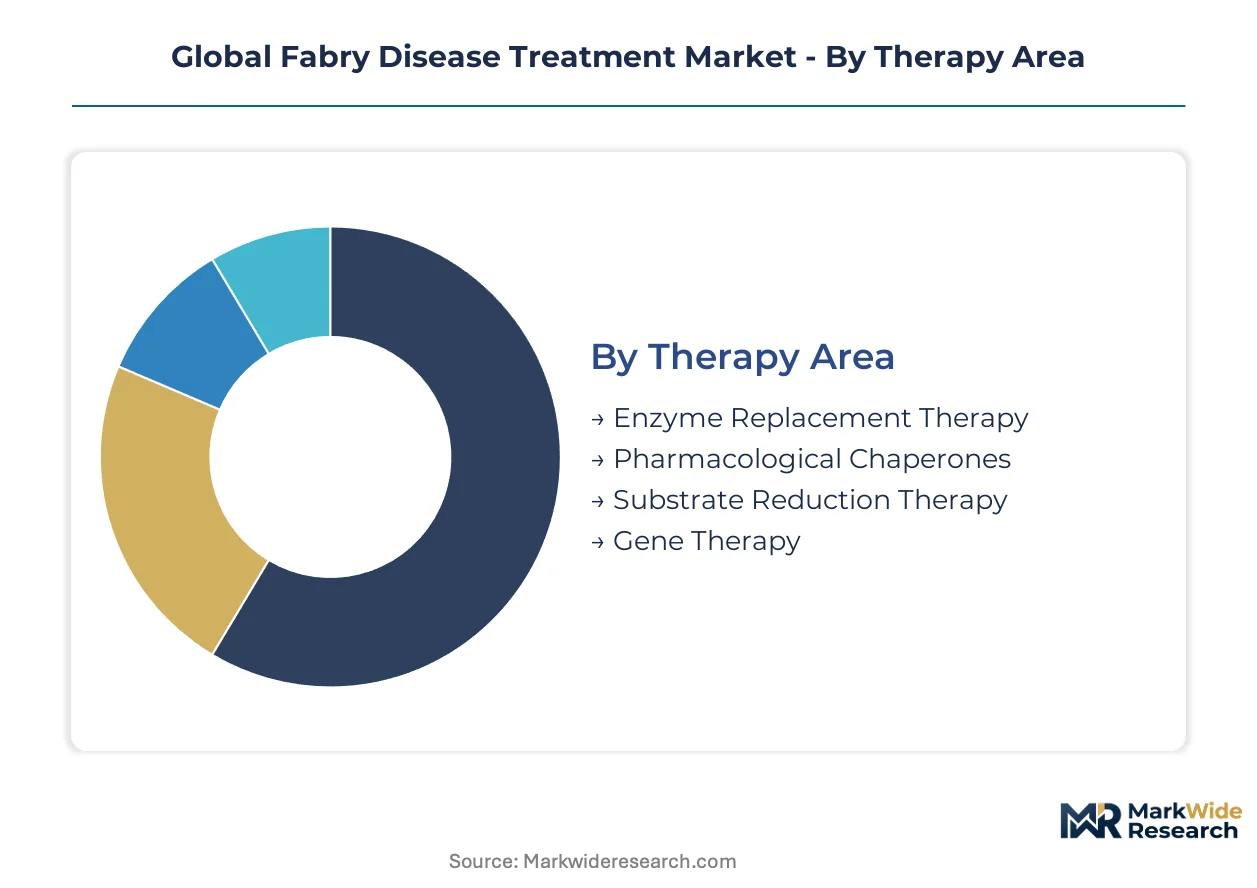
Fabry disease treatment segmentation reveals divergent commercial architectures across therapy modalities and care delivery settings. Each category reflects distinct margin profiles, regulatory pathways, and infrastructure requirements that reshape competitive positioning.
Therapy Area:
Mature infusion protocols anchor current revenue while emerging genetic interventions compress development timelines.
- Enzyme Replacement Therapy:Intravenous recombinant alpha-galactosidase A infusions clear globotriaosylceramide deposits from renal and cardiac tissue. Demand concentrates in the United States and Germany where payer frameworks for chronic ultra-rare disease management are most developed, though bioreactor capacity constraints in Belgium and the United States create supply vulnerability.
- Pharmacological Chaperones:Oral small-molecule formulations stabilize mutant enzyme folding in patients with amenable GLA mutations. Japan's PMDA Sakigake pathway accelerates approval for these tablet-based alternatives, reducing clinic dependency and expanding addressable populations beyond infusion-capable patients.
- Substrate Reduction Therapy:Ceramide analogs inhibit glycosphingolipid synthesis upstream of enzyme deficiency.
- Gene Therapy:AAV and lentiviral vectors deliver functional GLA gene copies for durable enzyme expression.
Enzyme Replacement Therapy retains volume leadership; Gene Therapy holds the steepest expansion curve.
Dosage Form:
Cost tier stratification separates premium biologics from convenience-oriented oral formats.
- Intravenous Infusion:Lyophilized recombinant enzyme preparations require cold-chain distribution to certified infusion centers. Supply concentrates in metropolitan clusters with established nephrology programs, leaving rural areas with limited access.
- Oral Tablets:Pharmacological chaperone tablets eliminate facility overhead and enable home-based administration. Germany's AMNOG framework provides rapid reimbursement negotiation for these patient-convenient formats, creating distinct margin pools separate from hospital-dependent protocols.
- Injectable Solutions:Prefilled syringes for subcutaneous enzyme administration.
- Sublingual Films:Dissolvable strips for rapid buccal absorption of small-molecule therapies.
Intravenous Infusion dominates revenue contribution; Oral Tablets are climbing the fastest.
Route of Administration:
Application context determines route selection — hospital-based versus ambulatory versus home settings.
- Intravenous:Enzyme replacement requires sterile administration in certified infusion centers with cardiac monitoring capability. The United States maintains the densest network of these specialized facilities, though geographic concentration leaves secondary urban markets underserved.
- Oral:Pharmacological chaperones and substrate reducers enable self-administration without clinical supervision. Japan's aging population drives preference for these independence-preserving formats, reducing caregiver burden and travel requirements.
- Subcutaneous:Emerging enzyme formulations administered via home nursing networks.
- Intramuscular:Depot injections for sustained-release gene therapy expression monitoring.
Intravenous routes retain procedure volume leadership; Subcutaneous delivery is gaining share fastest.
End User:
Customer type fragmentation reflects divergent procurement authority and patient flow patterns.
- Specialty Clinics:Dedicated nephrology and genetics centers manage long-term enzyme replacement protocols with established infusion infrastructure. These sites concentrate in Boston, Munich, and Tokyo where academic medical center density supports complex rare disease care.
- Home Healthcare Providers:Nursing networks and specialty pharmacies enable subcutaneous administration outside hospital settings. Germany's structured home care reimbursement creates favorable economics for these decentralized models, reducing facility overhead while maintaining clinical oversight.
- Research Institutes:Academic centers conducting gene therapy trials and natural history studies.
- Genetic Counseling Centers:Mutation screening sites that identify chaperone-eligible patients.
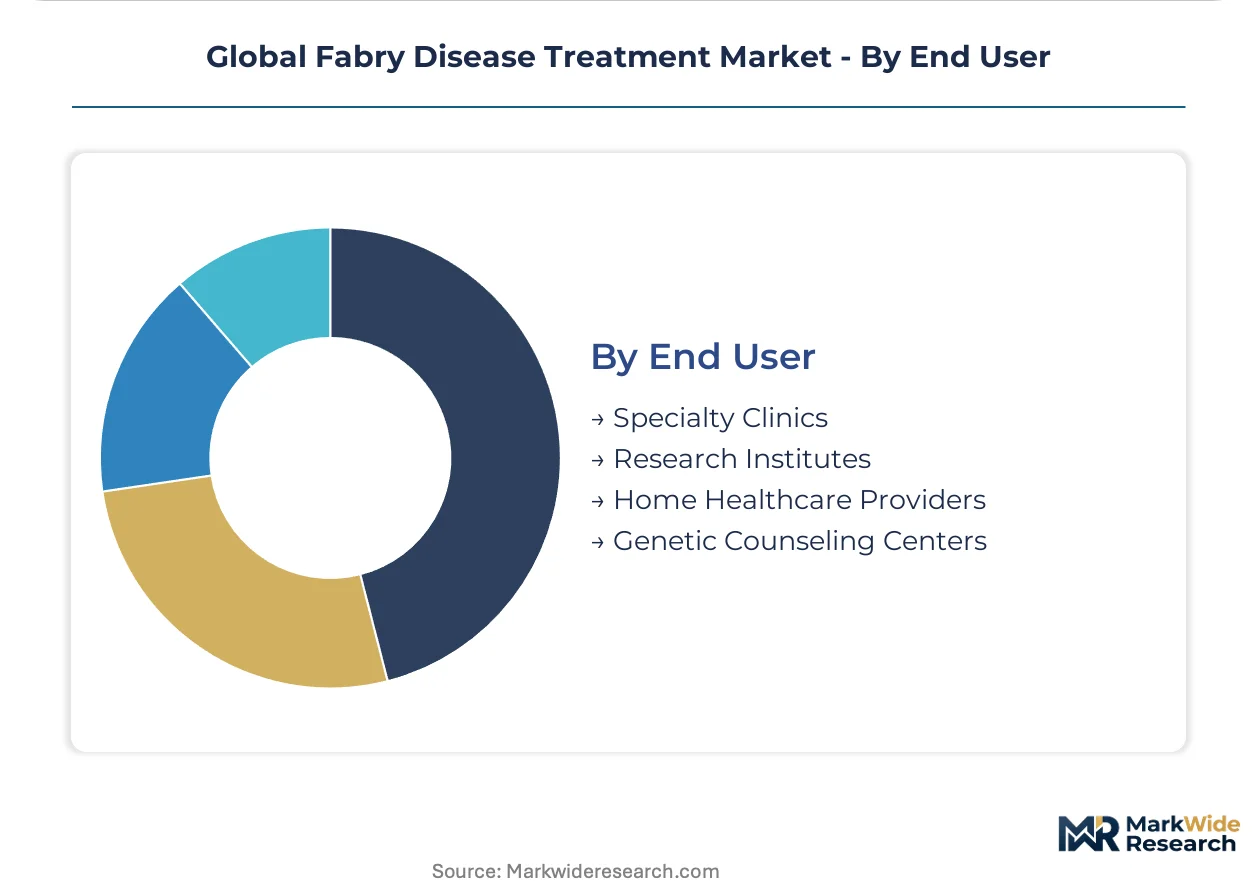
Specialty Clinics retain patient volume leadership; Home Healthcare Providers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where orphan drug reimbursement frameworks sustain premium positioning, while Japan's accelerated approval pathways compress commercialization timelines for novel modalities.
United States
FDA orphan drug exclusivity provisions and established infusion center networks anchor demand for enzyme replacement protocols. The country's national pharmaceutical regulator maintains seven-year market protection for novel therapies, creating extended revenue windows for sponsors. Boston's academic medical center cluster pilots integrated gene therapy monitoring systems that digitize post-treatment surveillance.
Germany
AMNOG's early benefit assessment framework provides rapid price negotiation pathways for ultra-rare conditions with demonstrated clinical value. EMA accelerated assessment pathways compress regulatory review periods for breakthrough-designated therapies. Munich's nephrology and genetics centers concentrate patient volume for long-term enzyme replacement management.
Japan
PMDA's Sakigake pathway rewards first-in-class development with priority review benefits for innovative Fabry therapies. The country's aging population drives preference for oral tablet formulations that reduce caregiver burden and travel requirements. Tokyo's specialty clinic density supports complex rare disease care coordination for pharmacological chaperone eligibility screening.
United Kingdom
NHS England's specialized commissioning framework concentrates funding decisions for high-cost orphan biologics at the national level. The country's national pharmaceutical regulator aligns with EMA pathways while maintaining distinct health technology assessment processes. London's academic medical centers participate in multinational gene therapy trials and natural history studies.
Switzerland
Swissmedic maintains streamlined approval processes for therapies with prior EMA or FDA authorization, reducing redundant regulatory burden. The country's pharmaceutical pricing framework references German and French benchmarks while preserving negotiation flexibility for ultra-rare conditions. Basel's biotech cluster hosts logistics platforms that bypass conventional distribution tiers for temperature-sensitive biologics.
Global Fabry Disease Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in manufacturing and vector supply. The vendor base stratifies across three tiers: established enzyme replacement suppliers with captive infusion networks, oral formulation developers reducing clinic dependency, and gene therapy platforms negotiating curative pricing constructs. Dominant competitive moves include direct-to-clinic distribution channel establishment and subcutaneous formulation development for home administration.
Among North American developers, Sanofi Genzyme and Amicus Therapeutics occupy distinct archetype positions. Sanofi Genzyme represents the established platform integrator with legacy supply relationships and certified infusion center density. Amicus Therapeutics exemplifies the oral formulation specialist reducing facility overhead through tablet-based alternatives. Takeda Pharmaceuticals anchors the Asia-Pacific contingent, extending rare disease footprint through global logistics capabilities that bypass conventional wholesale tiers.
| Leading Market Players |
|---|
| Sanofi Genzyme |
| Amicus Therapeutics |
| Takeda Pharmaceuticals |
| JCR Pharmaceuticals |
| Protalix BioTherapeutics |
| Chiesi Farmaceutici |
| ISU Abxis |
| Idorsia Pharmaceuticals |
| Green Cross Corporation |
| Others |
Supply & Pricing Matrix
Bioreactor undercapacity in Belgium and the United States compresses enzyme replacement supply and amplifies pricing power for manufacturers with captive production assets, forcing sponsors to prioritize yield optimization over volume discounting in contract negotiations with payers.
Pricing Analysis
The customization-premium spread separates standard infusion protocols from mutation-matched pharmacological chaperone regimens, with amenable GLA genotype testing creating tiered access based on biomarker eligibility rather than pure clinical indication. Price differentiation hinges on administration setting—hospital-based enzyme infusions command facility fees that oral tablet alternatives bypass—and on orphan exclusivity duration, where FDA seven-year protection sustains premium positioning. Pricing pressure stems from gene therapy curative pricing negotiations that force lifetime cost recalculations against chronic infusion models. Payers in Germany and Japan exhibit highest price sensitivity due to centralized health technology assessment frameworks, while United States commercial plans remain least sensitive given patient volume dispersion across fragmented insurance pools.
Supply Chain Analysis
Export-control regimes for viral vector manufacturing equipment limit AAV and lentiviral production capacity flows between the United States, Belgium, and Switzerland, constraining gene therapy scale-up for registrational trials. Supply concentrates in Belgium for recombinant enzyme bioreactors, the United States for plasmid DNA and cell bank materials, and Japan for pharmacological chaperone active pharmaceutical ingredients. Raw material dependencies include fetal bovine serum for cell culture, specialized chromatography resins for purification, and cryopreservation media for vector stability. Single-source vulnerability pervades certified infusion center networks, where metropolitan cluster concentration leaves rural areas unserved. Distribution runs through direct-to-clinic channels that Sanofi Genzyme, Amicus Therapeutics, and Takeda Pharmaceuticals operate alongside diminishing wholesale tier participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy platforms are reconfiguring Fabry disease economics toward one-time curative pricing, with AAV vector durability data and real-time enzyme expression monitoring creating interoperability between treatment administration and longitudinal patient surveillance ecosystems.
For Market Incumbents: Harden infusion center network exclusivity through subcutaneous formulation partnerships with home healthcare providers, reducing clinic dependency erosion from oral chaperone competitors. Deepen backward integration into plasmid DNA manufacturing to secure vector supply for gene therapy pipeline transitions. Prioritize FDA breakthrough therapy designation maintenance to compress regulatory timelines against emerging lentiviral platform entrants.
For New Entrants and Emerging Players: Build out pharmacological chaperone eligibility screening infrastructure in community nephrology settings, capturing mutation-amenable patients outside academic medical center concentration. Target Japan's Sakigake pathway for accelerated tablet formulation approval, leveraging PMDA priority review benefits ahead of Western regulatory submissions. Deploy direct-to-patient digital onboarding to bypass established specialty pharmacy distribution.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzyme replacement suppliers with captive infusion networks and long-term payer contracts, though gene therapy platform acquisitions offer steeper value appreciation contingent on durability data maturation. Platform integrators with vector manufacturing capabilities and global logistics infrastructure represent priority acquisition archetypes across the analysis window. Monitor EMA PRIME designation grants and FDA regenerative medicine advanced therapy conferrals as inflection signals for pipeline value step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | AAV vector capacity expansion in Belgium and Switzerland addresses supply constraints for registrational trials. |
| Direct-to-Clinic Distribution Establishment | Captive channels bypass wholesale tiers and improve cold-chain control for temperature-sensitive biologics. |
| Subcutaneous Formulation Development | Home administration protocols reduce facility overhead and expand addressable geography beyond metropolitan clusters. |
| Mutation-Specific Screening Infrastructure | GLA genotype testing networks fragment prescribing decisions and create chaperone-eligible patient identification. |
| Regulatory Accelerated Pathway Engagement | EMA PRIME and FDA breakthrough designations compress review timelines for novel enzyme and gene therapies. |
Research Methodology
The analysis maps enzyme replacement protocols, pharmacological chaperone tablets, substrate reduction therapies, and gene therapy platforms, each validated through formulary directors at United States commercial payers, regulatory affairs leads at EMA and FDA, and hospital procurement managers at academic medical centers in Boston, Munich, and Tokyo. Primary interviews with infusion center administrators and specialty pharmacy distribution executives combined with secondary validation from ClinicalTrials.gov entries, EMA assessment reports, FDA orphan drug designation databases, and Japan PMDA Sakigake approval records. Bottom-up patient population modeling and top-down revenue triangulation anchored segmentation-specific forecasts.
Assumptions held fixed include current regulatory pathway timelines for orphan biologics and existing reimbursement frameworks for ultra-rare conditions, while gene therapy durability assumptions and payer willingness-to-pay for curative pricing were varied across sensitivity scenarios. Segmentation dimensions encompassed therapy modality, dosage form, route of administration, and end-user setting. CAGRs derived from epidemiological prevalence projections, treatment penetration curves, and pricing evolution models incorporating AMNOG, NICE, and CMS benchmark trajectories. Forecast inputs included bioreactor capacity expansion schedules and vector manufacturing facility commissioning timelines.
Sensitivities concentrate around gene therapy long-term expression durability data, EMA cumulative safety database requirements for novel biologics, and Japan's aging population preference shifts toward oral administration formats. Forecasts reflect these assumptions and acknowledge revision risk from manufacturing disruptions in concentrated production geographies and from payer formulary exclusion actions. Cross-checking against IQVIA prescription audit data and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Ascites Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Global Sciatica Market
Medical Treatment
Otoplasty Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Microwave Ablation Market