
 Tauopathies Treatment Market | 2026-2036
Tauopathies Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tauopathies Treatment Market Outlook
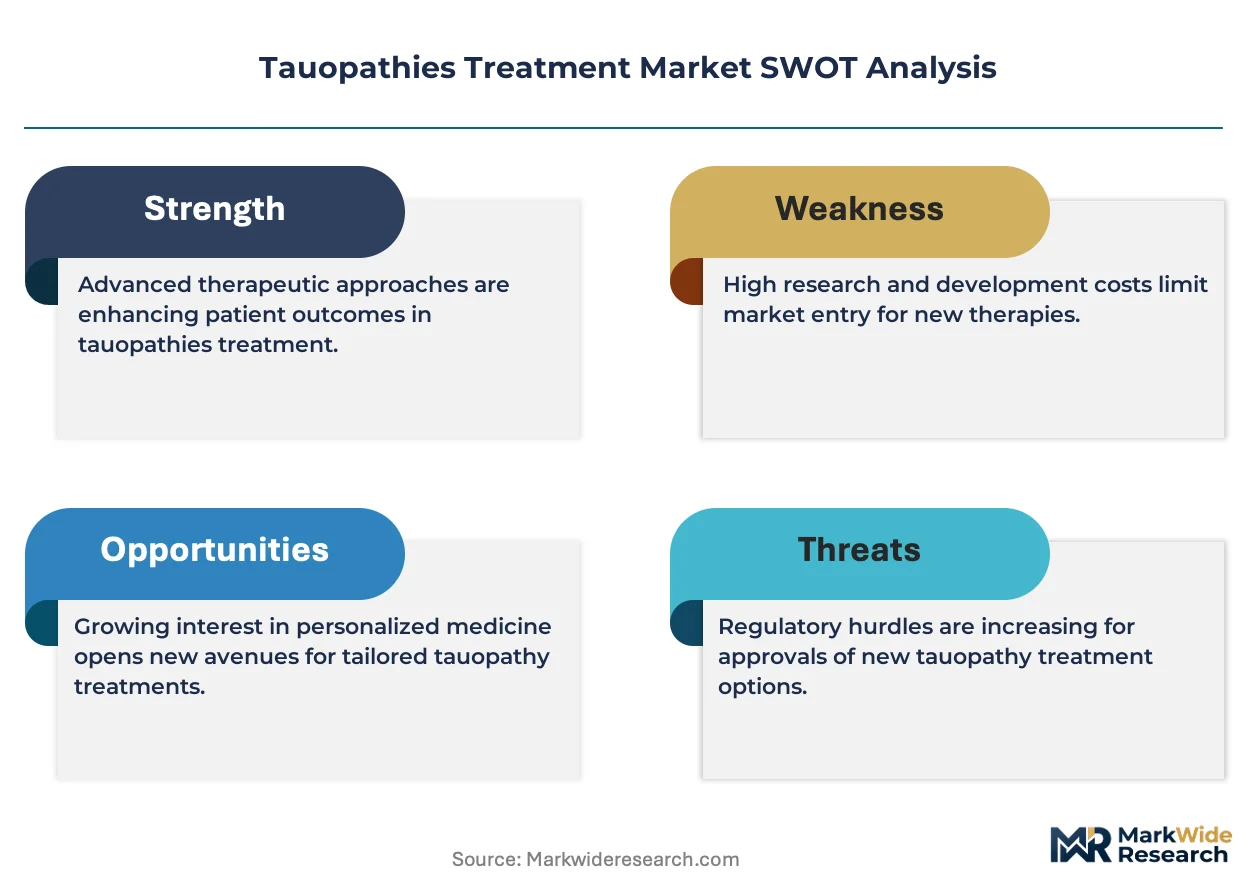
FDA Breakthrough Therapy designation is reorganizing competitive entry timelines for tau-directed drug developers. Eli Lilly and Company leverages its amyloid and tau parallel pipeline investments to sustain manufacturing readiness for anticipated label expansions. Roche Holding AG anchors European clinical trial infrastructure through dedicated neurodegeneration research facilities in Basel. AC Immune SA differentiates via vaccine-platform specialization against competing antibody approaches.
Tauopathies treatment encompasses therapeutic interventions targeting pathological tau protein aggregation, including monoclonal antibodies engineered to bind extracellular tau species and small molecule inhibitors modulating tau phosphorylation kinases. These modalities aim to halt neurofibrillary tangle propagation and preserve cognitive function in progressive neurodegenerative conditions. Monoclonal antibodies command the dominant share of current development investment due to demonstrated blood-brain barrier penetration advances, while gene therapy remains the fastest-expanding category as viral vector delivery systems mature for central nervous system indications. Small molecule inhibitors occupy established margin pools through oral bioavailability and scalable chemical synthesis relative to biologic manufacturing complexity.
FDA, EMA, and the International Council for Harmonisation of Technical Requirements for Pharmaceuticals for Human Use govern tauopathy therapy development through evolving biomarker qualification standards and adaptive trial design frameworks. These regulators increasingly require tau PET imaging validation and cerebrospinal fluid biomarker correlation as surrogate endpoints, elevating diagnostic companion requirements alongside therapeutic approval pathways. Stakeholders must monitor evolving FDA accelerated approval confirmatory trial requirements and EMA conditional marketing authorization renewal criteria to anticipate reimbursement and access volatility for novel tau-targeted modalities.
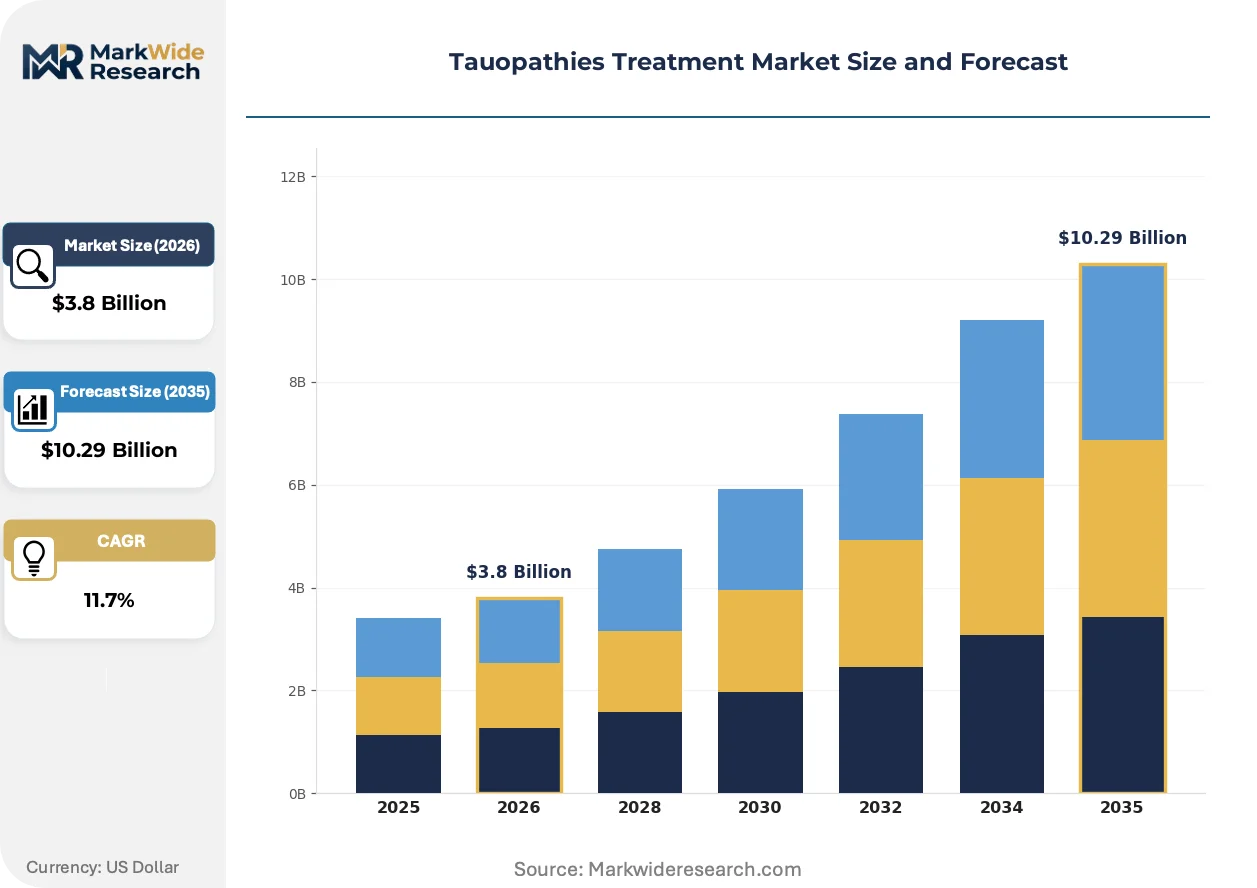
Market Dynamics
FDA accelerated approval pathways for Alzheimer's disease biologics are compressing development timelines while forcing diagnostic companion requirements that reshape reimbursement criteria across neurology clinics.
Growth Catalysts
- Tau PET Imaging Validation:FDA biomarker qualification standards are elevating diagnostic precision requirements that drive parallel investment in imaging infrastructure and therapeutic protocols.
- Germany's National Dementia Plans:EMA centralized review procedures accelerate patient access windows for novel tau-directed therapies through harmonized reimbursement frameworks.
- Blood-Brain Barrier Penetration Advances:Engineering improvements in monoclonal antibody delivery systems expand addressable patient populations previously excluded from biologic interventions.
Market Restraints
- Biologic Manufacturing Complexity:Viral vector production capacity constraints and cold-chain logistics requirements inflate per-dose costs relative to small molecule alternatives.
- Confirmatory Trial Uncertainty:FDA post-accelerated approval confirmatory study requirements create reimbursement volatility that delays payer contract finalization.
- Cerebrospinal Fluid Collection Barriers:Invasive biomarker sampling protocols limit patient enrollment in rural and elderly populations with mobility restrictions.
Strategic Opportunities
- Gene Therapy Platform Maturation:Viral vector delivery system advances for central nervous system indications open white space in disease-modifying interventions beyond symptomatic management.
- EMA Conditional Marketing Authorization:Renewal criteria frameworks enable earlier revenue recognition in European markets while confirmatory data accumulates.
- Oral Small Molecule Formulations:Scalable chemical synthesis routes and pharmacy distribution channels address patient preference for non-infusion administration modalities.
Industry Challenges
- Adaptive Trial Design Expertise:Biostatistical talent scarcity in tau PET imaging correlation methodologies delays protocol amendments and endpoint redefinitions.
- Cross-Border Diagnostic Harmonization:Divergent national reimbursement for companion imaging creates fragmented patient access within single regulatory jurisdictions.
- Intellectual Property Thickets:Overlapping patent claims on tau epitope binding regions complicate freedom-to-operate analyses for antibody developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tauopathies Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Vaccines, Gene Therapy Therapy Area: Alzheimer's Disease, Frontotemporal Dementia, Progressive Supranuclear Palsy, Corticobasal Degeneration End User: Hospitals, Research Institutions, Pharmaceutical Companies, Clinics Delivery Mode: Intravenous, Oral, Subcutaneous, Intranasal |
| Companies Covered | Eli Lilly and Company, Biogen Inc., Roche Holding AG, Johnson & Johnson, AstraZeneca plc, Novartis AG, Bristol-Myers Squibb Company, Otsuka Pharmaceutical Co., Ltd., AC Immune SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tauopathies Treatment Market Strategic Shifts
Tauopathy therapeutic development is pivoting from symptomatic management toward disease-modification claims that require biomarker-validated surrogate endpoints and restructured clinical trial architectures.
Gene therapy viral vector delivery systems are supplanting repeated monoclonal antibody infusions as the preferred modality for sustained tau suppression. Academic medical centers in the United States and Switzerland are prioritizing adeno-associated virus platform investments for central nervous system targeting. This shift is compressing development timelines for chronic administration models while elevating manufacturing scale-up requirements.
EMA conditional marketing authorization renewal criteria are forcing earlier commercial infrastructure commitments before confirmatory survival data matures. Pharmaceutical developers must pre-position manufacturing capacity and field medical teams based on surrogate biomarker endpoints rather than clinical benefit confirmation. European neurology clinics are restructuring patient monitoring protocols to satisfy post-authorization study enrollment obligations.
Patient advocacy organizations are demanding blood-based biomarker alternatives that eliminate lumbar puncture requirements for trial participation. Biotech developers are reallocating R&D expenditure toward plasma p-tau181 and p-tau217 assay validation to expand eligible patient pools. This behavioral shift is most visible in United States recruitment where elderly population mobility constraints previously excluded substantial addressable segments.
Tauopathies Treatment Market Segmentation
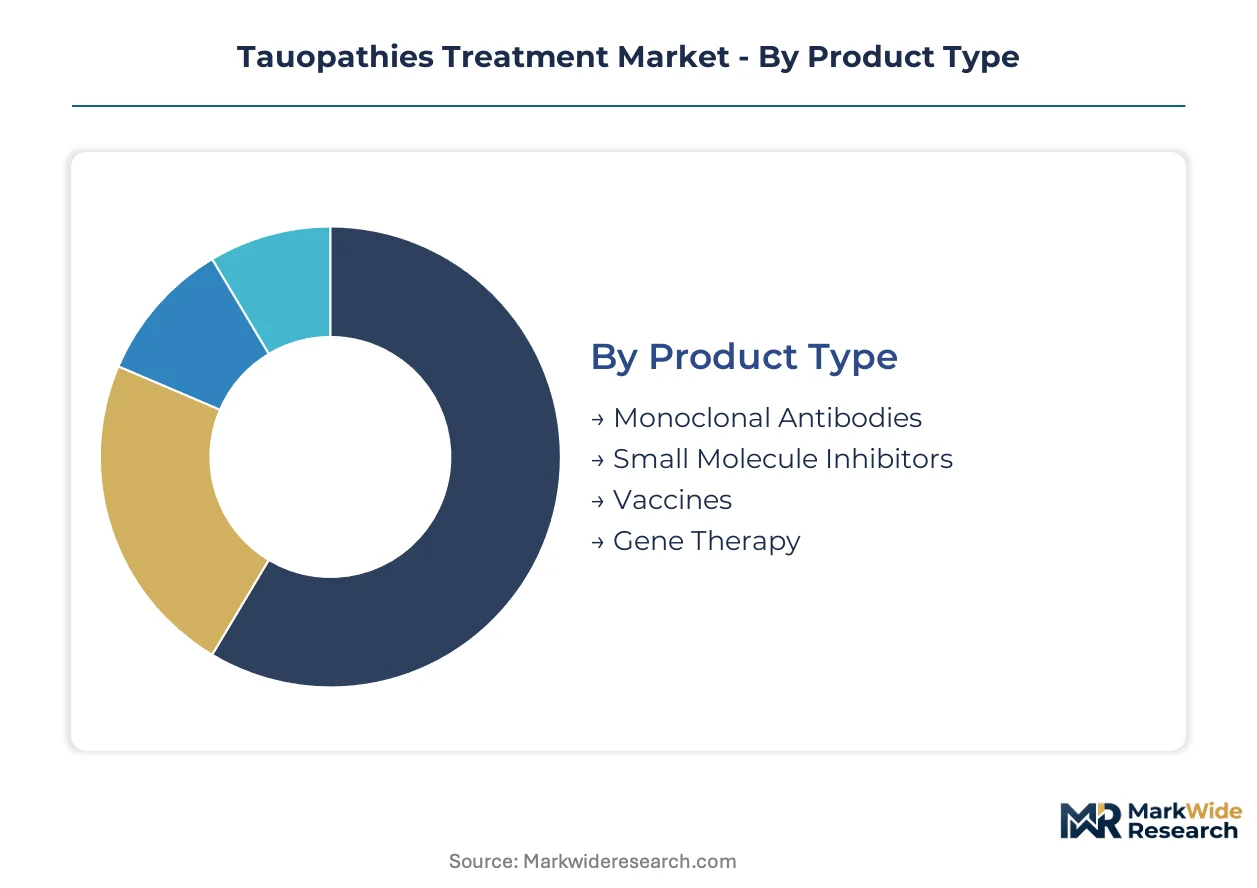
Product modality selection in tauopathies treatment determines regulatory pathway complexity, manufacturing investment scale, and reimbursement negotiation leverage. Therapy area concentration shapes clinical trial design priorities and biomarker validation requirements across heterogeneous neurodegenerative phenotypes.
Product Type:
Monoclonal antibodies concentrate development investment in the United States and Germany where FDA and EMA accelerated approval frameworks reward blood-brain barrier penetration advances. Small molecule inhibitors retain commercial viability in markets prioritizing oral bioavailability and pharmacy distribution economics.
- Monoclonal Antibodies:Engineered immunoglobulins bind extracellular tau species to halt neurofibrillary tangle propagation. United States neurology clinics drive infusion center infrastructure expansion as FDA biomarker qualification standards elevate diagnostic companion requirements. Manufacturing complexity and cold-chain logistics inflate per-dose costs relative to alternatives.
- Small Molecule Inhibitors:Chemical compounds modulate tau phosphorylation kinases through oral administration. European markets favor scalable synthesis routes and established pharmacy channels over biologic cold-chain dependency. Margin pools remain attractive despite slower disease-modification claims.
- Vaccines:Active immunization platforms induce endogenous antibody production against pathological tau epitopes.
- Gene Therapy:Viral vector delivery systems enable sustained tau suppression through single administration. Adeno-associated virus platform maturation in Swiss and United States academic medical centers accelerates central nervous system targeting capabilities.
Monoclonal antibodies hold the largest share; momentum sits with gene therapy as viral vector manufacturing scales.
Therapy Area:
Application concentration varies by diagnostic infrastructure maturity and biomarker validation status. Alzheimer's disease commands disproportionate trial enrollment due to FDA precedent for accelerated approval in amyloid-targeted therapies.
- Alzheimer's Disease:Progressive neurodegeneration characterized by amyloid plaques and tau neurofibrillary tangles. United States patient advocacy organizations drive blood-based biomarker adoption to eliminate lumbar puncture barriers for elderly recruitment. Confirmatory trial uncertainty creates reimbursement volatility.
- Frontotemporal Dementia:Heterogeneous syndromes linked to tau, progranulin, and C9orf72 pathologies. European specialized dementia centers concentrate expertise for rare phenotype stratification. Diagnostic delay limits addressable populations.
- Progressive Supranuclear Palsy:Atypical parkinsonian syndrome with tau pathology predominance.
- Corticobasal Degeneration:Rare tauopathy with asymmetric motor and cognitive decline.
Alzheimer's disease dominates development pipelines; frontotemporal dementia shows the steepest expansion trajectory as biomarker specificity improves.
End User:
Customer procurement patterns diverge by institutional reimbursement structure and research mission alignment. Hospitals integrate therapeutic and diagnostic protocols under value-based care frameworks.
- Hospitals:Integrated delivery networks coordinate infusion center capacity with neurology clinic expansion. United States health systems negotiate payer contracts contingent on FDA confirmatory trial timelines.
- Research Institutions:Academic medical centers in Switzerland and the United States prioritize adeno-associated virus platform investments.
- Pharmaceutical Companies:Sponsor-sponsored trial infrastructure and manufacturing scale-up.
- Clinics:Outpatient neurology practices manage chronic administration and monitoring protocols.
Hospitals capture the dominant procurement volume; research institutions are gaining share fastest through gene therapy platform partnerships.
Delivery Mode:
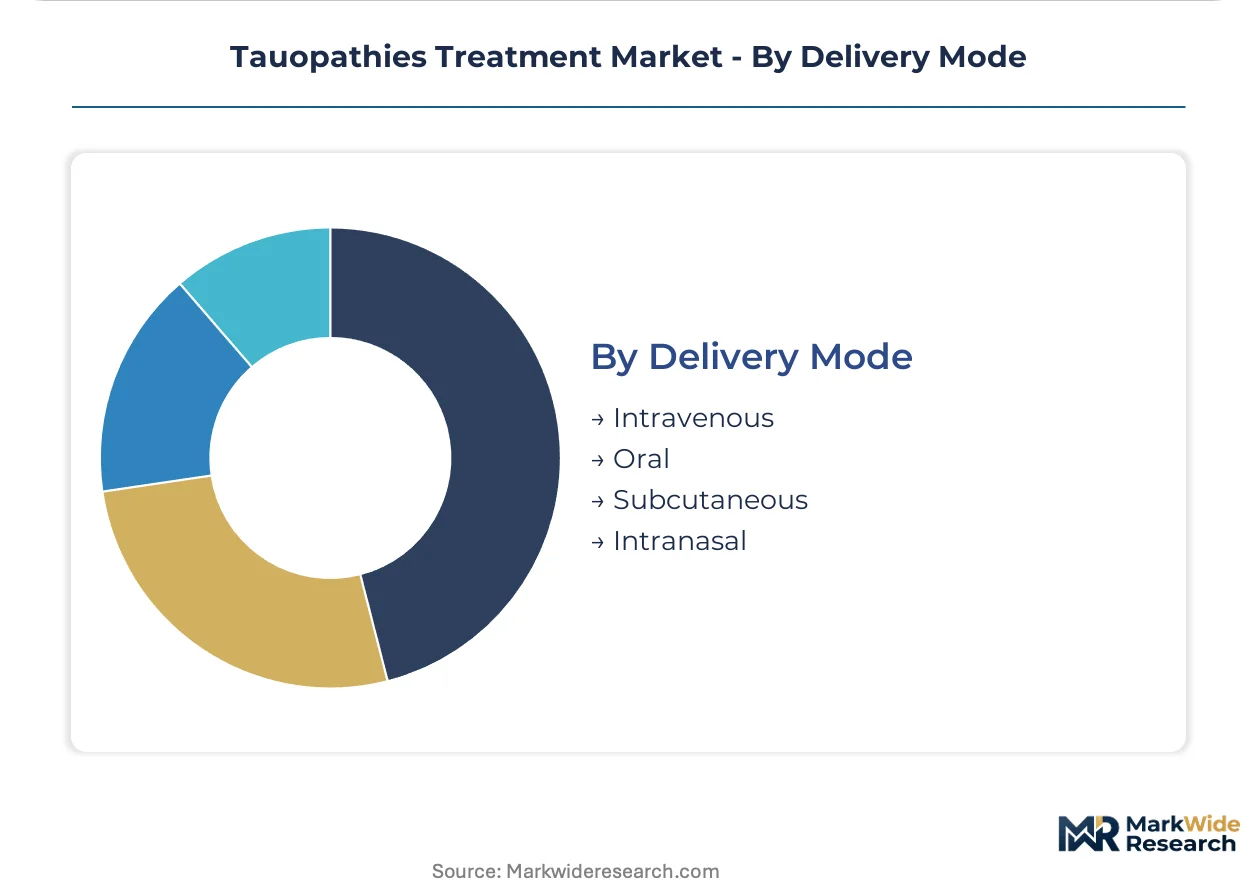
Administration route selection shapes patient adherence economics and site-of-care requirements. Intravenous infusion dominates monoclonal antibody distribution while oral formulations address mobility-constrained populations.
- Intravenous:Infusion center administration enables therapeutic drug monitoring and adverse event management. United States hospital outpatient departments expand capacity to accommodate biologic scheduling density.
- Oral:Pharmacy-dispensed tablets and capsules eliminate site-of-care dependency. Patient preference in rural and elderly segments drives small molecule development prioritization.
- Subcutaneous:Self-administration potential reduces infusion center burden.
- Intranasal:Non-invasive blood-brain barrier bypass for biologic delivery.
Intravenous administration retains the largest share; oral delivery is climbing the fastest as patient-centric trial design gains regulatory traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks are reshaping investment geography across tauopathy therapeutic development. National dementia plans and biomarker infrastructure maturity determine patient access velocity in each market.
United States
Neurology clinics in Massachusetts and California are expanding tau-targeted infusion capacity as FDA biomarker qualification standards elevate diagnostic companion requirements. The agency's breakthrough therapy designation compresses competitive entry timelines for developers with validated tau PET imaging protocols. Academic medical centers in Boston and San Francisco anchor adeno-associated virus platform investments for central nervous system gene therapy delivery.
Germany
EMA centralized review procedures accelerate patient access windows for novel tau-directed therapies through harmonized national reimbursement frameworks. The country's national dementia plans mandate specialized care infrastructure that concentrates expertise in Munich and Heidelberg university hospitals. Bavarian and Baden-Württemberg research clusters coordinate multicenter trial networks for frontotemporal dementia phenotyping.
Switzerland
Swissmedic regulatory precedents for neurodegenerative biologics attract developers seeking early European market entry with streamlined conditional authorization pathways. Basel anchors Roche Holding AG's dedicated neurodegeneration research facilities and manufacturing scale-up for monoclonal antibody production. Zurich and Geneva academic hospitals prioritize blood-brain barrier penetration engineering collaborations with viral vector platform specialists.
Japan
PMDA's Sakigake designation system accelerates tau-targeted therapy review timelines for developers with demonstrated disease-modification biomarker correlations. Tokyo and Osaka university hospitals concentrate expertise for progressive supranuclear palsy and corticobasal degeneration rare phenotype stratification. METI funding programs support domestic manufacturing capacity for gene therapy viral vector production.
United Kingdom
MHRA post-Brexit regulatory autonomy enables adaptive trial design frameworks that attract international tauopathy developers seeking flexible endpoint validation. London and Cambridge neuroscience clusters coordinate blood-based biomarker assay validation to eliminate lumbar puncture barriers for elderly recruitment. NHS England's specialized commissioning frameworks reshape reimbursement negotiation leverage for disease-modifying interventions.
Tauopathies Treatment Market Competitive Environment
Listed leaders compete with private specialists across pipeline depth and manufacturing readiness dimensions. Market structure concentrates around pharmaceutical conglomerates with parallel amyloid-tau investments and emerging biotech platforms with modality-specific specialization. Strategic archetypes include antibody-centric developers prioritizing infusion center partnerships, vaccine-platform specialists pursuing active immunization differentiation, and gene therapy innovators betting on single-administration disease modification. Dominant competitive moves encompass diagnostic companion commercialization alliances and manufacturing capacity pre-positioning ahead of confirmatory data readouts.
Within the large-cap pharmaceutical tier, Eli Lilly and Company and Roche Holding AG exemplify parallel pipeline investment strategies that sustain manufacturing readiness for anticipated label expansions. AC Immune SA occupies a distinct position as a vaccine-platform specialist competing against antibody-centric approaches. These three entities anchor competitive dynamics across FDA and EMA accelerated approval pathways, with each representing divergent modality bets on sustainable tau suppression mechanisms.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Biogen Inc. |
| Roche Holding AG |
| Johnson & Johnson |
| AstraZeneca plc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Otsuka Pharmaceutical Co., Ltd. |
| AC Immune SA |
| Others |
Value Chain & Pricing Dynamics
Gene therapy viral vector production displacing repeated monoclonal antibody manufacturing is redrawing supply geography toward Swiss and United States academic medical centers while compressing per-dose cost structures for chronic administration models.
Pricing Analysis
Certification level (FDA Breakthrough Therapy versus standard NDA) creates the primary spread between reimbursement tiers in the United States, with EMA conditional marketing authorization adding a European premium layer. Value-based contracting dominates hospital procurement, tying payment to biomarker-validated cognitive endpoints rather than unit dosing. Pricing pressure stems from confirmatory trial uncertainty that delays payer contract finalization for accelerated approval therapies. Small molecule oral formulations face the sharpest price sensitivity from Medicare Part D plans seeking pharmacy channel economics over infusion center overhead.
Supply Chain Analysis
Inventory lead times for adeno-associated virus vectors stretch manufacturing schedules, forcing developers to pre-position capacity before confirmatory data readouts. Supply concentrates in Switzerland, the United States, and Germany where specialized biologics facilities anchor viral vector production. Cold-chain logistics for monoclonal antibodies draw from established pharmaceutical distribution networks, while gene therapy manufacturing rests on single-source plasmid suppliers and fetal bovine serum dependencies. Tariff exposure on Chinese-sourced raw materials poses structural risk for cost-sensitive small molecule programs. Distribution runs through hospital outpatient departments and specialty pharmacy channels segmented by administration route.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States integrated delivery networks and European national health technology assessment bodies that negotiate access contingent on biomarker-validated outcomes rather than clinical trial surrogates alone.
For Market Incumbents: Shield manufacturing margins by securing captive viral vector production in Basel and Boston corridor facilities before gene therapy demand spikes. Reinforce diagnostic companion alliances with tau PET imaging vendors to lock in reimbursement pathway control against emerging blood-based biomarker substitutes. For New Entrants and Emerging Players: Differentiate on oral small molecule convenience for rural and elderly populations excluded from infusion-dependent trials. Target frontotemporal dementia phenotypes where biomarker specificity improvements are opening addressable populations faster than Alzheimer's disease saturation. Pursue EMA conditional marketing authorization first to establish European revenue base before FDA confirmatory requirements harden. For Investors and Strategic Acquirers: The market sits at a modality-transition phase that favors gene therapy platform specialists over antibody-centric developers with aging pipelines. Long-term viability hinges on single-administration disease-modification claims validated through surrogate biomarker endpoints. Watch for tau PET imaging correlation failures in confirmatory trials as the inflection signal for portfolio rebalancing toward small molecule oral programs.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Pre-positions viral vector capacity ahead of EMA renewal deadlines and FDA confirmatory readouts. |
| Diagnostic Companion Alliance | Locks in tau PET imaging reimbursement pathways alongside therapeutic label expansion negotiations. |
| Regulatory Approval Pathway | Prioritizes EMA conditional authorization to capture European revenue before FDA full approval. |
| Pipeline Diversification | Balances monoclonal antibody exposure with gene therapy bets on sustained tau suppression. |
| Reimbursement Strategy | Structures value-based contracts with Medicare Advantage plans around cognitive endpoint achievement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA approval documents, EMA assessment reports, ClinicalTrials.gov protocols, and hospital procurement databases. Interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists informed demand-side assumptions. Bottom-up patient flow modeling triangulated against top-down pharmaceutical revenue estimates across the analysis window.
Segmentation dimensions modeled include product modality, therapy area concentration, end-user procurement structure, and delivery mode preference throughout the projection horizon. CAGRs derive from biomarker adoption curves, regulatory pathway velocity assumptions, and manufacturing capacity expansion schedules. Forecast inputs incorporate tau PET imaging infrastructure buildout rates and blood-based biomarker assay validation timelines.
The analysis sits within stated boundaries; outcomes outside FDA accelerated approval continuity or EMA conditional authorization renewal would require recalibration. Forecasts reflect assumptions about biomarker qualification standards and adaptive trial design acceptance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Ascites Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market