
 Hepatocellular Carcinoma (HCC) Treatment Market | 2026-2036
Hepatocellular Carcinoma (HCC) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatocellular Carcinoma (HCC) Treatment Market Analysis
First-line combination therapy standards are rotating upward as regulatory benchmarks tighten and reimbursement ties to survival endpoints strengthen. Bayer leverages its kinase inhibitor portfolio to sustain dominance in targeted therapy segments. Bristol-Myers Squibb anchors its position through checkpoint inhibitor development, while Roche competes with differentiated diagnostics-linked treatment protocols across major oncology centers.
Hepatocellular Carcinoma treatment encompasses surgical, locoregional, and systemic interventions targeting primary liver malignancies arising from chronic hepatitis or cirrhosis, with immunotherapy agents typically requiring cold-chain intravenous administration at specialized infusion centers. The primary commercial purpose centers on extending overall survival in patients with Barcelona Clinic Liver Cancer stage B and C disease. Immunotherapy within the therapy area segment commands premium pricing and fastest-growing utilization as PD-1 and CTLA-4 combinations displace sorafenib monotherapy in frontline settings. Ablation techniques remain mature with stable reimbursement but face margin compression as hospitals consolidate purchasing for radiofrequency and microwave systems.
FDA breakthrough therapy designation and EMA conditional approval pathways shape trial investment and commercial launch sequencing for HCC drug developers, while China's NMPA priority review channel accelerates domestic market entry for novel biologics. The EU's MDR requirements for device-based ablation systems raise compliance costs for manufacturers seeking CE-marked distribution. Stakeholders must monitor biomarker-defined patient stratification as regulatory agencies condition approvals on companion diagnostic co-development.

Market Dynamics
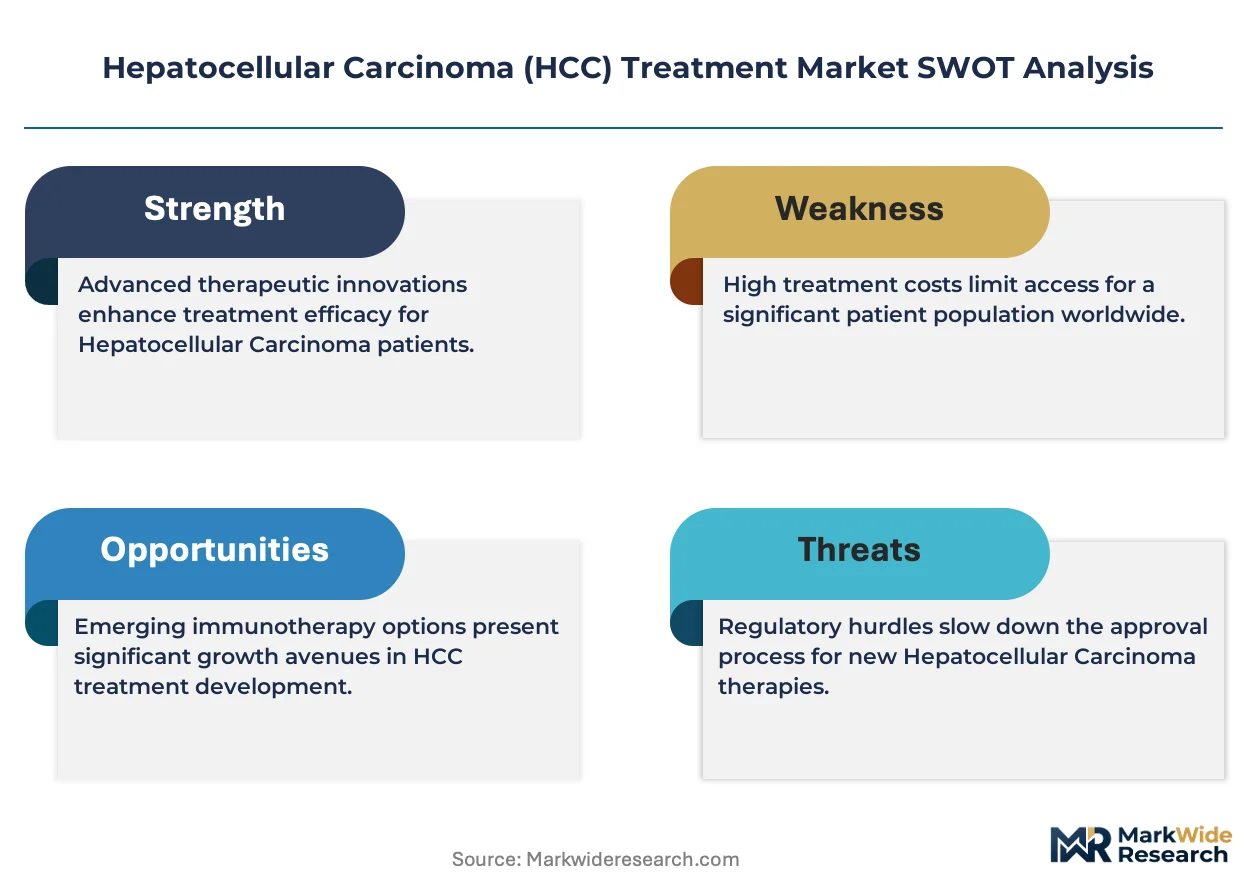
The transition from kinase inhibitor monotherapy to checkpoint inhibitor combinations is restructuring prescriber behavior, hospital formulary positioning, and infusion center capacity planning across major oncology networks.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for novel immunotherapy combinations, enabling earlier commercial access and payer coverage negotiations.
- China NMPA Priority Review Channel:Domestic biologics developers gain expedited market entry for PD-1 inhibitors, expanding patient access in the world's largest hepatitis B endemic population.
- Companion Diagnostic Co-Development Mandates:Regulatory agencies now require biomarker stratification protocols, driving investment in PD-L1 expression testing infrastructure at tertiary cancer centers.
Market Restraints
- Cold-Chain Distribution Costs:Intravenous immunotherapy agents require specialized logistics infrastructure, limiting reach to urban infusion centers and raising per-dose delivery expenses.
- EMA Conditional Approval Uncertainty:Post-marketing confirmatory trial obligations create reimbursement volatility across EU member states, delaying hospital adoption decisions.
- Biomarker Testing Fragmentation:Lack of standardized PD-L1 assay platforms across laboratories generates inconsistent patient selection, complicating clinical trial enrollment and real-world outcomes analysis.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered injection alternatives to intravenous delivery could shift treatment from hospital infusion centers to community oncology practices.
- Japan's Aging Hepatitis C Cohort:The country's high cirrhosis prevalence creates concentrated demand for adjuvant systemic therapy following curative resection or ablation.
- Real-World Evidence Registries:FDA's expanding acceptance of RWE for supplemental indications enables label expansion without redundant randomized controlled trials.
Industry Challenges
- Hepatology-Oncology Interface Coordination:Patient management requires seamless handoffs between transplant centers and medical oncology departments, straining referral workflows.
- Immune-Related Adverse Event Management:Checkpoint inhibitor toxicities demand specialized nursing expertise and rapid endocrinology consultation capacity that many community sites lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatocellular Carcinoma (HCC) Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Resection, Liver Transplantation, Ablation Techniques, Chemotherapy Therapy Area: Immunotherapy, Targeted Therapy, Radiofrequency Ablation, Transarterial Chemoembolization End User: Hospitals, Specialty Clinics, Cancer Treatment Centers, Academic Research Institutes Delivery Mode: Intravenous, Oral, Localized Treatment, Combination Therapy |
| Companies Covered | Bayer, AstraZeneca, Bristol-Myers Squibb, Eisai, Novartis, Exelixis, Roche, Innovent Biologics, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatocellular Carcinoma (HCC) Treatment Market Emerging Trajectories
Combination regimen development is overtaking monotherapy research, with trial designs now prioritizing overall survival endpoints over progression-free survival surrogates. This shift demands larger patient populations and longer follow-up periods.
Tyrosine kinase inhibitor development is bifurcating into two distinct trajectories: next-generation molecules targeting specific resistance mutations in the VEGF pathway, and dual-acting compounds simultaneously inhibiting angiogenic and immunomodulatory signaling. Academic medical centers in the United States and Germany are prioritizing the latter category for investigator-initiated trials. This technology is bifurcating the clinical development landscape, creating separate competitive arenas for precision-targeted and broad-spectrum approaches.
The EU Medical Device Regulation (MDR) is elevating clinical evidence requirements for radiofrequency and microwave ablation systems, forcing manufacturers to generate prospective safety data or withdraw CE-marked devices from European markets. Ablation equipment vendors are consolidating regulatory affairs functions and accelerating post-market clinical follow-up studies. Interventional radiology departments in France and Italy are delaying capital equipment purchases pending MDR certification clarity.
Purchasing consolidation at integrated delivery networks is compressing vendor negotiation cycles and unbundling device-procedure-drug bundles that previously obscured true therapy costs. Hospital systems in Texas and California are deploying value analysis committees with oncology pharmacy and interventional radiology representation. This behavioral shift is most pronounced in United States markets where Medicare bundled payment pilots for liver cancer episodes are operational.
Hepatocellular Carcinoma (HCC) Treatment Market Segmentation

HCC treatment segmentation reveals divergent commercial trajectories across intervention modalities. Therapy area and delivery mode distinctions increasingly dictate site-of-care requirements and reimbursement pathways.
Product Type:
Domestic demand concentrates in resection and ablation systems, while transplant infrastructure depends on international organ exchange protocols and cross-border surgical training networks.
- Surgical Resection:Anatomical liver resection with portal vein embolization for future liver remnant expansion. Hepatobiliary surgery units at Memorial Sloan Kettering and MD Anderson anchor North American volume, constrained by specialized surgeon availability.
- Liver Transplantation:Orthotopic transplant with Milan criteria patient selection. United Network for Organ Sharing allocation policies and specialized transplant centers in Pittsburgh and San Francisco concentrate domestic capacity, limited by donor organ scarcity.
- Ablation Techniques:Percutaneous radiofrequency and microwave thermal destruction of tumors under imaging guidance.
- Chemotherapy:Systemic cytotoxic agents including doxorubicin and FOLFOX regimens for advanced disease.
Surgical resection commands the established base. The steepest expansion runs through ablation techniques.
Therapy Area:
Cost tier stratification separates premium-priced immunotherapy from mature targeted agents and procedure-based interventions with compressed margins.
- Immunotherapy:Checkpoint inhibitors targeting PD-1, PD-L1, and CTLA-4 pathways administered via cold-chain intravenous infusion. Tertiary cancer centers in Boston and Houston are expanding dedicated infusion capacity to capture PD-1 combination protocol volumes.
- Targeted Therapy:Multikinase inhibitors disrupting angiogenic signaling through VEGF receptor blockade. Bayer's sorafenib and lenvatinib formulations dominate oral prescription volume at community oncology practices.
- Radiofrequency Ablation:Thermal energy delivery via electrode probes under ultrasound or CT guidance.
- Transarterial Chemoembolization:Locoregional chemotherapy delivery through hepatic artery catheterization combined with embolic particle occlusion.
Targeted therapy commands the established base. Immunotherapy is climbing the fastest as frontline combination protocols displace kinase inhibitor monotherapy.
End User:
Customer type determines purchasing authority complexity, with integrated delivery networks consolidating procurement for hospital systems while specialty clinics retain independent formulary control.
- Hospitals:Comprehensive oncology departments with embedded hepatology, interventional radiology, and surgical services. Major systems in Texas and California deploy value analysis committees with pharmacy and IR representation.
- Specialty Clinics:Community oncology practices managing systemic therapy without embedded interventional capabilities. These sites refer ablation and embolization procedures to affiliated hospital partners.
- Cancer Treatment Centers:Dedicated liver cancer centers with consolidated multidisciplinary tumor boards.
- Academic Research Institutes:Investigator-initiated trial sites with early-phase immunotherapy protocol access.
Hospitals command the established base. Cancer treatment centers are gaining share fastest through dedicated liver program investments.
Delivery Mode:
Supply concentration distinguishes hospital-dependent intravenous administration from distributed oral and localized alternatives that shift site-of-care economics.
- Intravenous:Infusion center administration requiring cold-chain logistics and specialized nursing for immune-related adverse event monitoring. Urban concentration limits rural patient access.
- Oral:Self-administered kinase inhibitors with pharmacy benefit manager reimbursement pathways. Community oncology practices in Florida and Arizona capture dispensing margin through specialty pharmacy integration.
- Localized Treatment:Image-guided percutaneous or intra-arterial delivery with interventional radiology suite requirements.
- Combination Therapy:Sequential or concurrent multimodal protocols integrating systemic and locoregional approaches.
Intravenous delivery commands the established base. Oral administration is expanding most quickly through subcutaneous formulation development and community practice channel shift.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Treatment demand flows concentrate in import-dependent markets with advanced infusion infrastructure, while manufacturing and clinical trial activity clusters in jurisdictions with expedited regulatory pathways. Export intensity for checkpoint inhibitors and kinase inhibitors runs highest from Switzerland, Germany, and the United States toward Asia-Pacific absorption centers.
United States
Memorial Sloan Kettering and MD Anderson anchor hepatobiliary surgical volume, drawing international referral flows for resection and transplant evaluation. FDA breakthrough therapy designation compresses development timelines for PD-1 combinations, enabling earlier commercial access negotiations. Boston and Houston tertiary centers are expanding dedicated infusion capacity to capture immunotherapy protocol volumes.
China
The world's largest hepatitis B endemic population generates concentrated demand for systemic therapy, with domestic biologics developers gaining expedited market entry through NMPA priority review channels. NMPA accelerated pathways for novel biologics are reshaping clinical trial design and commercial launch sequencing. Shanghai and Beijing cancer centers are building dedicated liver cancer programs with embedded interventional radiology suites.
Japan
An aging hepatitis C cohort creates sustained demand for adjuvant systemic therapy following curative resection or ablation, with concentrated prescriber behavior at university hospitals. PMDA consultation programs for oncology drug development streamline regulatory interactions for combination regimen sponsors. Osaka and Nagoya metropolitan clusters concentrate interventional radiology expertise for transarterial chemoembolization procedures.
Germany
Academic medical centers in Munich and Heidelberg prioritize investigator-initiated trials for dual-acting kinase inhibitors targeting angiogenic and immunomodulatory signaling. EMA conditional approval pathways shape post-marketing confirmatory trial obligations, creating reimbursement volatility across EU member states. The country's hepatology-oncology interface coordination models are being replicated by neighboring health systems.
United Kingdom
NHS England specialized commissioning frameworks concentrate liver cancer surgery at designated supra-regional centers in London and Manchester, limiting community site autonomy. NICE technology appraisals for immunotherapy combinations establish cost-effectiveness thresholds that influence formulary positioning across European markets. Real-world evidence registries at Imperial College London and University College London anchor FDA-recognized outcomes databases for supplemental indication expansion.
Hepatocellular Carcinoma (HCC) Treatment Market Vendor Landscape
Concentration sits with diversified pharmaceutical conglomerates and targeted biotechnology specialists, with mid-tier regional developers occupying distinct geographic niches. The competitive terrain divides between kinase inhibitor incumbents defending oral therapy positions and checkpoint inhibitor developers capturing infusion center capacity. Three archetypes dominate: multinational oncology platforms with diagnostic linkages, precision-targeted therapy specialists, and emerging biologics developers with NMPA-favored domestic status. Portfolio diversification into companion diagnostic co-development and subcutaneous formulation pipelines represents the dominant competitive moves.
Within the multinational oncology platform tier, Bayer and Bristol-Myers Squibb exemplify divergent strategic anchors. Bayer's kinase inhibitor portfolio sustains dominance in targeted therapy segments through oral VEGF pathway blockade. Bristol-Myers Squibb anchors its position through checkpoint inhibitor development with embedded infusion center partnerships. Roche occupies a differentiated position linking diagnostics-linked treatment protocols across major oncology centers. Among emerging biologics developers, Innovent Biologics represents the NMPA-priority domestic archetype with concentrated China market access.
| Leading Market Players |
|---|
| Bayer |
| AstraZeneca |
| Bristol-Myers Squibb |
| Eisai |
| Novartis |
| Exelixis |
| Roche |
| Innovent Biologics |
| Merck & Co. |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough therapy designation and EMA conditional approval pathways simultaneously gate supply qualification for novel immunotherapy developers and stratify price differentiation between accelerated-access premium tiers and standard regulatory channels. Cold-chain distribution requirements for checkpoint inhibitors concentrate supply authority at tertiary infusion centers, compressing margins for community oncology sites while enabling premium capture at academic medical centers.
Pricing Analysis
Hospital value analysis committees anchor pricing negotiations for systemic therapy portfolios, with three-tier pricing structure across premium, standard, and economy levels separating PD-1 combination protocols from kinase inhibitor monotherapy and mature cytotoxic regimens. Price differentiation centers on biomarker stratification requirements and companion diagnostic bundling. Pricing pressure stems from Medicare bundled payment pilots for liver cancer episodes in Texas and California markets. Community oncology practices exhibit highest price sensitivity due to pharmacy benefit manager reimbursement compression.
Supply Chain Analysis
Cold-chain logistics infrastructure at Indianapolis and Memphis distribution hubs underwrites immunotherapy delivery to urban infusion centers, with supply concentration in Switzerland, Germany, and the United States for checkpoint inhibitor manufacturing. Active pharmaceutical ingredient sourcing draws from Chinese biologics developers and Indian contract manufacturing organizations. Single-source vulnerability runs through monoclonal antibody production facilities. Distribution runs through specialty pharmacy networks with embedded patient support programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HCC treatment market functions as a defensive-moat arena where regulatory entrenchment through companion diagnostic co-development mandates creates substantial switching costs for incumbent pharmaceutical platforms.
For Market Incumbents: Consolidate infusion center partnerships through exclusive protocol access agreements, locking in capacity at Boston and Houston tertiary cancer centers. Deepen backward integration into PD-L1 assay development to control biomarker testing infrastructure against emerging diagnostic competitors. For New Entrants and Emerging Players: Subcutaneous formulation development gaps where incumbents under-serve community oncology practices present white-space entry points. Target oral and self-administered delivery modes in Florida and Arizona markets where specialty pharmacy integration captures dispensing margin. Pursue NMPA priority review channel access for domestic China market entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing infrastructure, favoring asset-light platform licensing models over captive production. Long-term viability across the analysis window hinges on companion diagnostic co-development capabilities. Watch FDA real-world evidence guidance expansion as the inflection signal for label expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | EMA and FDA mandates now condition approvals on biomarker stratification protocols. |
| Subcutaneous Formulation Pipeline | Self-administered delivery shifts treatment from hospital infusion centers to community practices. |
| Real-World Evidence Registry Investment | FDA's expanding RWE acceptance enables supplemental indications without redundant trials. |
| Infusion Center Capacity Expansion | Boston and Houston tertiary centers capture PD-1 combination protocol volumes. |
| NMPA Priority Review Channel Access | Domestic China biologics developers gain expedited market entry in hepatitis B endemic population. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Primary interviews engaged drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and payer access specialists. Secondary validation incorporated CMS Medicare reimbursement data, GPO contracts, and formulary positioning records. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing across the analysis window.
Segmentation dimensions modeled encompass therapy area, delivery mode, end-user facility type, and regional regulatory cluster throughout the forecast period. CAGRs were derived from treatment protocol adoption curves and reimbursement pathway maturation. Forecast inputs incorporated checkpoint inhibitor infusion center capacity expansion timelines and NMPA priority review approval velocity for domestic China biologics.
Underlying assumptions cover immunotherapy combination protocol displacement rates and bundled payment pilot expansion, with deviation risk concentrated in EMA conditional approval uncertainty and biomarker testing platform standardization delays. Practitioners should keep alternative scenarios live as FDA real-world evidence guidance and CMS episode payment models evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Porphyria Treatment Market