
 Pompe Disease Market | 2026-2036
Pompe Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Pompe Disease Market Outlook
FDA Breakthrough Therapy and EMA PRIME qualification cycles is reorganizing competitive entry in the Pompe Disease Market. Sanofi leverages its established manufacturing scale for alglucosidase alfa to sustain dominance in intravenous ERT supply. Amicus Therapeutics differentiates through subcutaneous delivery innovation with avalglucosidase alfa, positioning against infusion-center dependency.
Pompe disease is a progressive lysosomal storage disorder caused by acid alpha-glucosidase deficiency, resulting in glycogen accumulation in cardiac, skeletal, and smooth muscle tissue; enzymatic activity below 1% of normal defines infantile-onset severity. Enzyme Replacement Therapy occupies the mature revenue core, while Gene Therapy represents the fastest-growing development category as AAV vector approaches advance through clinical validation. Subcutaneous administration routes are capturing investment priority due to reduced infusion burden and potential homecare migration.
FDA orphan drug exclusivity, EMA PRIME designation, and Japan's SAKIGAKE framework collectively accelerate review timelines and extend market protection for first movers. These regulatory instruments shape demand by conditioning payer reimbursement on demonstrated clinical endpoints and manufacturing consistency. Stakeholders must monitor vector immunogenicity data from ongoing gene therapy trials and assess manufacturing readiness for potential subcutaneous ERT transitions.
Market Dynamics
Gene therapy vectors are compressing development timelines for infantile-onset cases, forcing intravenous enzyme replacement suppliers to defend reimbursement through head-to-head cardiovascular outcome data.
Growth Catalysts
- Newborn screening mandates:United States state-level expansion and Japan's metabolic disorder panel additions are capturing presymptomatic patients before irreversible muscle damage accumulates.
- EMA PRIME designation:Accelerated assessment pathways for rare diseases reduce regulatory review periods, enabling faster commercialization of subcutaneous delivery innovations.
- Homecare infusion infrastructure:Specialty pharmacy networks in Germany and the United States are building nurse-administered subcutaneous capabilities outside hospital settings.
Market Restraints
- Plasma-derived enzyme scarcity:Bioreactor capacity constraints at contract manufacturing organizations limit alglucosidase alfa output during demand surges.
- Immunogenicity surveillance burden:Neutralizing antibody monitoring requirements under FDA orphan drug post-market protocols add per-patient compliance costs.
- Gene therapy durability uncertainty:AAV vector expression longevity remains unvalidated beyond five-year horizons, creating payer hesitation on one-time pricing models.
Strategic Opportunities
- Japan's SAKIGAKE fast-track:Conditional early approval for innovative modalities enables revenue capture while confirmatory trials continue.
- Cross-indication vector platforms:Lysosomal storage expertise from Gaucher and Fabry programs transfers directly to Pompe AAV construct optimization.
- Patient registry data monetization:Longitudinal natural history databases in the United States support payer negotiations and label expansion filings.
Industry Challenges
- Biomanufacturing talent scarcity:Cell culture specialists and viral vector process engineers command premium compensation, constraining scale-up timelines.
- Multi-site clinical coordination:Rare disease trial recruitment across dispersed pediatric centers requires dedicated patient navigation infrastructure.
- Reimbursement evidence thresholds:Germany's G-BA demands six-minute walk test improvements for continued coverage, pressuring real-world data collection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pompe Disease Market |
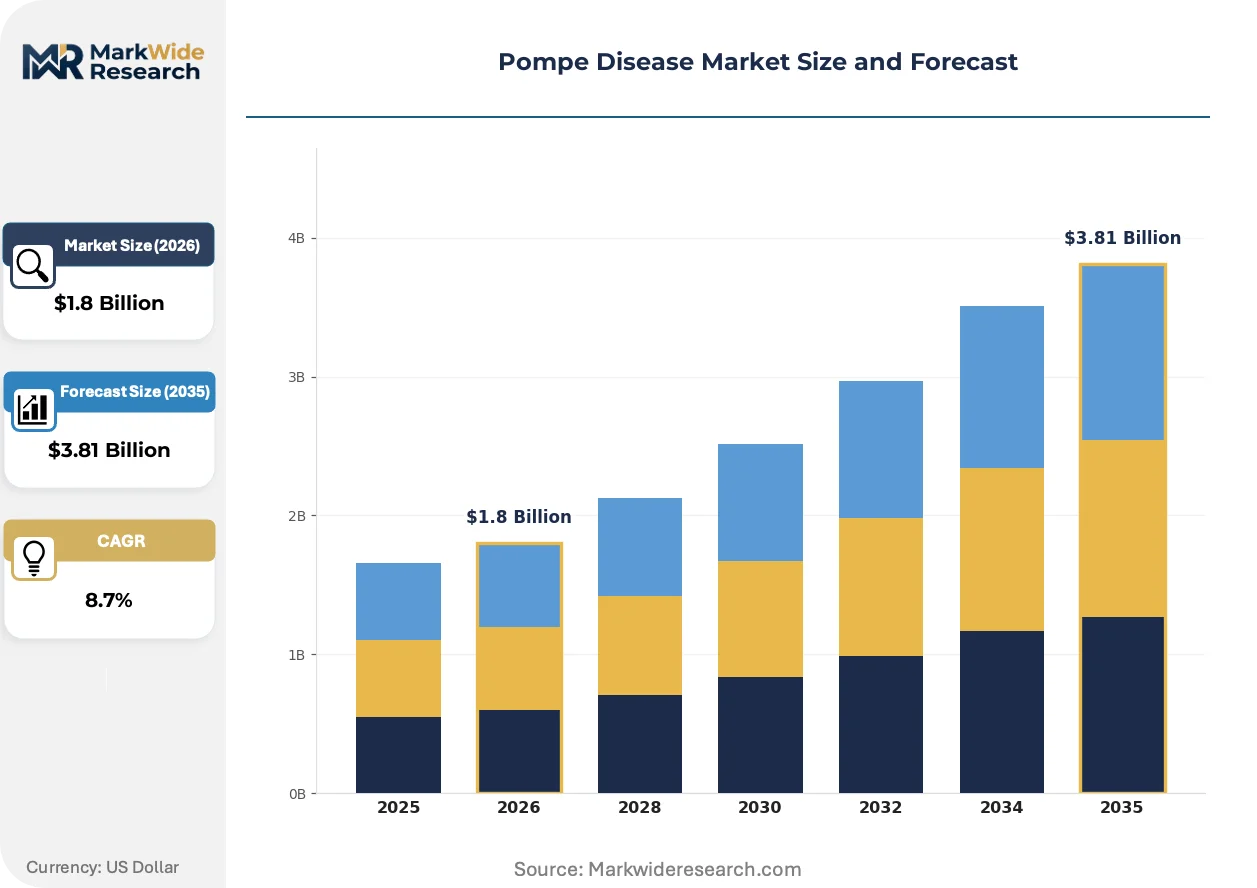
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Supportive Care, Others End User: Hospitals, Clinics, Homecare, Research Institutions Administration Route: Intravenous, Subcutaneous, Oral, Others Treatment Stage: Early Onset, Late Onset, Severe Cases, Mild Cases |
| Companies Covered | Sanofi, Amicus Therapeutics, Genzyme Corporation, Astellas Pharma, Valerion Therapeutics, Maze Therapeutics, Abeona Therapeutics, Oxyrane, Genethon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pompe Disease Market Strategic Shifts
Subcutaneous delivery mechanisms are redrawing competitive boundaries between hospital-dependent and home-treatable modalities. Vector engineering and regulatory acceleration are converging to compress development cycles.
AAV9-based gene therapy constructs are displacing chronic intravenous infusion paradigms for infantile-onset patients. Pediatric metabolic centers in the United States and Japan are prioritizing one-time administration protocols. This displacement is forcing enzyme replacement manufacturers to emphasize late-onset populations where gene therapy durability remains unproven.
FDA Breakthrough Therapy designation timelines are compressing Phase 2-to-approval intervals for novel modalities. Sponsors receive rolling review privileges and intensive regulatory guidance, reducing program risk capital requirements. ERT developers are responding by accelerating cardiovascular mortality endpoint trials to match gene therapy efficacy claims.
Specialty pharmacy distribution is capturing infusion administration from academic medical centers. Patients in Germany and the United States increasingly receive subcutaneous enzyme replacement at home through nurse-supported protocols. This channel migration is most advanced in adult late-onset cases with established anti-drug antibody profiles.
Pompe Disease Market Segmentation
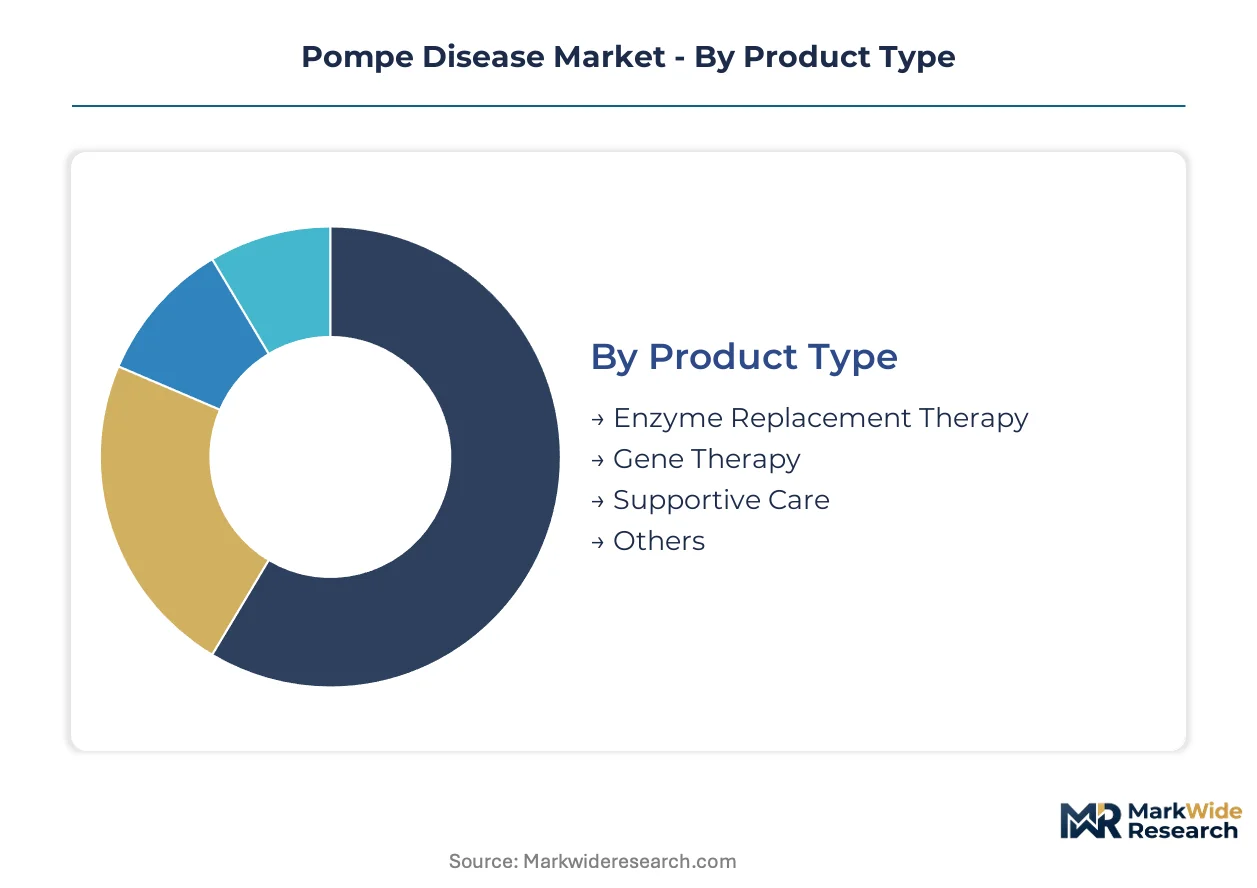
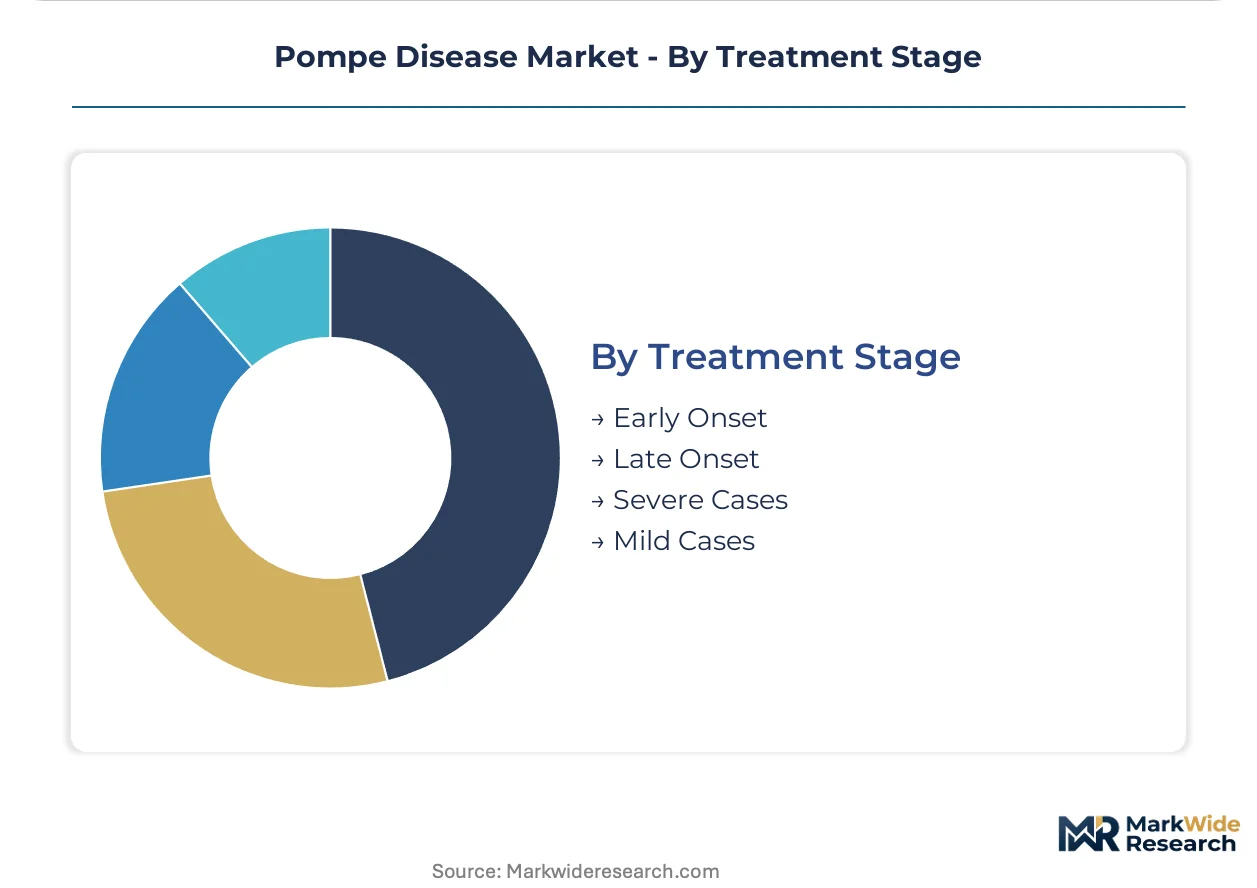
Segmentation in the Pompe Disease Market reveals how treatment modality, care setting, and patient severity stratify commercial opportunity. Manufacturers must align development priorities with where reimbursement certainty and unmet need intersect.
Product Type:
Margin pools concentrate in chronic administration modalities where manufacturing scale and pricing power compound over treatment duration.
- Enzyme Replacement Therapy:Intravenous and subcutaneous formulations of recombinant acid alpha-glucosidase constitute the established revenue base. Hospital-based infusion in the United States and Germany anchors demand, though specialty pharmacy channels are capturing share in late-onset populations with stable antibody profiles.
- Gene Therapy:AAV9 vector constructs targeting liver-directed GAA expression are advancing through Phase 3 validation. Japan's PMDA and the FDA have granted accelerated review designations, positioning one-time administration protocols to reshape infantile-onset treatment economics.
- Supportive Care:Respiratory support, nutritional intervention, and physical therapy protocols address symptomatic management gaps.
- Others:Emerging modalities including substrate reduction approaches and molecular chaperone therapies remain preclinical or early clinical.
The dominant share belongs to Enzyme Replacement Therapy, while Gene Therapy is closing the gap fastest.
End User:
Channel economics diverge sharply between acute care reimbursement and emerging home-based administration models.
- Hospitals:Academic medical centers in the United States, Germany, and Japan manage complex infantile-onset cases requiring intensive monitoring. FDA orphan drug post-market surveillance protocols for immunogenicity tracking reinforce hospital dependency for initial treatment phases.
- Clinics:Outpatient metabolic centers handle stable late-onset patients with established enzyme response profiles.
- Homecare:Nurse-administered subcutaneous infusion is expanding fastest in Germany and select United States states with mature specialty pharmacy infrastructure.
- Research Institutions:Pediatric centers conduct natural history studies and gene therapy trials under FDA and EMA pediatric investigation plans.
Hospitals retain the largest patient volume, though Homecare is expanding most quickly where reimbursement frameworks accommodate outpatient administration.
Administration Route:
Delivery innovation is redrawing competitive boundaries between site-of-care constraints and patient convenience.
- Intravenous:Established alglucosidase alfa administration requires infusion center capacity and nursing supervision. United States hospital systems maintain this route for infantile-onset patients where cardiovascular monitoring demands continuous observation.
- Subcutaneous:Next-generation enzyme formulations and novel delivery devices enable home-based administration. EMA PRIME-designated programs are prioritizing this route to reduce infusion burden and capture adult late-onset populations.
- Oral:No approved oral GAA replacement exists; investigational chaperone molecules target specific mutations.
- Others:Intrathecal and intramuscular experimental routes remain preclinical for CNS-predominant phenotypes.
Intravenous delivery holds the established position, while Subcutaneous approaches are gaining share fastest through homecare channel development.
Treatment Stage:
Patient stratification by onset timing and severity determines therapy selection, monitoring intensity, and commercial access pathways.
- Early Onset:Infantile presentations with complete GAA deficiency require immediate intervention to prevent cardiomyopathy progression. Newborn screening expansion in the United States and Japan is capturing this segment before irreversible organ damage.
- Late Onset:Juvenile and adult forms with residual enzyme activity present with progressive skeletal myopathy. Germany's G-BA and United States commercial payers condition continued coverage on functional endpoint demonstration.
- Severe Cases:Respiratory-compromised patients with ventilator dependency represent the highest per-patient cost segment.
- Mild Cases:Slowly progressive phenotypes with preserved ambulation offer longest treatment duration but lowest per-period intensity.
Late Onset carries the largest addressable population, while Early Onset is climbing the fastest through newborn screening program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialty pharmacy networks concentrate treatment demand in jurisdictions with mature newborn screening infrastructure and orphan drug reimbursement frameworks. FDA, EMA, and PMDA accelerated pathways compress commercialization timelines for innovators targeting these presymptomatic patient capture systems.
United States
Newborn screening expansion across state health departments captures infantile-onset patients before cardiomyopathy progression. FDA Breakthrough Therapy designation grants rolling review privileges to gene therapy sponsors. Boston Children's Hospital and Duke University Medical Center anchor clinical trial recruitment for AAV9-based constructs.
Germany
Specialty pharmacy networks build nurse-administered subcutaneous infusion capabilities outside hospital settings. G-BA demands six-minute walk test improvements for continued ERT coverage, pressuring real-world data collection. Heidelberg and Munich pediatric metabolic centers coordinate natural history registries supporting payer negotiations.
Japan
PMDA's SAKIGAKE framework enables conditional early approval for innovative modalities while confirmatory trials continue. METI coordinates metabolic disorder panel additions to newborn screening protocols. Tokyo and Osaka academic hospitals prioritize one-time gene therapy administration over chronic intravenous infusion.
United Kingdom
NHS England's specialized commissioning framework concentrates Pompe treatment in designated supraregional centers. MHRA rolling review pathways align with EMA PRIME acceleration for subcutaneous delivery innovations. London and Manchester metabolic units manage adult late-onset populations through outpatient clinic protocols.
Switzerland
Swissmedic orphan drug procedures synchronize with EMA centralized approvals, reducing regulatory duplication for ERT manufacturers. Cantonal hospital networks in Zurich and Geneva maintain infusion center capacity for complex pediatric cases. Reimbursement clarity under mandatory health insurance enables rapid treatment initiation post-diagnosis.
Pompe Disease Market Competitive Environment
Player mix skews toward established biopharmaceutical conglomerates with lysosomal storage disorder portfolios and emerging gene therapy specialists. Market structure concentrates around intravenous enzyme replacement incumbents defending reimbursement through cardiovascular outcome data. Three archetypes dominate: multinational ERT scale operators, subcutaneous delivery innovators, and AAV vector gene therapy developers. Competitive moves center on manufacturing capacity expansion and head-to-head clinical trial positioning against novel modalities.
Within the multinational conglomerate tier, Sanofi and Amicus Therapeutics occupy positions reflecting divergent strategic bets on administration route innovation. Sanofi exemplifies the established intravenous ERT incumbent leveraging bioreactor scale and post-market surveillance infrastructure. Amicus Therapeutics represents the subcutaneous delivery specialist archetype, targeting infusion-center independence through next-generation formulation development. Among gene therapy specialists, Astellas Pharma anchors the AAV vector developer category, advancing liver-directed expression constructs through accelerated regulatory pathways.
| Leading Market Players |
|---|
| Sanofi |
| Amicus Therapeutics |
| Genzyme Corporation |
| Astellas Pharma |
| Valerion Therapeutics |
| Maze Therapeutics |
| Abeona Therapeutics |
| Oxyrane |
| Genethon |
| Others |
Value Chain & Pricing Dynamics
Ninety-day bioreactor campaign cycles for recombinant acid alpha-glucosidase production concentrate manufacturing in FDA-inspected facilities across the United States and Germany, anchoring pricing power with incumbents who have amortized viral clearance validation costs across decade-long product lifecycles. This supply concentration enables cost-plus contracts indexed to plasma-derived raw material baskets, while limiting price competition from entrants lacking comparable manufacturing scale.
Pricing Analysis
Cost-plus contracts with plasma protein indexation dominate enzyme replacement procurement between manufacturers and hospital systems in the United States and Germany. Price differentiation rests on bioreactor scale and FDA orphan drug exclusivity tenure, with volume scale and post-market surveillance infrastructure as secondary drivers. Cost compression in late-onset patient segments is intensifying because gene therapy sponsors are offering one-time administration economics against chronic infusion pricing. Academic medical centers with captive infusion capacity exhibit lowest price sensitivity; specialty pharmacy networks competing for homecare contracts show highest.
Supply Chain Analysis
Inventory buffers spanning sixty-to-ninety days of finished enzyme concentrate sit with contract manufacturing organizations in the United States, Germany, and Switzerland. Raw material dependencies include cell culture media, protein A resins, and plasma-derived albumin supplements. Single-source vulnerability concentrates in viral vector supply for gene therapy candidates, where AAV9 producer cell lines remain proprietary to a limited supplier base. Distribution runs through cold-chain specialty pharmacy networks with nurse-administered subcutaneous capabilities expanding fastest in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pompe Disease Market functions as a service-attach opportunity where infusion administration, immunogenicity monitoring, and patient navigation layers expand faster than drug product margins alone. Homecare infrastructure and registry data monetization represent recurring-revenue streams with superior retention economics.
For Market Incumbents: Fortify bioreactor capacity in FDA-registered facilities to defend against gene therapy displacement in infantile-onset populations. Accelerate cardiovascular mortality endpoint trials to match AAV vector efficacy claims. Lock in specialty pharmacy exclusivity arrangements before subcutaneous formulation transitions commoditize infusion services. For New Entrants and Emerging Players: Homecare nurse-administered gaps in late-onset adult populations offer the most penetrable white-space, as incumbents prioritize hospital-based infantile cases. Target Germany's G-BA reimbursement framework where six-minute walk test data requirements favor real-world evidence specialists. Pursue EMA PRIME designation to compress regulatory timelines against established players. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AAV vector manufacturing as platform technologies achieve yield improvements. Long-term viability over a five-to-ten year window favors gene therapy developers with liver-directed expression constructs and confirmed immunogenicity profiles. Watch for vector durability data beyond five-year horizons as the inflection signal separating sustainable one-time pricing from chronic therapy dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Bioreactor capacity expansion in FDA-registered facilities secures supply continuity for infantile-onset demand surges. |
| Regulatory Approval Pathway | EMA PRIME designation accelerates subcutaneous formulation review against standard intravenous timelines. |
| Clinical Trial Advancement | Head-to-head cardiovascular outcome studies defend enzyme replacement reimbursement against gene therapy claims. |
| Pipeline Diversification | AAV9 vector constructs targeting liver-directed GAA expression capture infantile-onset market share from chronic infusion. |
| Licensing Agreement | Cross-indication vector platforms from Gaucher and Fabry programs transfer manufacturing expertise to Pompe constructs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including drug development executives at enzyme replacement manufacturers, regulatory affairs leads navigating FDA orphan drug protocols, formulary directors at United States academic medical centers, and payer access specialists in Germany's G-BA framework. Secondary validation drew from FDA Breakthrough Therapy designation filings, EMA PRIME submission documents, ClinicalTrials.gov registry entries, and newborn screening program expansion announcements. Bottom-up patient population estimates and top-down revenue triangulation were reconciled across independent analytical tracks.
Across the projection horizon, the analytical framework modeled segmentation dimensions including treatment modality, administration route, patient onset timing, and regional regulatory cluster. CAGRs were derived from slope analysis of historical revenue trajectories adjusted for newborn screening penetration curves and gene therapy launch scenarios. Forecast inputs incorporated bioreactor capacity expansion schedules and vector immunogenicity surveillance burden estimates.
Material uncertainties — gene therapy durability validation, plasma-derived enzyme scarcity events, and reimbursement threshold revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory acceleration continuity and payer acceptance of one-time pricing models. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Rare Inflammatory Disease Treatment Market