
 Global Nano Therapy Market | 2026-2036
Global Nano Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nano Therapy Market Foresight
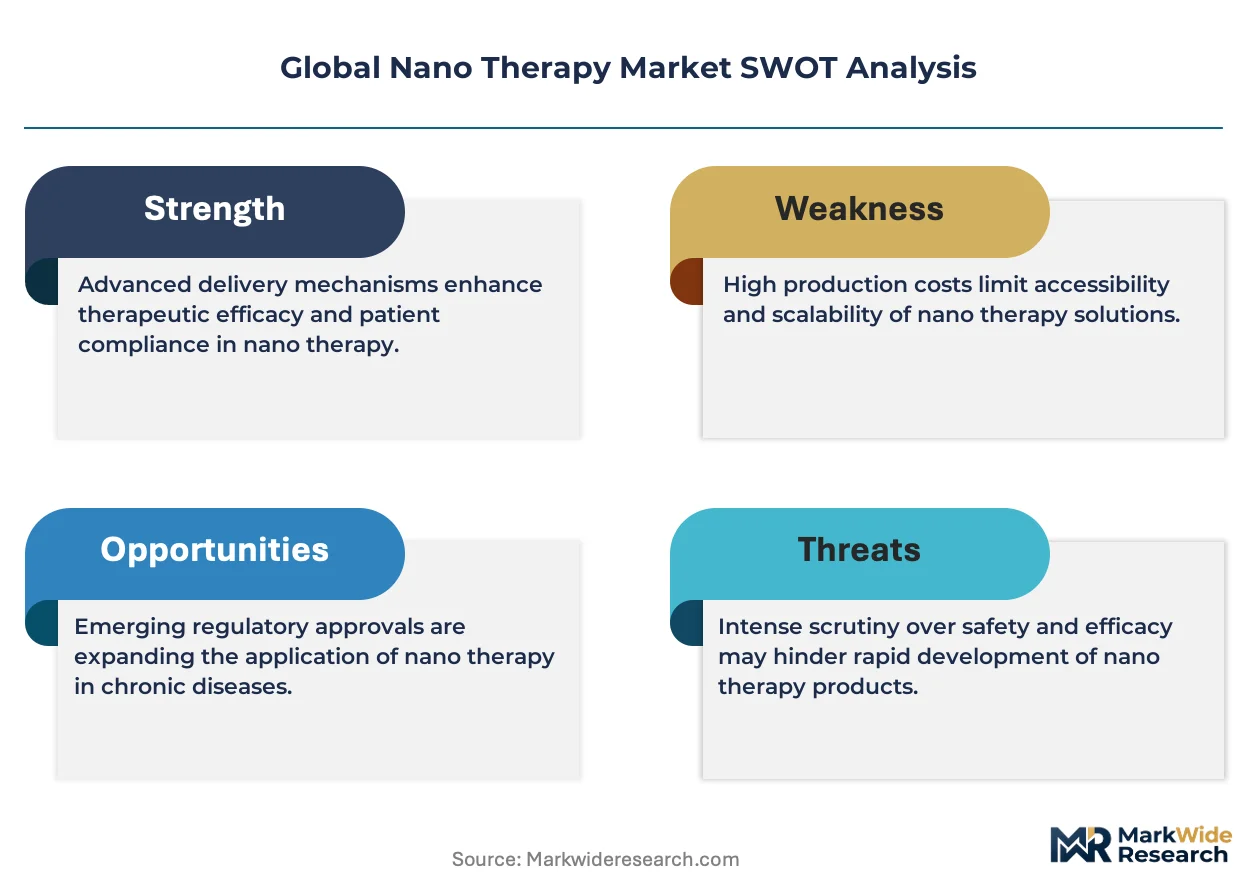
Multi-source procurement of active pharmaceutical ingredients is shifting toward captive nanoparticle manufacturing among top developers. Novartis AG anchors its position through in-house lipid nanoparticle production for gene therapies. Sanofi competes by leveraging external CDMO partnerships while retaining formulation control. Pfizer Inc. dominates commercial-scale mRNA lipid nanoparticle supply through integrated manufacturing networks.
Nano therapy employs engineered nanoscale carriers, typically 1–100 nanometers in diameter, to deliver therapeutic agents with enhanced bioavailability and targeted tissue accumulation. Lipid-based nanoparticles lead clinical translation due to proven mRNA vaccine delivery, while polymer-based nanocarriers represent the fastest-growing segment for controlled-release oncology applications. Metallic nanoparticles occupy a specialized niche in photothermal ablation, with margin pools concentrated in diagnostic-therapeutic combination products. Quantum dots remain preclinical for most therapy areas, though neurological disorder applications show emerging promise for blood-brain barrier penetration.
The FDA's nanotechnology guidance framework and EMA's reflection papers on nanomedicine quality shape product standards, while China's NMPA accelerates local trial requirements for imported nano formulations. REACH compliance in Europe adds material characterization burdens that filter out undercapitalized developers. Stakeholders must monitor evolving pharmacovigilance expectations for long-acting depot formulations and decide on regulatory submission sequencing across jurisdictions before committing to platform scale-up.
Market Dynamics
The FDA's accelerated approval pathways for nanomedicines are compressing development timelines and forcing developers to build manufacturing readiness before Phase II completion. This regulatory velocity is concentrating investment among firms with integrated lipid nanoparticle production capabilities.
Growth Catalysts
- mRNA platform validation:The proven efficacy of lipid nanoparticle delivery in infectious disease vaccines has opened oncology and rare disease applications. Clinical pipelines now prioritize nucleic acid therapeutics using established formulation architectures.
- REACH material characterization:European compliance requirements for nanomaterial safety data have created de facto quality standards that reduce competitive fragmentation. Developers meeting ECHA thresholds gain automatic credibility in multiple jurisdictions.
- Specialized manufacturing clusters:Concentrated expertise in Boston, Basel, and Osaka is shortening supplier qualification cycles. Proximity to regulatory agencies accelerates pre-submission feedback loops.
Market Restraints
- High-purity lipid input costs:Ionizable cationic lipids and PEGylated derivatives face supply constraints from limited qualified chemical suppliers. Price volatility in pharmaceutical-grade cholesterol further squeezes formulation margins.
- Single-source CDMO dependency:Commercial-scale lipid nanoparticle manufacturing concentrates among three contract providers. Capacity allocation disputes during demand surges delay program timelines.
- Immunogenicity uncertainty:PEG-specific antibodies and complement activation risks require extensive patient monitoring. Post-market surveillance obligations extend liability exposure beyond traditional small molecules.
Strategic Opportunities
- Neurological disorder penetration:Blood-brain barrier traversal using surface-modified nanoparticles remains clinically underexploited. Quantum dot and exosome hybrid approaches show preclinical promise for glioblastoma and Alzheimer's delivery.
- India's PLI scheme for pharmaceuticals:Domestic manufacturing incentives for complex generics create entry points for nanoparticle formulation technology transfer. Local CDMO partnerships can serve emerging market demand at reduced cost structures.
- Photothermal-metabolic combination therapy:Gold nanorod platforms integrated with immune checkpoint inhibition enable dual-mechanism oncology protocols. Metallic nanoparticle margins concentrate in diagnostic-therapeutic combination products.
Industry Challenges
- Process analytical technology integration:Real-time particle size and encapsulation efficiency monitoring requires specialized spectroscopy expertise. Talent scarcity in pharmaceutical nanotechnology slows technology transfer from development to commercial suites.
- Multi-jurisdiction submission sequencing:Divergent FDA, EMA, and NMPA expectations for stability data and impurity profiles force redundant study designs. Regulatory strategy misalignment delays first-in-human approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nano Therapy Market |
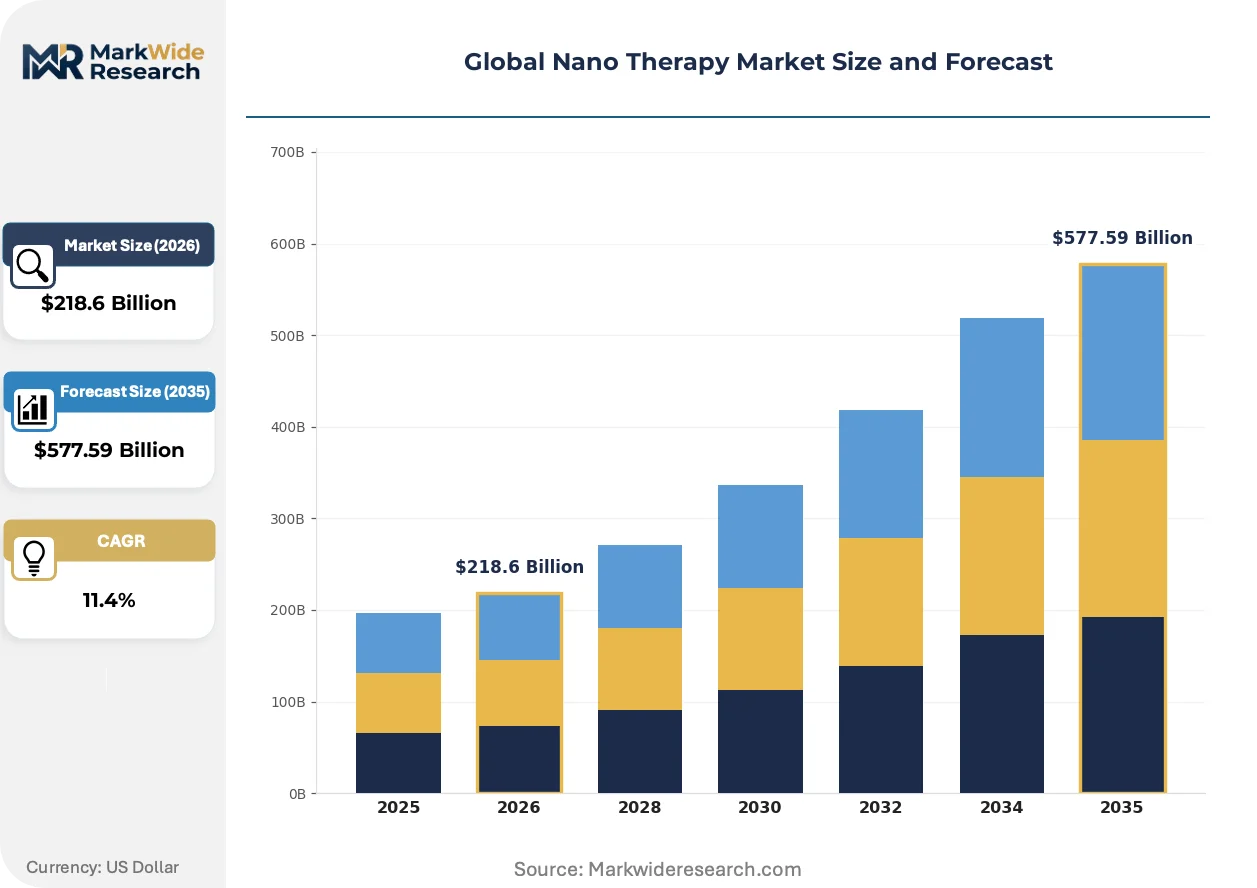
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $577.59 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lipid-Based Nanoparticles, Polymer-Based Nanocarriers, Metallic Nanoparticles, Quantum Dots, Dendrimers Therapy Area: Oncology, Neurological Disorders, Cardiovascular Diseases, Infectious Diseases, Autoimmune Disorders Delivery Mechanism: Intravenous, Oral, Transdermal, Inhalation, Implantable Devices End User: Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Clinical Laboratories, Contract Research Organizations |
| Companies Covered | Novartis AG, Sanofi, Pfizer Inc., Arrowhead Pharmaceuticals, Inc., Alnylam Pharmaceuticals, Inc., Johnson & Johnson, Merck & Co., Inc., AstraZeneca plc, Moderna, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nano Therapy Market Shifts & Advancements
Platform standardization is displacing bespoke formulation development as developers seek regulatory predictability and manufacturing fungibility across therapeutic programs.
Microfluidic manufacturing is modularizing lipid nanoparticle production by enabling continuous-flow synthesis with real-time quality control. Mid-sized biotech firms are adopting these systems to reduce batch-to-batch variability without building traditional stainless-steel suites. The technology is compressing scale-up timelines from years to months for clinical supply.
EMA's reflection papers on nanomedicine quality are harmonizing European expectations for critical quality attributes and comparability protocols. Manufacturers must now demonstrate physicochemical equivalence across production sites before gaining multi-country approval. Oncology applications face the steepest documentation burdens as dose-ranging studies expand.
Hospital procurement consortia are consolidating nanoparticle drug purchasing through centralized tendering mechanisms in Germany and France. Traditional specialty pharmacy distribution channels face margin compression as integrated delivery networks negotiate direct manufacturer contracts. The shift is most visible in cancer centers seeking total cost-of-care accountability for CAR-T and gene therapy administration.
Global Nano Therapy Market Segmentation
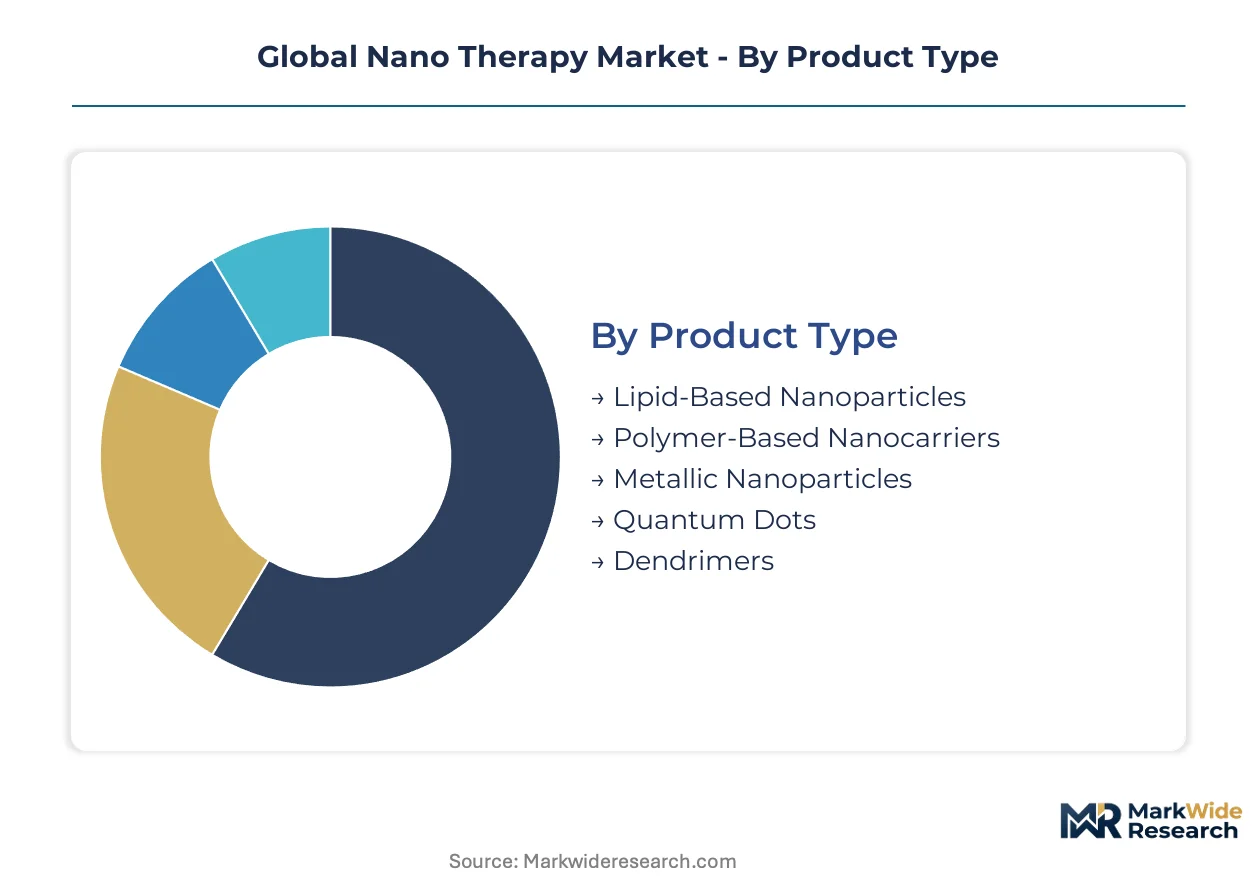
Nano therapy market segmentation reveals distinct regulatory pathways and manufacturing requirements across product architectures. Each category carries specific FDA, EMA, and NMPA compliance burdens that shape commercialization timelines and investment thresholds.
Product Type:
FDA's nanotechnology guidance framework imposes tiered characterization requirements: lipid-based platforms face accelerated review pathways, while metallic and quantum dot formulations trigger extended safety protocols under EPA and REACH oversight.
- Lipid-Based Nanoparticles:Ionizable cationic lipids form the core architecture proven in mRNA vaccine delivery. Demand concentrates in oncology nucleic acid therapeutics where Boston and Basel manufacturing clusters supply Pfizer and Moderna pipeline programs. FDA breakthrough therapy designations compress Phase I-to-approval timelines for this segment.
- Polymer-Based Nanocarriers:Poly(lactic-co-glycolic acid) and polyethylene glycol constructs enable controlled-release kinetics for chronic dosing. Japanese pharmaceutical companies in Osaka prioritize these platforms for Alzheimer's and Parkinson's applications requiring sustained blood-brain barrier penetration. EMA quality reflection papers mandate extensive degradation product monitoring.
- Metallic Nanoparticles:Gold nanorods and iron oxide cores serve photothermal ablation and MRI-guided therapy.
- Quantum Dots:Cadmium-selenide and carbon-based structures remain preclinical for most indications.
- Dendrimers:Branched polyamidoamine architectures offer precise surface functionalization for targeted payload delivery.
Leading the category by volume: Lipid-Based Nanoparticles. Growing fastest: Polymer-Based Nanocarriers.
Therapy Area:
Cost tier segmentation aligns with reimbursement complexity: oncology commands premium pricing with outcome-based contracts, while infectious disease applications face volume-driven procurement pressures from hospital consortia.
- Oncology:CAR-T enhancement and solid tumor penetration drive the steepest R&D investment. German cancer centers in Heidelberg and Munich negotiate direct manufacturer contracts bypassing traditional pharmacy distribution. Payer concentration demands robust progression-free survival data packages.
- Neurological Disorders:Glioblastoma and Alzheimer's represent the largest addressable unmet need. Surface-modified nanoparticles traversing blood-brain barriers attract Japanese PMDA priority review for orphan indications. Clinical trial recruitment challenges in progressive patient populations extend development timelines.
- Cardiovascular Diseases:Atherosclerotic plaque targeting and ischemic tissue regeneration applications.
- Infectious Diseases:mRNA vaccine delivery established validation; expansion into antimicrobial resistance therapies.
- Autoimmune Disorders:Tolerance induction via antigen-specific nanoparticle presentation.
Dominant by revenue concentration: Oncology. Expanding most quickly: Neurological Disorders.
Delivery Mechanism:
Application setting determines infrastructure requirements: hospital-based intravenous administration needs cold-chain logistics, while oral and transdermal formats enable outpatient chronic disease management.
- Intravenous:Lipid nanoparticle infusion requires specialized pharmacy compounding and patient monitoring for complement activation. United States oncology infusion centers in Houston and New York City build dedicated nanomedicine administration suites. PEG-specific antibody screening protocols add pre-treatment cost burdens.
- Oral:Gastrointestinal stability challenges limit bioavailability for most nanocarrier architectures. Indian CDMOs in Hyderabad develop enteric coating technologies for emerging market cost structures. BCS classification complexity delays ANDA approvals for complex generic nanoparticles.
- Transdermal:Microneedle arrays and permeation-enhancing formulations.
- Inhalation:Pulmonary deposition targeting for respiratory and systemic delivery.
- Implantable Devices:Long-acting depot formulations requiring surgical placement.
Highest procedure volume: Intravenous. Gaining share fastest: Oral.
End User:
Customer type segmentation reflects divergent procurement authority: pharmaceutical companies control platform licensing decisions, while research institutes influence early-stage technology adoption through grant-funded investigator-initiated trials.
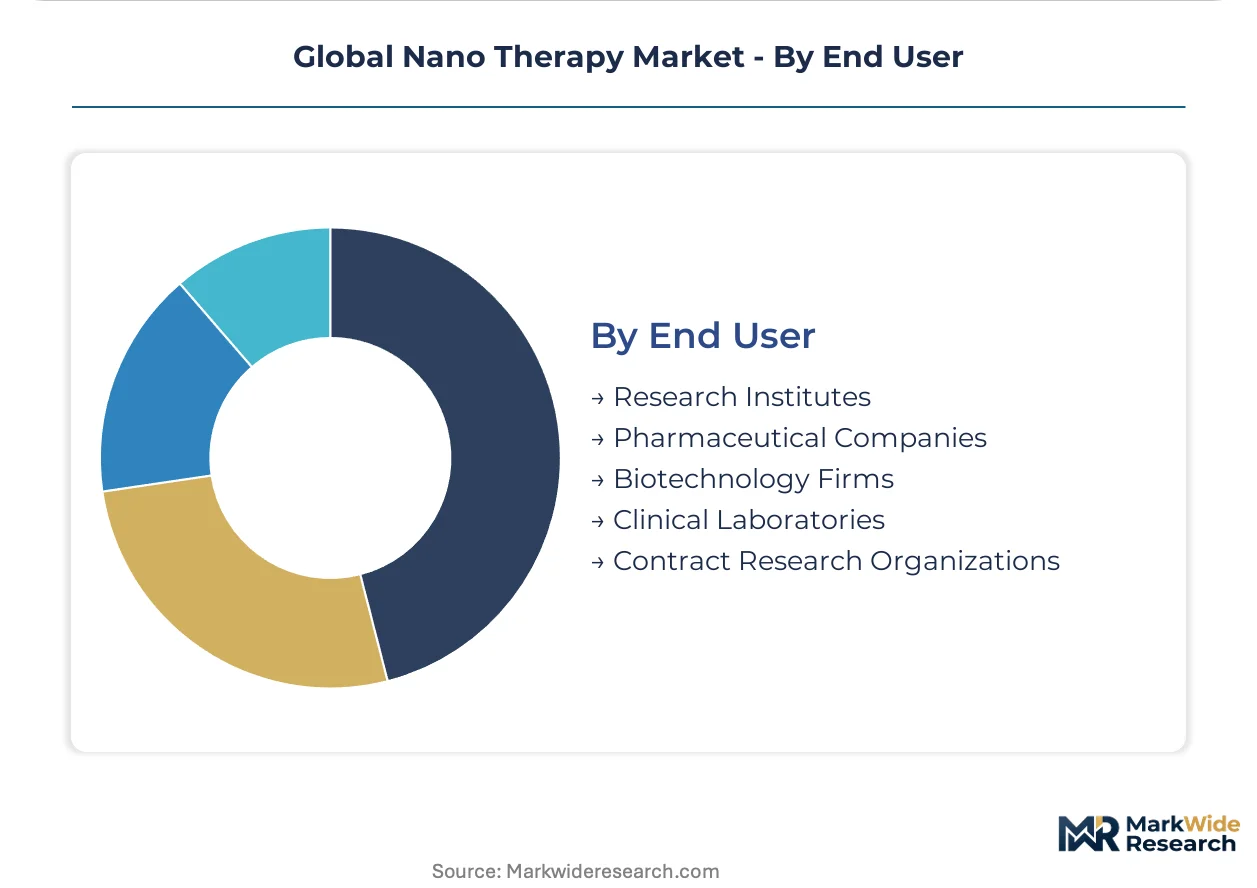
- Pharmaceutical Companies:Integrated manufacturing investments dominate capital allocation for commercial-scale lipid nanoparticle production. Novartis AG and Sanofi build captive supply chains to reduce CDMO dependency. Internal platform standardization across therapeutic programs accelerates regulatory submission preparation.
- Biotechnology Firms:Asset-specific licensing deals with university technology transfer offices. Mid-sized developers in Cambridge and South San Francisco adopt microfluidic manufacturing to compress scale-up timelines. Venture financing availability fluctuates with clinical proof-of-concept data readouts.
- Research Institutes:NIH and Wellcome Trust funding priorities shape preclinical pipeline directions.
- Clinical Laboratories:Companion diagnostic development for nanoparticle theranostic combinations.
- Contract Research Organizations:Specialized bioanalytical capabilities for pharmacokinetic studies.
Largest procurement authority: Pharmaceutical Companies. Climbing the fastest: Biotechnology Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ionizable cationic lipid supply chains anchor manufacturing investment in the United States, Germany, and Japan, where specialized production clusters have formed around regulatory expertise and CDMO concentration.
United States
FDA breakthrough therapy designations for lipid nanoparticle oncology programs accelerate clinical timelines. The agency's nanotechnology guidance framework mandates tiered characterization that filters undercapitalized developers. Boston and Houston manufacturing clusters supply Pfizer and Moderna pipeline programs while building dedicated nanomedicine administration suites in oncology infusion centers.
Germany
Heidelberg and Munich cancer centers negotiate direct manufacturer contracts that bypass traditional pharmacy distribution channels. REACH material characterization requirements through ECHA create de facto quality standards reducing competitive fragmentation. Hospital procurement consortia consolidate nanoparticle drug purchasing through centralized tendering mechanisms across Baden-Württemberg and Bavaria.
Japan
PMDA priority review for orphan neurological indications attracts surface-modified nanoparticle developers targeting blood-brain barrier traversal. METI funding priorities support Osaka-based manufacturing clusters specializing in polymer-based nanocarriers for Alzheimer's applications. Clinical trial recruitment challenges in progressive patient populations extend development timelines for glioblastoma programs.
China
NMPA accelerates local trial requirements for imported nano formulations while building domestic lipid nanoparticle capabilities. Yangtze River Delta biotech parks attract technology transfer partnerships for complex generic nanoparticle production. SAMR oversight of nanomaterial safety data creates parallel compliance tracks for multinational sponsors.
India
PLI scheme incentives for pharmaceutical manufacturing create entry points for nanoparticle formulation technology transfer. Hyderabad CDMOs develop enteric coating technologies for oral nanocarrier bioavailability challenges. CDSCO abbreviated approval pathways for complex generics concentrate investment among firms with captive lipid supply chains.
Global Nano Therapy Market Competitive Landscape
Capacity expansion dominates the current landscape as developers build manufacturing readiness before Phase II completion. The vendor base concentrates among integrated pharmaceutical conglomerates and specialized biotechnology firms with platform standardization capabilities. Three archetypes define competitive positioning: captive manufacturers controlling lipid supply chains, CDMO-dependent developers leveraging external partnerships, and microfluidic technology adopters compressing scale-up timelines. M&A activity targets formulation expertise and regional manufacturing footprints, while strategic partnerships secure ionizable cationic lipid supply from limited qualified chemical suppliers.
Within the integrated manufacturing tier, Novartis AG anchors European positioning through Swiss-based captive production networks. Sanofi exemplifies the hybrid archetype combining external CDMO partnerships with retained formulation control. Pfizer Inc. occupies the scale-driven position through commercial-scale mRNA lipid nanoparticle supply chains. Arrowhead Pharmaceuticals, Inc. and Alnylam Pharmaceuticals, Inc. represent the biotechnology specialist vector with asset-specific licensing strategies and RNAi platform concentration.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi |
| Pfizer Inc. |
| Arrowhead Pharmaceuticals, Inc. |
| Alnylam Pharmaceuticals, Inc. |
| Johnson & Johnson |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Moderna, Inc. |
| Others |
Supply & Pricing Matrix
Hospital procurement consortia in Germany and France are consolidating nanoparticle drug purchasing through centralized tendering mechanisms, forcing manufacturers to absorb cold-chain logistics costs into bundled service agreements while competing on total cost-of-care accountability rather than per-unit pricing.
Pricing Analysis
Service bundling separates manufacturers offering integrated patient monitoring and PEG-specific antibody screening protocols from those pricing drug product alone. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with FDA breakthrough therapy designation carrying certification premiums. Pricing pressure stems from single-source CDMO dependency concentrating capacity allocation leverage among three contract providers. Biotechnology firms with microfluidic manufacturing capabilities exhibit lowest price sensitivity due to compressed scale-up timelines, while hospital systems negotiating direct contracts show highest sensitivity to per-dose economics.
Supply Chain Analysis
Cold-chain freight costs for ionizable cationic lipids and PEGylated derivatives anchor supply chain economics, with pharmaceutical-grade cholesterol shipments requiring temperature-controlled logistics from limited qualified chemical suppliers in the United States, Germany, and Switzerland. Raw material dependencies center on ionizable lipids, high-purity cholesterol, and nucleoside phosphoramidites. Single-source vulnerability concentrates among three commercial-scale lipid nanoparticle CDMOs. Distribution runs through specialized pharmacy compounding networks with dedicated nanomedicine administration suites in oncology infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Nano Therapy Market functions as a vertical-integration race where captive lipid supply chains determine manufacturing readiness before Phase II completion, with ionizable cationic lipid procurement emerging as the decisive upstream lever.
For Market Incumbents: Deepen backward integration into ionizable cationic lipid production to reduce CDMO dependency and defend margins against emerging microfluidic technology adopters. Expand captive manufacturing footprints in Boston and Basel clusters to accelerate regulatory submission preparation. Secure long-term supply agreements with qualified chemical suppliers before capacity allocation disputes intensify.
For New Entrants and Emerging Players: Capture white-space opportunities in neurological disorder applications where blood-brain barrier traversal remains clinically underexploited, particularly glioblastoma and Alzheimer's delivery using surface-modified polymer nanocarriers. Target India's PLI scheme incentives for technology transfer partnerships with Hyderabad CDMOs. Pursue asset-specific licensing strategies with university technology transfer offices to access quantum dot and exosome hybrid platforms.
For Investors and Strategic Acquirers: The window for entry favors biotechnology specialists with RNAi platform concentration and microfluidic manufacturing capabilities. Long-term viability rests on regulatory submission sequencing expertise across FDA, EMA, and NMPA jurisdictions. Watch for inflection signals in PMDA priority review designations for orphan neurological indications as validation of blood-brain barrier penetration platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive lipid nanoparticle production reduces CDMO dependency and accelerates regulatory timelines. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase I-to-approval timelines for oncology nucleic acid therapeutics. |
| Licensing Agreement | Asset-specific deals with university technology transfer offices access preclinical quantum dot platforms. |
| Pipeline Diversification | Expansion from infectious disease mRNA into oncology and rare disease applications leverages proven formulation architectures. |
| Joint Venture | Local CDMO partnerships in India serve emerging market demand at reduced cost structures under PLI incentives. |
Research Methodology
Multi-period observation of clinical trial advancement rates, regulatory submission patterns, and manufacturing capacity buildouts anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, therapy area, delivery mechanism, and end user categories.
Input-output matrix framing connected ionizable lipid supply constraints to formulation pricing dynamics and CDMO capacity utilization to program timeline compression. Segmentation dimensions modeled included nanocarrier architecture, therapeutic indication, administration route, and regional regulatory cluster across the projection horizon. CAGRs derived from patient population epidemiology, treatment penetration assumptions, and pricing trajectory analysis. Industry-specific inputs encompassed REACH material characterization compliance rates and PMDA priority review designation frequencies.
The model holds under stable regulatory harmonization between FDA, EMA, and NMPA; deviation in jurisdictional divergence or immunogenicity signal emergence would shift commercialization timelines and investment thresholds. Forecasts reflect documented assumptions regarding manufacturing scale-up feasibility and lipid supplier qualification rates. Stakeholders should weight assumptions against their own operating context and captive supply chain development status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market