
 Anorectal Malformation Treatment Market | 2026-2036
Anorectal Malformation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anorectal Malformation Treatment Market Outlook
Pediatric hospitals are rebalancing toward dedicated anorectal malformation centers as surgical volume shifts away from general community hospitals. Medtronic anchors its position through advanced energy device portfolios used in posterior sagittal approaches. Johnson & Johnson (Ethicon) differentiates via suture and mesh platforms tailored to neonatal tissue properties. Becton, Dickinson and Company competes through instrument systems that integrate with minimally invasive pediatric workflows.
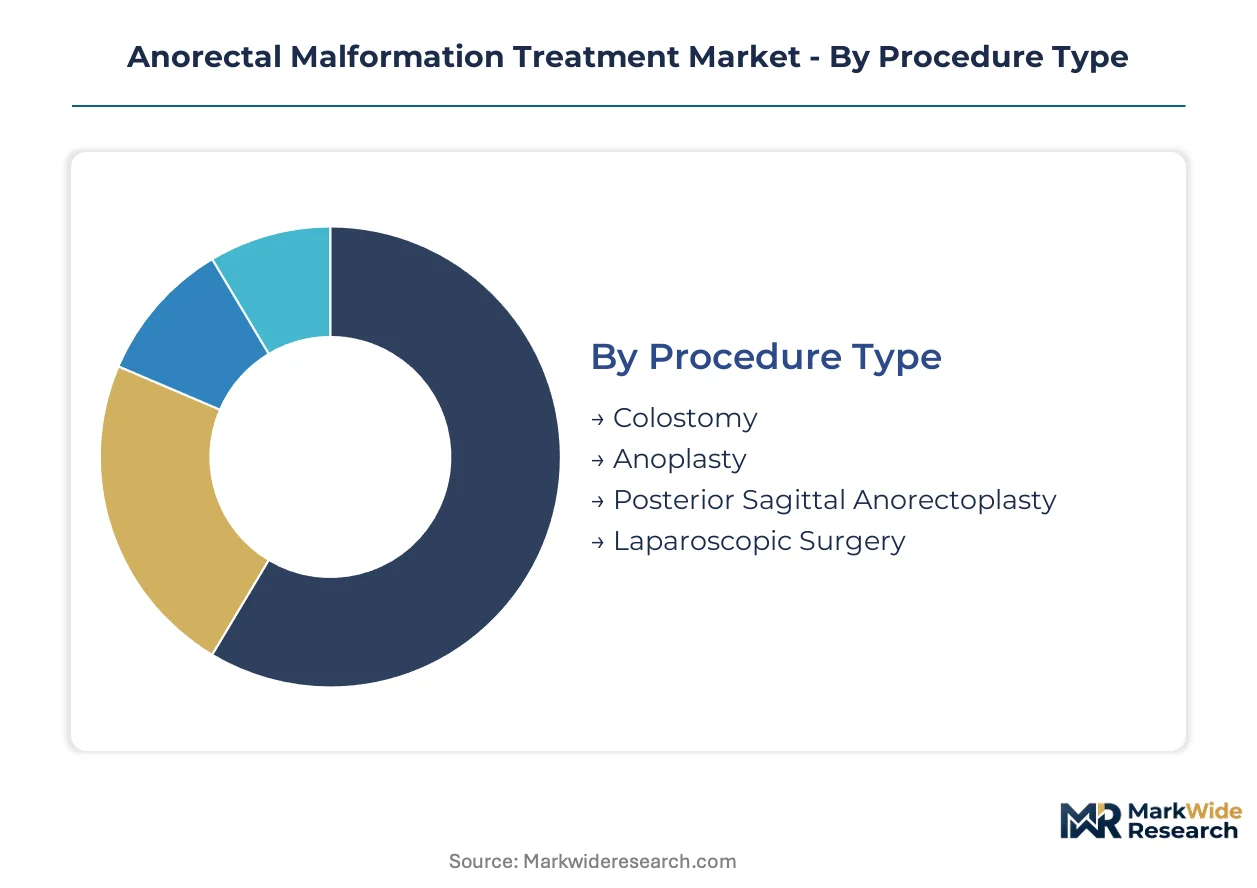
Anorectal malformation treatment encompasses surgical correction of congenital defects in the rectum and anus, typically requiring staged procedures involving colostomy creation, definitive pull-through, and continence restoration, with outcomes measured by bowel function scores and quality-of-life indices. The procedure type dimension shows posterior sagittal anorectoplasty occupying the core volume position due to its status as the standard definitive repair, while laparoscopic approaches represent the fastest-growing category as centers adopt minimally invasive techniques for high-type lesions. The technology dimension reveals minimally invasive surgery capturing expanding share in tertiary pediatric centers, though traditional open approaches retain dominance in resource-limited settings where robotic capital investment remains prohibitive.
FDA pediatric device guidance shapes product development timelines by requiring age-specific safety data, while EU MDR imposes stricter clinical evidence standards for implantable surgical materials used in neonatal populations. Health Canada's pediatric regulatory framework adds another compliance layer for manufacturers seeking North American market access. Stakeholders must monitor how evolving reimbursement for robotic-assisted pediatric procedures influences capital allocation across hospital systems.
Market Dynamics
Pediatric surgical centers are consolidating anorectal malformation procedures into dedicated colorectal programs, concentrating case volume in tertiary institutions while community hospitals exit complex neonatal reconstruction. This volume migration is reshaping instrument procurement patterns and vendor relationships.
Growth Catalysts
- EU MDR pediatric safety frameworks:Stricter clinical evidence requirements for implantable neonatal materials are accelerating hospital upgrades to certified device portfolios, driving replacement cycles.
- Robotic-assisted pull-through procedures:Tertiary pediatric centers are integrating minimally invasive platforms for high-type lesions, expanding addressable procedure volumes.
- Japan's congenital anomaly referral networks:Deepening concentration of specialized cases in designated children's hospitals is concentrating demand for advanced surgical instrumentation.
Market Restraints
- Capital intensity of robotic platforms:Da Vinci system acquisition and maintenance costs exceed budgets of mid-tier pediatric hospitals, limiting addressable market expansion.
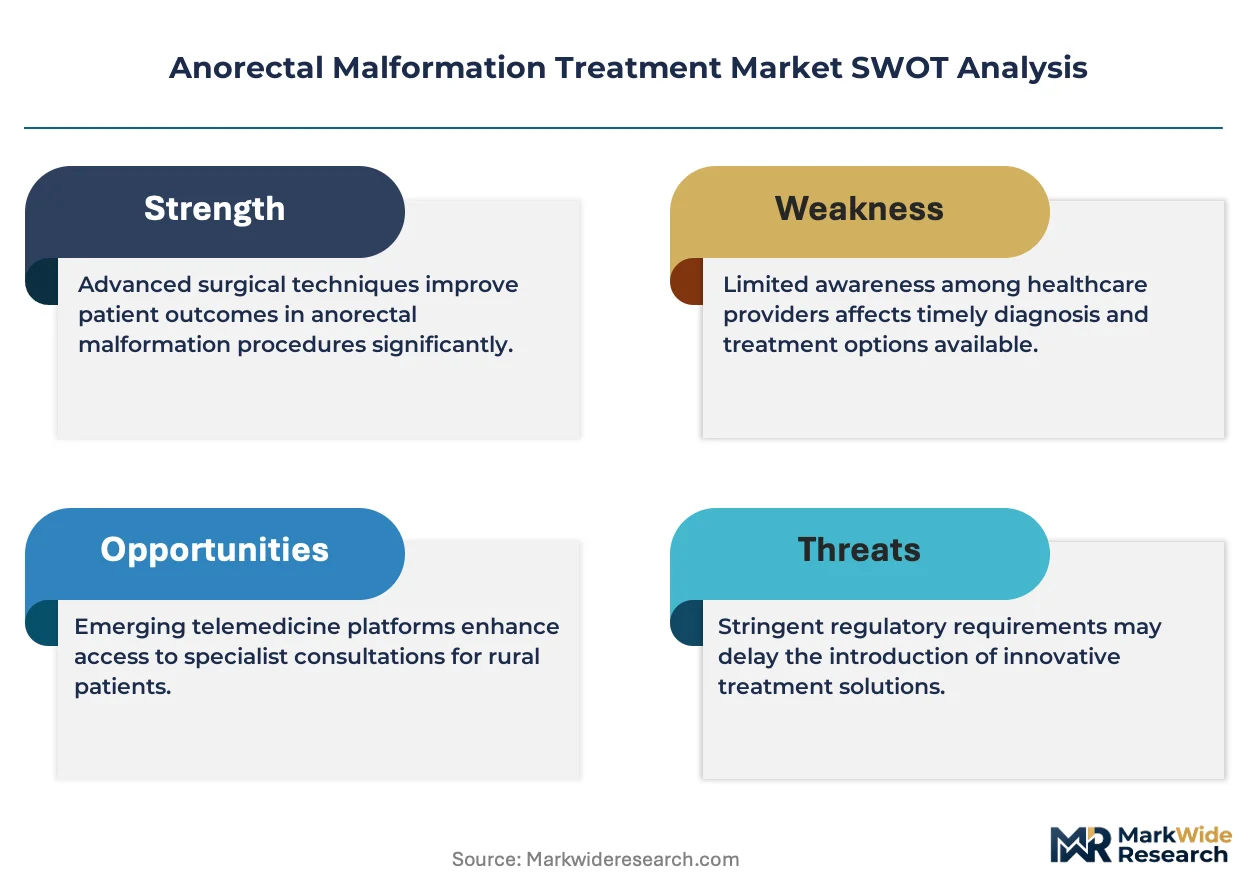
- Neonatal tissue-specific validation requirements:FDA pediatric device guidance mandates age-stratified safety data, extending development timelines and elevating R&D costs.
- Specialized pediatric surgeon scarcity:Fellowship-trained pediatric colorectal specialists concentrate in academic medical centers, constraining procedure volume growth outside major metropolitan clusters.
Strategic Opportunities
- India's emerging pediatric surgery infrastructure:Government-funded children's hospital expansion under national health missions is creating first-mover advantages for instrument suppliers establishing training partnerships.
- Teleproctoring-enabled skill transfer:Real-time surgical guidance platforms are allowing high-volume centers to support distant procedures, expanding serviceable geography.
- Bioresorbable anastomotic reinforcement:Convergence of absorbable polymer science with neonatal surgical applications offers pathways to reduce reoperation rates.
Industry Challenges
- Pediatric-specific regulatory navigation:Health Canada's pediatric framework imposes additional clinical evidence layers, complicating North American market entry strategies.
- Instrument sterilization validation:Reusable laparoscopic tools for neonates require specialized reprocessing protocols that many surgical centers lack infrastructure to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anorectal Malformation Treatment Market |
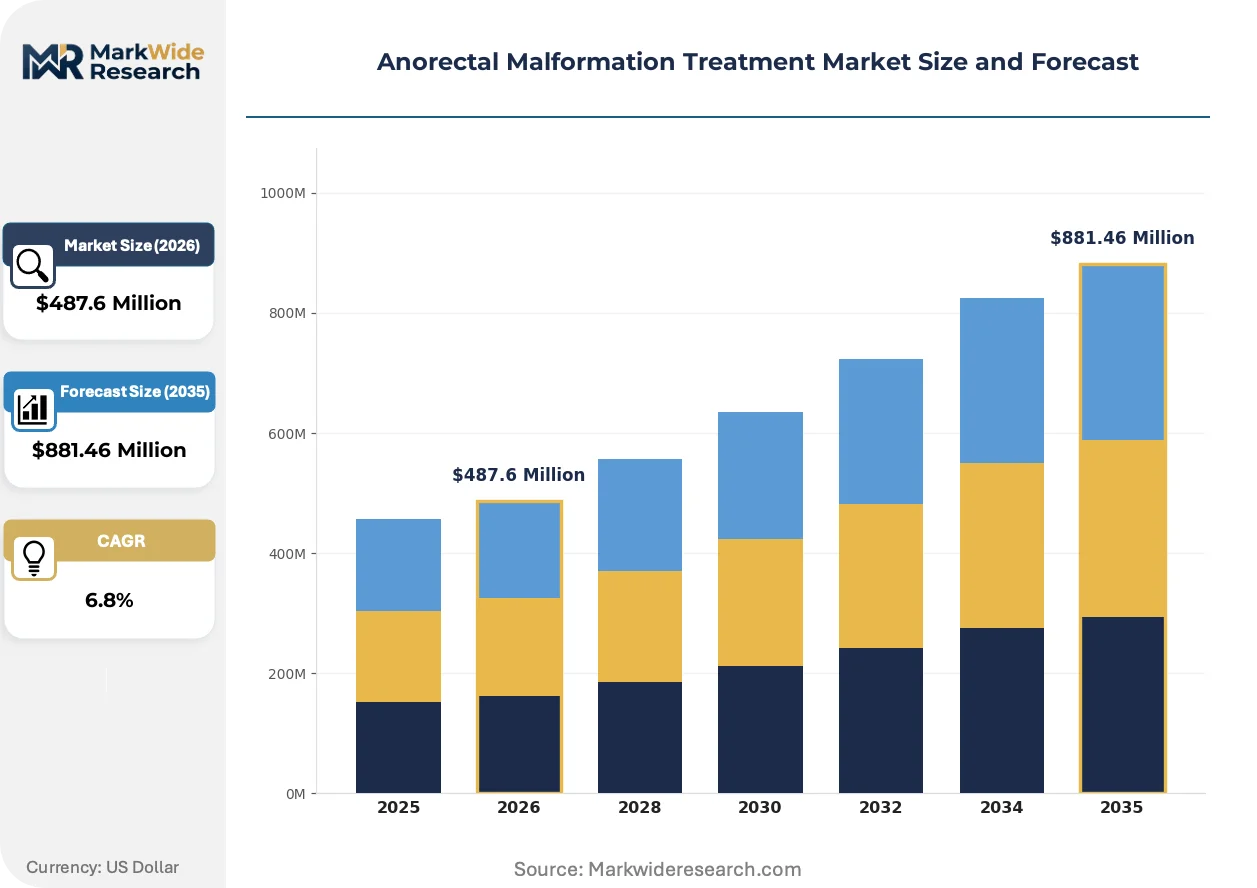
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Colostomy, Anoplasty, Posterior Sagittal Anorectoplasty, Laparoscopic Surgery End User: Pediatric Hospitals, Surgical Centers, Medical Clinics, Specialty Clinics Technology: Robotic Surgery, Minimally Invasive Surgery, Traditional Surgery, Laser Surgery Care Setting: Inpatient, Outpatient, Emergency Care, Follow-Up Care |
| Companies Covered | Sanofi, Bausch Health Companies Inc., Medtronic, Becton, Dickinson and Company, Stryker, Johnson & Johnson (Ethicon), Cleveland Clinic, Nationwide Children's Hospital, Intermountain Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anorectal Malformation Treatment Market Strategic Shifts
Surgical technique evolution and regulatory recalibration are compressing development timelines while elevating performance thresholds for neonatal reconstruction devices. Three intersecting developments are restructuring competitive positioning.
Single-incision laparoscopic platforms are absorbing capital allocation previously directed toward multi-port systems in pediatric colorectal surgery. Tertiary children's hospitals in Germany and the United States are piloting these approaches for high-type anorectal malformations, reducing abdominal wall trauma in neonates. The technology is absorbing market share from conventional laparoscopy by promising faster recovery and improved cosmetic outcomes.
REACH substance restrictions are forcing reformulation of polymeric suture materials and mesh composites used in neonatal pull-through procedures. European manufacturers are accelerating biocompatible alternative development to maintain CE marking compliance. Pediatric device divisions face the steepest reformulation burden, as neonatal exposure thresholds sit below general surgical material limits.
Consolidated procurement through hospital system central contracts is displacing individual surgeon preference in instrument selection. Large United States pediatric networks are standardizing across affiliated children's hospitals, compressing vendor diversity. This pattern is most visible in the southeastern United States, where health system mergers have reduced supplier counts by half across neonatal surgical service lines.
Anorectal Malformation Treatment Market Segmentation
Surgical technique evolution and care setting diversification are fragmenting procurement patterns across pediatric colorectal service lines. Vendors must align portfolio development with distinct upgrade cycles across open, laparoscopic, and robotic platforms.
Procedure Type:
Replacement cycles accelerate where centers transition from multi-stage open repairs toward single-approach definitive reconstruction.
- Posterior Sagittal Anorectoplasty:The standard definitive repair employs midline sacral incision with precise sphincter complex reconstruction. Demand concentrates in United States and German tertiary children's hospitals where fellowship-trained pediatric colorectal surgeons manage high case volumes.
- Laparoscopic Surgery:Minimally invasive approaches for high-type lesions utilize multi-port or single-incision abdominal entry with laparoscopic-assisted pull-through. Tertiary centers in Japan and the United States are absorbing capital for platform expansion as outcomes data matures.
- Colostomy:Diverting stoma creation remains the initial staged procedure for high-type malformations, performed in neonatal intensive care settings.
- Anoplasty:Perineal reconstruction for low-type lesions without colostomy requirement.
Posterior sagittal anorectoplasty sits at the top of the volume ranking, with laparoscopic surgery climbing the fastest.
End User:
Customer concentration patterns track the geographic distribution of fellowship-trained pediatric colorectal specialists and dedicated surgical volume.
- Pediatric Hospitals:Dedicated children's hospitals with colorectal surgery programs account for the dominant share of complex neonatal reconstruction. United States academic medical centers and Japan's designated children's hospitals are deepening referral networks that concentrate demand.
- Surgical Centers:Ambulatory facilities handle select follow-up procedures and secondary interventions for established patients with stabilized anatomy.
- Medical Clinics:General pediatric and family practice settings manage initial screening and referral coordination.
- Specialty Clinics:Dedicated anorectal malformation centers provide longitudinal bowel management and continence restoration programs.
Pediatric hospitals command the procurement budget concentration, with specialty clinics expanding fastest as longitudinal care models mature.
Technology:
Capital allocation intensity varies sharply across platforms, with robotic systems requiring dedicated infrastructure and maintenance contracts.
- Minimally Invasive Surgery:Conventional laparoscopic and thoracoscopic platforms represent the core technology transition pathway for centers upgrading from open approaches. German and United States pediatric networks are standardizing instrument configurations across system-affiliated hospitals.
- Robotic Surgery:Da Vinci systems enable enhanced dexterity for high-type pull-through procedures in narrow neonatal pelvic anatomy. Capital intensity limits deployment to elite tertiary centers with sufficient case volume to justify fixed costs.
- Traditional Surgery:Open posterior sagittal and perineal approaches retain dominance where minimally invasive capital investment remains prohibitive.
- Laser Surgery:Selective application for fistula management and tissue dissection in specific anatomical variants.
Traditional surgery retains volume leadership, with robotic surgery gaining share fastest among capital-equipped centers.
Care Setting:
Reimbursement structures and clinical acuity determine where each procedural phase occurs across the care continuum.
- Inpatient:Neonatal definitive reconstruction and staged procedures require intensive care capability and specialized nursing. United States children's hospitals and Japan's national children's medical centers maintain the deepest inpatient surgical infrastructure.
- Emergency Care:Acute obstruction management and stoma complications present through emergency departments.
- Outpatient:Selective anoplasty and fistula procedures migrate to ambulatory settings as techniques standardize.
- Follow-Up Care:Bowel management programs and continence restoration therapy occur across multiple settings.
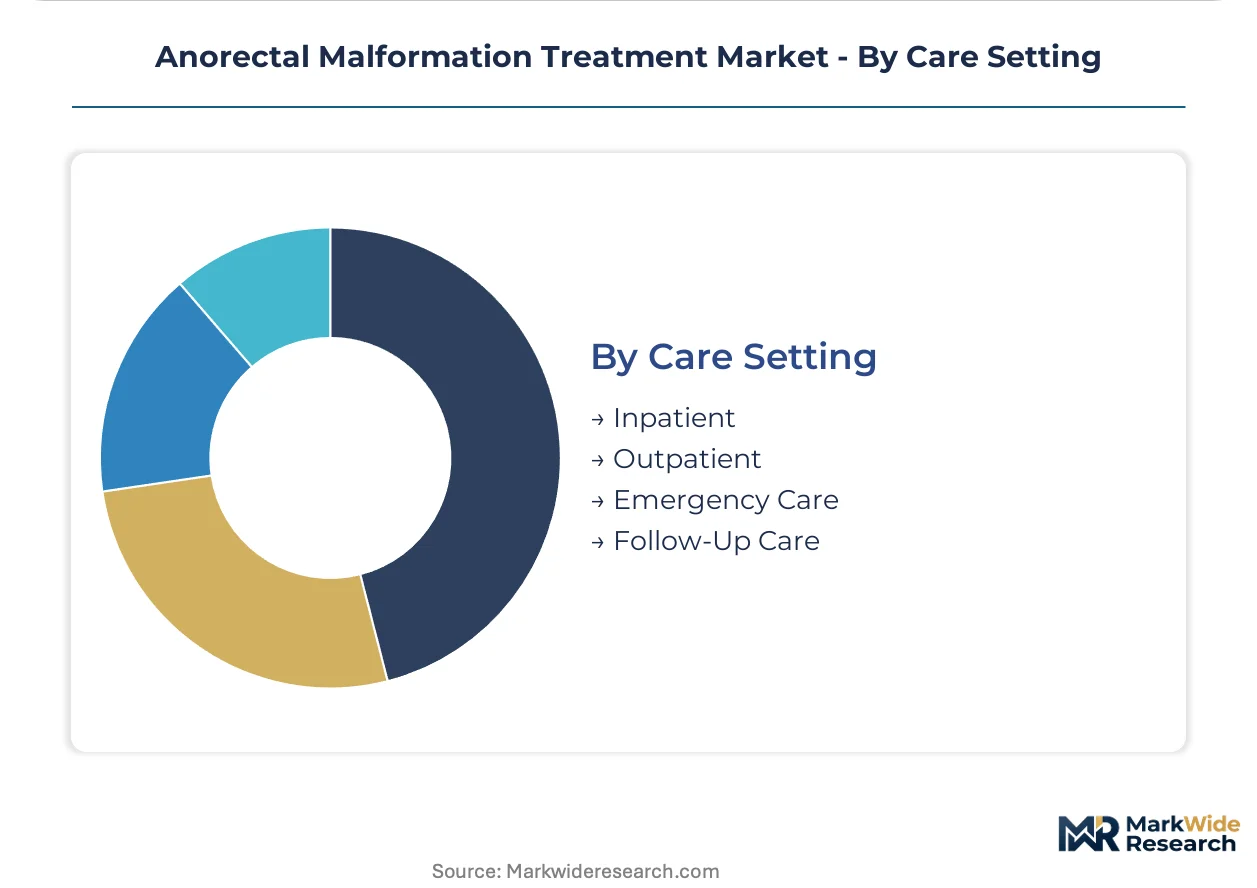
Inpatient care anchors procedure value, with outpatient migration expanding fastest as ambulatory reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating pediatric surgical instrument production in jurisdictions with streamlined premarket pathways, while demand clusters where referral networks for congenital anomalies are deepest. FDA pediatric device guidance and EU MDR safety requirements create compliance cost differentials that shape manufacturing location decisions.
United States
Pediatric hospitals in Boston and Philadelphia are deepening dedicated colorectal surgery programs that concentrate case volume. FDA pediatric device guidance mandates age-stratified safety data, extending development timelines for neonatal surgical materials. The southeastern United States shows health system mergers reducing supplier counts by half across neonatal surgical service lines.
Germany
Tertiary children's hospitals in Bavaria and North Rhine-Westphalia are piloting single-incision laparoscopic platforms for high-type anorectal malformations. REACH substance restrictions are forcing reformulation of polymeric suture materials to maintain CE marking compliance. The Eindhoven-to-Dortmund corridor hosts instrument sterilization validation facilities serving central European pediatric networks.
Japan
Designated children's hospitals in Tokyo and Osaka are deepening congenital anomaly referral networks that concentrate demand for advanced surgical instrumentation. METI industrial policy supports domestic production of minimally invasive surgical platforms. The Kanto region maintains the deepest inpatient surgical infrastructure for neonatal definitive reconstruction.
India
Government-funded children's hospital expansion under national health missions is creating first-mover advantages for instrument suppliers. CDSCO pediatric regulatory frameworks are evolving toward alignment with international standards. Maharashtra and Karnataka are absorbing capital for pediatric surgery infrastructure as training partnerships mature with tertiary academic medical centers.
United Kingdom
Pediatric colorectal specialists in London and Manchester are consolidating anorectal malformation procedures into dedicated programs. MHRA post-Brexit regulatory autonomy is creating divergence from EU MDR implementation timelines. The NHS England specialized commissioning framework is standardizing instrument procurement across affiliated children's hospitals.
Anorectal Malformation Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated device portfolios commanding premium positioning in tertiary pediatric centers while regional suppliers capture replacement cycles in emerging markets. The vendor base organizes around three archetypes: diversified medtech conglomerates with pediatric divisions, dedicated pediatric surgical instrument specialists, and hospital-affiliated research enterprises. M&A activity concentrates on minimally invasive platform acquisitions, while strategic partnerships focus on teleproctoring-enabled skill transfer networks.
Among diversified medtech conglomerates, Medtronic, Johnson & Johnson (Ethicon), and Stryker occupy positions anchored by energy device portfolios, suture platforms, and integrated instrument systems respectively. Becton, Dickinson and Company represents the specialized instrumentation archetype with workflows designed for neonatal minimally invasive procedures. Cleveland Clinic and Nationwide Children's Hospital exemplify the hospital-affiliated research enterprise model, where clinical volume drives protocol development that shapes vendor selection criteria across referral networks.
| Leading Market Players |
|---|
| Sanofi |
| Bausch Health Companies Inc. |
| Medtronic |
| Becton, Dickinson and Company |
| Stryker |
| Johnson & Johnson (Ethicon) |
| Cleveland Clinic |
| Nationwide Children's Hospital |
| Intermountain Healthcare |
| Others |
Value Chain & Pricing Dynamics
Hospital-affiliated research enterprises and sovereign-backed children's hospital networks anchor procurement concentration, translating volume aggregation into pricing leverage while channeling supply contracts toward vendors with validated pediatric regulatory dossiers.
Pricing Analysis
Distributor margins on neonatal surgical instruments compress as health system central contracts displace individual surgeon preference. Three-tier pricing structure across premium, standard, and economy levels tracks CE marking tier and volume scale, with FDA-cleared portfolios commanding substantial premia over Health Canada-only submissions. Cost compression in standard-tier laparoscopic platforms is intensifying because consolidated procurement through southeastern United States pediatric networks halves supplier counts. Academic medical centers exhibit lowest price sensitivity; mid-tier community hospitals exiting complex reconstruction show highest.
Supply Chain Analysis
Domestic-content mandates under India's national health missions are reshaping sourcing, requiring local assembly for government-funded children's hospital tenders. Component manufacturing concentrates in Germany, the United States, and Japan, with specialized sterilization validation facilities clustering in the Eindhoven-to-Dortmund corridor. Supply draws from polymeric suture materials, energy device electronics, and precision-machined laparoscopic instruments. Single-source vulnerability runs through REACH-compliant polymer suppliers facing reformulation deadlines. Distribution runs through regional medical device distributors with pediatric specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where referral network deepening and EU MDR compliance costs filter demand toward premium-certified portfolios.
For Market Incumbents: Deploy certification investment as the primary lever. Accelerate FDA pediatric device guidance compliance to maintain access to United States academic medical centers; consolidate channel control through exclusive distribution agreements with designated children's hospitals in Japan. Threat substitution from single-incision platforms demands proactive portfolio refresh. For New Entrants and Emerging Players: Teleproctoring-enabled skill transfer routes offer lowest-friction entry. Target India's government-funded children's hospital expansion as the most penetrable geography; establish training partnerships with Maharashtra and Karnataka academic medical centers. Go-to-market angle: bundle instrument supply with real-time surgical guidance platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier instrument sterilization validation specialists with pediatric protocol expertise. Five-to-ten year viability hinges on robotic-assisted procedure reimbursement expansion. Acquisition target archetype: bioresorbable anastomotic reinforcement developers with neonatal-specific polymer science. Signal to watch: METI industrial policy shifts on domestic production subsidies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pediatric Device Submission | Age-stratified safety data unlocks United States academic medical center procurement. |
| CE Marking Pathway Acceleration | REACH-compliant reformulation maintains European tertiary children's hospital access. |
| Hospital System Partnership | Exclusive supply agreements with Japan's designated children's hospitals concentrate volume. |
| Software Companion Development | Teleproctoring platforms expand serviceable geography for high-type lesion procedures. |
| Reimbursement Strategy | Robotic-assisted pull-through coding determines capital allocation across pediatric networks. |
Study Parameters
Bottom-up pediatric hospital procurement modeling reconciled against top-down surgical instrument production tracking forms the analytical core. Primary interviews with pediatric colorectal surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EUDAMED device registrations, hospital procurement databases, and CMS Medicare reimbursement data. Triangulation against manufacturer production disclosures and customs records ensures coverage alignment.
Historical trendline analysis across procedure volume, technology adoption, and regulatory submission trajectories informed projection parameters. Segmentation dimensions modeled include procedure type, care setting, technology platform, and end-user concentration tier. CAGRs derive from fitted growth curves applied to bottom-up volume estimates, calibrated against top-down market sizing. Forecast inputs incorporate EU MDR transition timelines and robotic-assisted procedure diffusion rates.
The model assumes a particular technology adoption path; alternative pathways for single-incision laparoscopic platforms would alter the outlook. Forecasts reflect assumptions on referral network consolidation velocity and REACH substance restriction implementation timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Hypercoagulability Treatment Market