
 Non-Infectious Diarrhea Treatment Market | 2026-2036
Non-Infectious Diarrhea Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Infectious Diarrhea Treatment Market Analytics
Gastroenterology specialist shortages across developed healthcare systems is redrawing competitive dynamics in chronic diarrhea management. Pfizer Inc. leverages its biologics manufacturing infrastructure to sustain supply security for inflammatory bowel disease therapies. Sanofi anchors its position through deep relationships with European hospital formularies, while GlaxoSmithKline competes aggressively in over-the-counter antidiarrheal segments through pharmacy channel dominance.
Non-infectious diarrhea treatment encompasses pharmacological and non-pharmacological interventions targeting chronic or recurrent diarrheal symptoms not attributable to pathogens, typically formulated with electrolyte-balancing compounds, opioid-receptor agonists, or live microbial cultures to restore intestinal homeostasis. The primary commercial purpose centers on reducing stool frequency, improving patient quality of life, and preventing dehydration-related hospitalizations in chronic conditions. Oral rehydration solutions occupy the largest volume position due to their first-line status in clinical protocols across therapy areas, while probiotics represent the fastest-expanding category as functional gastrointestinal disorder diagnoses multiply. Malabsorption syndromes command premium pricing within the therapy area dimension, reflecting the complexity of enzyme replacement and specialized nutritional support required.
The FDA maintains stringent bioequivalence requirements for generic antidiarrheal formulations, while the EMA's pharmacovigilance frameworks shape post-market surveillance obligations for probiotic-containing products. These regulatory architectures elevate compliance costs but simultaneously protect incumbent positions for manufacturers with established quality management systems. Stakeholders must monitor evolving gut microbiome research and its potential to reclassify existing therapeutic categories or trigger new indication expansions.
Market Dynamics
FDA's accelerated approval pathways for gastrointestinal therapeutics are compressing development timelines and forcing established manufacturers to reconfigure clinical trial investments. This regulatory velocity is redrawing competitive entry barriers across prescription and over-the-counter segments.
Growth Catalysts
- Specialized IBD Center Expansion:United States healthcare systems are deploying dedicated inflammatory bowel disease facilities that standardize biologic and probiotic prescribing protocols.
- EMA Pharmacovigilance Frameworks:Post-market surveillance obligations for live microbial products are elevating quality benchmarks that favor manufacturers with established pharmacovigilance infrastructure.
- Direct-to-Consumer Probiotic Channels:Pharmacy and e-commerce platforms are bypassing traditional physician gatekeeping for functional gastrointestinal disorder management.
Market Restraints
- Enzyme Replacement Input Concentration:Supply of porcine-derived pancreatic enzymes concentrates among contracted agricultural processors, exposing malabsorption therapy pricing to livestock commodity cycles.
- Biologics Manufacturing Capacity Scarcity:Contract development and manufacturing organizations for monoclonal antibody production face 18-month queue times that throttle inflammatory bowel disease therapy launches.
- Bioequivalence Testing Burden:FDA's stringent requirements for generic loperamide formulations impose dissolution profile studies that add 12-18 months to abbreviated new drug application timelines.
Strategic Opportunities
- Microbiome Diagnostic Convergence:Stool metagenomic profiling is creating indication expansion pathways for existing live biotherapeutic products into irritable bowel syndrome subtypes.
- Hospital Formulary Deepening:European purchasing consortiums are consolidating gastrointestinal therapeutic procurement, rewarding suppliers with integrated rehydration and nutritional support portfolios.
- Telehealth Protocol Integration:Remote patient monitoring platforms are embedding chronic diarrhea management algorithms that automate prescription renewal for stable functional disorder patients.
Industry Challenges
- Gastroenterologist Workforce Compression:Fellowship program output has flatlined against chronic functional disorder diagnosis growth, stretching specialist consultation capacity.
- Cold Chain Integrity Requirements:Live microbial culture stability demands are forcing distribution network reconfiguration with temperature-controlled logistics investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Infectious Diarrhea Treatment Market |
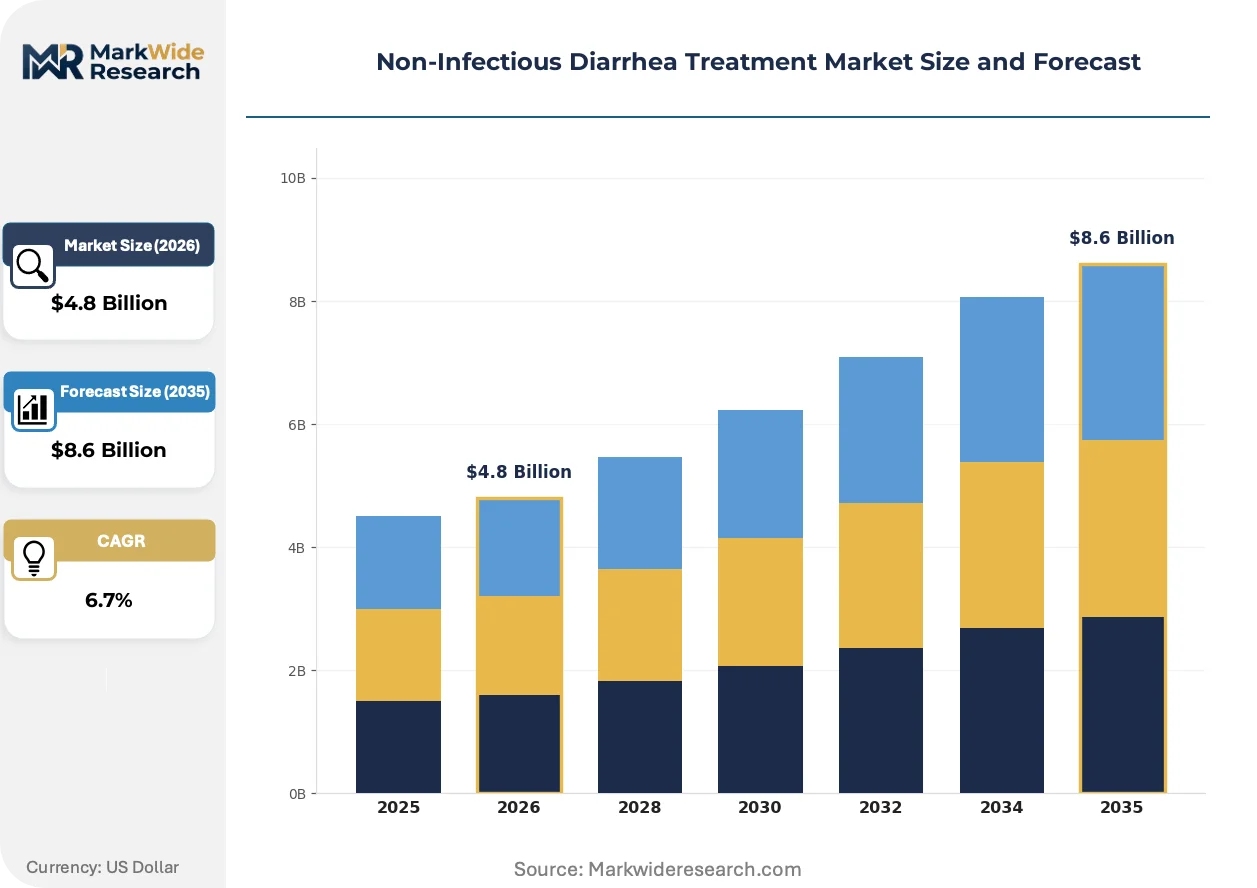
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Rehydration Solutions, Antidiarrheal Medications, Probiotics, Gastrointestinal Enzymes Therapy Area: Inflammatory Bowel Disease, Irritable Bowel Syndrome, Malabsorption Syndromes, Functional Gastrointestinal Disorders Delivery Mode: Oral, Injectable, Enteral, Rectal End User: Hospitals, Outpatient Clinics, Home Healthcare, Pharmacies |
| Companies Covered | Bausch Health Companies Inc., Procter & Gamble, Pfizer Inc., Johnson & Johnson, Sanofi, GlaxoSmithKline, Novartis, Perrigo, Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Infectious Diarrhea Treatment Market Evolving Landscape
Live biotherapeutic products are migrating from dietary supplement positioning toward drug-grade manufacturing standards, forcing capital reallocation across fermentation capacity and quality systems. This shift is compressing the historical separation between nutraceutical and pharmaceutical supply chains.
Targeted microbiome modulation using defined consortia of commensal bacteria is displacing traditional broad-spectrum probiotic formulations in investigator-initiated trials. Academic medical centers in Germany and the Netherlands are adopting these precision cocktails for recurrent Clostridioides difficile prevention protocols. The structural consequence is a capability gap between fermentation-scale manufacturers and clinical-grade good manufacturing practice requirements.
EMA's revised guidance on fecal microbiota transplantation classification is redefining regulatory boundaries between tissue-based therapies and regulated biologics. Manufacturers of standardized microbial preparations must now submit marketing authorization applications previously handled through hospital exemption pathways. Small and mid-cap developers in Denmark and Switzerland are responding by partnering with established plasma fractionators to access existing quality management infrastructure.
Patients with functional gastrointestinal disorders are consolidating purchasing decisions through subscription-based pharmacy services that bundle antidiarrheal, rehydration, and nutritional support products. United States direct-to-consumer platforms are capturing prescription renewal flows previously managed through gastroenterology clinic dispensing. This channel migration is most visible among commercially insured populations in metropolitan markets where same-day delivery logistics have achieved critical density.
Non-Infectious Diarrhea Treatment Market Segmentation
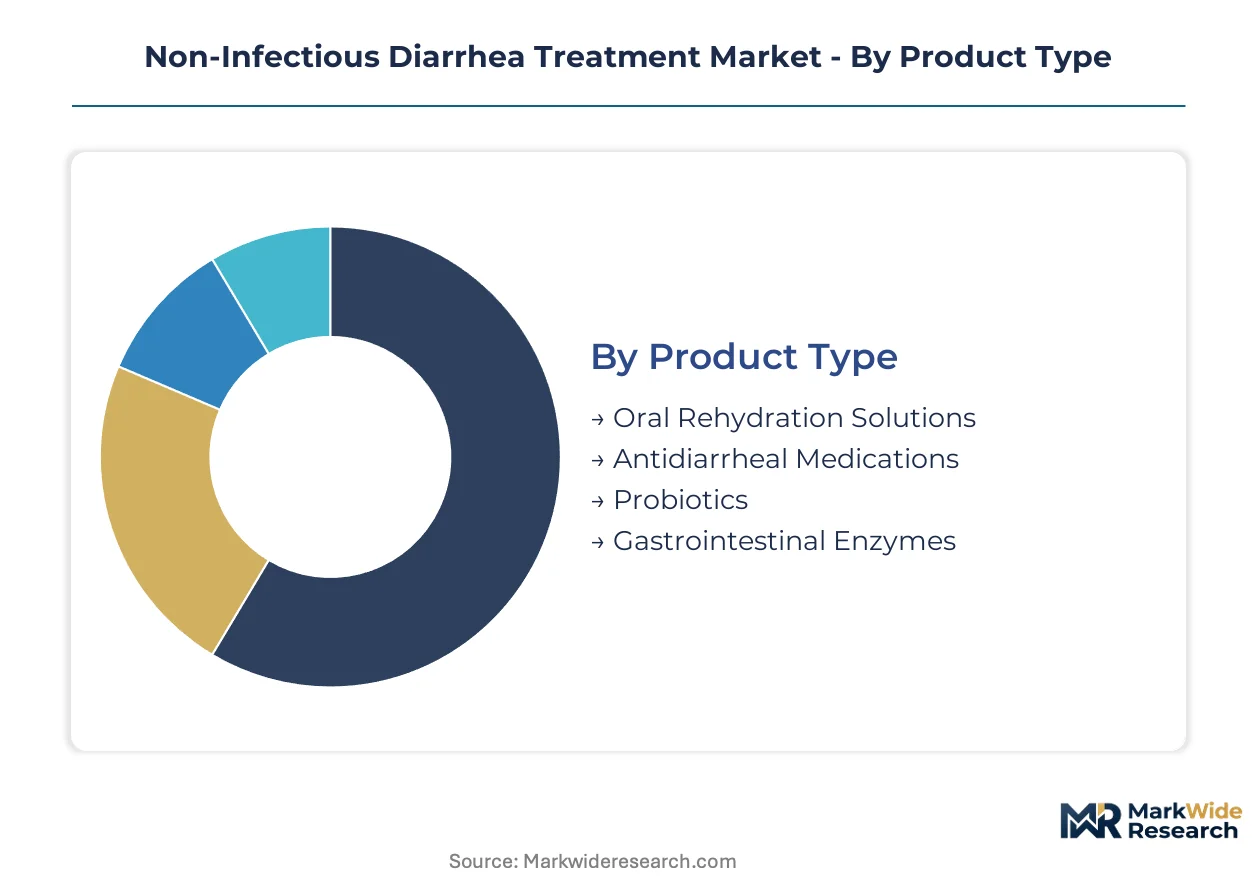
Segmentation in non-infectious diarrhea treatment reveals distinct margin architectures across product categories, with premium capture varying sharply by clinical setting and reimbursement pathway. Understanding these fault lines enables targeted portfolio positioning against evolving prescribing behaviors.
Product Type:
Margin pools concentrate in formulations requiring specialized manufacturing infrastructure or live culture handling, separating commodity electrolyte products from premium-positioned biotherapeutics.
- Oral Rehydration Solutions:Electrolyte-balancing formulations containing sodium, potassium, and glucose in WHO-recommended ratios. Demand concentrates in pediatric hospital admissions and tropical medicine protocols across India and Brazil, where dehydration-related hospitalizations drive volume procurement contracts with national health systems.
- Probiotics:Live microbial cultures including Lactobacillus and Bifidobacterium strains formulated for intestinal homeostasis restoration. Direct-to-consumer channels in the United States and Germany are absorbing share fastest as functional gastrointestinal disorder diagnoses multiply and pharmacy subscription services bypass traditional physician gatekeeping.
- Antidiarrheal Medications:Opioid-receptor agonists like loperamide and diphenoxylate that reduce intestinal motility.
- Gastrointestinal Enzymes:Porcine-derived pancreatic enzyme replacements for malabsorption management.
Oral rehydration solutions hold installed capacity. Probiotics are rotating up the share rankings.
Therapy Area:
Application intensity varies by chronicity and diagnostic clarity, with recurring conditions supporting sustained prescription volumes against acute episodic presentations.
- Inflammatory Bowel Disease:Chronic autoimmune conditions including Crohn's disease and ulcerative colitis requiring biologic and immunomodulator interventions. Specialized IBD centers in the United States and United Kingdom are standardizing biologic prescribing protocols that bundle antidiarrheal adjuncts with primary therapy.
- Malabsorption Syndromes:Enzyme deficiency states including cystic fibrosis-related pancreatic insufficiency and chronic pancreatitis. European hospital formularies command premium pricing for these therapies, reflecting the complexity of nutritional support and the contracted supply base for porcine-derived enzymes.
- Irritable Bowel Syndrome:Functional disorder with diarrhea-predominant subtypes.
- Functional Gastrointestinal Disorders:Chronic symptom clusters without structural abnormalities.
Inflammatory bowel disease anchors prescription value. Malabsorption syndromes are climbing the fastest on pricing power.
Delivery Mode:
Patient adherence and acute intervention requirements shape channel selection, with self-administered oral formats dominating maintenance therapy against clinician-delivered alternatives for severe presentations.
- Oral:Tablets, capsules, solutions, and powders for gastrointestinal administration. Home healthcare adoption in Japan and Australia is expanding fastest as telehealth protocols automate prescription renewal for stable chronic conditions.
- Injectable:Parenteral biologics and anti-inflammatory agents for severe IBD exacerbations. Hospital infusion centers in Germany and France concentrate demand for these high-acuity interventions.
- Enteral:Tube-delivered formulations for patients with compromised swallowing.
- Rectal:Localized delivery for distal colonic inflammation.
Oral delivery commands volume leadership. Injectable formats are gaining share on biologic penetration.
End User:
Purchasing authority fragmentation across institutional and retail channels creates divergent margin profiles, with consolidated procurement in health systems against dispersed consumer decision-making.
- Hospitals:Inpatient and emergency departments managing acute dehydration and severe IBD flares. Purchasing consortiums in the United Kingdom and Netherlands are consolidating gastrointestinal therapeutic procurement, rewarding suppliers with integrated portfolios spanning rehydration, enzyme replacement, and nutritional support.
- Pharmacies:Retail and mail-order dispensers for maintenance prescriptions and over-the-counter products. United States direct-to-consumer platforms are capturing renewal flows previously managed through gastroenterology clinic dispensing, particularly in metropolitan markets with same-day delivery density.
- Outpatient Clinics:Gastroenterology specialist facilities for chronic disease management.
- Home Healthcare:Residential settings for long-term nutritional and enzyme support.
Hospitals retain contract leverage. Pharmacies are rotating up the share rankings on channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for gastrointestinal therapeutics are compressing development timelines across the United States, while EMA pharmacovigilance frameworks reshape European post-market obligations for live microbial products.
United States
Specialized IBD centers in metropolitan markets standardize biologic prescribing protocols that bundle antidiarrheal adjuncts with primary therapy. Medicare reimbursement adjustments for chronic care management expand telehealth protocol integration for functional gastrointestinal disorder patients. The Boston-Cambridge corridor anchors live biotherapeutic research translation from academic medical centers to commercial manufacturing.
Germany
Hospital purchasing consortiums consolidate gastrointestinal therapeutic procurement across integrated rehydration and nutritional support portfolios. EMA pharmacovigilance frameworks for probiotic-containing products elevate quality benchmarks favoring established manufacturers. The Rhine-Ruhr and Bavarian industrial clusters concentrate fermentation-scale manufacturing for clinical-grade microbial preparations.
United Kingdom
NHS England specialized commissioning frameworks for inflammatory bowel disease concentrate biologic prescribing within designated centers of excellence. NICE technology appraisals shape formulary access for enzyme replacement therapies in cystic fibrosis-related pancreatic insufficiency. The Oxford-Cambridge-London golden triangle dominates microbiome diagnostic convergence research and precision consortium development.
Japan
PMDA streamlined review pathways for gastrointestinal biologics accelerate market entry for inflammatory bowel disease therapies. METI industrial policy supports domestic fermentation capacity expansion for live microbial culture production. The Kanto region around Tokyo concentrates pharmaceutical manufacturing infrastructure and specialist gastroenterology training programs.
India
CDSCO regulatory harmonization with ICH guidelines accelerates abbreviated new drug application timelines for generic loperamide formulations. National health mission procurement contracts for oral rehydration solutions drive volume manufacturing scale in pediatric hospital supply chains. Gujarat and Maharashtra pharmaceutical clusters dominate active pharmaceutical ingredient production for antidiarrheal medications and electrolyte formulations.
Non-Infectious Diarrhea Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated biologics manufacturers commanding premium positioning against fragmented probiotic suppliers. The structure separates pharmaceutical-grade live biotherapeutic developers from dietary supplement positioned competitors. Strategic archetypes include vertically integrated biologics manufacturers, fermentation-scale probiotic specialists, and diversified consumer health portfolios. Dominant competitive moves encompass M&A activity targeting microbiome diagnostic convergence capabilities and capacity expansion into drug-grade manufacturing standards for live cultures.
Within the integrated pharmaceutical tier, Pfizer Inc. and Sanofi occupy positions reflecting established biologics manufacturing infrastructure and European hospital formulary relationships respectively. GlaxoSmithKline exemplifies the consumer health diversification archetype through pharmacy channel dominance in over-the-counter antidiarrheal segments. These anchors represent distinct competitive vectors: prescription biologics supply security, institutional procurement consolidation, and retail distribution scale.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| Procter & Gamble |
| Pfizer Inc. |
| Johnson & Johnson |
| Sanofi |
| GlaxoSmithKline |
| Novartis |
| Perrigo |
| Lupin |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for porcine-derived pancreatic enzymes lock in supply access and price visibility for European hospital formularies, insulating malabsorption therapy pricing from livestock commodity volatility while exposing contracted buyers to minimum volume commitments. This contract architecture concentrates pricing power with agricultural processors in Denmark and the Netherlands, creating asymmetric leverage that feeds through to enzyme replacement therapy costs.
Pricing Analysis
United States-Germany price spreads for live biotherapeutic products exceed those for commodity electrolyte formulations, reflecting cold chain logistics premiums and FDA drug-grade certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade probiotics from dietary supplement positioned alternatives, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from direct-to-consumer channel expansion compressing pharmacy markups. Hospital procurement managers exhibit lowest price sensitivity, while individual consumers through subscription services demonstrate highest elasticity.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled live microbial cultures have intensified following port congestion on Rotterdam-Singapore trade lanes, forcing fermentation-scale manufacturers to reconfigure distribution networks. Supply concentrates in Germany, Denmark, and Switzerland for clinical-grade probiotic manufacturing, while India and China dominate active pharmaceutical ingredient production for generic loperamide. Raw material dependencies include porcine pancreatic tissue, specialized fermentation media, and monoclonal antibody cell lines. Single-source vulnerability pervades biologics manufacturing capacity, with contract development organizations facing extended queue times. Distribution runs through hospital purchasing consortiums in Europe and direct-to-consumer platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for gastrointestinal therapeutics compress development timelines, creating high-growth disruption as live biotherapeutic products migrate from supplement to drug-grade standards. This regulatory inflection rewards manufacturers with existing quality management infrastructure.
For Market Incumbents: Consolidate fermentation capacity in the Rhine-Ruhr industrial cluster to capture EMA pharmacovigilance compliance premiums, while deepening hospital formulary relationships through integrated rehydration and nutritional support portfolios. Threat substitution from microbiome diagnostic convergence demands defensive certification investment in drug-grade good manufacturing practice standards. For New Entrants and Emerging Players: Differentiate on precision consortium formulations for irritable bowel syndrome subtypes, exploiting the capability gap between fermentation-scale manufacturers and clinical-grade requirements. White-space targets include telehealth-integrated chronic diarrhea management protocols and subscription-based pharmacy services in United States metropolitan markets. Direct-to-consumer positioning with same-day delivery logistics offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Fermentation-scale specialists with existing cold chain infrastructure represent priority acquisition targets, given biologics manufacturing capacity scarcity and live microbial culture stability demands. Long-term viability over the next decade hinges on microbiome diagnostic convergence capabilities and pharmacovigilance infrastructure ownership. Watch stool metagenomic profiling adoption rates in German and Dutch academic medical centers as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Drug-Grade Manufacturing Scale-Up | FDA compliance investments separate pharmaceutical-grade live biotherapeutics from dietary supplement competitors. |
| Microbiome Diagnostic Partnership | Stool metagenomic profiling integration creates indication expansion pathways for existing live biotherapeutic products. |
| Cold Chain Distribution Expansion | Temperature-controlled logistics investments address live microbial culture stability demands across European hospital networks. |
| Hospital Formulary Deepening | Integrated rehydration and nutritional support portfolios capture consolidated procurement from NHS England specialized commissioning frameworks. |
| Direct-to-Consumer Channel Launch | Pharmacy subscription services bypass traditional physician gatekeeping for functional gastrointestinal disorder management in United States metropolitan markets. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors anchors the qualitative findings against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up and top-down triangulation reconciles patient-level prescription data with manufacturer-reported capacity and revenue disclosures.
Sensitivity analysis across therapy area, product type, delivery mode, and end user segmentation dimensions informs the analytical framework over the projection horizon. CAGRs derive from modeled patient population growth, diagnosis rate trends, and pricing trajectory assumptions specific to live biotherapeutic products and enzyme replacement therapies.
The analysis sits within stated boundaries; outcomes outside FDA accelerated approval pathway maintenance, EMA pharmacovigilance framework stability, or sustained gastroenterology specialist supply would require recalibration. Forecasts reflect documented assumptions regarding biologics manufacturing capacity expansion and direct-to-consumer channel penetration rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market