
 Canine Dilated Cardiomyopathy Drugs Market | 2026-2036
Canine Dilated Cardiomyopathy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Dilated Cardiomyopathy Drugs Market Outlook
Aftermarket service revenue from chronic disease management protocols is reconfiguring how pharmaceutical firms capture lifetime value per patient. Zoetis Inc. leverages its specialty diagnostics division to anchor longitudinal care relationships. Boehringer Ingelheim sustains competitive positioning through integrated cardiology portfolios spanning both small and large animal segments. Merck & Co. dominates the injectable formulation channel through established veterinary distribution partnerships.
Canine dilated cardiomyopathy drugs comprise pharmacological agents designed to modulate cardiac preload, afterload, and contractility in dogs presenting with idiopathic or breed-associated myocardial dysfunction, typically administered as oral tablets with bioavailability thresholds exceeding sixty percent for systemic ACE inhibitors. These therapeutics serve to delay disease progression, reduce congestive heart failure episodes, and extend survival intervals in affected patients. The drug type dimension shows ACE inhibitors and beta blockers capturing the core chronic therapy margin pool, while positive inotropes concentrate in emergency and hospital settings with premium pricing structures. The administration route dimension reveals oral formulations sustaining the highest refill frequency and patient compliance rates, whereas intravenous delivery generates concentrated revenue per episode in critical care environments.
The FDA Center for Veterinary Medicine evaluates all new animal drug applications through the New Animal Drug Application pathway, requiring demonstration of target animal safety and effectiveness prior to market authorization. The USDA Animal and Plant Health Inspection Service oversees certain biologic products that may intersect with cardiac therapeutic protocols in research settings. Stakeholders must monitor evolving FDA guidance on biomarker endpoints for accelerated approval pathways in veterinary cardiology, as surrogate measures of cardiac function could reshape clinical trial economics and time-to-market calculations.
Market Dynamics
Veterinary cardiology practices are consolidating diagnostic and therapeutic workflows around longitudinal patient monitoring systems, compressing the interval between disease detection and pharmaceutical intervention for at-risk breeds.
Growth Catalysts
- Specialty veterinary infrastructure expansion:Academic teaching hospitals in the United States are establishing dedicated cardiac imaging suites that accelerate referral pathways for Doberman Pinschers and Great Danes.
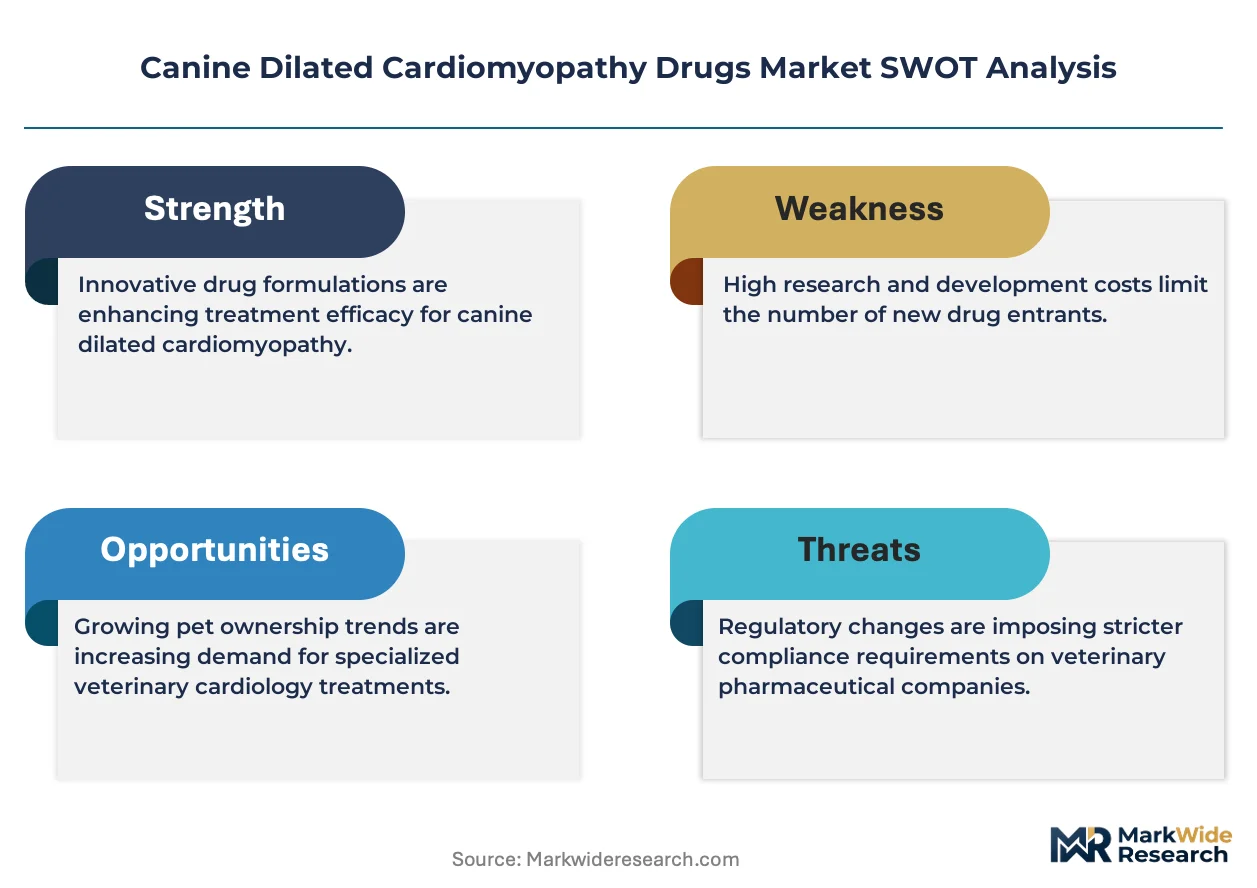
- FDA biomarker guidance evolution:The Center for Veterinary Medicine's draft framework on surrogate endpoints for accelerated approval is reducing clinical trial duration for novel cardiac therapeutics.
- Pet insurance penetration:Reimbursement coverage for chronic disease management in North America is shifting owner willingness toward sustained pharmaceutical compliance.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of veterinary-grade enalapril and pimobendan relies on contract manufacturers concentrated in India and China, exposing supply chains to export license volatility.
- Target animal safety thresholds:FDA-mandated margin of safety studies require dose escalation protocols that extend development timelines by 18-24 months.
- Generic substitution pressure:Patent-expired ACE inhibitors face price erosion from compounding pharmacies operating outside formal veterinary distribution channels.
Strategic Opportunities
- Underpenetrated European markets:France and Germany maintain lower specialty cardiology referral rates than the United States, creating whitespace for diagnostic-anchored pharmaceutical partnerships.
- Wearable cardiac monitoring convergence:Integration of Holter monitoring data with telemedicine platforms is collapsing the feedback loop between arrhythmia detection and prescription adjustment.
- USDA biologic intersection:Cell-based therapies regulated under the Animal and Plant Health Inspection Service pathway may complement small-molecule protocols in refractory cases.
Industry Challenges
- Veterinary cardiologist workforce scarcity:Residency training programs produce fewer than 50 new specialists annually across North America, constraining prescription volume growth.
- Formulation stability requirements:Pimobendan chewable tablets demand moisture-barrier packaging that complicates cold-chain logistics in humid climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Dilated Cardiomyopathy Drugs Market |
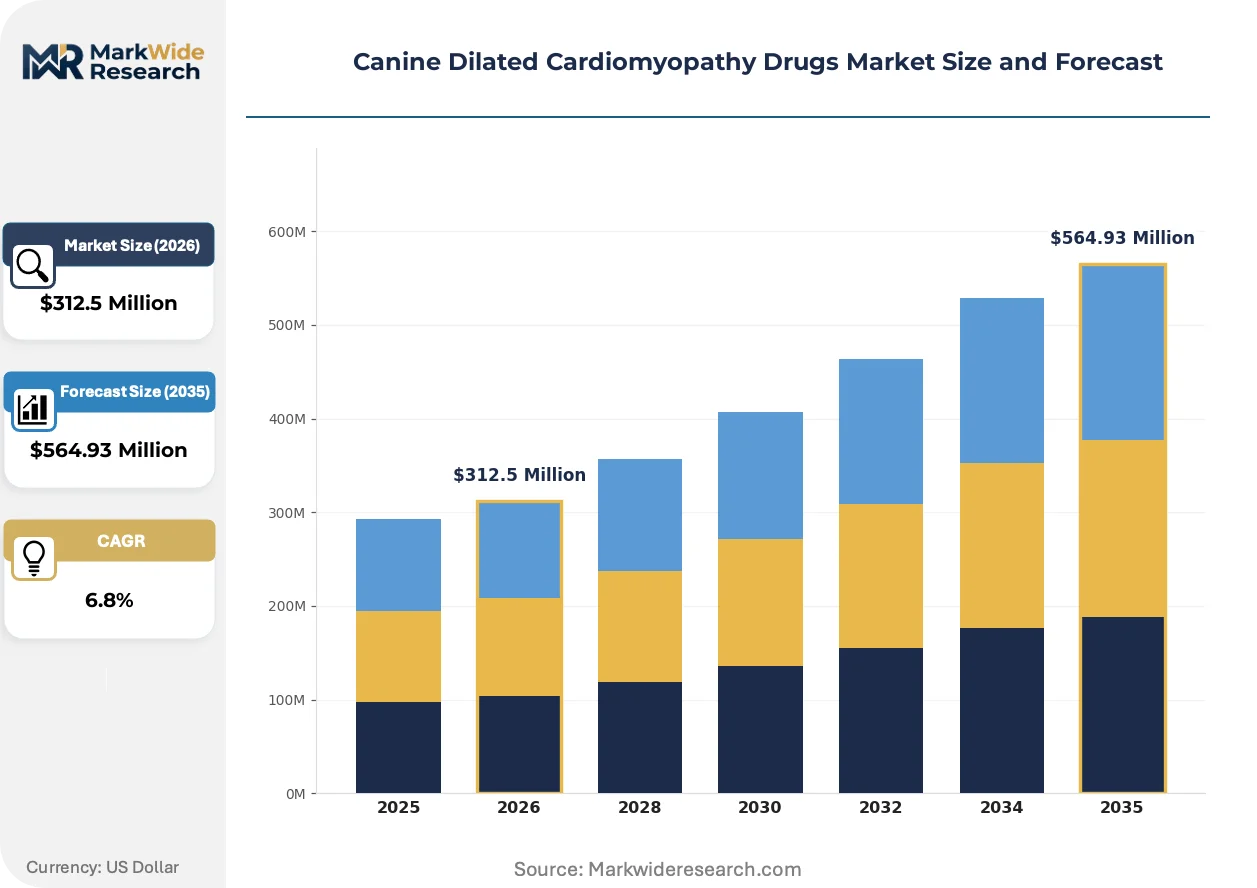
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: ACE Inhibitors, Diuretics, Beta Blockers, Positive Inotropes Administration Route: Oral, Injectable, Transdermal, Intravenous End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Research Institutions Therapeutic Area: Cardiology, Emergency Medicine, Preventative Care, Palliative Care |
| Companies Covered | Zoetis Inc., Boehringer Ingelheim, Elanco Animal Health, Merck & Co., Dechra Pharmaceuticals, Ceva Santé Animale, Virbac, Vetoquinol, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Dilated Cardiomyopathy Drugs Market Strategic Shifts
Pharmaceutical firms are embedding diagnostic services within therapeutic offerings, converting episodic prescription refills into continuous care relationships that capture lifetime patient value.
Point-of-care NT-proBNP immunoassays are collapsing the diagnostic latency between clinical suspicion and treatment initiation. Emergency and general practice veterinarians in the United States are deploying these platforms during routine wellness examinations for at-risk breeds. The compression of detection-to-treatment intervals is shifting market share toward manufacturers with integrated diagnostic-therapeutic portfolios.
The FDA Center for Veterinary Medicine's 2023 guidance on biomarker-qualified endpoints is restructuring clinical trial design for idiopathic dilated cardiomyopathy therapeutics. Sponsors may now substitute echocardiographic measures for survival endpoints in certain protocol configurations. Large animal health divisions at multinational firms are reallocating R&D budgets toward veterinary cardiology programs that leverage this regulatory pathway.
Subscription-based chronic disease management programs are displacing transactional prescription models in specialty practices. Pet owners in metropolitan United States markets are enrolling Doberman Pinschers and Boxers in monthly monitoring plans that bundle pharmaceuticals with telemedicine consultations. This behavioral shift concentrates purchasing authority within integrated veterinary health networks rather than independent retail pharmacies.
Canine Dilated Cardiomyopathy Drugs Market Segmentation
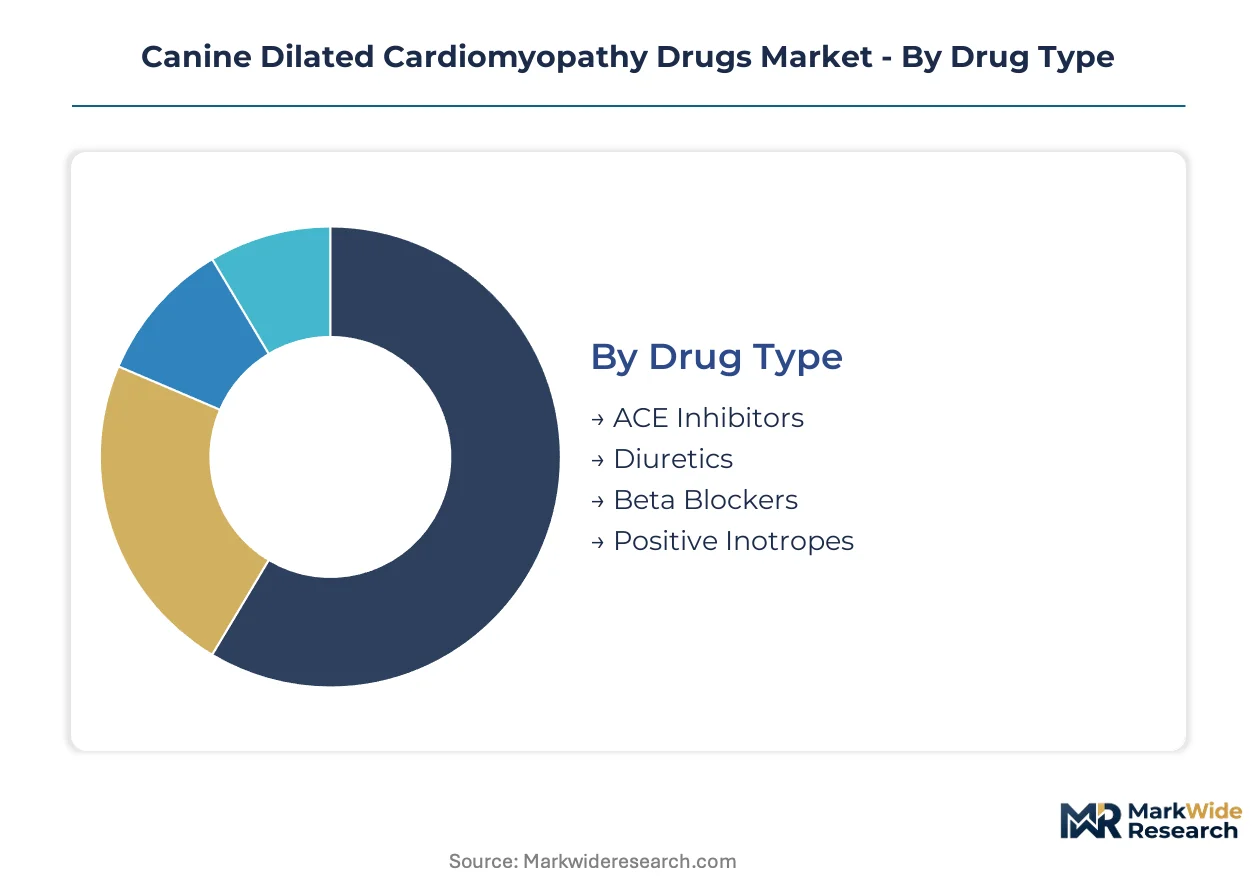
Segmentation in canine dilated cardiomyopathy therapeutics reveals how chronic disease management economics reshape pharmaceutical strategy. Each dimension exposes distinct margin profiles, compliance patterns, and service intensity requirements that determine competitive positioning.
Drug Type:
After-sales service intensity varies dramatically across drug classes, with chronic oral therapies generating recurring diagnostic touchpoints that compound lifetime value capture.
- ACE Inhibitors:These agents modulate renin-angiotensin-aldosterone system activity to reduce cardiac preload and afterload. Demand concentrates in United States specialty practices serving Doberman Pinschers and Great Danes, where breed-screening protocols trigger early intervention. The FDA Center for Veterinary Medicine mandates target animal safety studies that extend development timelines, entrenching incumbents with established enalapril and benazepril formulations.
- Beta Blockers:Carvedilol and metoprolol formulations attenuate sympathetic nervous system overactivation in dilated cardiomyopathy patients. European markets—particularly Germany and France—exhibit slower uptake due to fragmented specialty referral infrastructure, creating whitespace for diagnostic-anchored market entry strategies.
- Diuretics:Furosemide and spironolactone manage congestive heart failure fluid accumulation.
- Positive Inotropes:Pimobendan dominates emergency and hospital settings with premium per-episode economics.
By volume, ACE inhibitors lead. By growth pace, positive inotropes are ahead.
Administration Route:
Cost tier stratification separates chronic outpatient management from acute intervention economics, with oral formulations commanding refill frequency advantages.
- Oral:Tablets and chewables sustain highest patient compliance rates through at-home administration convenience. United States pet insurance penetration supports sustained refill adherence, converting monthly prescriptions into predictable revenue streams.
- Intravenous:Hospital-delivered bolus therapies generate concentrated revenue per episode in critical care environments. Academic teaching hospitals in the United States deploy these protocols for decompensated heart failure stabilization.
- Injectable:Subcutaneous depot formulations extend dosing intervals for non-compliant owners.
- Transdermal:Patch-based delivery remains experimental with limited commercial penetration.
By volume, oral administration leads. By margin per episode, intravenous delivery is ahead.
End User:
Customer type determines purchasing authority concentration, with integrated veterinary networks displacing independent retail channels.
- Veterinary Clinics:General practice veterinarians in the United States initiate first-line therapy following point-of-care NT-proBNP screening. These settings favor generic ACE inhibitors with established safety profiles.
- Animal Hospitals:Emergency and specialty referral centers manage decompensated cases requiring intravenous positive inotropes and continuous monitoring.
- Pet Owners:Direct purchasing concentrates in subscription-based chronic disease management programs.
- Research Institutions:Academic veterinary medical centers conduct clinical trials under FDA Center for Veterinary Medicine oversight.
By prescription volume, veterinary clinics lead. By revenue concentration, animal hospitals are ahead.
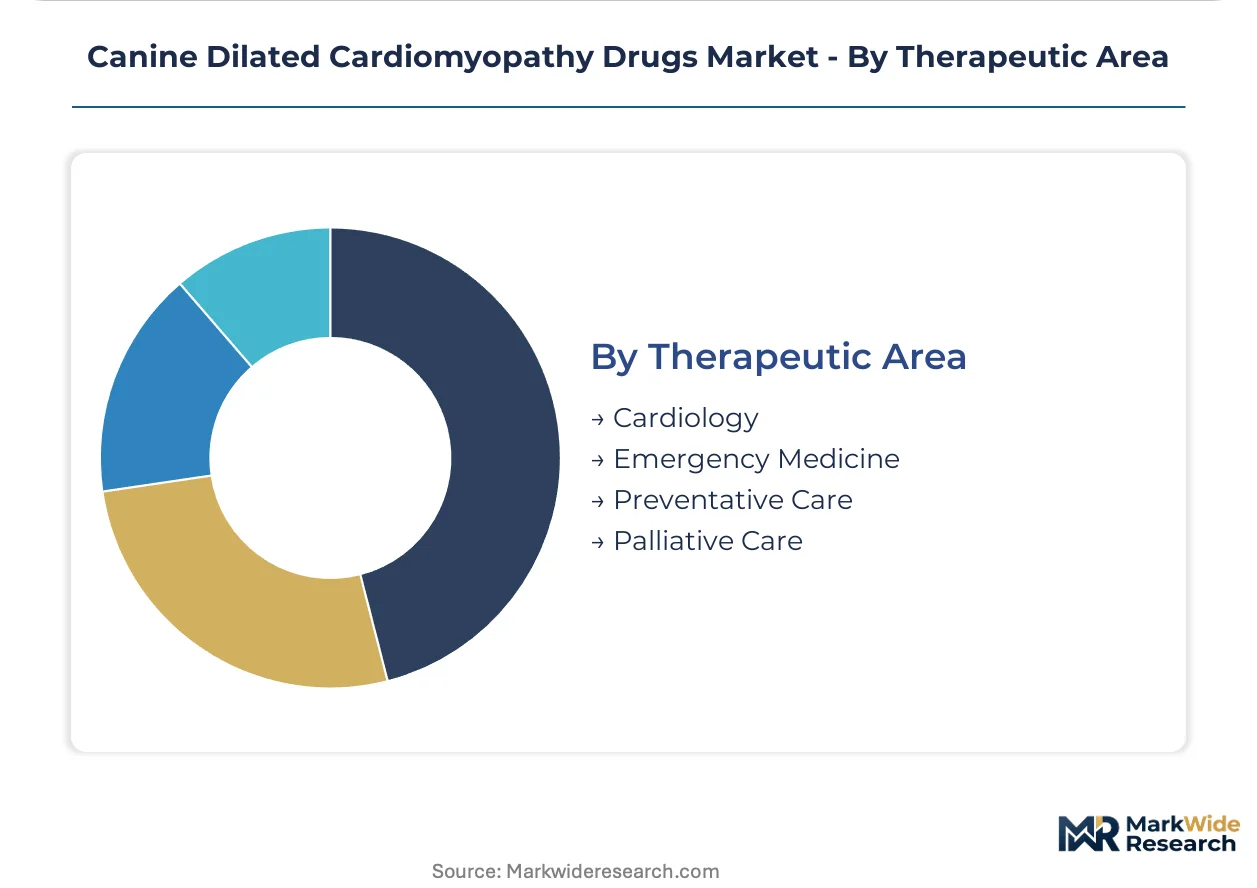
Therapeutic Area:
Application maturity separates established cardiology protocols from emerging preventative and palliative frameworks.
- Cardiology:Board-certified veterinary cardiologists manage complex cases with multimodal drug combinations. United States residency programs produce fewer than 50 new specialists annually, constraining prescription volume expansion.
- Emergency Medicine:Critical care veterinarians administer intravenous inotropes and diuretics for acute decompensation. Urban United States markets concentrate 24-hour emergency capacity.
- Preventative Care:Breed-specific screening in Doberman Pinschers and Boxers expands addressable patient pools.
- Palliative Care:End-stage disease management prioritizes quality-of-life outcomes over survival extension.
By current revenue, cardiology leads. By expansion trajectory, preventative care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Owner price sensitivity varies sharply across geographies, with United States buyers accepting premium chronic disease management costs while European markets resist out-of-pocket veterinary cardiology expenditures. This elasticity divergence shapes pharmaceutical pricing architecture and distribution channel investment priorities.
United States
Specialty veterinary infrastructure concentration in metropolitan corridors drives the highest per-patient pharmaceutical spend globally. The FDA Center for Veterinary Medicine maintains stringent New Animal Drug Application requirements that extend development timelines but reinforce incumbent positioning. Academic teaching hospitals in Philadelphia, Raleigh-Durham, and Davis anchor clinical trial networks for breed-specific DCM protocols.
Germany
Fragmented specialty referral patterns suppress cardiology prescription volumes relative to population scale. The Bundesinstitut für Arzneimittel und Medizinprodukte coordinates with EMA frameworks for veterinary medicinal products. Industrial clusters around Munich and Hanover concentrate contract manufacturing for active pharmaceutical ingredients serving European veterinary markets.
France
Lower pet insurance penetration constrains owner willingness to pursue sustained ACE inhibitor therapy for asymptomatic patients. ANSM oversight of veterinary pharmaceuticals intersects with EU-wide regulatory harmonization efforts. The Lyon-Grenoble corridor hosts veterinary diagnostic platforms accelerating point-of-care NT-proBNP deployment in general practice settings.
United Kingdom
Breed-screening protocols for Doberman Pinschers concentrate in Southeast England referral practices with established cardiologist relationships. The Veterinary Medicines Directorate enforces pharmacovigilance requirements that shape post-market surveillance obligations. The Cambridge-Norwich axis supports genomic research initiatives targeting hereditary DCM biomarker development.
Japan
Aging pet demographics elevate chronic cardiac disease prevalence among small-breed populations previously underrepresented in DCM research. PMDA veterinary drug evaluation pathways demand Japan-specific target animal safety data that extends registration timelines. Tokyo and Osaka metropolitan veterinary medical centers pioneer wearable cardiac monitoring integration with pharmaceutical compliance programs.
Canine Dilated Cardiomyopathy Drugs Market Competitive Environment
Capability concentration sits with integrated animal health conglomerates possessing diagnostic-therapeutic portfolios; scale advantage sits with pharmaceutical divisions leveraging human drug pipeline spillover into veterinary indications. The market structure exhibits tiered consolidation, with three to four entities commanding chronic therapy volume and mid-cap specialists capturing emergency inotrope niches. Dominant strategic archetypes include vertically integrated health networks, human-pharma veterinary divisions, and independent specialty pharmaceutical firms. Competitive dynamics center on diagnostic anchoring strategies and subscription-based chronic disease management program expansion.
Within the integrated animal health tier, Zoetis Inc. and Boehringer Ingelheim exemplify portfolio breadth spanning cardiology diagnostics and therapeutics. Merck & Co. occupies a distinct position anchored in injectable formulation channels and established veterinary distribution relationships. These three entities represent divergent strategic postures: diagnostic-led longitudinal capture, human-pharma pipeline extension, and distribution-centric volume aggregation.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Merck & Co. |
| Dechra Pharmaceuticals |
| Ceva Santé Animale |
| Virbac |
| Vetoquinol |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Contract manufacturers in India and China concentrating veterinary-grade enalapril and pimobendan production anchor margin distribution toward formulation and diagnostic-anchored service tiers downstream. This upstream concentration leaves downstream pharmaceutical firms vulnerable to export license volatility while concentrating pricing power with integrated players controlling cold-chain distribution networks.
Pricing Analysis
After-sales diagnostic service contracts capture the dominant lifetime value pool in this market, converting transactional prescription refills into recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates board-certified cardiologist protocols from general practice initiation and compounding pharmacy substitution. Pricing pressure stems from generic ACE inhibitor availability through non-veterinary channels. Pet owners in metropolitan United States markets exhibit lowest price sensitivity due to insurance penetration, while European general practitioners face highest resistance to sustained asymptomatic therapy costs.
Supply Chain Analysis
Active pharmaceutical ingredient synthesis for pimobendan and benazepril draws from industrial clusters in India, China, and select European contract manufacturing facilities. Key inputs include veterinary-grade chemical intermediates, moisture-barrier packaging films, and cold-chain logistics infrastructure. Single-source vulnerability concentrates around pimobendan chewable tablet production due to specialized formulation requirements. Distribution runs through established veterinary distribution partnerships serving specialty practices and academic teaching hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across European referral infrastructure and wearable monitoring integration creates niche entry points for differentiated positioning. Breed-specific screening protocol expansion generates addressable patient pools beyond incumbent capture.
For Market Incumbents: Pre-empt compounding pharmacy substitution by embedding point-of-care NT-proBNP diagnostics within chronic disease management subscriptions. Anchor longitudinal patient relationships through telemedicine platform integration that collapses detection-to-treatment intervals. Threat of generic price erosion demands backward integration into diagnostic service delivery rather than formulation commodity competition alone. For New Entrants and Emerging Players: Establish a beachhead in French and German general practice settings where specialty cardiology referral rates lag United States benchmarks. Target wearable cardiac monitoring convergence as the go-to-market angle, leveraging Holter data integration to differentiate from established pharmaceutical-only portfolios. White-space exists in subscription-based chronic disease management programs outside metropolitan United States corridors. For Investors and Strategic Acquirers: Capital is best deployed toward diagnostic-therapeutic integrated platforms with established FDA Center for Veterinary Medicine relationships over pure-play formulation assets. Long-term viability across the analysis window hinges on regulatory pathway expertise and specialty veterinary network density. Signal to monitor: FDA biomarker-qualified endpoint guidance expansion accelerating clinical trial economics for novel therapeutic entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Integration | Point-of-care NT-proBNP deployment anchors prescription capture in general practice settings. |
| Subscription Program Expansion | Monthly monitoring bundles convert episodic refills into predictable recurring revenue streams. |
| Wearable Monitoring Convergence | Holter platform integration collapses feedback loops between arrhythmia detection and dose adjustment. |
| European Market Entry | Diagnostic-anchored partnerships address fragmented specialty referral infrastructure in France and Germany. |
| Biomarker-Guided Development | FDA surrogate endpoint qualification reduces clinical trial duration for novel cardiac therapeutics. |
Study Parameters
The analysis maps ACE inhibitor, beta blocker, positive inotrope, and diuretic therapeutic classes, each validated through veterinary cardiologists, specialty practice administrators, pharmaceutical regulatory affairs leads, and pet insurance reimbursement specialists. Primary interviews with these stakeholders combined with secondary validation against FDA Center for Veterinary Medicine filings, EMA veterinary medicinal product submissions, ClinicalTrials.gov protocol registrations, and specialty veterinary practice management databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Assumptions held fixed include current FDA biomarker guidance framework, existing pet insurance penetration trajectories in North America, and specialty veterinary residency training program output rates. Variables modeled across the projection horizon encompass European regulatory harmonization progress, wearable monitoring adoption curves, and generic substitution channel expansion. Segmentation dimensions covered drug type, administration route, end user archetype, and therapeutic area. CAGRs derived from longitudinal patient value capture modeling and breed-specific disease prevalence projections.
Macroeconomic conditions sit as an overlay; deviation in veterinary care expenditure elasticity or active pharmaceutical ingredient trade policy would shift the trajectory. Forecasts reflect assumptions about regulatory pathway stability and specialty workforce expansion. Cross-checking against AVMA veterinary employment statistics and FDA new animal drug approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Liquid Filled Hard Capsules Market