
 House Dust Mite Allergy Treatment Market | 2026-2036
House Dust Mite Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
House Dust Mite Allergy Treatment Market Analysis
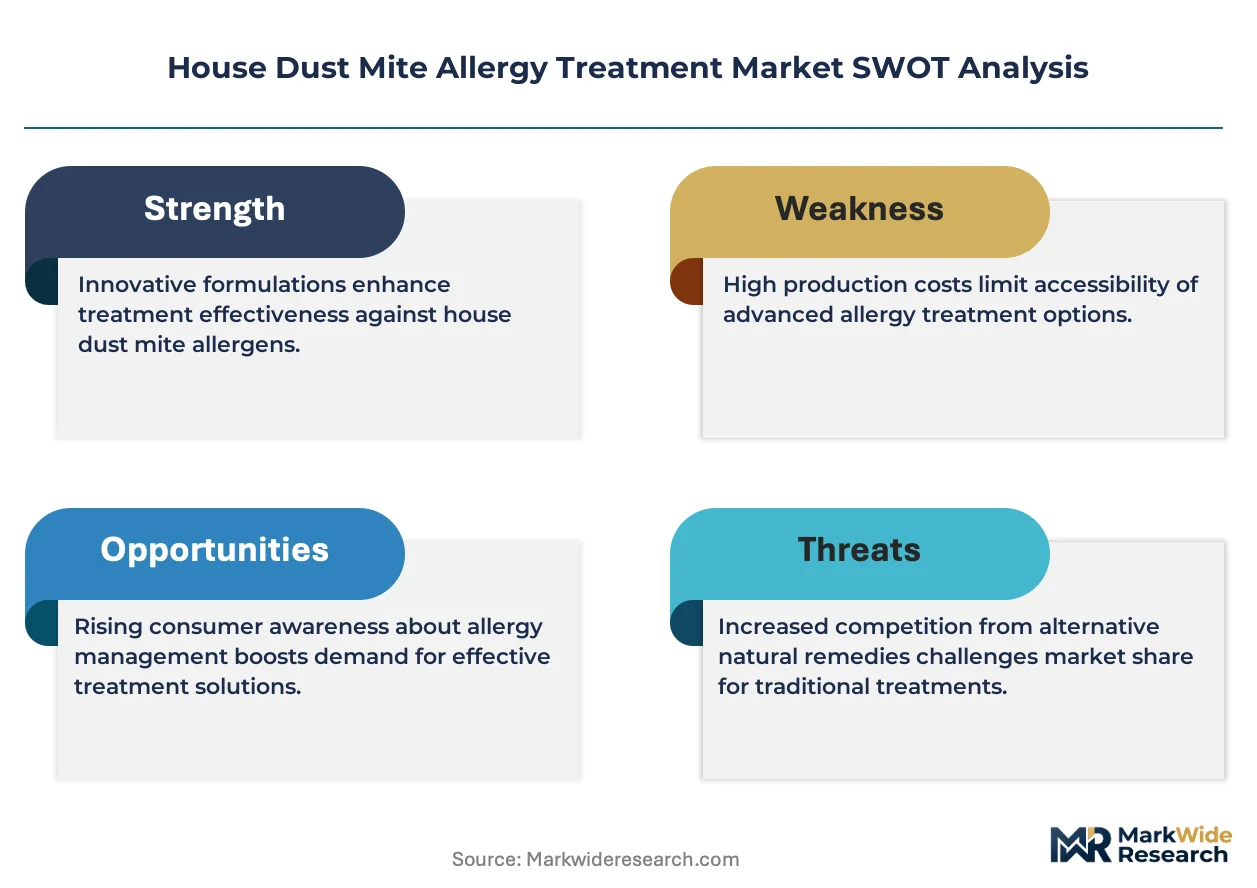
Pharmaceutical-grade allergen extract standardization is unwinding legacy manufacturing tolerances and forcing investments in potency-assured production lines. ALK-Abello A/S anchors European immunotherapy supply through vertically controlled extract cultivation. GlaxoSmithKline plc leverages its respiratory portfolio breadth to cross-sell symptomatic and disease-modifying therapies. Sanofi competes on biologic adjuvant science, differentiating its extract formulations through sustained-release delivery platforms.
House dust mite allergy treatment encompasses pharmacologic and immunologic interventions targeting hypersensitivity reactions to Dermatophagoides pteronyssinus and Dermatophagoides farinae proteins, with standardized extracts measured in biological units or major allergen content per dose to ensure batch-to-batch consistency. The primary purpose is to interrupt IgE-mediated inflammatory cascades while inducing immune tolerance through repeated controlled allergen exposure. Immunotherapy extracts command premium positioning due to manufacturing complexity and extended treatment protocols, while sublingual delivery is gaining fastest as home-administration protocols reduce clinic burden. Antihistamines remain the volume backbone through pharmacy channels, though margin pools are thinning from generic saturation.
The FDA oversees allergen extract licensing under biologics regulations, with potency standards directly shaping extract pricing and supplier qualification thresholds. EMA's MDR framework and the EU F-Gas Regulation affect device-delivery systems and cold-chain packaging for temperature-sensitive biologics. Health Canada's allergen extract review pathway creates parallel compliance obligations for North American suppliers. Stakeholders must monitor how evolving potency-standard enforcement and sublingual tablet approvals reshape competitive access and manufacturing investment priorities.
Market Dynamics
Pediatric allergology clinics are expanding sublingual immunotherapy programs as first-line intervention, reshaping patient flow from hospital-based injection protocols to home-administered tablet regimens. The FDA's evolving guidance on allergen extract potency standards is simultaneously forcing manufacturing retooling and supplier consolidation.
Growth Catalysts
- MDR Framework Compliance:The EU's Medical Device Regulation is accelerating sublingual tablet approvals by establishing clearer biocompatibility pathways for orodispersible allergen formulations.
- Pediatric First-Line Protocols:Allergy clinics in the United States are prioritizing needle-free immunotherapy for children aged 5-12, expanding addressable patient pools beyond injection-tolerant adults.
- Reimbursement Parity:Germany's statutory health insurance system now covers sublingual immunotherapy at equivalent rates to subcutaneous treatment, removing cost barriers to adoption.
Market Restraints
- Extract Potency Volatility:Biological unit standardization requires live mite cultivation cycles of 8-12 weeks, creating input timing mismatches against demand forecasting.
- Cold-Chain Concentration:Temperature-sensitive allergen extracts depend on specialized logistics providers in the Netherlands and Denmark, concentrating supply risk in Northern European distribution nodes.
- Biologic Substitution Threat:Anti-IgE monoclonal antibodies for severe allergic asthma are capturing refractory patients who would otherwise convert to immunotherapy.
Strategic Opportunities
- Underpenetrated Primary Care:France's network of general practitioners remains largely untapped for sublingual prescribing, with only 15% of eligible patients receiving allergist referrals.
- Digital Adherence Monitoring:Smartphone-connected dosing reminders paired with telemedicine follow-up are opening home-treatment compliance improvements previously requiring clinic supervision.
- Fast-Melt Formulation Convergence:Lyophilized extract technology combined with taste-masking polymers is enabling pediatric formulations that dissolve without water.
Industry Challenges
- Allergen Standardization Expertise Gap:Major allergen content quantification requires mass spectrometry capabilities that few contract manufacturing organizations possess, constraining capacity expansion.
- Legacy System Integration:Electronic health record platforms in US allergy practices lack standardized sublingual dosing modules, forcing manual workaround protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | House Dust Mite Allergy Treatment Market |
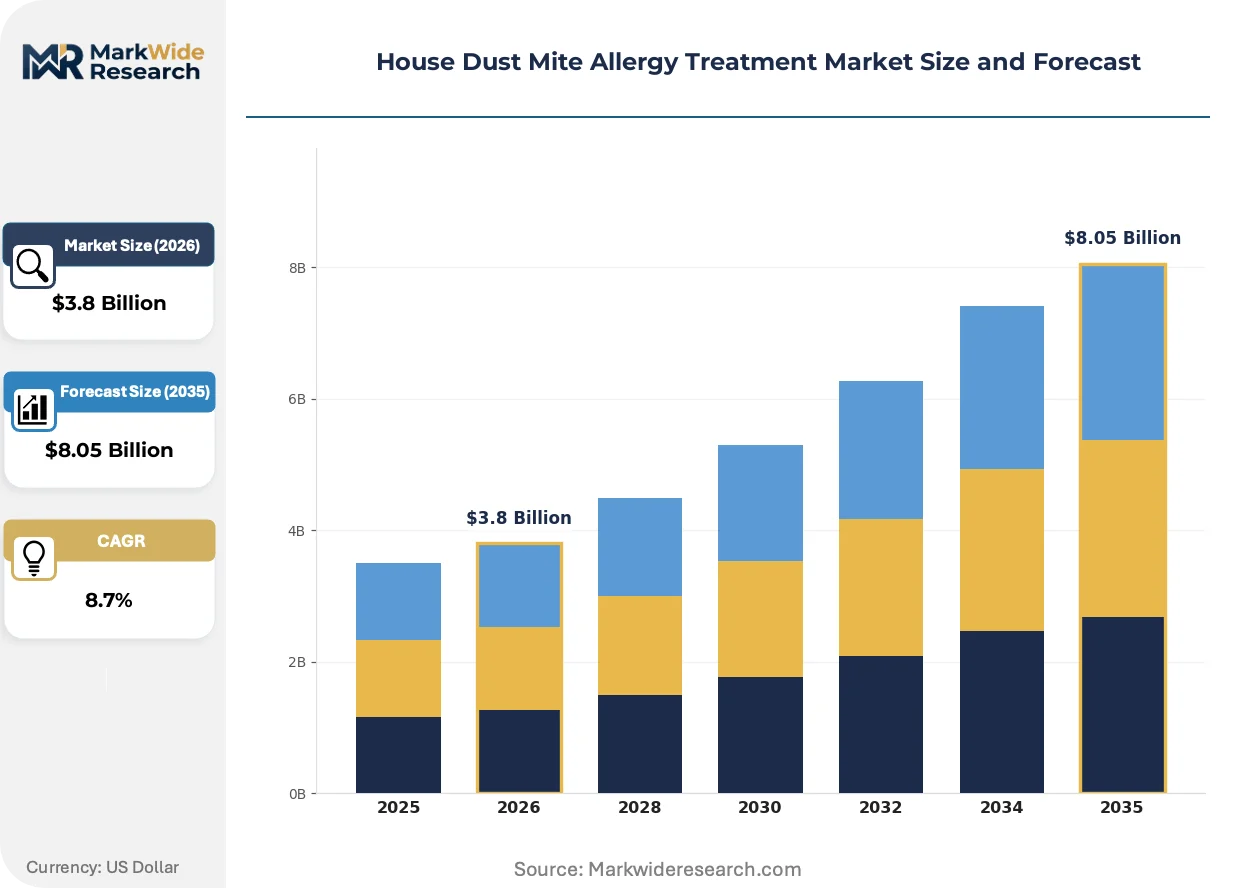
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Antihistamines, Nasal Sprays, Eye Drops Delivery Mode: Subcutaneous, Sublingual, Oral, Inhalation End User: Hospitals, Clinics, Home Care, Pharmacies Age Group: Children, Adults, Seniors, Adolescents |
| Companies Covered | GlaxoSmithKline plc, Johnson & Johnson, ALK-Abello A/S, Catalent Pharma Solutions Limited, Merz Pharma GmbH & Co. KGaA, Allergy Therapeutics PLC, Sanofi, Seqirus UK Limited, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
House Dust Mite Allergy Treatment Market Emerging Trajectories
Sublingual tablet delivery is compressing the traditional clinic-visit model while biologic potency assays and digital adherence tools are rewriting manufacturing and patient management protocols. These shifts are redistributing value capture from injection administration services toward formulation science and remote monitoring infrastructure.
Recombinant allergen technology is supplanting native extract production for standardized immunotherapy formulations. European manufacturers are adopting yeast-expression systems to produce Der p 1 and Der p 2 proteins with batch-to-batch consistency impossible in mite-cultured extracts. This shift is enabling precision dosing protocols and reducing anaphylaxis risk profiles that have constrained prescriber enthusiasm.
The FDA's updated allergen extract potency guidance is mandating transition from biological units to major allergen content labeling by 2027. Manufacturers must revalidate entire product lines using standardized ELISA or mass spectrometry methods, with sublingual tablet suppliers investing most heavily in analytical infrastructure to meet the accelerated compliance timeline.
Home-administration protocols are displacing clinic-based injection cycles as the dominant patient experience model. Pharmacy benefit managers in the United States are expanding mail-order sublingual coverage, while allergy practices are unbundling observation fees from product reimbursement. This behavioral pivot is most pronounced in suburban markets where travel time to specialty clinics previously drove treatment abandonment.
House Dust Mite Allergy Treatment Market Segmentation
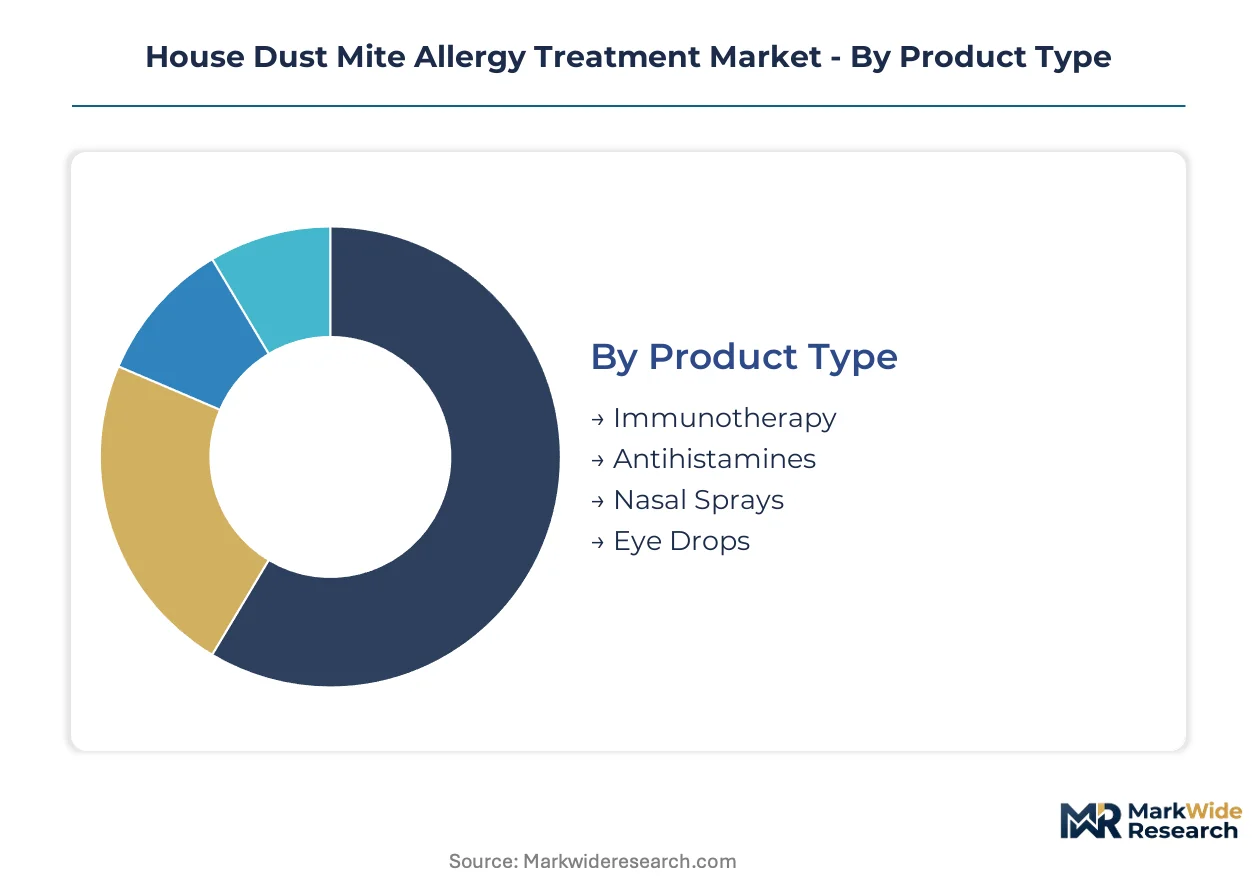
House dust mite allergy treatment segmentation reveals how substitution pressures from biologics and symptomatic therapies fragment patient flows across delivery channels. Manufacturers must align formulation investments with where prescribing authority and reimbursement gatekeeping concentrate.
Product Type:
Immunotherapy extracts face the most acute substitution pressure from anti-IgE monoclonals in severe asthma populations, while antihistamines confront generic saturation across pharmacy channels.
- Immunotherapy:Standardized allergen extracts measured in biological units or major allergen content induce immune tolerance through controlled exposure. Demand concentrates in pediatric allergology clinics expanding sublingual first-line protocols, though biologic substitution captures refractory severe cases.
- Antihistamines:Second-generation H1 receptor antagonists block histamine-mediated symptoms without sedation. Volume concentrates in United States pharmacy channels where OTC availability and generic pricing sustain high prescription counts despite thinning margins.
- Nasal Sprays:Topical corticosteroid and antihistamine formulations deliver localized nasal symptom control.
- Eye Drops:Mast cell stabilizers and dual-action antihistamine formulations address allergic conjunctivitis symptoms.
Antihistamines retain volume leadership; immunotherapy holds the steepest expansion curve as disease-modifying positioning commands premium reimbursement.
Delivery Mode:
Cost tier differentiation separates clinic-administered injection protocols from home-based tablet regimens, with reimbursement parity in Germany removing historical cost barriers to sublingual adoption.
- Subcutaneous:Extract injections administered in supervised clinical settings require 30-minute post-dose observation periods. Demand concentrates in hospital-based allergy departments where anaphylaxis risk management infrastructure justifies higher reimbursement rates.
- Sublingual:Orodispersible tablets and drops enable home administration without medical supervision. Pediatric allergology clinics in the United States prioritize this mode for children aged 5-12, expanding addressable pools beyond injection-tolerant adults.
- Oral:Swallowed tablet and capsule formulations of antihistamines and leukotriene modifiers.
- Inhalation:Dry powder and metered-dose delivery for corticosteroid and bronchodilator combinations.
Subcutaneous delivery retains volume leadership in severe patient cohorts; sublingual gains share fastest where pediatric protocols and mail-order pharmacy coverage converge.
End User:
Application concentration shifts toward home care as sublingual tablet approvals and digital adherence tools unbundle observation fees from product reimbursement.
- Home Care:Patient-administered sublingual protocols supported by smartphone-connected dosing reminders and telemedicine follow-up. United States pharmacy benefit managers are expanding mail-order coverage for these regimens.
- Clinics:Outpatient allergy practices performing diagnostic testing and initiating immunotherapy. France's general practitioner network remains largely untapped for sublingual prescribing, with only 15% of eligible patients receiving allergist referrals.
- Hospitals:Inpatient and emergency settings managing acute allergic reactions and severe asthma exacerbations.
- Pharmacies:Retail and mail-order dispensaries handling antihistamine volume and sublingual tablet distribution.
Clinics retain volume leadership in immunotherapy initiation; home care posts the steepest expansion trajectory as administration models decentralize.
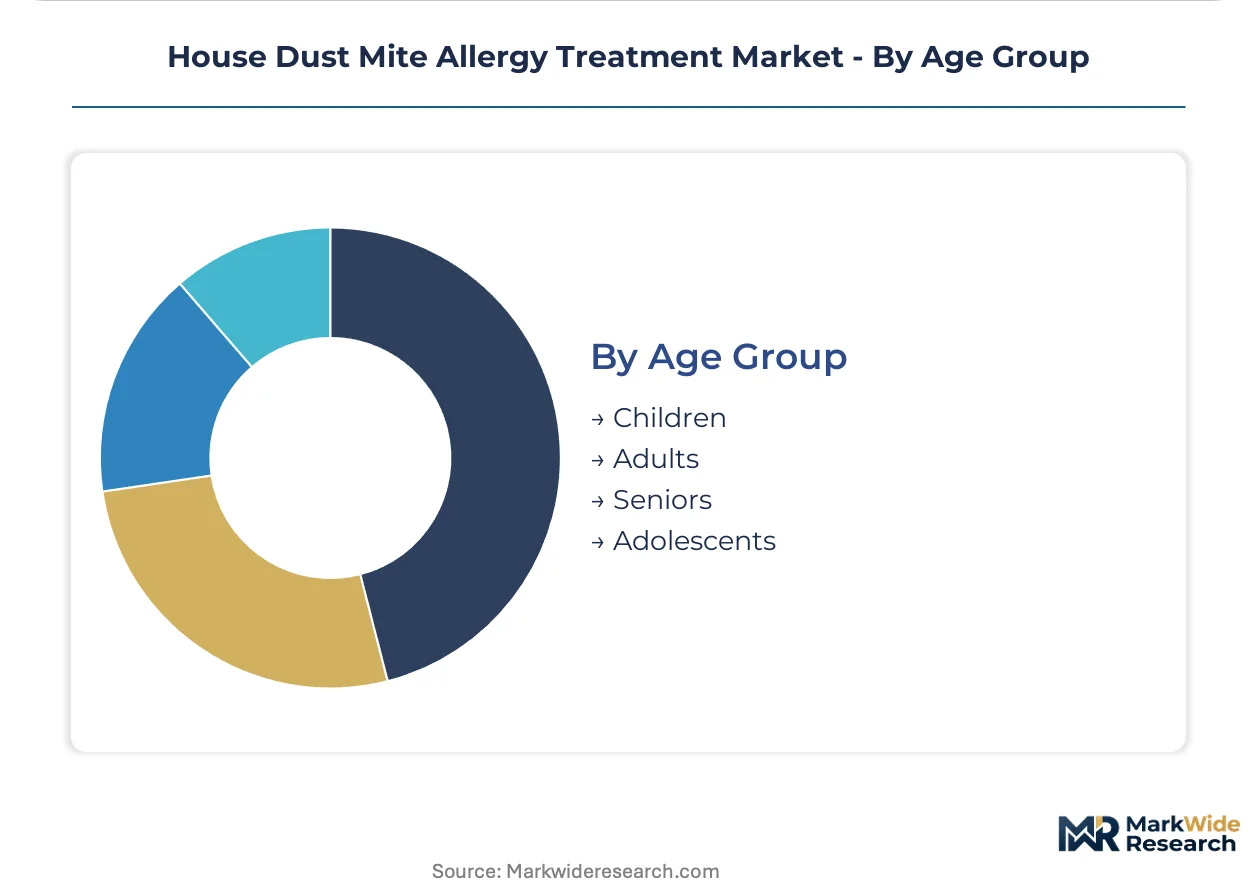
Age Group:
Customer type segmentation exposes how pediatric prescribing protocols reshape formulation requirements toward taste-masking and needle-free delivery.
- Children:Patients aged 5-12 drive fastest adoption of sublingual tablet protocols as United States allergy clinics prioritize needle-free first-line intervention. Fast-melt lyophilized formulations with taste-masking polymers enable water-free administration.
- Adults:Working-age patients balance symptom control with occupational performance demands. This cohort sustains antihistamine volume through pharmacy channels while converting to immunotherapy based on severity and lifestyle constraints.
- Adolescents:Transitional age group requiring protocol adjustments between pediatric and adult dosing.
- Seniors:Elderly populations with comorbid respiratory conditions and polypharmacy considerations.
Adults retain volume leadership across all product categories; children represent the steepest expansion curve as pediatric protocol adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extract manufacturing clusters in Denmark and the Netherlands control cold-chain distribution for temperature-sensitive allergen formulations, while diagnostic penetration rates and reimbursement policies determine treatment adoption across patient populations.
United States
Pediatric allergology clinics in suburban markets drive fastest sublingual tablet adoption as travel barriers to specialty care reshape patient flow. FDA allergen extract potency guidance mandates major allergen content labeling transitions by 2027, forcing analytical infrastructure investments. Greater Boston and Research Triangle Park concentrate biopharma manufacturing capabilities supporting recombinant allergen production.
Germany
Statutory health insurance reimbursement parity between sublingual and subcutaneous immunotherapy removes cost barriers to home-administered protocols. EMA's MDR framework establishes clearer biocompatibility pathways for orodispersible allergen formulations. Bavaria's pharmaceutical manufacturing corridor anchors European extract standardization expertise.
France
General practitioner networks remain underpenetrated for sublingual prescribing, with allergist referral rates at 15% of eligible patients. ANSM oversees allergen extract licensing parallel to EMA centralized procedures. Île-de-France concentrates hospital-based allergy departments managing severe refractory cases.
United Kingdom
NICE cost-effectiveness assessments shape immunotherapy access through specialized commissioning frameworks. MHRA post-Brexit regulatory autonomy creates parallel compliance tracks for extract suppliers. London and Southeast England concentrate pediatric allergy services expanding needle-free first-line protocols.
Japan
PMDA allergen extract approvals emphasize batch-to-batch consistency metrics for mite-cultured formulations. METI industrial policy supports precision fermentation investments in recombinant allergen production. Kanto region pharmaceutical clusters advance yeast-expression systems for Der p 1 and Der p 2 proteins.
House Dust Mite Allergy Treatment Market Vendor Landscape
Concentration sits with vertically integrated extract manufacturers and respiratory-focused pharmaceutical conglomerates. The supplier base stratifies across three tiers: mite-cultivation specialists controlling upstream biological supply, diversified pharma groups cross-selling symptomatic and disease-modifying therapies, and contract manufacturers filling analytical standardization gaps. Dominant competitive moves include recombinant technology licensing and sublingual formulation portfolio expansion.
Within the vertically integrated tier, ALK-Abello A/S exemplifies captive mite cultivation and extract standardization capabilities. GlaxoSmithKline plc represents diversified respiratory portfolio leverage across symptomatic and immunologic interventions. Sanofi occupies a position in biologic adjuvant science and sustained-release delivery platforms.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Johnson & Johnson |
| ALK-Abello A/S |
| Catalent Pharma Solutions Limited |
| Merz Pharma GmbH & Co. KGaA |
| Allergy Therapeutics PLC |
| Sanofi |
| Seqirus UK Limited |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between extract manufacturers and pediatric allergology networks lock in multi-year supply commitments while stabilizing unit economics against biological unit volatility. These arrangements concentrate purchasing power among vertically integrated suppliers in Denmark and the Netherlands, insulating contracted buyers from spot-market fluctuations in mite-cultured raw material availability.
Pricing Analysis
FDA potency standardization mandates dictate the pricing tier structure across allergen extract portfolios, separating major allergen content-labeled products from legacy biological unit formulations. Price differentiation hinges on certification grade and analytical infrastructure investment, with mass spectrometry-capable suppliers commanding premiums over ELISA-standard competitors. Cost compression in sublingual tablet segments is intensifying because generic antihistamine substitution erodes symptomatic therapy margins. Pharmacy benefit managers exhibit highest price sensitivity, while hospital-based allergy departments tolerate premium positioning for anaphylaxis risk-managed injection protocols.
Supply Chain Analysis
Strategic stockpiling of live mite cultures dominates inventory strategy, given 8-12 week cultivation cycles that preclude just-in-time responsiveness to demand surges. Geographic supply concentration centers on Denmark, the Netherlands, and Germany, where cold-chain infrastructure supports temperature-sensitive extract distribution. Raw material dependencies encompass Dermatophagoides pteronyssinus and Dermatophagoides farinae cultivation media, lyophilization excipients, and taste-masking polymers for pediatric formulations. Single-source vulnerability in Northern European distribution nodes poses structural risk. Distribution runs through specialized logistics providers serving hospital pharmacies and mail-order channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometry capabilities for major allergen quantification represent the binding constraint on extract manufacturing expansion, with fewer than a dozen contract organizations possessing validated analytical infrastructure. This capability gap concentrates margin capture among incumbent suppliers while raising barriers for capacity scaling.
For Market Incumbents: Fortify analytical infrastructure investments to meet FDA major allergen content labeling transitions, while securing captive mite cultivation capacity in Denmark and the Netherlands against biologic substitution threats from anti-IgE monoclonals. Prioritize backward integration into recombinant allergen production via yeast-expression systems to reduce biological unit volatility exposure. For New Entrants and Emerging Players: Differentiate on digital adherence monitoring platforms paired with sublingual tablet formulations, targeting France's underpenetrated general practitioner network where allergist referral rates sit at fifteen percent of eligible patients. Pursue white-label contract manufacturing partnerships with established extract suppliers to bypass mass spectrometry capability gaps while building proprietary formulation expertise. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated extract manufacturers with validated potency-assay capabilities and established pediatric clinic relationships, given five-to-ten year immunotherapy protocol durations that sustain recurring revenue visibility. The signal to watch is FDA enforcement discretion on biological unit phase-out timelines, which would accelerate consolidation among non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Allergen Production Scale-Up | Yeast-expression systems for Der p 1 and Der p 2 proteins reduce batch-to-batch variability and anaphylaxis risk profiles. |
| Sublingual Tablet Regulatory Approval Pathway | EMA MDR framework biocompatibility clearances accelerate orodispersible formulation market access across European pediatric networks. |
| Digital Adherence Platform Integration | Smartphone-connected dosing reminders paired with telemedicine follow-up improve home-treatment compliance without clinic supervision costs. |
| Mass Spectrometry Analytical Infrastructure Investment | FDA major allergen content labeling mandates require ELISA or mass spectrometry validation for continued extract licensing. |
| Pediatric First-Line Protocol Expansion | United States allergy clinics prioritize needle-free immunotherapy for children aged 5-12, expanding addressable patient pools beyond injection-tolerant adults. |
Methodological Framework
A spread of perspectives from allergology clinic directors, pharmaceutical regulatory affairs leads, pharmacy benefit managers, and extract manufacturing quality heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA allergen extract guidance documents, EMA centralized procedure filings, ClinicalTrials.gov immunotherapy protocol registrations, and statutory health insurance reimbursement databases. Bottom-up patient flow modeling and top-down pharmaceutical market sizing were triangulated to converge on segment-level estimates.
Segmentation dimensions modeled encompass product type, delivery mode, end user, and age group across the projection horizon, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from patient volume projections weighted by treatment protocol completion rates and reimbursement parity assumptions. Forecast inputs incorporated sublingual tablet approval trajectories, biologic substitution elasticities in severe asthma populations, and potency standardization compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement parity for home-administered immunotherapy or accelerated FDA enforcement discretion would require recalibration. Forecasts reflect assumptions regarding pediatric protocol adoption curves and cold-chain distribution reliability. Revision becomes warranted when anti-IgE monoclonal capture rates in refractory patient populations cross thresholds that materially compress immunotherapy conversion funnels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Global Hyperhidrosis Treatment Market