
 Allergy Treatment Market | 2026-2036
Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy Treatment Market Analysis
Buyer concentration among hospital procurement groups is pivoting toward consolidated purchasing agreements for biologic allergy therapies. GlaxoSmithKline leverages its respiratory franchise to anchor seasonal allergy portfolios across European formulary networks. Sanofi competes through differentiated dupilumab positioning in severe allergic asthma segments. AbbVie Inc. sustains R&D intensity in next-generation antihistamine candidates targeting refractory patient pools.
Allergy treatment encompasses pharmacological and immunological interventions designed to modulate hypersensitivity responses, including small-molecule antagonists of histamine H1 receptors and allergen-specific immunotherapy extracts standardized by protein content or biological units. Its primary commercial purpose centers on symptom suppression, disease modification, and prophylaxis against IgE-mediated pathologies across outpatient and inpatient settings. Immunotherapy segments command premium positioning due to curative potential and multi-year treatment protocols, while intranasal delivery modes lead volume share through patient convenience and over-the-counter accessibility. Oral antihistamines remain the mature revenue base, though sublingual immunotherapy registers the fastest clinical adoption curve among allergist practices.
The FDA maintains stringent IND requirements for novel allergy biologics, while the EMA's MDR framework reshapes post-market surveillance obligations for immunotherapy device-drug combinations. Japan's PMDA imposes localized efficacy bridging studies that extend market access timelines for imported allergy therapies. Stakeholders must monitor evolving pharmacovigilance mandates and reimbursement negotiations for curative immunotherapy regimens against chronic symptomatic management paradigms.
Market Dynamics
Consolidated purchasing agreements among hospital procurement groups are compressing margins for biologic allergy therapies while amplifying volume commitments to preferred suppliers.
Growth Catalysts
- EMA MDR Framework:Post-market surveillance obligations for immunotherapy device-drug combinations are driving quality upgrades that differentiate compliant suppliers from fragmented competitors.
- Pediatric allergology expansion:Hospital systems in the United States and Germany are scaling dedicated immunotherapy protocols, creating dedicated service lines with multi-year patient retention.
- Sublingual immunotherapy:Allergist practices are accelerating clinical adoption of oral delivery formats that reduce injection burden and expand addressable patient pools beyond traditional shot clinics.
Market Restraints
- Specialist concentration:Densest care networks in the United States, Germany, and Japan create access bottlenecks that limit therapy penetration in secondary and tertiary markets.
- FDA pharmacovigilance tightening:Heightened IND requirements for novel allergy biologics extend development timelines and elevate clinical trial costs for pipeline candidates.
- Biologic cold chain complexity:Temperature-sensitive monoclonal antibodies require specialized logistics infrastructure that fragments distribution economics outside major metropolitan hubs.
Strategic Opportunities
- Refractory patient pools:Next-generation antihistamine candidates targeting non-responders to first-line therapy command premium positioning in severe allergic asthma segments.
- Japan PMDA bridging studies:Localized efficacy requirements, while extending timelines, create first-mover advantages for sponsors investing in domestic clinical infrastructure.
- Over-the-counter intranasal migration:Patient convenience preferences are pulling prescription-grade delivery technologies into retail pharmacy channels with direct-to-consumer marketing potential.
Industry Challenges
- Allergist workforce scarcity:Fellowship-trained specialists concentrate in academic medical centers, constraining protocol expansion into community hospital settings.
- Multi-year immunotherapy adherence:Curative treatment protocols face dropout rates that compress lifetime value calculations and strain reimbursement justification.
- Legacy extract standardization:Protein content and biological unit variability across allergen-specific immunotherapy batches complicates outcome consistency in real-world settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy Treatment Market |
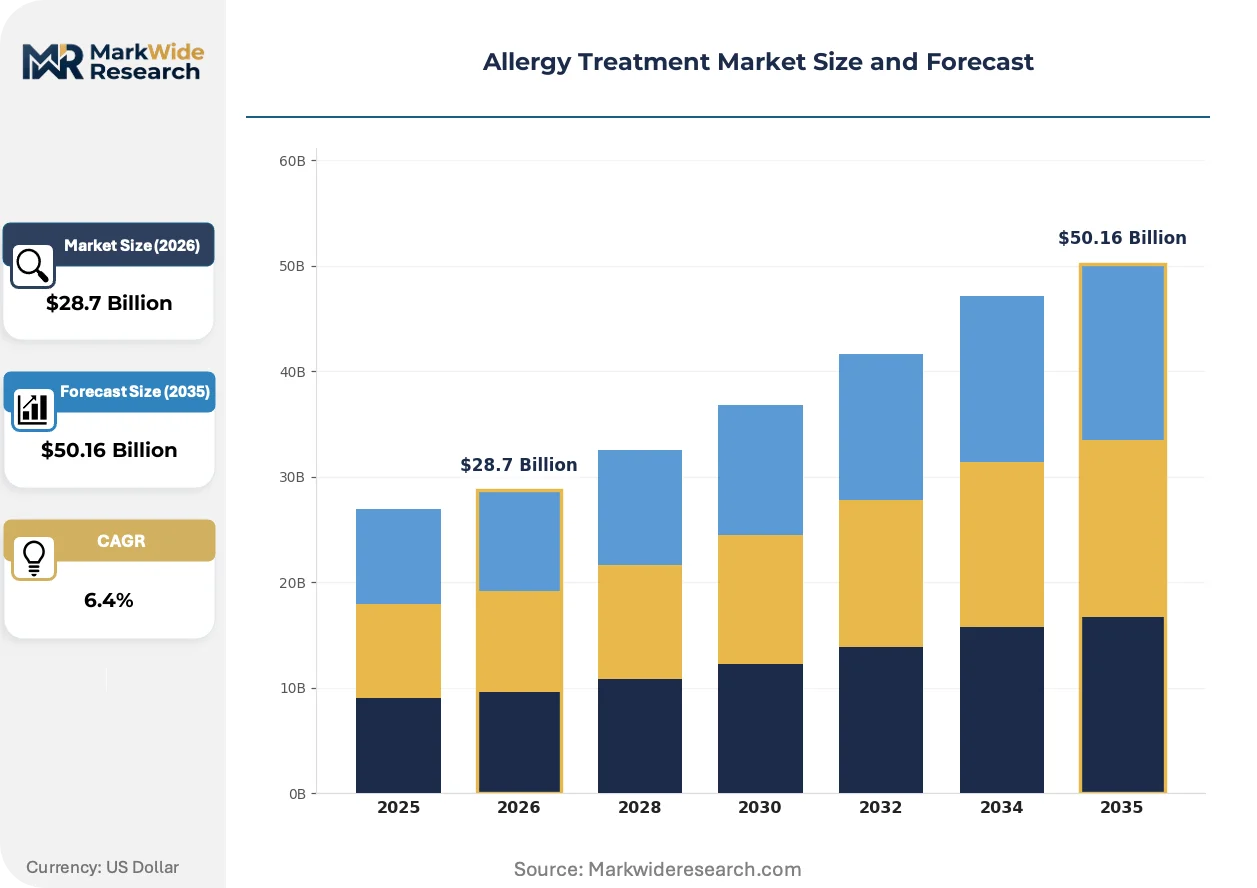
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Nasal Corticosteroids, Leukotriene Receptor Antagonists, Immunotherapy Delivery Mode: Oral, Intranasal, Subcutaneous, Sublingual End User: Hospitals, Clinics, Homecare, Retail Pharmacies Application: Seasonal Allergies, Perennial Allergies, Allergic Rhinitis, Allergic Asthma |
| Companies Covered | GlaxoSmithKline, AbbVie Inc., Pfizer Inc., Allergy Therapeutics PLC, ALK-Abello, Johnson & Johnson, Novartis AG, F. Hoffmann-La Roche Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy Treatment Market Emerging Trajectories
Digitization of patient monitoring and delivery device connectivity are converging to reshape how adherence is tracked and reimbursed across immunotherapy protocols.
Biologic-digital combination products are unifying injectable therapies with embedded sensors that capture dosing timestamps and injection site reactions. Severe asthma clinics in the United States are piloting these systems to demonstrate outcomes data to payers. This convergence is unifying previously separate pharmaceutical and medical device revenue streams into integrated contracting arrangements.
REACH authorization requirements for novel excipients in allergen extracts are forcing reformulation investments across European immunotherapy manufacturers. The ECHA evaluation timeline adds months to product lifecycle management. Sublingual tablet producers are responding by accelerating biodegradable polymer substitutions ahead of sunset dates.
Hospital procurement groups are consolidating biologic allergy therapy purchasing into multi-hospital system agreements that displace individual hospital pharmacy negotiations. Specialty distributors serving academic medical centers are losing volume to direct manufacturer contracts. This concentration is most visible in Germany, where university hospital networks have centralized formulary decisions for dupilumab-class therapies.
Allergy Treatment Market Segmentation
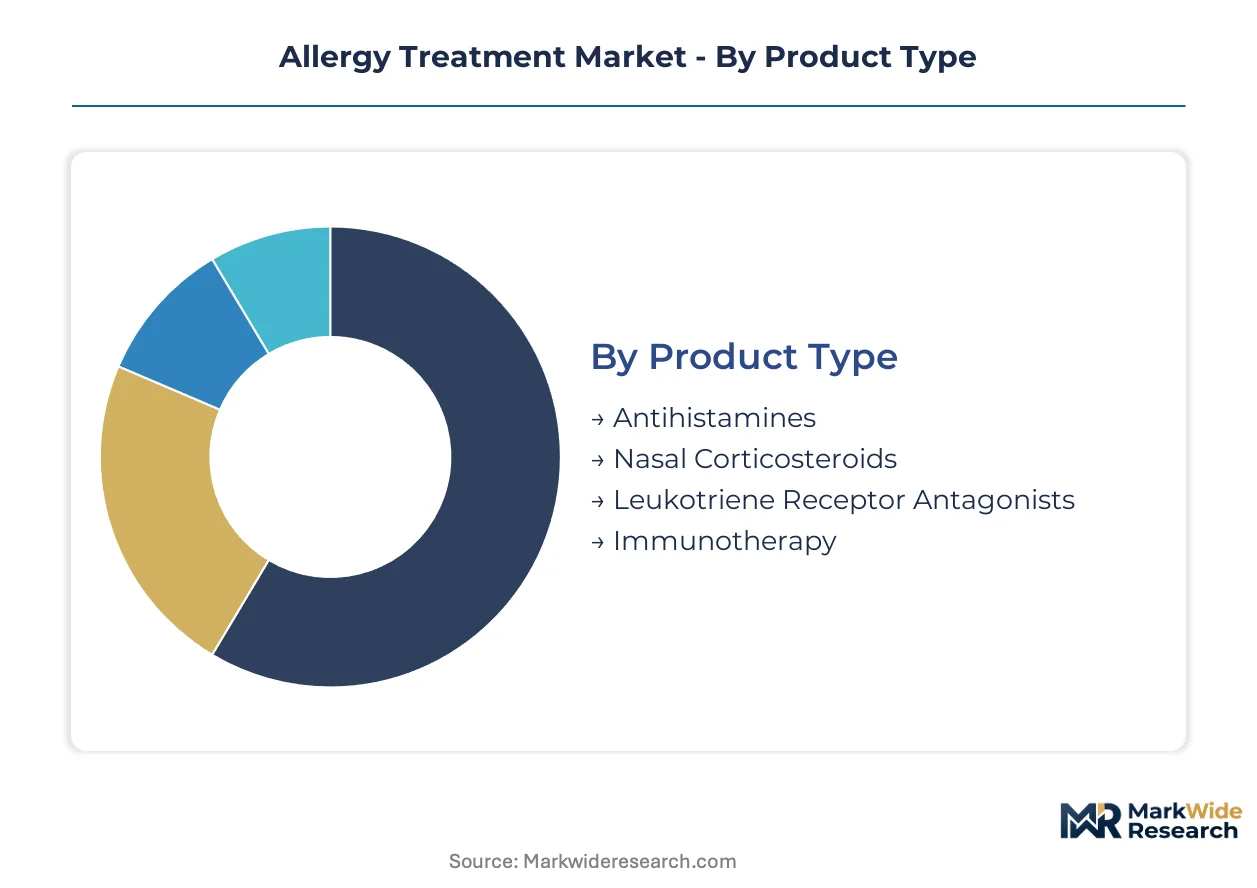
Segmentation in allergy treatment reveals divergent purchasing logics across clinical versus retail channels, with immunotherapy protocols demanding multi-year commitment structures that reshape lifetime value calculations for manufacturers.
Product Type:
Buyers differentiate primarily by curative intent versus symptomatic suppression, with hospital procurement groups weighting disease-modification outcomes against pharmacy-driven convenience metrics.
- Antihistamines:Small-molecule H1 receptor antagonists available in first-generation sedating and second-generation non-sedating formulations. United States retail pharmacies command the dominant volume share, driven by over-the-counter accessibility and seasonal purchase patterns that spike during pollen cycles.
- Nasal Corticosteroids:Intranasal glucocorticoid formulations delivering localized anti-inflammatory action with minimal systemic absorption. German hospital outpatient clinics favor these for moderate persistent allergic rhinitis, constrained by formulary tier placement that limits biologic escalation.
- Leukotriene Receptor Antagonists:Oral montelukast-class therapies targeting inflammatory mediators in allergic asthma pathways. Pediatric allergology departments in Japan prescribe these as maintenance therapy, though PMDA black-box warnings on neuropsychiatric effects have tightened prescribing protocols.
- Immunotherapy:Allergen-specific extracts standardized by protein content or biological units, administered via subcutaneous injection or sublingual drops. Academic medical centers in the United States and Germany anchor demand for SCIT protocols, with sublingual formats expanding community clinic access.
Antihistamines lead volumes today; immunotherapy is gaining share fastest.
Delivery Mode:
Route selection hinges on patient self-administration capability versus specialist supervision requirements, with reimbursement frameworks favoring injection-based protocols in institutional settings.
- Oral:Tablet and liquid formulations spanning antihistamines, leukotriene modifiers, and emerging sublingual immunotherapy tablets. Retail pharmacy chains across the United States prioritize oral formats for inventory turnover efficiency and direct-to-consumer marketing pathways.
- Intranasal:Metered-dose spray devices delivering corticosteroids or antihistamines to nasal mucosa. Japanese consumers demonstrate highest per-capita adoption, driven by cultural preference for non-invasive intervention and OTC availability of prescription-grade devices.
- Subcutaneous:Injection protocols requiring allergist administration in supervised clinical environments. German university hospital networks concentrate SCIT delivery, with centralized formulary decisions compressing supplier margins through multi-hospital purchasing agreements.
- Sublingual:Oral-dissolving tablets or drops enabling home-based immunotherapy without injection burden. United States allergist practices are accelerating clinical adoption, expanding addressable pools beyond traditional shot clinic catchment areas.
Oral administration dominates current prescription volumes; sublingual delivery is climbing the fastest as practice workflows adapt.
End User:
Channel selection reflects therapy complexity gradients, with biologic therapies requiring cold chain integrity concentrating in hospital settings while maintenance antihistamines flow through retail.
- Hospitals:Inpatient and emergency departments managing anaphylaxis and severe asthma exacerbations. United States academic medical centers anchor biologic allergy therapy demand, with consolidated purchasing agreements displacing individual pharmacy negotiations.
- Clinics:Outpatient allergist practices delivering immunotherapy protocols and biologic injections. German specialist networks concentrate in urban clusters, creating access bottlenecks that limit protocol expansion into secondary markets.
- Homecare:Self-administered sublingual immunotherapy and maintenance pharmacotherapy. Patient convenience preferences in Japan are pulling prescription-grade delivery technologies into home settings with remote monitoring support.
- Retail Pharmacies:Over-the-counter antihistamines and intranasal corticosteroids. United States pharmacy chains leverage seasonal marketing campaigns that synchronize with pollen forecast services.
Retail pharmacies capture the highest transaction volumes; hospital channels deliver the steepest revenue per patient.
Application:
Disease chronicity and severity stratification drive therapy selection, with perennial conditions justifying immunotherapy investment against seasonal patterns favoring symptomatic management.
- Seasonal Allergies:IgE-mediated responses to pollen, mold spores, and outdoor allergens with predictable temporal patterns. United States retail channels concentrate demand, with prescription-to-OTC migration compressing branded revenue pools.
- Perennial Allergies:Year-round sensitization to dust mites, pet dander, and indoor allergens. German immunotherapy clinics prioritize these patients for multi-year SCIT protocols given higher adherence rates versus seasonal dropouts.
- Allergic Rhinitis:Nasal mucosa inflammation presenting as intermittent or persistent disease. Japanese otorhinolaryngology practices anchor intranasal corticosteroid prescribing, with PMDA efficacy requirements shaping formulation preferences.
- Allergic Asthma:Lower airway inflammation with allergic triggers requiring step-up therapy algorithms. United States severe asthma clinics pilot biologic-digital combination products to demonstrate outcomes data to payers.
Allergic rhinitis generates the largest patient population; allergic asthma commands the highest per-patient therapy investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement groups consolidate biologic purchasing power more aggressively than German university networks, compressing supplier margins through multi-hospital agreements rather than individual pharmacy negotiations.
United States
Severe asthma clinics pilot biologic-digital combination products to demonstrate outcomes data to payers, while academic medical centers anchor demand for subcutaneous immunotherapy protocols. FDA pharmacovigilance tightening extends IND timelines for novel allergy biologics. Boston and New York Metro clusters concentrate pediatric allergology expansion with dedicated immunotherapy service lines.
Germany
University hospital networks centralize formulary decisions for dupilumab-class therapies, displacing specialty distributors with direct manufacturer contracts. EMA MDR framework reshapes post-market surveillance obligations for immunotherapy device-drug combinations. Bavaria and North Rhine-Westphalia host densest specialist networks, creating access bottlenecks that limit protocol expansion into secondary markets.
Japan
Patient convenience preferences pull prescription-grade intranasal delivery technologies into retail pharmacy channels with direct-to-consumer marketing potential. PMDA imposes localized efficacy bridging studies that extend market access timelines for imported allergy therapies. Tokyo and Osaka metropolitan areas demonstrate highest per-capita adoption of non-invasive intervention formats.
United Kingdom
Hospital outpatient clinics favor nasal corticosteroids for moderate persistent allergic rhinitis, constrained by formulary tier placement that limits biologic escalation. MHRA aligns with EMA pharmacovigilance standards for allergen extract standardization. London and Southeast England concentrate fellowship-trained allergist workforce in academic medical centers.
India
Expanding middle-class patient pools drive demand for affordable oral antihistamine formulations across retail pharmacy chains. CDSCO regulatory pathways for biosimilar allergy therapies attract domestic manufacturing investment. Maharashtra and Gujarat pharmaceutical clusters scale production of generic immunotherapy extracts for regional export.
Allergy Treatment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct portfolio strategies. Respiratory and immunology franchises anchor seasonal allergy positioning for broad-based pharmaceutical groups, while dedicated allergology firms concentrate on extract standardization and immunotherapy protocol development. Three archetypes dominate: integrated respiratory-immunology platforms, standalone allergen extract manufacturers, and biologic monoclonal antibody developers. Consolidated purchasing agreements among hospital procurement groups compress margins and amplify volume commitments to preferred suppliers, while sublingual tablet producers accelerate biodegradable polymer substitutions ahead of ECHA sunset dates.
Within the integrated pharmaceutical tier, GlaxoSmithKline and Sanofi occupy positions anchored by respiratory franchise extensions into allergy portfolios. AbbVie Inc. exemplifies the biologic development archetype through sustained R&D intensity in next-generation therapeutic candidates. These three entities represent contrasting strategic postures: franchise leverage versus pipeline concentration versus therapeutic area depth.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AbbVie Inc. |
| Pfizer Inc. |
| Allergy Therapeutics PLC |
| ALK-Abello |
| Johnson & Johnson |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Curative versus symptomatic therapy divergence separates premium immunotherapy protocols from commoditized antihistamine baskets, with that bifurcation manifesting in German hospital formulary tier placement and cold-chain logistics investment patterns. Hospital procurement groups exploit this tiering through consolidated purchasing agreements that compress biologic margins while amplifying volume commitments to preferred suppliers.
Pricing Analysis
Capacity additions in Indian generic manufacturing are reshaping price floors for oral antihistamine formulations across retail pharmacy channels. Three-tier pricing structure across premium biologics, standard immunotherapy extracts, and economy antihistamines reflects FDA and EMA certification gradients alongside cold-chain delivery cost differentials. Pricing pressure stems from consolidated hospital procurement negotiations in the United States and Germany. Retail pharmacy chains demonstrate highest price sensitivity, while academic medical centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
EMA MDR certification requirements and FDA IND standards gate supplier participation, filtering extract manufacturers by protein standardization capability and post-market surveillance infrastructure. Active pharmaceutical ingredient production concentrates in India and China, while biologic fill-finish operations anchor in Germany and the United States. Supply chains draw from temperature-sensitive monoclonal antibodies, standardized allergen extracts, and biodegradable polymer excipients. Single-source vulnerability runs through specialized cold-chain logistics providers serving metropolitan hospital hubs. Distribution runs through specialty distributors for academic medical centers and direct manufacturer contracts for consolidated hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in sublingual immunotherapy formats where home administration eliminates clinic overhead and extends patient retention curves. Biodegradable polymer substitution ahead of ECHA sunset dates offers additional cost-down runway for extract manufacturers.
For Market Incumbents: Anchor respiratory-immunology franchise extensions through pediatric allergology service line partnerships in Boston and New York Metro clusters. Defend against sublingual tablet entrants by securing exclusive formulary placement for subcutaneous protocols in German university hospital networks. Backward integration into extract standardization capabilities insulates margin pressure from protein content variability. For New Entrants and Emerging Players: Specialty distributors serving community allergist practices represent the most accessible channel wedge for sublingual immunotherapy formats bypassing academic medical center concentration. Target United States secondary markets outside Boston-New York corridor where shot clinic access bottlenecks create patient pool expansion opportunity. Direct-to-consumer marketing through pollen forecast service partnerships offers lowest-friction patient acquisition. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR compliance costs fragment extract manufacturers lacking reformulation capital. Long-term viability favors sponsors with bridging study infrastructure for PMDA market access and biologic-digital combination product pipelines. Acquisition target archetype: mid-cap allergen extract specialists with REACH-compliant polymer platforms. Watch FDA pharmacovigilance guidance expansion as inflection indicator for clinical trial cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Substitution | ECHA REACH compliance ahead of sunset dates preserves European market access for extract manufacturers. |
| Pediatric Allergology Service Line | Dedicated immunotherapy protocols in Boston and New York Metro clusters secure multi-year patient retention. |
| Biologic-Digital Combination Development | Embedded sensor integration with dupilumab-class therapies demonstrates outcomes data to United States payers. |
| PMDA Bridging Study Infrastructure | Localized efficacy investment in Tokyo and Osaka creates first-mover advantage for imported allergy therapies. |
| Consolidated Hospital Procurement Contract | Multi-hospital system agreements in Germany displace specialty distributors with direct manufacturer volume commitments. |
Methodological Framework
Multiple input streams — allergist practice administrators, hospital formulary directors, biologic supply chain managers, and regulatory affairs specialists — were reconciled against FDA 510(k) filings, EMA MDR submissions, ClinicalTrials.gov protocols, and hospital procurement database extracts. Bottom-up patient volume modeling across seasonal and perennial allergy indications was cross-validated with top-down pharmaceutical revenue segmentation. Primary interviews with pediatric allergology department heads and GPO contracts managers informed immunotherapy protocol adoption curves.
Data-stream reconciliation anchored quantitative outputs across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user channel, and application severity stratification. CAGRs were derived from patient population growth trajectories, therapy switching patterns, and reimbursement framework evolution. Forecast inputs incorporated pollen forecast service partnership expansion rates and sublingual tablet pharmacy stocking data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA pharmacovigilance tightening, EMA MDR enforcement intensity, and allergist workforce scarcity in secondary markets. Forecasts reflect documented assumptions regarding immunotherapy adherence curves and biologic cold-chain infrastructure expansion. A model refresh is warranted upon material change in consolidated hospital procurement negotiation dynamics or PMDA bridging study timeline requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Nasal Allergy Treatment Market