
 Splenomegaly Therapeutics Market | 2026-2036
Splenomegaly Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Splenomegaly Therapeutics Market Analytics
Good Manufacturing Practice certification for biologic drug production is reorganizing competitive entry in splenomegaly therapeutics. Novartis AG leverages its established JAK inhibitor portfolio to anchor presence in myelofibrosis-related splenic enlargement. Incyte Corporation specializes in precision signaling pathway blockade, while Bristol-Myers Squibb Company competes through immunomodulatory agent development for lymphoid malignancies.
Splenomegaly therapeutics encompass pharmacological interventions targeting pathological spleen enlargement from hematologic, infectious, autoimmune, or neoplastic etiologies, with monoclonal antibodies and small molecules forming the core mechanistic classes. These agents function primarily to reduce splenic burden, alleviate cytopenias, and interrupt disease-driving molecular pathways in conditions such as myelofibrosis and lymphoma. Monoclonal antibodies command substantial margin pools due to premium positioning in oncology-linked splenomegaly, while small molecules gain traction through oral bioavailability advantages in outpatient autoimmune and hematologic disorder management. The intravenous delivery mode retains institutional dominance through hospital infusion center capture, though subcutaneous formulations are expanding access in specialty clinic settings.
FDA accelerated approval designations and EMA orphan drug frameworks shape development economics by compressing trial timelines for rare splenic disorder indications. The EU MDR and ISO 13485 quality standards govern device-drug combination products used in splenic intervention, creating compliance thresholds for market participation. Stakeholders must monitor evolving reimbursement policies for biologic splenomegaly agents across Medicare, Medicaid, and European national health technology assessment bodies to anticipate access-driven volume shifts.
Market Dynamics
FDA accelerated approval pathways for rare disease therapeutics are compressing clinical development timelines and reshaping competitive entry economics in splenomegaly therapeutics. Hospital-based hematology departments are expanding adoption of targeted biologics, creating institutional lock-in effects that favor early movers with infusion center relationships.
Growth Catalysts
- Orphan Drug Incentives:EMA orphan drug frameworks provide protocol assistance and fee reductions for developers targeting myelofibrosis-related splenic enlargement. This accelerates European market entry for novel signaling pathway inhibitors.
- Biologic Manufacturing Scale-Up:Good Manufacturing Practice certification expansion in contract manufacturing organizations is reducing production bottlenecks for monoclonal antibody therapies. This enables faster commercialization of splenomegaly-targeted biologics.
- Specialized Treatment Center Density:United States lymphoproliferative disorder treatment centers are driving protocol innovation through prospective registry data collection. This creates real-world evidence generation infrastructure that supports label expansion.
Market Restraints
- Plasma-Derived Input Volatility:Fractionation feedstock supply concentration in North American and European collection networks creates raw material cost instability for immunoglobulin-based splenomegaly therapies.
- Reimbursement Compression:Medicare and Medicaid prior authorization requirements for biologic splenomegaly agents are extending time-to-therapy initiation and creating administrative burden for hematology practices.
- Substitution Threat from Splenectomy:Laparoscopic surgical techniques and improved perioperative management are preserving splenectomy as a cost-competitive alternative for selected autoimmune and hematologic indications.
Strategic Opportunities
- Subcutaneous Formulation Expansion:Self-administration routes for JAK inhibitors and monoclonal antibodies are opening specialty clinic and home care channels outside hospital infusion centers.
- Companion Diagnostic Integration:Molecular profiling of splenic pathology is enabling patient stratification for targeted therapy selection, creating value-capture opportunities for integrated diagnostic-therapeutic platforms.
- EU MDR Compliance Services:Device-drug combination products for splenic intervention require ISO 13485 quality system certification, creating service revenue streams for regulatory consulting and quality assurance providers.
Industry Challenges
- Cellular Therapy Manufacturing Expertise:CAR-T and other engineered cell therapies for lymphoid malignancies require specialized cleanroom operations and vector production capabilities that exceed standard biologic manufacturing skill bases.
- Real-World Evidence Standardization:Heterogeneous data capture across hospital-based hematology departments complicates post-market surveillance and comparative effectiveness research for splenomegaly therapeutics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Splenomegaly Therapeutics Market |
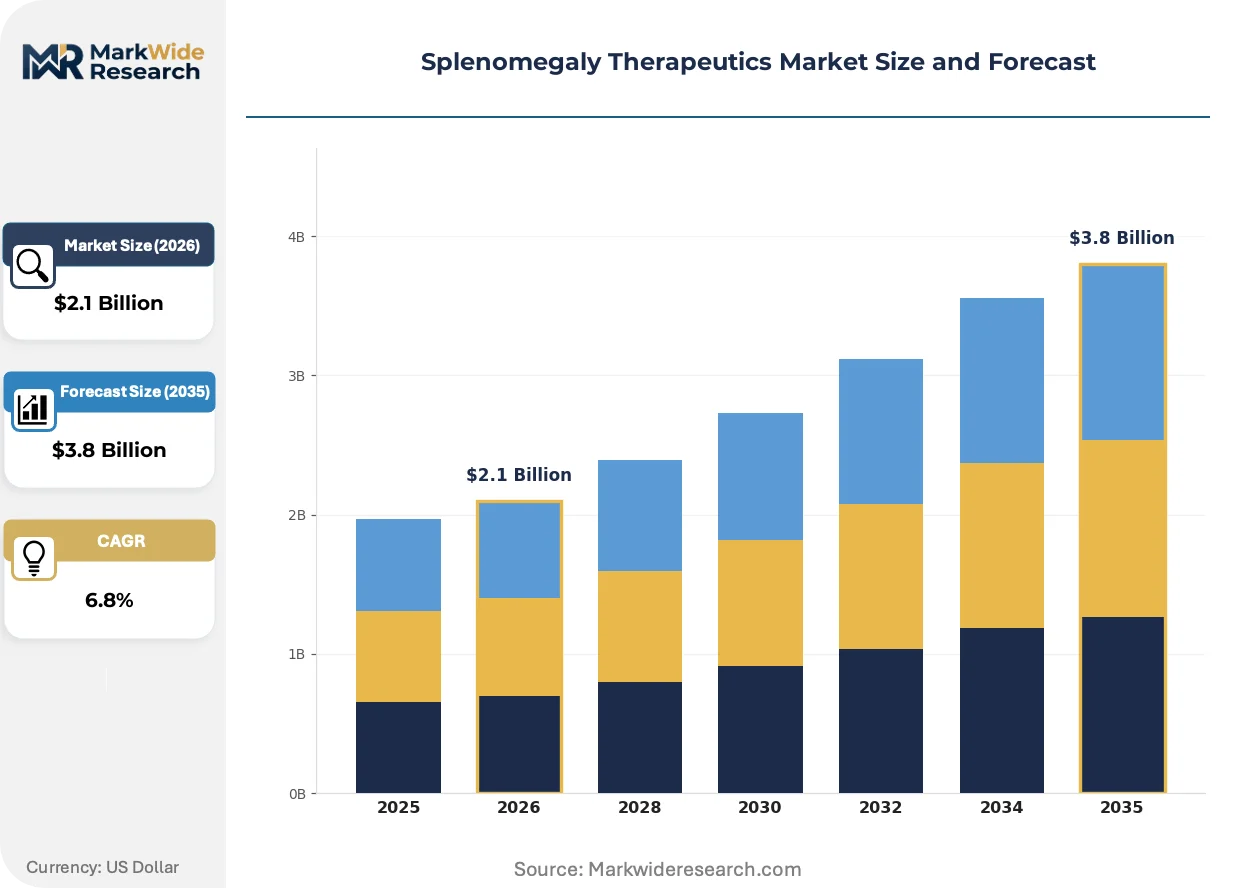
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Small Molecules, Enzyme Inhibitors Therapy Area: Hematologic Disorders, Autoimmune Diseases, Infectious Diseases, Oncology Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Specialty Clinics, Outpatient Facilities, Research Institutions |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Incyte Corporation, Novartis AG, Sanofi, Pfizer Inc., F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Splenomegaly Therapeutics Market Evolving Landscape
Novel drug delivery technologies and regulatory pathway innovations are restructuring how splenomegaly therapeutics reach patients. These developments are compressing development timelines while expanding administration settings beyond traditional hospital confines.
Subcutaneous formulation technologies for monoclonal antibodies and small molecule inhibitors are miniaturizing the infrastructure required for splenomegaly therapy administration. Community oncology practices and specialty infusion clinics are adopting these portable delivery systems to capture patient volume from academic medical centers. This decentralization is compressing the historical dominance of hospital-based hematology departments in splenomegaly care.
EU MDR and FDA breakthrough therapy designation frameworks are converging to create synchronized regulatory expectations for rare disease therapeutics. Developers now design single development programs capable of supporting simultaneous US and European submissions for splenic disorder indications. This harmonization is most visible in myelofibrosis-related splenomegaly, where sponsors are pursuing parallel accelerated approval pathways.
Hospital procurement committees are consolidating biologic purchasing through specialty pharmacy networks and group purchasing organizations. This channel concentration is displacing direct manufacturer-to-provider contracting for splenomegaly therapeutics. The shift is most pronounced in United States integrated delivery networks, where formulary placement decisions increasingly rest with centralized pharmacy and therapeutics committees rather than individual hematology divisions.
Splenomegaly Therapeutics Market Segmentation
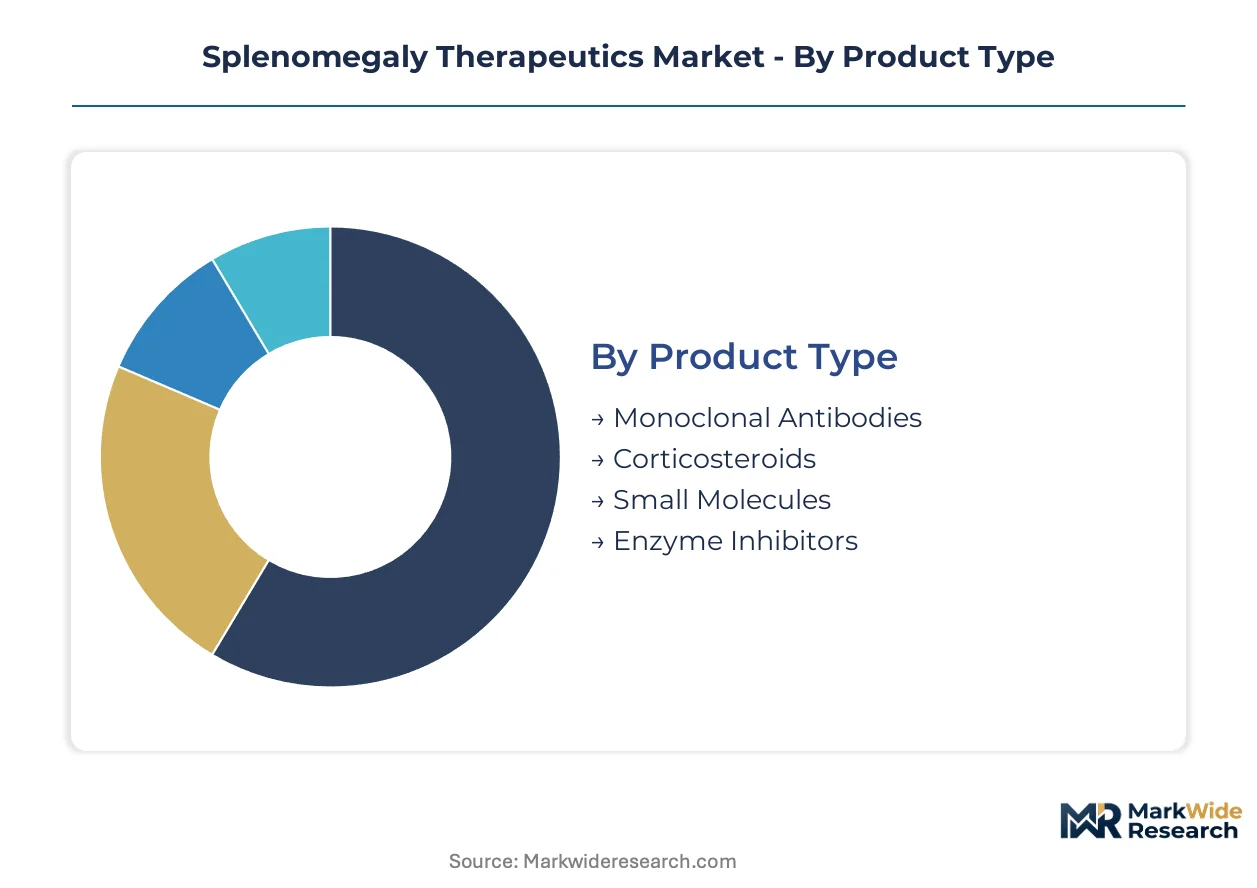
Splenomegaly therapeutics segment across mechanistic classes, disease etiologies, and care settings. Understanding where margin pools concentrate and how delivery infrastructure shapes access reveals competitive positioning opportunities.
Product Type:
Monoclonal antibodies command premium pricing in oncology-linked splenomegaly, while small molecules capture volume through outpatient oral administration.
- Monoclonal Antibodies:Engineered immunoglobulins targeting CD20, CD52, or splenic signaling nodes deliver high-efficacy cytoreduction in lymphoproliferative disorders. Demand concentrates in United States academic medical centers where infusion center infrastructure supports IV administration and reimbursement pathways favor biologic premiums.
- Small Molecules:Oral kinase inhibitors and immunomodulatory agents enable self-administration outside hospital settings. Prescription volume is rotating toward community hematology practices in Germany and France as JAK inhibitor labels expand beyond myelofibrosis into polycythemia vera with splenic involvement.
- Corticosteroids:First-line immunosuppression for autoimmune splenomegaly retains cost-tier positioning despite biologic displacement in refractory cases.
- Enzyme Inhibitors:Targeted metabolic pathway blockers address rare lysosomal storage disorders with splenic manifestations, serving ultra-orphan indications with concentrated prescriber bases.
Monoclonal antibodies hold installed capacity. Small molecules are rotating up the share rankings.
Therapy Area:
Application concentration follows disease prevalence and treatment intensity, with hematologic malignancies driving the highest per-patient therapeutic burden.
- Hematologic Disorders:Myelofibrosis, polycythemia vera, and essential thrombocythemia generate sustained splenic-directed therapy demand through chronic disease management. United States specialized treatment centers in Boston, Houston, and Seattle anchor protocol development and real-world evidence generation for JAK inhibitor optimization.
- Oncology:Lymphoma and leukemia-related splenomegaly requires intensive cytoreductive regimens with combination biologic therapy. European reference networks in France, Italy, and the Netherlands coordinate access to CAR-T and novel antibody-drug conjugates for refractory cases.
- Autoimmune Diseases:Lupus and rheumatoid arthritis with splenic involvement represent maintenance therapy volume where corticosteroid-sparing biologics are penetrating.
- Infectious Diseases:Malaria, visceral leishmaniasis, and EBV-related splenomegaly concentrate demand in endemic geographies with distinct access and pricing frameworks.
Hematologic disorders anchor therapeutic innovation. Oncology is climbing the fastest as lymphoma biologics expand labels.
Delivery Mode:
Patient preference and site-of-care economics are reshaping formulation development priorities across administration routes.
- Intravenous:Infusion center administration retains institutional capture for high-complexity biologics requiring monitoring. Hospital-based hematology departments in the United States maintain formulary control over IV monoclonal antibodies through specialty pharmacy networks.
- Subcutaneous:Self-injection formulations for JAK inhibitors and select antibodies are displacing hospital visits in German and Swiss outpatient settings. Community oncology practices in Munich and Zurich are capturing patient volume from academic centers through portable delivery system adoption.
- Oral:Small molecule kinase inhibitors enable home-based chronic disease management with highest patient convenience quotient.
- Intramuscular:Depot formulations for sustained corticosteroid delivery serve select autoimmune indications with compliance advantages.
Intravenous holds installed capacity. Subcutaneous is rotating up the share rankings.
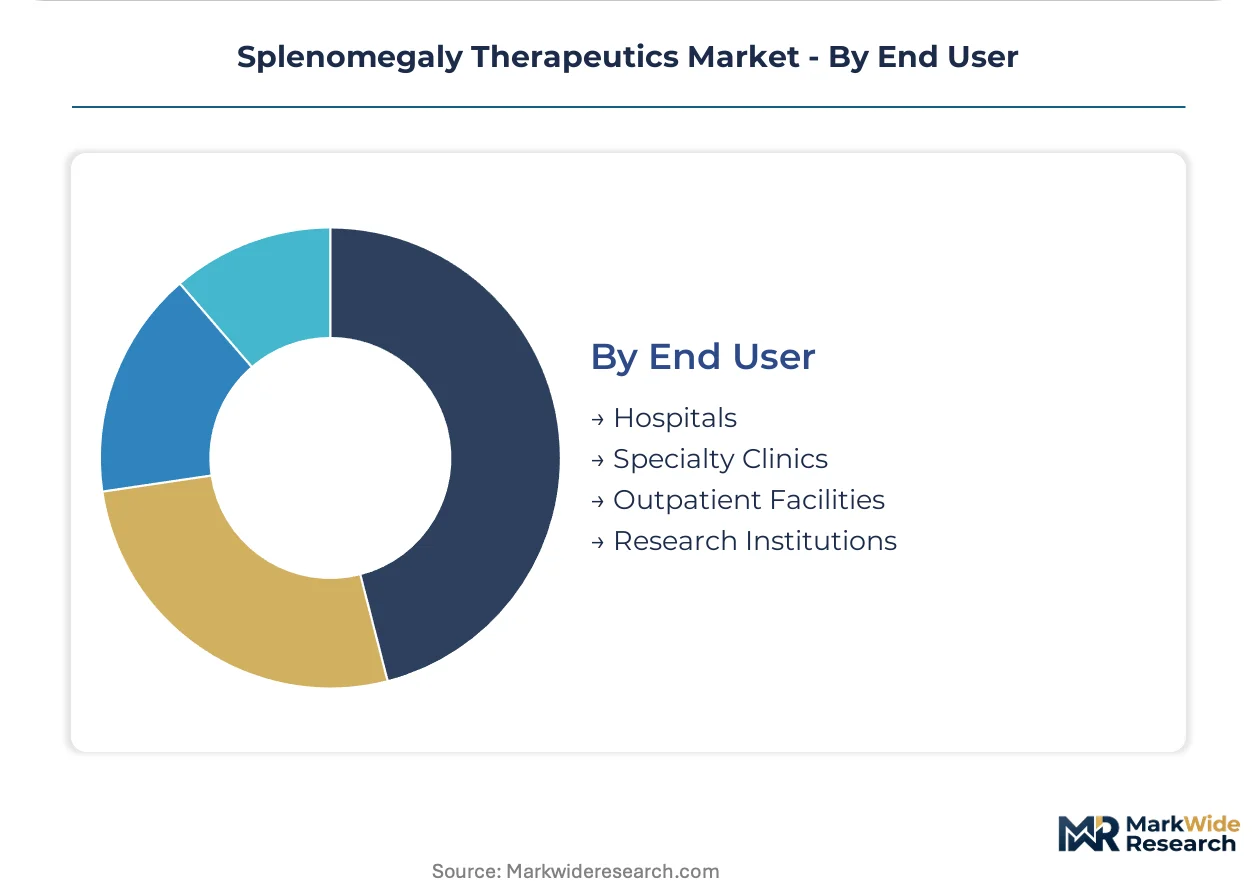
End User:
Channel structure concentrates purchasing power while fragmenting prescriber decision-making across care settings.
- Hospitals:Academic medical centers and community hospital systems anchor biologic infusion volume through centralized pharmacy and therapeutics committees. United States integrated delivery networks in California, Texas, and New York are consolidating splenomegaly therapeutics procurement through group purchasing organizations.
- Specialty Clinics:Independent hematology-oncology practices and multi-specialty groups are gaining subcutaneous and oral therapy volume. French cancer centers and German onkologische Schwerpunkte are expanding molecular profiling capabilities to support targeted therapy selection.
- Outpatient Facilities:Ambulatory infusion centers and retail specialty pharmacies are capturing stable chronic therapy administration.
- Research Institutions:National cancer institutes and academic research organizations anchor clinical trial enrollment and early access programs for novel splenomegaly therapeutics.
Hospitals hold installed capacity. Specialty clinics are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized hematology departments concentrate purchasing power for splenomegaly therapeutics across mature healthcare systems. Reimbursement frameworks and orphan drug policies determine regional access patterns for biologic therapies targeting myelofibrosis-related splenic enlargement.
United States
FDA accelerated approval pathways compress development timelines for rare disease therapeutics targeting splenic disorders. Medicare and Medicaid prior authorization requirements create administrative friction for biologic therapy initiation. Boston, Houston, and Seattle anchor specialized lymphoproliferative disorder treatment centers that drive protocol innovation and real-world evidence generation.
Germany
Community oncology practices in Munich and Hamburg capture patient volume through subcutaneous formulation adoption outside academic centers. EMA orphan drug frameworks provide protocol assistance and fee reductions for developers of signaling pathway inhibitors. The country's statutory health insurance system maintains centralized pharmacy and therapeutics committees that consolidate biologic purchasing decisions.
France
French cancer centers expand molecular profiling capabilities to support targeted therapy selection for lymphoma-related splenomegaly. ANSM and HAS coordinate reimbursement assessments for novel biologics through early access programs. Reference networks in Paris, Lyon, and Marseille coordinate access to CAR-T and antibody-drug conjugates for refractory hematologic malignancies.
Switzerland
Swissmedic maintains accelerated review pathways for therapies addressing unmet needs in rare splenic disorders. Outpatient hematology practices in Zurich and Basel adopt portable delivery systems for JAK inhibitor administration. The country's mandatory health insurance framework supports premium positioning for monoclonal antibody therapies in oncology-linked splenomegaly.
United Kingdom
NICE technology appraisals determine NHS England access for biologic splenomegaly agents through cost-effectiveness thresholds. London, Manchester, and Birmingham host specialized hematology centers that anchor clinical trial enrollment for novel therapeutics. The UK Medicines and Healthcare products Regulatory Agency participates in FDA-EMA regulatory convergence initiatives for rare disease therapeutics.
Splenomegaly Therapeutics Market Competitive Landscape
Player mix skews toward large-cap pharmaceutical conglomerates with established oncology and hematology franchises. The competitive field exhibits moderate consolidation around JAK inhibitor and monoclonal antibody portfolios. Three strategic archetypes dominate: signaling pathway specialists, immunomodulatory platform developers, and broad hematology-oncology portfolio players. Capacity expansion in biologic manufacturing and strategic partnerships for companion diagnostic integration represent the dominant competitive moves.
Among the signaling pathway specialists, Incyte Corporation occupies a position exemplifying precision kinase inhibition focus, while Novartis AG represents the diversified pharmaceutical conglomerate archetype with cross-portfolio synergies in myeloproliferative disorders. Bristol-Myers Squibb Company sits within the immunomodulatory platform tier, anchoring presence through established biologic development infrastructure.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Incyte Corporation |
| Novartis AG |
| Sanofi |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| AstraZeneca plc |
| Others |
Value Network & Pricing Analysis
Ninety-day plasma collection cycles in North American and European fractionation networks concentrate bargaining power among three dominant suppliers, directly amplifying price volatility for immunoglobulin-based splenomegaly therapies while compressing margins for downstream biologic manufacturers.
Pricing Analysis
Cost-plus contracts indexed to plasma protein pricing benchmarks dominate procurement between fractionators and biologic developers, with pass-through clauses amplifying feedstock cost swings into finished therapy pricing. Three-tier pricing structure across premium monoclonal antibodies, standard JAK inhibitors, and economy corticosteroid tiers reflects certification grade and infusion center service bundling. Pricing pressure stems from Medicare prior authorization requirements extending time-to-therapy initiation. Community hematology practices exhibit highest price sensitivity; academic medical centers with specialty pharmacy networks show lowest.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled biologics spiked on trans-Atlantic lanes following port congestion at Rotterdam and Hamburg, compressing just-in-time delivery windows for European hospital infusion centers. Manufacturing concentrates in the United States, Germany, and Switzerland, with plasma fractionation drawing from North American and European collection networks. Critical dependencies include plasma feedstock, single-use bioreactor components, and viral filtration membranes. Single-source vulnerability in vector production for emerging cell therapies threatens supply continuity. Distribution runs through specialty pharmacy networks and group purchasing organizations consolidating hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Splenomegaly therapeutics fragment across mechanistic classes and care settings, creating white-space opportunities as subcutaneous formulation adoption decentralizes patient volume from academic infusion centers toward community specialty clinics.
For Market Incumbents: Consolidate infusion center relationships through exclusive biologic supply agreements before subcutaneous formulations erode institutional capture. Acquire companion diagnostic capabilities to lock in patient stratification workflows. JAK inhibitor commoditization in myelofibrosis threatens margin pools; defend through label expansion into polycythemia vera with splenic involvement. For New Entrants and Emerging Players: Anchor in French and German community oncology practices adopting portable delivery systems for JAK inhibitor administration. Target autoimmune splenomegaly indications where corticosteroid-sparing biologics remain underpenetrated. Pursue EU MDR compliance service partnerships as device-drug combination products proliferate in splenic intervention. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cellular therapy manufacturing as CAR-T production requirements exceed standard biologic cleanroom capabilities. Long-term viability favors platform companies with integrated diagnostic-therapeutic positioning over single-asset developers. Acquisition target archetype: signaling pathway specialists with validated kinase inhibitors and companion diagnostic partnerships. Signal to watch: FDA breakthrough therapy designation frequency in rare splenic disorder indications.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Community oncology practices in Munich and Zurich capture patient volume from academic centers through portable delivery adoption. |
| Companion Diagnostic Integration | Molecular profiling of splenic pathology enables patient stratification for targeted therapy selection in French cancer centers. |
| EU MDR Compliance Investment | Device-drug combination products for splenic intervention require ISO 13485 certification, creating service revenue streams. |
| Specialty Pharmacy Network Partnership | United States integrated delivery networks consolidate biologic purchasing through group purchasing organizations displacing direct contracting. |
| Real-World Evidence Infrastructure | Boston, Houston, and Seattle treatment centers anchor protocol development through prospective registry data collection. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down epidemiological triangulation anchored volume estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include mechanistic class, disease etiology, delivery mode, and care setting. CAGRs derived from treatment-line penetration curves and pricing trajectory assumptions. Forecast inputs incorporated JAK inhibitor label expansion patterns and subcutaneous formulation adoption rates in community hematology practices.
Underlying assumptions cover regulatory pathway timelines and reimbursement policy stability, with deviation risk concentrated in Medicare prior authorization requirement changes and plasma feedstock supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market