
 Transarterial Chemoembolization (TACE) Market | 2026-2036
Transarterial Chemoembolization (TACE) Market Size, Share, and Industry Trends Forecast 2026-2036
Transarterial Chemoembolization (TACE) Market Analytics
Drug-eluting bead precision specifications is rotating toward higher embolic uniformity and calibrated doxorubicin loading as the default procurement benchmark. Cook Medical leverages captive manufacturing of calibrated microspheres to sustain its position in North American catheter labs. Merit Medical Systems anchors its portfolio through integrated embolic delivery platforms that span preparation through deployment. Boston Scientific competes on intermediate catheter technique compatibility across its embolization portfolio.
Transarterial chemoembolization denotes a dual-mechanism locoregional therapy combining selective intra-arterial injection of chemotherapeutic agents with subsequent arterial embolization using biocompatible carriers, typically calibrated microspheres or gelatin sponge fragments measuring 100-300 micrometers, to achieve tumor ischemia and sustained drug exposure. The procedure serves as first-line palliative intervention for intermediate-stage hepatocellular carcinoma in patients preserving liver function but ineligible for surgical resection or transplantation. Drug-eluting beads command margin concentration due to reproducible pharmacokinetic profiles and premium reimbursement positioning against conventional gelatin sponge protocols. Hepatocellular carcinoma applications dominate procedure volumes while specialized cancer centers represent the fastest-expanding end-user channel as regional hub-and-spoke referral networks consolidate complex interventional oncology.
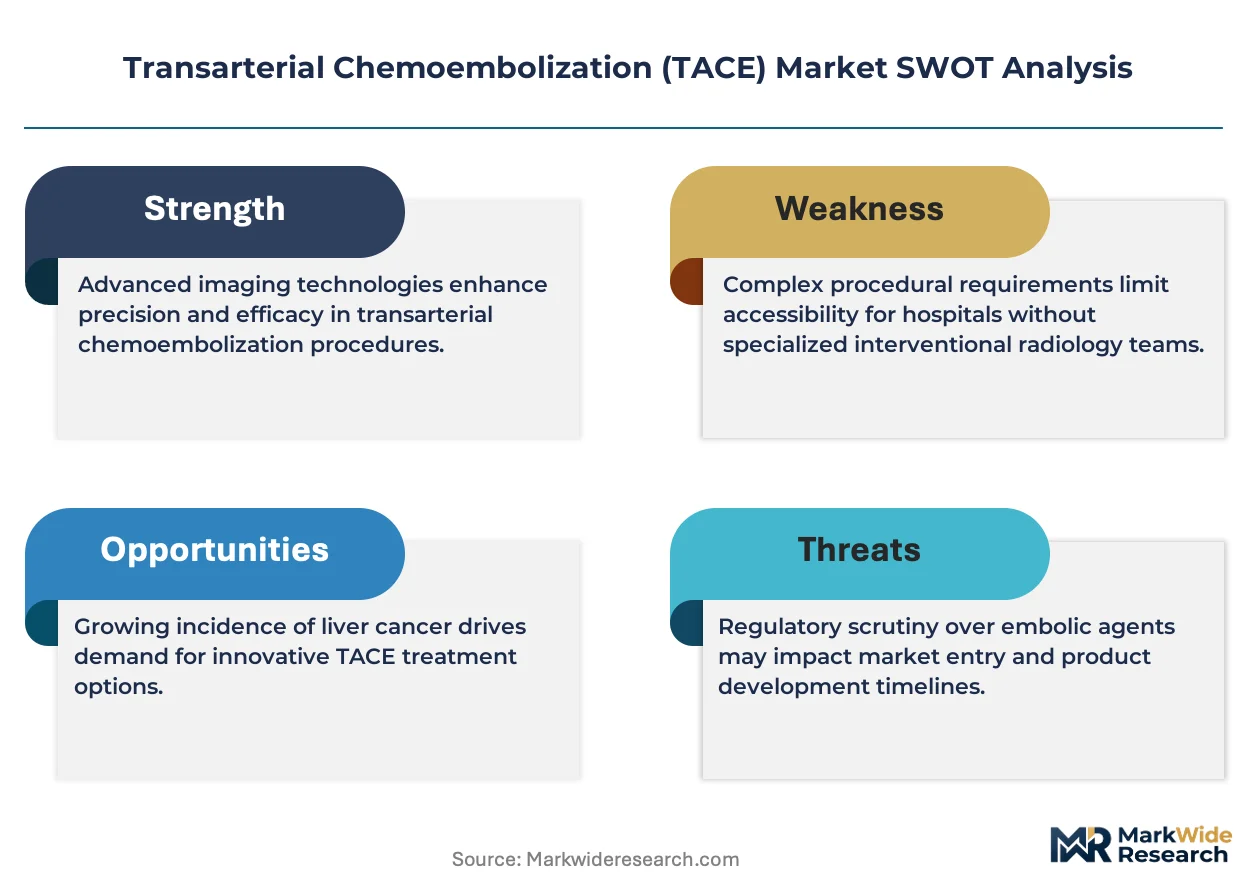
FDA premarket notification pathways and EMA medical device regulation conformity assessments govern embolic agent commercialization, with both frameworks tightening biocompatibility and drug-device combination classification requirements. The EPA and OSHA intersect through waste handling mandates for chemotherapy preparation suites, elevating capital requirements for clinic-based TACE programs. Stakeholders must monitor evolving CE marking transitions under the EU Medical Device Regulation and corresponding notified body capacity constraints that could delay European market entry timelines.
Market Dynamics
Drug-eluting bead standardization is compressing procurement cycles as tertiary hospitals consolidate supplier relationships around calibrated embolic platforms with reproducible pharmacokinetic profiles.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's expedited pathway for drug-eluting bead platforms compresses commercialization timelines for manufacturers demonstrating superior clinical endpoints in unresectable hepatocellular carcinoma.
- Hub-and-Spoke Consolidation:Regional referral networks are concentrating complex interventional oncology procedures at specialized cancer centers, amplifying procedure volume at high-throughput facilities.
- Embolic Uniformity Specifications:Calibrated microsphere manufacturing advances are enabling tighter doxorubicin loading tolerances that satisfy interventional radiology departments demanding procedural reproducibility.
Market Restraints
- Notified Body Capacity Constraints:EU Medical Device Regulation transitions are throttling CE marking throughput, delaying European market entry for novel embolic agents.
- Platinum Input Volatility:Intermediate catheter construction relies on platinum-iridium alloys subject to commodity price swings that compress margin structures.
- Gelatin Sponge Substitution:Conventional embolic protocols retain cost advantages in resource-constrained settings, capping premium bead penetration in price-sensitive segments.
Strategic Opportunities
- India Interventional Radiology Infrastructure:CDSCO regulatory harmonization initiatives and private hospital capital expenditure programs are creating first-mover advantages for calibrated bead suppliers.
- Convergence with Ablation Technologies:Combined TACE-radiofrequency ablation protocols are expanding addressable patient populations beyond intermediate-stage hepatocellular carcinoma into mixed-modality treatment planning.
- Japan PMDA Sakigake Pathway:Japan's regenerative medicine and innovative device fast-track is accelerating reimbursement negotiations for next-generation drug-eluting platforms.
Industry Challenges
- Interventional Radiology Fellowship Pipeline:Procedural complexity demands specialized training that outpaces academic program expansion, creating talent scarcity at expanding TACE programs.
- OSHA Chemotherapy Waste Compliance:EPA intersection mandates for preparation suite ventilation and disposal infrastructure elevate capital requirements for clinic-based programs.
- Legacy Catheter Compatibility:Drug-eluting bead platforms require intermediate catheter technique standardization that conflicts with installed base equipment at smaller interventional suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transarterial Chemoembolization (TACE) Market |
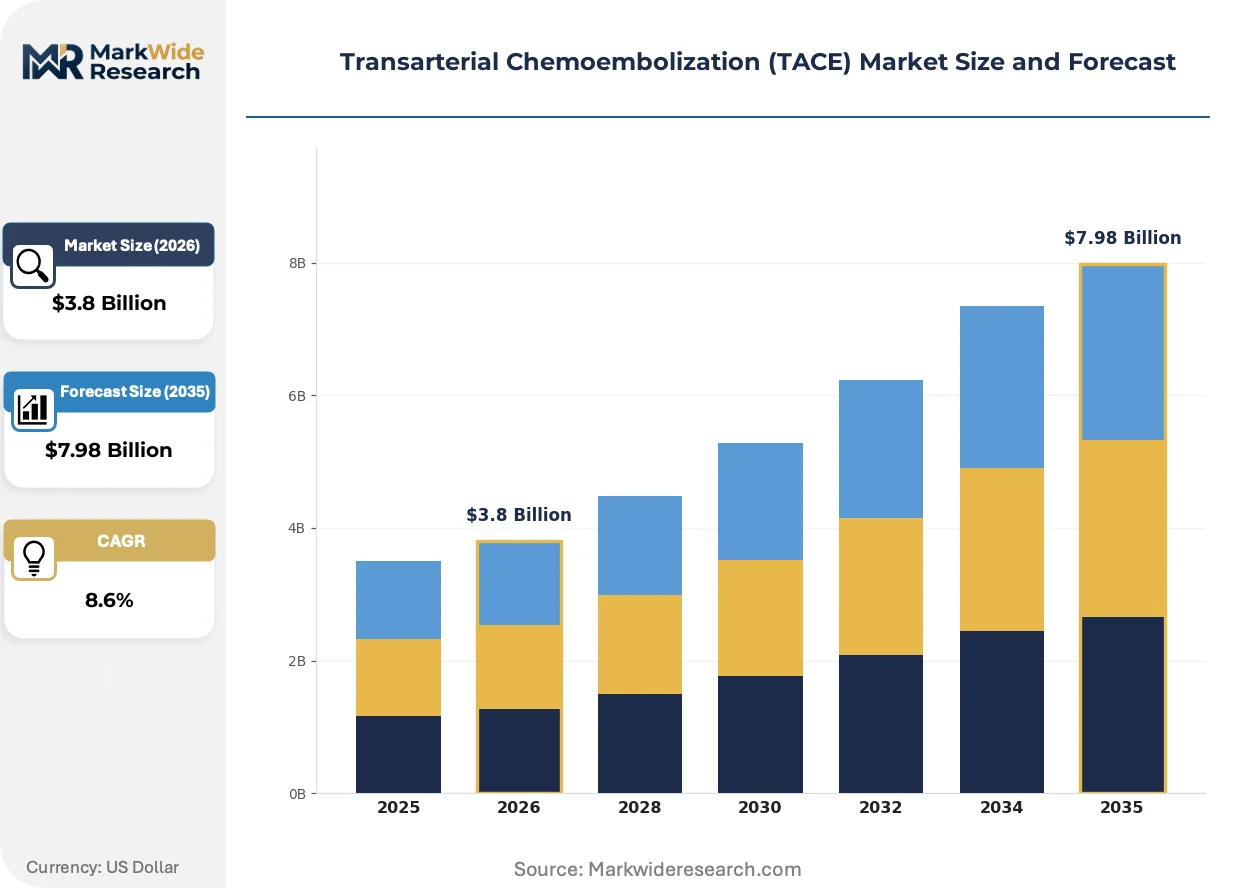
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microspheres, Gelatin Sponge, Embolic Agents, Drug-Eluting Beads Application: Hepatocellular Carcinoma, Liver Metastases, Bile Duct Tumors, Renal Cell Carcinoma End User: Hospitals, Clinics, Specialized Cancer Centers, Research Institutions Delivery Mode: Intra-arterial Injection, Catheter-Based Delivery, Intermediate Catheter Technique, Selective Catheterization |
| Companies Covered | Cook Medical, Merit Medical Systems, Inc., Boston Scientific Corporation, Novartis AG, Pfizer Inc., Terumo Corporation, Siemens Healthineers AG, Nippon Kayaku Co., Ltd., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transarterial Chemoembolization (TACE) Market Evolving Landscape
Embolic platform evolution is bifurcating between precision-calibrated systems and cost-optimized alternatives as reimbursement compression forces explicit value demonstration.
Calibrated microsphere manufacturing is fragmenting competitive positioning as automated sizing technology enables smaller manufacturers to achieve batch-to-batch uniformity previously exclusive to integrated suppliers. Community hospital interventional suites are adopting these platforms at accelerating pace as procurement committees prioritize total cost-per-procedure metrics. The resulting supplier landscape is fragmenting market share concentration and compressing pricing power for legacy incumbents.
EU Medical Device Regulation biocompatibility classification tightening is extending conformity assessment timelines for drug-device combination products. EMA notified body capacity bottlenecks are forcing manufacturers to front-load clinical evidence packages or risk launch delays. European commercial strategies are responding through parallel regulatory filings in Switzerland and the United Kingdom to circumvent MDR queue congestion.
Buyers are unbundling after-sales technical support from device procurement contracts, treating catheter training and procedure optimization as separate purchasing decisions. Specialized cancer centers are displacing bundled service agreements with à la carte education purchasing that prioritizes peer-to-peer proctoring over manufacturer field support. This behavioral shift is most pronounced in Germany and Japan where interventional radiology professional societies exert strong purchasing influence.
Transarterial Chemoembolization (TACE) Market Segmentation
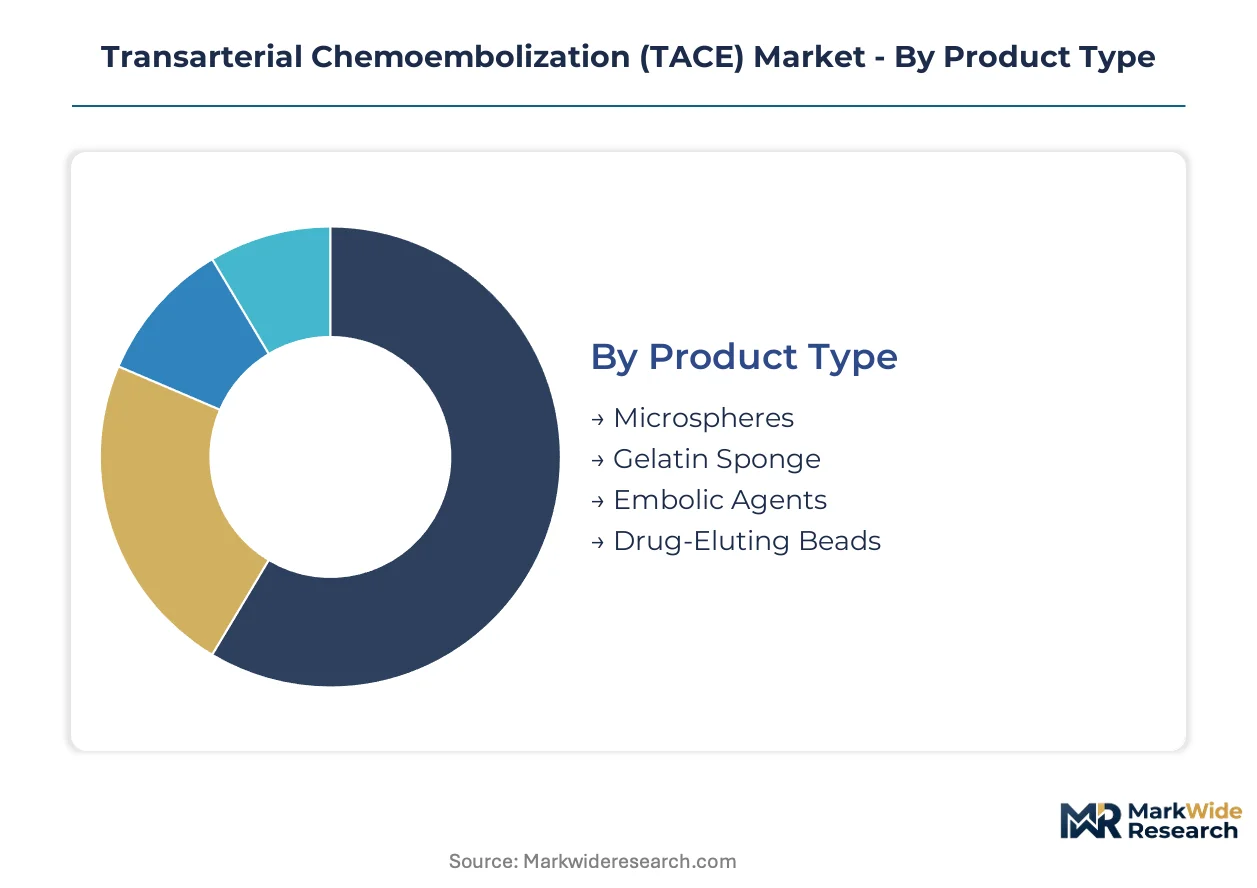
Segmentation in the TACE market reveals distinct procurement patterns across embolic technologies, clinical applications, and delivery infrastructure. Each dimension carries unique regulatory, reimbursement, and technical specifications that shape supplier selection and facility investment decisions.
Product Type:
FDA premarket notification pathways and EMA medical device regulation conformity assessments govern each embolic agent category differently, with drug-device combination classifications imposing stricter biocompatibility documentation on polymer-based platforms than conventional absorbable materials.
- Drug-Eluting Beads:Polymer-based calibrated microspheres engineered for precise doxorubicin loading and sustained release kinetics. Demand concentrates in tertiary hospital interventional radiology departments across the United States and Germany where premium reimbursement codes support acquisition costs; FDA breakthrough device designations for next-generation platforms are accelerating clinical validation timelines.
- Microspheres:Biocompatible spherical embolic agents manufactured through calibrated sizing processes to achieve uniform arterial occlusion. Specialized cancer centers in Japan are standardizing procurement around automated sizing specifications; PMDA Sakigake pathway incentives are compressing regulatory review periods for precision-manufactured variants.
- Gelatin Sponge:Absorbable embolic material derived from purified porcine collagen, traditionally prepared as manually cut fragments for intra-arterial deployment.
- Embolic Agents:Broad category encompassing particulate and liquid embolic materials including polyvinyl alcohol particles and ethylene vinyl alcohol copolymers.
Drug-eluting beads handle the majority of throughput in reimbursed markets; microspheres are gaining share fastest as manufacturing automation reduces batch-to-batch variability costs.
Application:
Clinical indication determines procedure complexity, imaging protocol requirements, and follow-up surveillance intensity, with hepatocellular carcinoma commanding the most standardized reimbursement pathways while emerging applications demand case-by-case prior authorization.
- Hepatocellular Carcinoma:Primary liver malignancy representing the dominant TACE indication under Barcelona Clinic Liver Cancer intermediate-stage staging protocols. United States oncology departments at academic medical centers are expanding procedure volumes as hub-and-spoke referral networks consolidate complex cases; Medicare reimbursement stability supports capital equipment investment for dedicated interventional suites.
- Liver Metastases:Secondary hepatic malignancies originating from colorectal, neuroendocrine, or other primary sites amenable to locoregional therapy. Specialized cancer centers in Germany are pioneering combination protocols with systemic immunotherapy; EMA accelerated assessment pathways for drug-eluting bead platforms are streamlining market access for metastatic indications.
- Bile Duct Tumors:Cholangiocarcinoma and perihilar malignancies requiring selective arterial targeting of biliary vasculature.
- Renal Cell Carcinoma:Kidney malignancies treated through segmental or subsegmental arterial embolization prior to nephrectomy or as palliative intervention.
Hepatocellular carcinoma absorbs the dominant share of procedure volume; liver metastases are climbing fastest as combination therapy protocols expand addressable patient populations.
End User:
Facility type determines capital intensity requirements, staffing models, and regulatory compliance scope, with OSHA chemotherapy waste handling mandates creating tiered barriers to entry across hospital-based versus clinic-based programs.
- Specialized Cancer Centers:Dedicated oncology institutions with integrated interventional radiology departments and comprehensive tumor board infrastructure. These facilities across Japan and Germany are displacing bundled manufacturer service agreements with à la carte education purchasing; professional society purchasing influence is strongest in this channel.
- Hospitals:General acute care institutions with interventional radiology capabilities embedded within broader surgical or diagnostic imaging departments. Tertiary hospitals in the United States are consolidating supplier relationships around calibrated embolic platforms; procurement committees prioritize total cost-per-procedure metrics over device acquisition price alone.
- Clinics:Outpatient-based interventional facilities requiring streamlined ventilation and waste disposal infrastructure for chemotherapy preparation.
- Research Institutions:Academic medical centers conducting clinical trials for novel embolic agents and combination therapy protocols.
Hospitals manage the largest installed base of TACE programs; specialized cancer centers are expanding most quickly as regional referral networks concentrate complex procedures.
Delivery Mode:
Technical approach to arterial access and embolic deployment determines catheter inventory requirements, operator training pathways, and compatibility constraints with installed base equipment.
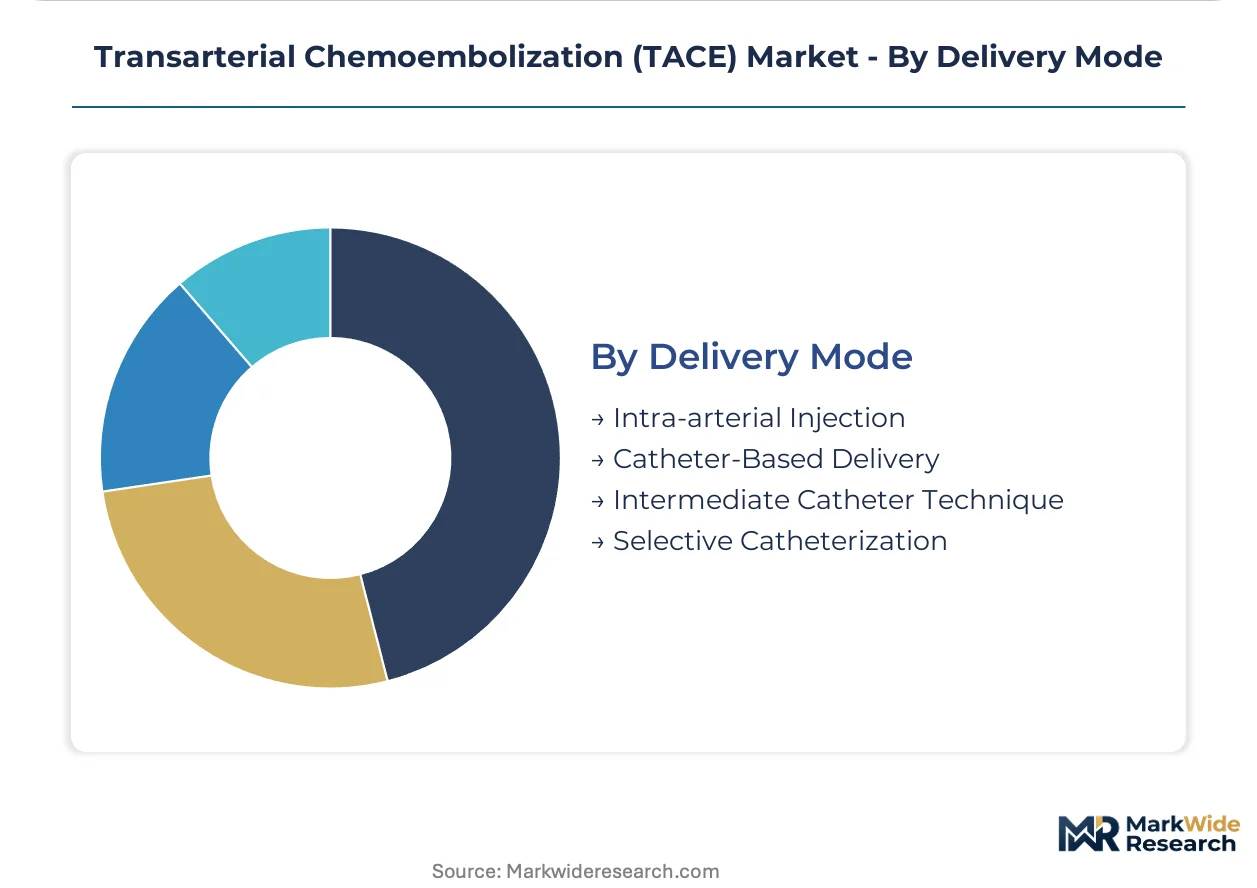
- Catheter-Based Delivery:Standard transfemoral arterial access utilizing diagnostic and selective catheters for hepatic artery cannulation. Community hospital interventional suites across the United States are adopting automated preparation platforms; compatibility with legacy catheter inventories is a decisive procurement criterion.
- Intermediate Catheter Technique:Advanced coaxial systems enabling superselective segmental and subsegmental arterial access for precision embolization. Demand concentrates in high-volume Japanese centers where PMDA reimbursement incentives reward procedure complexity; platinum-iridium alloy construction exposes programs to commodity input volatility.
- Intra-arterial Injection:Direct chemotherapeutic agent administration without calibrated embolic carrier.
- Selective Catheterization:Anatomically targeted arterial access minimizing non-tumor perfusion.
Catheter-based delivery handles the dominant procedure volume; intermediate catheter technique is expanding most quickly as training programs proliferate at specialized cancer centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibrated microsphere manufacturing clusters in the United States, Germany, and Japan supply the dominant share of drug-eluting bead platforms. Interventional radiology infrastructure density and reimbursement stability determine procurement velocity across major tertiary hospital networks.
United States
Medicare reimbursement codes for TACE procedures stabilize capital investment cycles at academic medical centers. FDA breakthrough device designations compress commercialization timelines for next-generation drug-eluting platforms. The Cleveland Clinic and MD Anderson anchor hub-and-spoke referral networks that concentrate complex hepatocellular carcinoma cases.
Germany
Specialized cancer centers in Bavaria and North Rhine-Westphalia displace bundled manufacturer service agreements with à la carte education purchasing. EMA accelerated assessment pathways streamline market access for combination therapy protocols. The University Hospital Heidelberg anchors clinical validation networks for metastatic liver disease applications.
Japan
PMDA Sakigake fast-track incentives reward procedure complexity at high-volume Kanto-region centers. METI reimbursement negotiations accelerate adoption of next-generation embolic platforms. The National Cancer Center Hospital in Tokyo standardizes intermediate catheter technique training across regional referral networks.
India
Private hospital capital expenditure programs in Maharashtra and Karnataka create first-mover advantages for calibrated bead suppliers. CDSCO regulatory harmonization initiatives reduce import clearance friction for polymer-based embolic agents. Apollo Hospitals in Chennai and Fortis in Delhi anchor interventional radiology expansion into tier-two cities.
Switzerland
Swissmedic parallel regulatory filings circumvent EU MDR queue congestion for novel drug-device combinations. University Hospital Zurich anchors cross-border referral networks serving hepatocellular carcinoma patients from neighboring EU member states. Basel-region pharmaceutical manufacturing clusters supply active pharmaceutical ingredients for doxorubicin-loading processes.
Transarterial Chemoembolization (TACE) Market Competitive Landscape
Concentration sits with integrated medical device conglomerates possessing captive microsphere manufacturing and catheter distribution infrastructure. Three to five multinational suppliers command premium positioning in reimbursed markets while regional fabricators compete on cost-optimized alternatives. Strategic archetypes span precision-calibrated platform specialists, diversified interventional portfolio holders, and pharmaceutical-device combination developers. Competitive moves center on M&A for manufacturing automation capabilities and strategic partnerships with specialized cancer centers for clinical validation.
Among diversified interventional portfolio holders, Cook Medical, Merit Medical Systems, and Boston Scientific occupy positions shaped by catheter lab relationships and embolic delivery system integration. Cook Medical exemplifies the precision-manufacturing archetype through calibrated microsphere production. Merit Medical Systems represents integrated platform bundling from preparation through deployment. Boston Scientific anchors intermediate catheter technique compatibility across its embolization portfolio. These three corporations collectively illustrate how North American infrastructure density shapes competitive positioning in reimbursed markets.
| Leading Market Players |
|---|
| Cook Medical |
| Merit Medical Systems, Inc. |
| Boston Scientific Corporation |
| Novartis AG |
| Pfizer Inc. |
| Terumo Corporation |
| Siemens Healthineers AG |
| Nippon Kayaku Co., Ltd. |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with calibrated microsphere manufacturers lock in supply access for tertiary hospital networks while anchoring price visibility against platinum-iridium alloy volatility. These arrangements concentrate procurement leverage among United States and German interventional radiology departments that command sufficient procedure volume to justify minimum order commitments.
Pricing Analysis
FDA breakthrough device designation pathways dictate the pricing tier structure across drug-eluting bead platforms, with designated products commanding premium positioning against conventional gelatin sponge alternatives. Three-tier pricing structure across premium, standard, and economy levels separates PMDA Sakigake-recognized platforms from CE-marked intermediates and unregulated commodity microspheres. Cost compression in the economy tier is intensifying because automated sizing technology enables smaller manufacturers to achieve batch-to-batch uniformity. Community hospital interventional suites exhibit the highest price sensitivity, while specialized cancer centers in Japan and Germany prioritize procedural reproducibility over acquisition cost.
Supply Chain Analysis
The United States, Germany, and Japan anchor calibrated microsphere manufacturing and intermediate catheter production for the TACE ecosystem. Polymer resin feedstocks for doxorubicin loading draw from Basel-region pharmaceutical clusters, while platinum-iridium alloy for catheter construction rests on South African and Russian mining output. Single-source vulnerability concentrates in automated sizing equipment for microsphere calibration, where two European suppliers control dominant market share. Distribution runs through interventional radiology GPO contracts and direct hospital system agreements, with specialized cancer centers increasingly unbundling technical support from device procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TACE market sits in early-cycle expansion as hub-and-spoke referral networks concentrate complex hepatocellular carcinoma cases at specialized cancer centers, amplifying procedure volume at high-throughput facilities beyond traditional hospital settings.
For Market Incumbents: Consolidate supplier relationships around captive microsphere manufacturing to defend against automated sizing technology enabling smaller competitors to achieve batch-to-batch uniformity. Deepen backward integration into polymer resin supply to offset commodity input volatility. Prioritize CE marking pathway investments to circumvent EU MDR queue congestion threatening European market access timelines. For New Entrants and Emerging Players: Lead with CDSCO regulatory harmonization initiatives in Maharashtra and Karnataka private hospital networks, where capital expenditure programs create first-mover advantages for calibrated bead suppliers. Target India's tier-two city expansion as the most penetrable geography, with Apollo Hospitals and Fortis anchoring interventional radiology infrastructure buildout. Pursue peer-to-peer proctoring partnerships over bundled manufacturer service agreements to align with German and Japanese professional society purchasing influence. For Investors and Strategic Acquirers: Automated sizing technology specialists with demonstrated batch-to-batch uniformity represent the highest-conviction acquisition archetype for medium-term value creation. The TACE market exhibits durable expansion characteristics across a 5-10 year window as intermediate-stage hepatocellular carcinoma incidence rises and interventional radiology fellowship programs slowly expand. Monitor PMDA reimbursement negotiation outcomes as the critical inflection indicator for next-generation drug-eluting platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited pathway compresses commercialization timelines for manufacturers demonstrating superior clinical endpoints. |
| CE Marking Pathway Investment | Front-loaded clinical evidence packages circumvent EMA notified body capacity bottlenecks delaying European entry. |
| Hospital System Partnership | Hub-and-spoke consolidation concentrates procedure volume at specialized cancer centers with integrated tumor board infrastructure. |
| Software Companion Development | Automated preparation platforms streamline catheter-based delivery compatibility with legacy interventional suite inventories. |
| Reimbursement Strategy | Medicare code stability and PMDA Sakigake incentives anchor capital investment cycles for dedicated TACE programs. |
Research Methodology
Desk research of FDA 510(k) filings, EMA medical device regulation conformity assessments, and hospital procurement databases preceded structured interviews with interventional radiologists, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement data, and SEC 10-K disclosures from publicly traded device manufacturers. Bottom-up procedure volume estimates triangulated against top-down market size calculations across the analysis window.
Variance decomposition across product type, application, end user, and delivery mode segmentation dimensions shaped the analytical framework. CAGRs were derived from log-linear trend fitting across the projection horizon, with hepatocellular carcinoma incidence trajectories and interventional radiology fellowship expansion rates serving as primary demand-side inputs. Supply-side constraints including platinum-iridium alloy availability and automated sizing equipment capacity informed elasticity assumptions.
Forecasts assume regulatory continuity in FDA premarket notification pathways and EU Medical Device Regulation implementation; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding reimbursement stability, procedural complexity training pipeline expansion, and chemotherapy waste handling compliance cost trajectories. Recalibration cycles align with material shifts in PMDA reimbursement negotiations, CDSCO harmonization milestones, and hub-and-spoke network consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Menopause Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Leprosy Treatment Market