
 Europe Alpha-Glucosidase Inhibitors Market | 2026-2036
Europe Alpha-Glucosidase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alpha-Glucosidase Inhibitors Market Foresight
Asset-light licensing and royalty-based partnerships are reshaping competitive dynamics in the Europe Alpha-Glucosidase Inhibitors Market, allowing mid-size firms to commercialize molecules without captive manufacturing. Bayer AG leverages its established European distribution infrastructure to sustain hospital formulary presence for acarbose across Germany and France. Takeda Pharmaceutical Company anchors its position through deep specialization in metabolic disease portfolios, while Sanofi competes via broad diabetes care integration that extends alpha-glucosidase inhibitor prescribing into combination therapy protocols.
Alpha-glucosidase inhibitors are oral antidiabetic agents that delay carbohydrate absorption in the small intestine by reversibly binding intestinal alpha-glucosidase enzymes, thereby flattening postprandial glucose excursions in type 2 diabetes patients. These agents functionally require administration with the first bite of each meal to achieve therapeutic enzyme inhibition at the brush border membrane. Among product types, acarbose occupies the largest installed base due to decades of clinical familiarity, while voglibose gains traction in markets prioritizing gastrointestinal tolerability profiles. The oral route of administration dominates prescribing patterns, though hospital settings remain the primary initiation point before patients transition to homecare channels with pharmacy-based refill systems.
EMA marketing authorization requirements and the EU MDR framework govern pharmaceutical quality, bioequivalence standards, and post-market surveillance for alpha-glucosidase inhibitors distributed across European member states. REACH and ECHA guidelines additionally influence excipient sourcing and manufacturing environmental compliance for active pharmaceutical ingredient production. National health technology assessment bodies in France, Germany, and Italy shape reimbursement access and pricing negotiations, creating heterogeneous market entry conditions. Stakeholders must monitor evolving EMA guidance on complex generic equivalence criteria and HTA body willingness-to-pay thresholds as biosimilar competition intensifies across European diabetes care pathways.
Market Dynamics
Hospital formulary integration of alpha-glucosidase inhibitors into combination diabetes protocols is restructuring prescribing authority across Western European health systems. The EU MDR post-market surveillance mandates are forcing manufacturers to rebuild pharmacovigilance infrastructure, compressing margins for generic oral antidiabetic producers.
Growth Catalysts
- EU MDR pharmacovigilance mandates:Enhanced post-market surveillance requirements are compelling manufacturers to invest in real-world evidence generation, creating competitive differentiation for compliant suppliers across Germany and France.
- Hospital-based combination therapy protocols:German, French, and Italian physicians are expanding acarbose co-prescription with SGLT2 inhibitors and GLP-1 receptor agonists to flatten postprandial glucose excursions.
- Brush-border enzyme targeting:Reversible intestinal alpha-glucosidase inhibition delivers meal-dependent glucose control without hypoglycemia risk, sustaining demand among elderly type 2 diabetes populations.
Market Restraints
- Starch hydrolysate excipient cost volatility:Fluctuating maize and wheat derivative prices squeeze formulation margins for oral alpha-glucosidase inhibitor production.
- Generic substitution pressure:Biosimilar competition and reference pricing mechanisms in Italy and Spain compress branded product reimbursement ceilings.
- Gastrointestinal tolerability ceiling:Flatulence and diarrhea incidence limits patient persistence, capping long-term adherence rates below other oral antidiabetic classes.
Strategic Opportunities
- Eastern European reimbursement expansion:Poland and Romania are building hospital diabetes care infrastructure where alpha-glucosidase inhibitor formulary inclusion remains underdeveloped.
- Homecare channel migration:Pharmacy-based refill systems for stable patients reduce hospital pharmacy dependency and capture margin from chronic therapy maintenance.
- EMA complex generic equivalence guidance:Evolving bioequivalence criteria for modified-release formulations create first-mover advantage for manufacturers with advanced pharmacokinetic modeling capabilities.
Industry Challenges
- Pharmacovigilance data science talent scarcity:EU MDR mandated signal detection and periodic safety update report automation requires specialized biostatisticians in short supply across European contract research organizations.
- Legacy health technology assessment dossier recompilation:France's HAS and Germany's IQWiG demand renewed cost-effectiveness evidence for combination therapy positioning, extending market access timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alpha-Glucosidase Inhibitors Market |
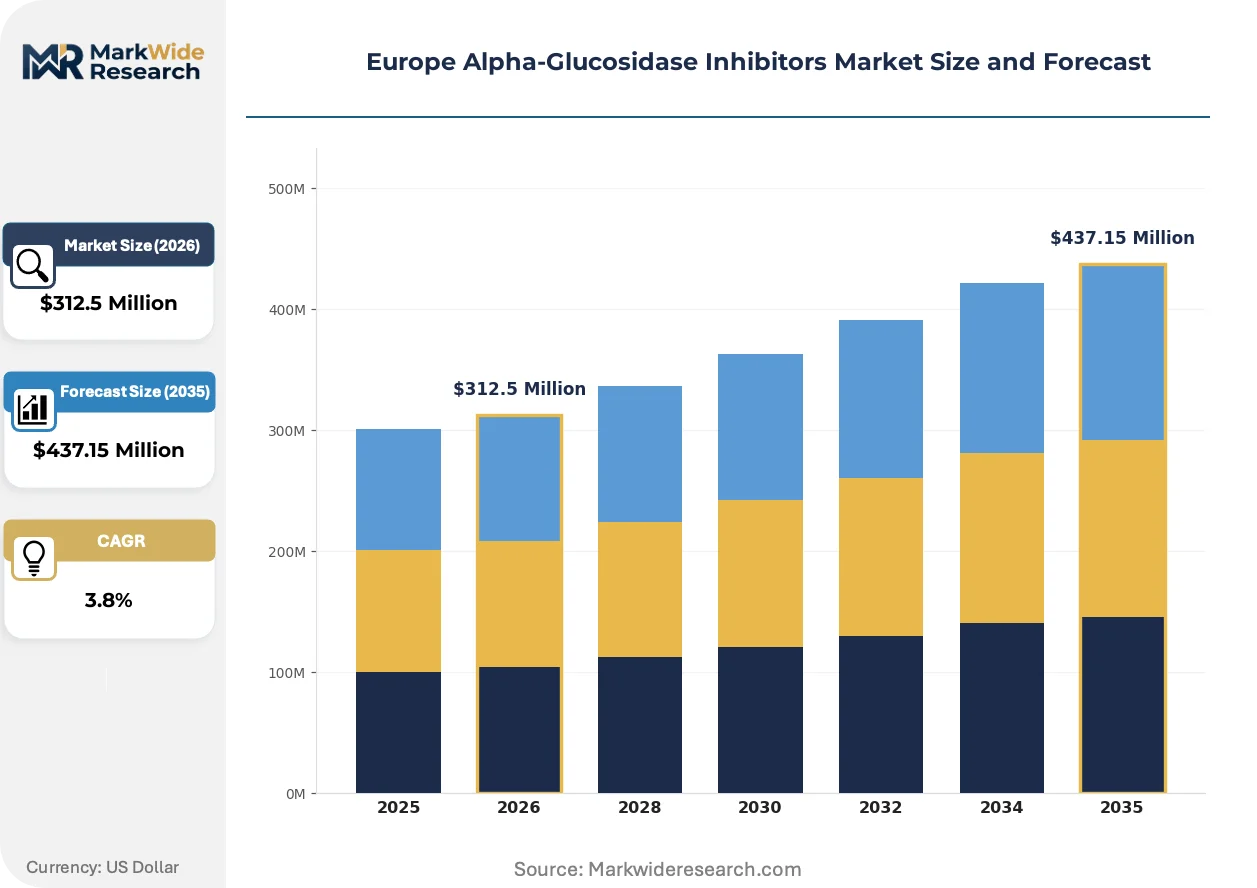
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $437.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acarbose, Miglitol, Voglibose, Others End User: Hospitals, Clinics, Homecare, Pharmacies Route of Administration: Oral, Injectable, Sublingual, Other Distribution Channel: Online, Offline, Wholesalers, Retailers |
| Companies Covered | Bayer AG, Takeda Pharmaceutical Company, Pfizer, Sun Pharma, Glenmark Pharmaceuticals, Merck & Co., Inc., Novartis AG, Sanofi, Hexal AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alpha-Glucosidase Inhibitors Market Shifts & Advancements
Alpha-glucosidase inhibitor commercialization is pivoting toward integrated diabetes care platforms rather than standalone molecule marketing. Manufacturers are embedding these agents into broader metabolic disease portfolios to capture hospital formulary preference.
Modified-release acarbose formulations are hybridizing immediate-release and extended-release pharmacokinetic profiles to reduce dosing frequency while maintaining postprandial glucose control. German hospital pharmacies are piloting these formulations for elderly polypharmacy patients. This technology is compressing the competitive gap between alpha-glucosidase inhibitors and newer oral antidiabetic classes on convenience metrics.
EMA's evolving guidance on complex generic equivalence is tightening bioequivalence study requirements for orally administered enzyme inhibitors. Manufacturers must now demonstrate brush-border membrane binding kinetics beyond traditional pharmacokinetic endpoints. French and Italian generic entrants are responding by investing in regional clinical trial infrastructure to satisfy national health technology assessment body evidentiary standards.
Hospital procurement consortia in Germany and France are consolidating oral antidiabetic purchasing through centralized tender mechanisms. Regional hospital alliances are displacing individual pharmacy negotiations, compressing price differentiation opportunities. This concentration is most visible in the Rhine-Ruhr and Île-de-France hospital networks where multi-year framework agreements now dominate alpha-glucosidase inhibitor sourcing.
Europe Alpha-Glucosidase Inhibitors Market Segmentation
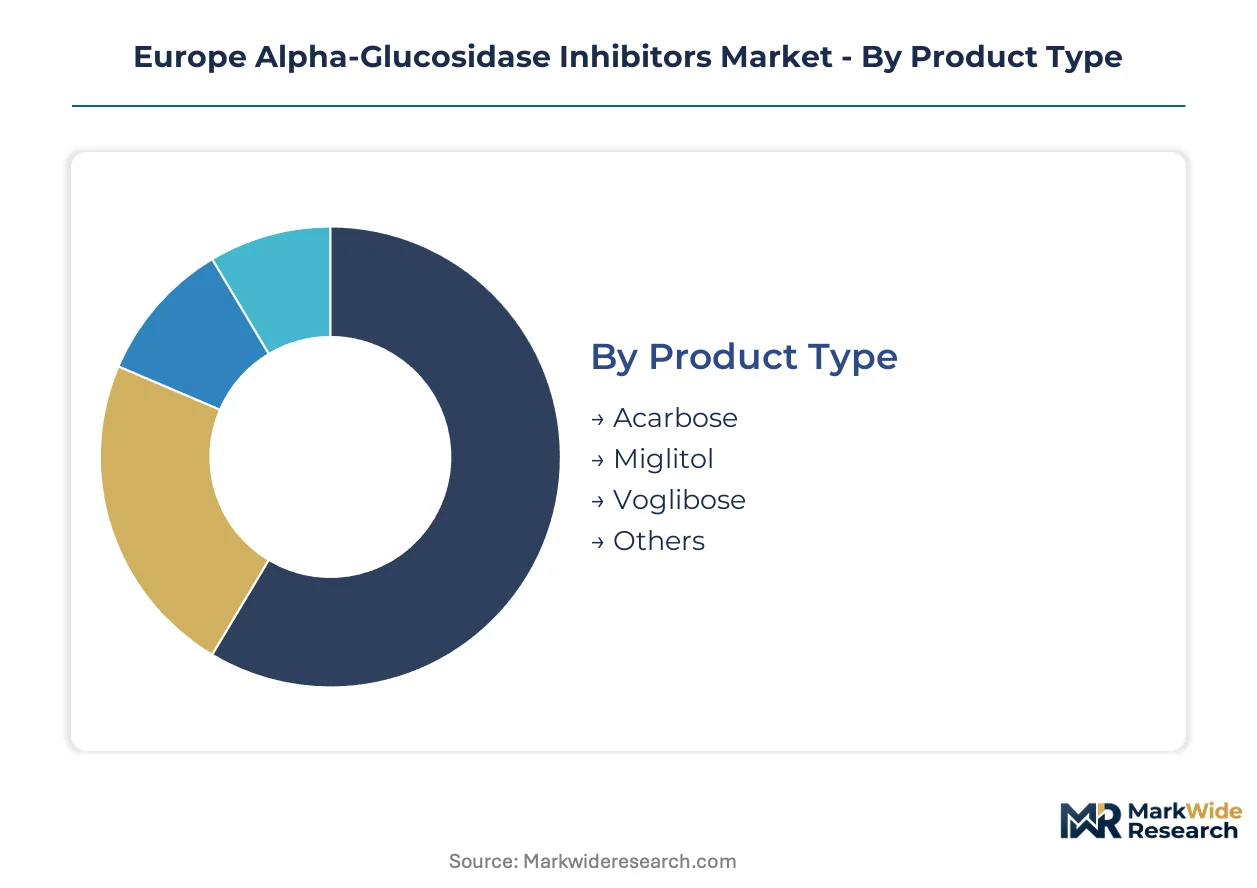
Segmentation of the Europe Alpha-Glucosidase Inhibitors Market reveals how prescribing authority, reimbursement pathways, and patient flow dynamics concentrate value across distinct commercial channels. Each dimension shapes competitive positioning differently for manufacturers navigating heterogeneous national health systems.
Product Type:
Cost tier stratification across molecular variants determines margin structures and formulary access depth within European hospital systems.
- Acarbose:Decades of clinical familiarity and extensive real-world safety data anchor hospital formulary preference across Germany and France. German physicians prescribe acarbose extensively in combination protocols with SGLT2 inhibitors for elderly type 2 diabetes populations requiring meal-dependent glucose control without hypoglycemia risk.
- Voglibose:Superior gastrointestinal tolerability profiles drive adoption in Italian and Spanish markets where patient persistence concerns constrain acarbose utilization. French hospital pharmacies increasingly stock voglibose for polypharmacy patients exhibiting flatulence intolerance to first-generation alpha-glucosidase inhibitors.
- Miglitol:Niche positioning in specialized metabolic clinics with specific absorption kinetics requirements.
- Others:Emerging modified-release formulations and combination molecules in early-stage EMA regulatory review.
Acarbose commands the established base. The steepest expansion runs through voglibose as tolerability-driven switching accelerates.
End User:
Application concentration determines where prescribing authority and procurement leverage reside across European diabetes care pathways.
- Hospitals:Primary initiation point for alpha-glucosidase inhibitor therapy where endocrinologists construct combination regimens integrating SGLT2 inhibitors and GLP-1 receptor agonists. German hospital formulary committees in Rhine-Ruhr networks negotiate multi-year framework agreements consolidating oral antidiabetic purchasing.
- Homecare:Pharmacy-based refill systems capture margin from stable patients transitioning from hospital initiation, reducing acute care dependency while maintaining therapy adherence through community-based monitoring.
- Clinics:Specialized diabetes centers in France and Italy managing complex metabolic cases requiring individualized dosing titration.
- Pharmacies:Dispensing infrastructure for chronic maintenance therapy with generic substitution protocols varying by national reimbursement rules.
Hospitals anchor the revenue concentration. Homecare channels are gaining share fastest as chronic disease management decentralizes.
Route of Administration:
Volume distribution across delivery mechanisms reflects patient convenience requirements and brush-border enzyme targeting pharmacology.
- Oral:Dominant administration route requiring first-bite dosing to achieve therapeutic intestinal alpha-glucosidase inhibition at the brush border membrane. Modified-release oral formulations under German hospital pharmacy pilot programs aim to reduce dosing frequency for elderly polypharmacy patients.
- Injectable:Minimal penetration given the functional requirement for meal-synchronized intestinal enzyme binding that oral delivery uniquely satisfies.
- Sublingual:Experimental formulations in early development seeking absorption profile alternatives.
- Other:Transdermal and buccal delivery research programs without commercial scale.
Oral administration holds absolute volume dominance. Injectable routes show negligible traction given mechanistic constraints.
Distribution Channel:
Customer type fragmentation across procurement mechanisms shapes price realization and margin compression exposure for manufacturers.
- Offline:Hospital procurement consortia and pharmacy wholesale networks handle the majority of alpha-glucosidase inhibitor volume. Île-de-France hospital alliances displace individual pharmacy negotiations through centralized tender mechanisms.
- Wholesalers:Regional distributors in Germany and Italy manage inventory logistics for hospital formulary replenishment and community pharmacy supply chains.
- Online:Emerging direct-to-patient platforms for chronic therapy refills in markets with relaxed pharmacy dispensing regulations.
- Retailers:Limited role given prescription requirements and reimbursement processing complexity.
Offline channels control the volume concentration. Wholesaler consolidation is accelerating fastest as regional procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement consortia and French HTA reimbursement frameworks are concentrating alpha-glucosidase inhibitor prescribing authority across Western European health systems. National health technology assessment bodies in Italy and Spain are tightening evidentiary standards for combination diabetes therapy positioning. Eastern European markets in Poland and Romania are building hospital infrastructure where formulary inclusion for oral antidiabetic agents remains underdeveloped.
Germany
Rhine-Ruhr hospital networks negotiate multi-year framework agreements consolidating oral antidiabetic purchasing through centralized tender mechanisms. The Federal Joint Committee (G-BA) evaluates cost-effectiveness evidence for combination therapy protocols integrating acarbose with SGLT2 inhibitors. Bavarian diabetes centers in Munich and Nuremberg pilot modified-release formulations for elderly polypharmacy patients requiring reduced dosing frequency.
France
Île-de-France hospital alliances displace individual pharmacy negotiations through regional procurement consortia covering Paris metropolitan diabetes care pathways. The Haute Autorité de Santé (HAS) demands renewed cost-effectiveness dossiers for alpha-glucosidase inhibitor positioning within combination regimens. Lyon and Marseille hospital formularies increasingly stock voglibose for patients exhibiting gastrointestinal intolerance to first-generation agents.
Italy
Lombardy and Veneto regional health systems prioritize voglibose adoption based on superior tolerability profiles that improve patient persistence in long-term diabetes management. The Italian Medicines Agency (AIFA) regulates pricing and reimbursement through reference mechanisms that compress branded product ceilings. Milan and Turin hospital pharmacies manage generic substitution protocols that accelerate biosimilar penetration in oral antidiabetic categories.
Spain
Catalonia and Madrid autonomous communities reference-price oral antidiabetic agents through regional procurement frameworks that intensify generic competition. The Spanish Agency for Medicines and Health Products (AEMPS) enforces EU MDR post-market surveillance requirements for pharmaceutical manufacturers distributing across Iberian markets. Barcelona hospital networks integrate alpha-glucosidase inhibitors into stepped-care protocols for type 2 diabetes patients with postprandial glucose control requirements.
Poland
Warsaw and Kraków hospital systems are expanding endocrinology departments where formulary inclusion for alpha-glucosidase inhibitors in combination regimens remains limited. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products (URPL) processes marketing authorizations for generic oral antidiabetic entrants seeking access to Central European reimbursement pathways. Polish diabetes care infrastructure investments are creating first-mover opportunities for manufacturers establishing hospital formulary relationships.
Europe Alpha-Glucosidase Inhibitors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital procurement and pharmacy distribution tiers. The European alpha-glucosidase inhibitor market structures around three archetypes: established pharmaceutical conglomerates with metabolic disease portfolios, mid-size generic manufacturers with regional manufacturing footprints, and licensing-focused firms leveraging asset-light commercialization models. M&A activity concentrates on acquiring regional distribution rights, while strategic partnerships target co-development of modified-release formulations.
Among established pharmaceutical conglomerates, Bayer AG and Takeda Pharmaceutical Company exemplify archetypes with deep European hospital formulary presence and specialized metabolic disease expertise. Sanofi occupies a position integrating alpha-glucosidase inhibitors into broad diabetes care platforms that extend prescribing into combination therapy protocols. These three companies represent contrasting approaches to sustaining market position—through distribution infrastructure depth, therapeutic area specialization, and portfolio integration respectively.
| Leading Market Players |
|---|
| Bayer AG |
| Takeda Pharmaceutical Company |
| Pfizer |
| Sun Pharma |
| Glenmark Pharmaceuticals |
| Merck & Co., Inc. |
| Novartis AG |
| Sanofi |
| Hexal AG |
| Others |
Supply & Pricing Matrix
Indian and Chinese API manufacturing concentration for acarbose and voglibose active pharmaceutical ingredients anchors cost structures that cascade through European formulation and packaging tiers, concentrating margin capture with upstream chemical suppliers while compressing downstream finished-product pricing power.
Pricing Analysis
EMA certification tiers and EU MDR compliance status create the primary spread between premium branded formulations and economy generic alternatives in European hospital procurement. Three-tier pricing structure across originator, complex generic, and commodity generic levels stratifies according to bioequivalence study sophistication and pharmacovigilance infrastructure depth. Cost compression in the commodity generic tier is intensifying because Italian and Spanish reference pricing mechanisms accelerate substitution protocols. Hospital procurement consortia in Germany exhibit lowest price sensitivity due to multi-year framework agreement security, while independent pharmacies in Eastern European markets demonstrate highest sensitivity to per-unit acquisition costs.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for starch hydrolysate excipient sourcing and alpha-glucosidase enzyme fermentation capacity. Active pharmaceutical ingredient production concentrates in India, China, and selected Eastern European contract manufacturing sites. Formulation draws from maize-derived excipients, specialized fermentation media, and brush-border membrane binding assay reagents. Single-source vulnerability in Chinese fermentation capacity for acarbose intermediates threatens supply continuity during geopolitical friction periods. Distribution runs through regional hospital procurement consortia and pharmaceutical wholesale networks with limited direct-to-hospital penetration by API manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment: EU MDR compliance infrastructure and EMA marketing authorization pathways create switching costs that protect established positions from rapid competitive displacement.
For Market Incumbents: Harden pharmacovigilance data science capabilities through specialized biostatistician recruitment and automated periodic safety update report systems to defend against EU MDR enforcement gaps that emerging generic entrants cannot bridge. Deepen backward integration into Indian API sourcing relationships to secure fermentation capacity commitments before Chinese supply uncertainty escalates. Channel control through hospital formulary committee relationships in Rhine-Ruhr and Île-de-France networks remains the critical defensive lever against biosimilar substitution.
For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian hospital diabetes care infrastructure where formulary inclusion for alpha-glucosidase inhibitors remains underdeveloped and incumbent relationships are weakest. Target voglibose positioning in Italian regional health systems where gastrointestinal tolerability advantages drive switching from acarbose among elderly polypharmacy populations. A go-to-market angle emphasizing modified-release formulation convenience for dosing frequency reduction captures physician attention in German Bavarian diabetes centers piloting adherence-improvement protocols.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-size generic manufacturers possessing EMA-approved acarbose dossiers but lacking hospital formulary sales infrastructure across France and Germany. The five-to-ten year viability window favors platforms with demonstrated EU MDR compliance automation and established health technology assessment body relationships. Acquisition target archetype: regional generic players with approved alpha-glucosidase inhibitor portfolios and underutilized pharmacovigilance infrastructure capable of scaling to combination therapy evidence generation. The signal to watch is HAS and IQWiG willingness-to-pay threshold recalibration for postprandial glucose control agents within SGLT2 inhibitor combination protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Release Formulation Development | Reduces dosing frequency for elderly polypharmacy patients in German hospital pilots. |
| EU MDR Pharmacovigilance Automation | Creates compliance differentiation that generic entrants cannot replicate across EMA member states. |
| Hospital Procurement Consortium Partnership | Secures multi-year framework agreements in Rhine-Ruhr and Île-de-France networks. |
| Eastern European Formulary Expansion | Captures first-mover advantage in Polish and Romanian hospital diabetes infrastructure buildout. |
| Health Technology Assessment Dossier Investment | Satisfies HAS and IQWiG cost-effectiveness demands for combination therapy positioning. |
Research Methodology
Cross-validation between formulary database analysis and hospital procurement record aggregation anchors the qualitative findings on prescribing authority shifts across German, French, and Italian health systems. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists were combined with secondary validation against EMA submission databases, ClinicalTrials.gov records, national health technology assessment body publications, and hospital formulary databases. Bottom-up patient flow modeling and top-down pharmaceutical expenditure tracking were triangulated to constrain estimation variance.
Calibration against historical pricing trajectories and volume shifts across the analysis window informed the analytical framework. Segmentation dimensions modeled include product type, end user channel, route of administration, and distribution mechanism, with additional stratification by national reimbursement pathway cluster. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and procurement consolidation patterns. Forecast inputs incorporated EU MDR implementation timelines, health technology assessment body evidentiary requirement evolution, and hospital procurement consortia expansion rates.
Stress conditions across API supply disruption, reimbursement ceiling compression, and biosimilar entry velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and procurement alliance formation speed. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Oral & Topical Anaesthetics Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Global HER2 Antibodies Market