
 Polyvinyl Chloride Resins Market | 2026-2036
Polyvinyl Chloride Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Chloride Resins Market Intelligence
Demand from the building and construction sector for pipes and fittings is hardening its majority share of the polyvinyl chloride resins market. This trend reinforces the material's foundational role in global infrastructure projects. Shin-Etsu Chemical leverages its vast manufacturing scale to serve Asian construction markets. In Europe, INEOS Group sustains a strong position through its integrated production facilities, while Westlake Corporation competes in North America by specializing in rigid PVC applications.
Polyvinyl Chloride (PVC) resin is a synthetic thermoplastic polymer created through the polymerization of vinyl chloride monomer. Its formulation can be modified with plasticizers to produce either rigid or flexible materials, prized for their durability and chemical resistance. Rigid PVC constitutes the largest product segment, driven by its use in pipes and fittings within the building and construction industry. Flexible PVC formulations, conversely, serve more specialized applications in healthcare and electrical insulation.
Market access and product composition are shaped by stringent chemical regulations. The European Union's REACH framework governs the use of plasticizers, while the US EPA sets emission standards for production facilities. In China, national GB standards dictate material safety for consumer and construction products. Future profitability depends on navigating these divergent regulatory landscapes while developing cost-effective, lower-carbon production pathways.
Market Dynamics
The polyvinyl chloride resins market is defined by a core tension between sustained, high-volume demand from the construction sector and intensifying regulatory pressure on chemical safety and environmental impact, particularly concerning plasticizers and end-of-life management.
Growth Catalysts
- Urban Infrastructure Expansion:Rapid urbanization in Southeast Asia and India continues to drive significant investment in water supply, sanitation, and electrical grids, creating foundational demand for PVC pipes, fittings, and cable insulation.
- Medical Grade Applications:The healthcare industry's requirement for sterile, durable, and chemically inert materials sustains demand for flexible PVC in applications such as intravenous bags, medical tubing, and dialysis equipment.
- Bio-Based Plasticizers:The development and commercialization of non-phthalate and bio-based plasticizers are enabling PVC products to meet stricter environmental health standards, opening access to previously restricted consumer and medical markets.
Market Restraints
- Feedstock Price Volatility:Production costs are directly tied to the fluctuating prices of ethylene and chlorine, the primary feedstocks for vinyl chloride monomer, creating margin pressure for resin manufacturers.
- Regulatory Restrictions:The European Union's REACH regulation imposes stringent controls on the use of specific phthalate plasticizers, requiring costly reformulation and certification for products sold within the EU market.
- Material Substitution:In residential plumbing and packaging, PVC faces competition from materials like cross-linked polyethylene (PEX), polypropylene (PP), and polyethylene terephthalate (PET), which are perceived as more flexible or easily recyclable.
Strategic Opportunities
- Advanced Formulation Development:Creating specialized PVC compounds with enhanced UV resistance, fire retardancy, and thermal stability opens opportunities in high-value sectors like automotive exteriors, window profiles, and specialty roofing membranes.
- Circular Economy Integration:Investing in advanced chemical and mechanical recycling technologies to process post-consumer PVC waste can create new revenue streams and meet policy mandates for recycled content.
- African Infrastructure Projects:Underpenetrated markets across Africa present long-term growth potential as nations build out foundational water, sanitation, and power infrastructure, requiring vast quantities of durable piping and wiring.
Industry Challenges
- Capital-Intensive Production:Modernizing or constructing PVC resin plants to comply with stringent air and water emission standards, such as those enforced by the US EPA, requires significant capital investment.
- Recycling Logistics:Establishing efficient collection and sorting systems for post-consumer PVC, especially from complex construction and demolition waste streams, remains a major logistical barrier to achieving higher recycling rates.
- Divergent Global Standards:Manufacturers must manage complex compliance requirements across different regions, navigating the differences between China's GB standards, European CE marking, and North American material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Chloride Resins Market |
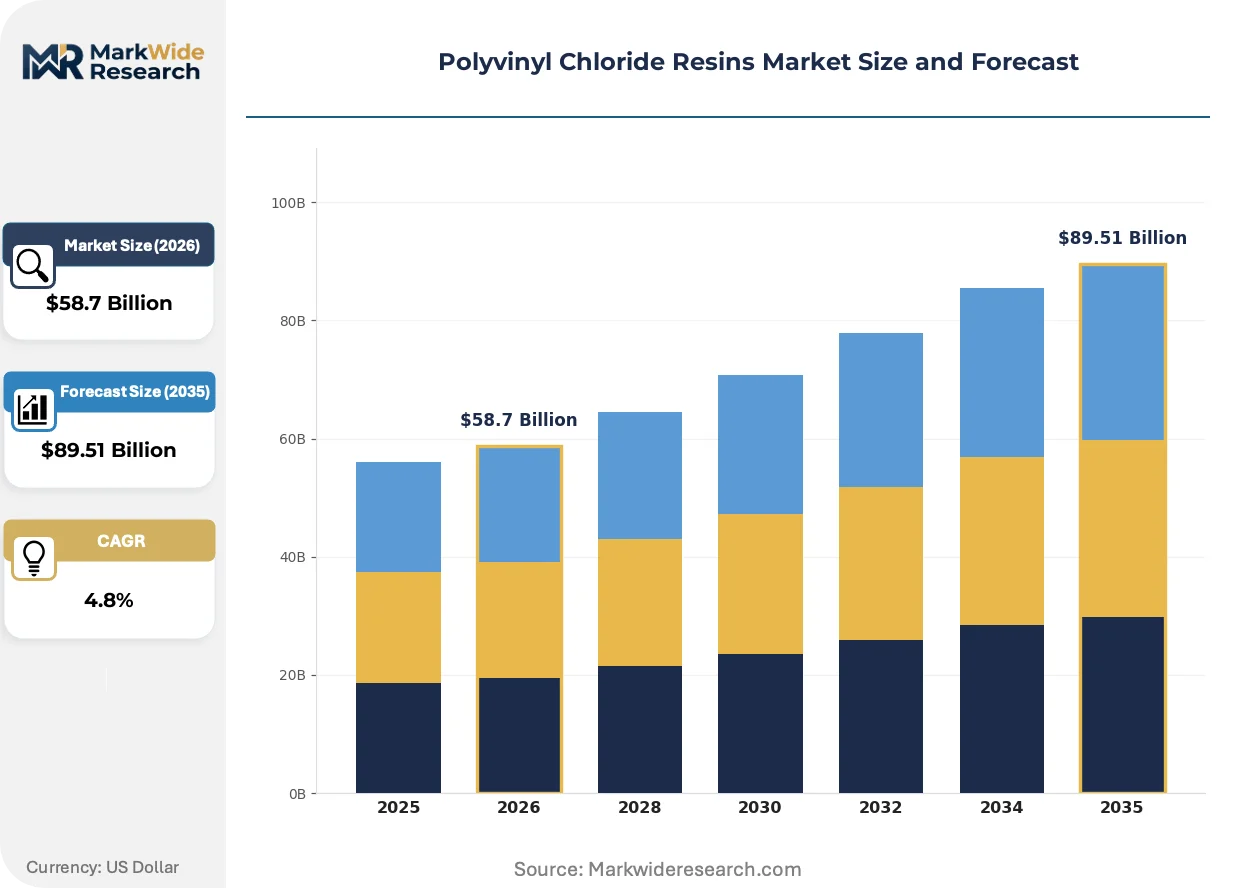
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, PVC Foam, PVC Compounds Application: Building & Construction, Consumer Goods, Healthcare, Electricals End Use Industry: Packaging, Automotive, Pipes & Fittings, Footwear Form: Powder, Granule, Paste, Sheet |
| Companies Covered | LG Chem, ChemChina, Shin-Etsu Chemical, Braskem, OxyChem, Westlake Corporation, INEOS Group, Mitsubishi Chemical Corporation, Formosa Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Chloride Resins Market Strategic Shifts & Innovations
Innovation in the polyvinyl chloride resins market centers on enhancing material properties to meet dual demands for higher performance and improved sustainability. These efforts are guided by evolving chemical regulations and a demand-side shift toward greater product transparency.
Advanced molecular compounding allows for precise control over polymer structure and additive integration. This technology is being adopted by manufacturers of specialized materials for sensitive applications like medical device components and automotive interiors. The process is unifying the historically separate objectives of flexibility and chemical inertness, resulting in materials that withstand demanding conditions without leaching additives.
The European Union’s Circular Economy Action Plan is compelling a systemic shift in the plastics value chain. This policy framework creates direct pressure to increase the use of recycled content in new PVC products and to design for easier disassembly and recovery. The building materials segment is most affected, prompting investment in chemical recycling processes that can convert old PVC back into virgin-quality raw materials.
A clear movement toward specification-driven purchasing is altering procurement dynamics away from decisions based solely on price. Buyers in the electronics and healthcare industries now frequently demand comprehensive data on chemical composition to verify compliance with standards like RoHS or specific biocompatibility tests. This trend is most pronounced in North American and European markets where regulatory oversight is most intense.
Polyvinyl Chloride Resins Market Segmentation
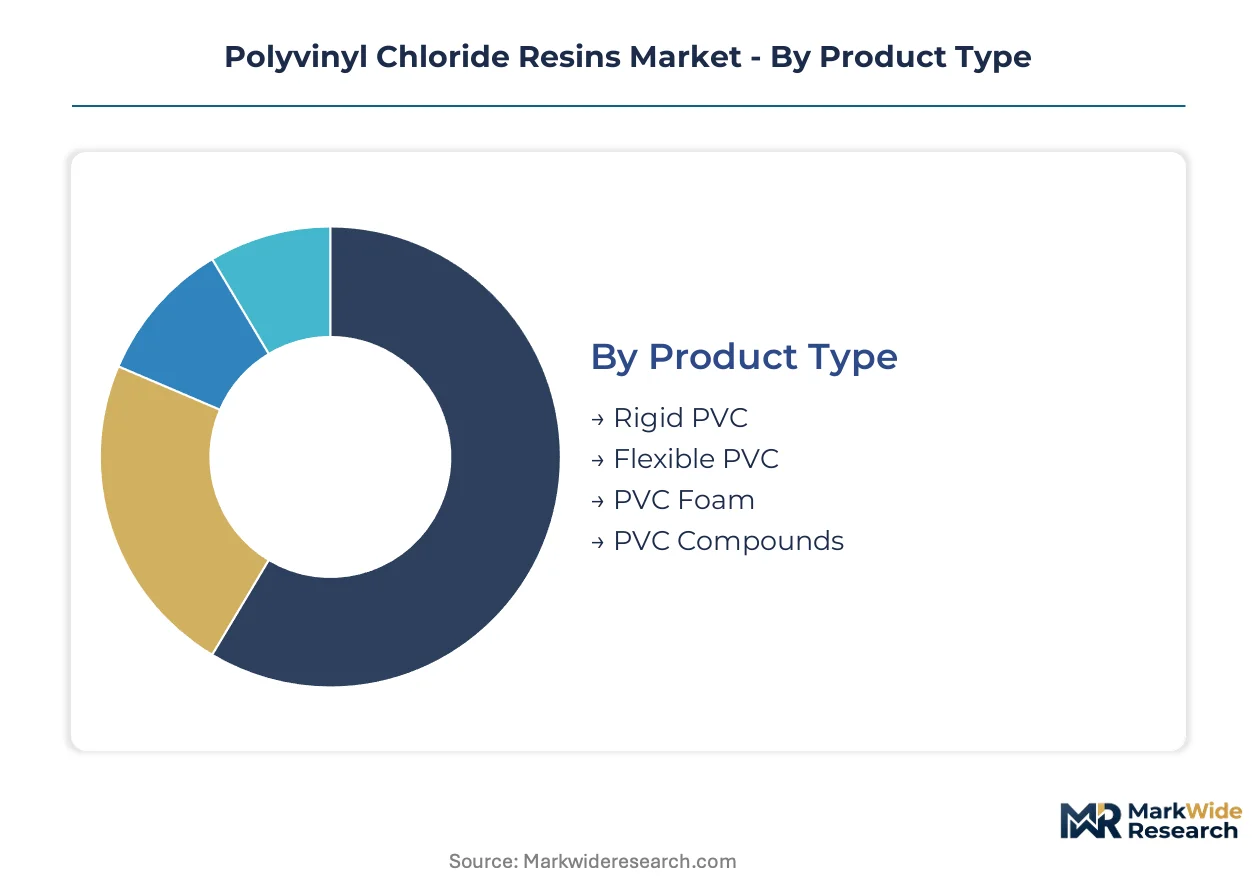
Understanding the polyvinyl chloride resins market through its distinct segments illuminates the diverse material specifications and end-use requirements driving demand. Different product forms and application areas dictate specific performance characteristics, influencing manufacturing processes and supply chain configurations. This granular view helps identify areas of concentrated demand and emerging opportunities across various industries.
Product Type:
The technical specifications of PVC resins determine their suitability for various manufacturing processes and final product performance.
- Rigid PVC:This unplasticized form of PVC offers high strength, stiffness, and chemical resistance, making it ideal for structural applications. Demand concentrates heavily in the building and construction sector for pipes and fittings, driven by ongoing infrastructure development in China and Southeast Asia.
- Flexible PVC:Created by adding plasticizers, this form exhibits elasticity, softness, and improved processability. It finds significant demand in specialized applications like medical tubing and electrical cable insulation, where pliability and chemical inertness are critical.
- PVC Foam:This lightweight, cellular PVC material provides excellent insulation and sound dampening. It is used in signage, displays, and some interior automotive components.
- PVC Compounds:These are custom blends of PVC resin with additives like stabilizers, lubricants, and pigments, tailored for specific processing and performance. They are crucial for specialized profiles.
Rigid PVC leads on scale; Flexible PVC leads on momentum.
Application:
The application landscape for polyvinyl chloride resins reflects the material's adaptability across numerous industrial and consumer uses.
- Building & Construction:This segment represents the largest consumer of PVC, utilizing the material for pipes, window profiles, roofing membranes, and flooring. Sustained urbanization and infrastructure investments, particularly in India and across Africa, underpin this foundational demand.
- Healthcare:Medical applications leverage flexible PVC for its sterility, biocompatibility, and chemical inertness in products such as IV bags, blood storage containers, and medical tubing. Stringent regulatory requirements for material safety drive continuous innovation in this specialized segment.
- Consumer Goods:PVC finds extensive use in products from toys and footwear to apparel and sports equipment. Its durability and cost-effectiveness make it a preferred material.
- Electricals:In the electrical sector, PVC is critical for wire and cable insulation due to its excellent dielectric properties and flame retardancy.
Building & Construction captures the dominant share; Healthcare applications are expanding most quickly.
End Use Industry:
Polyvinyl chloride resins serve a broad spectrum of end-use industries, each valuing specific material attributes for their products.
- Pipes & Fittings:This industry is a primary consumer of rigid PVC, manufacturing water supply, drainage, and electrical conduit systems. Global infrastructure projects and urban sanitation initiatives in emerging economies like India continue to drive high-volume demand.
- Packaging:PVC is utilized in various packaging formats, including blister packs, shrink wrap, and bottles, offering clarity and barrier properties. Regulatory pressure influences material choices.
- Automotive:In the automotive sector, PVC is used for interior trim, underbody coatings, and wire harnesses, valued for its durability and flame resistance.
- Footwear:PVC provides durable, water-resistant, and cost-effective material solutions for various footwear components, including soles and uppers.
Pipes & Fittings command the largest volume; Automotive applications are experiencing significant material innovation.
Form:
The physical forms of polyvinyl chloride resins dictate their processing methods and suitability for different manufacturing operations.
- Powder:PVC resin in powder form is the fundamental raw material for compounding and processes like calendering. This form requires further processing with additives.
- Granule:Granular PVC is widely used in extrusion and injection molding processes, offering excellent flow characteristics and consistent feeding into machinery. Its ease of handling makes it suitable for high-volume manufacturing.
- Paste:PVC paste, or plastisol, is a dispersion of fine PVC resin particles in a liquid plasticizer, used for coating and rotational molding.
- Sheet:PVC sheets are produced through calendering or extrusion and are used in applications such as vacuum forming, signage, and construction panels.
Granule form dominates processing efficiency; Paste form offers unique coating and molding capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese construction hubs drive significant polyvinyl chloride resins demand, underpinning global market growth. Urbanization projects and manufacturing expansion require vast quantities of PVC materials. This sustained activity influences production and consumption patterns across other major economies.
China
Ongoing infrastructure development and robust manufacturing activities in China create substantial demand for rigid PVC. The national GB standards dictate material safety for construction and consumer products. Major chemical producers in the Yangtze River Delta continue to scale production to meet this internal demand.
India
Rapid urbanization in India fuels extensive demand for PVC pipes and fittings in water supply and sanitation projects. The Bureau of Indian Standards (BIS) ensures product quality and safety for these critical applications. Chemical industrial zones in Gujarat are expanding capacities to serve the country's infrastructure needs.
United States
North American construction, particularly for residential and commercial buildings, sustains demand for rigid PVC window profiles and pipes. The US EPA sets emission standards for PVC production facilities, influencing manufacturing processes. Petrochemical complexes along the Gulf Coast remain central to domestic PVC resin output.
Germany
European markets, especially Germany, focus on high-performance PVC compounds for window frames and specialized construction. The EU's REACH framework imposes stringent controls on plasticizer use, driving formulation innovation. Integrated chemical sites in the Rhine-Ruhr region adapt production to meet these evolving regulatory demands.
Brazil
South American demand, particularly from Brazil, arises from significant investments in water infrastructure and affordable housing initiatives. The Brazilian Association of Technical Standards (ABNT) guides material specifications for PVC products. Major chemical manufacturers near São Paulo are expanding to capitalize on regional construction growth.
Polyvinyl Chloride Resins Market Key Industry Players
Capacity expansion dominates the current landscape of the polyvinyl chloride resins market. The industry exhibits a tiered structure, with a few global giants controlling significant production volumes alongside numerous regional specialists. This tiered structure fosters intense competition in bulk commodity segments while allowing for differentiation in specialty applications. Strategic archetypes include large integrated chemical producers and niche players focused on advanced formulations. Geographic expansion and technology licensing represent dominant competitive moves among market participants.
At the scale-driven end, Shin-Etsu Chemical exemplifies a global leader with vast manufacturing capabilities, particularly serving Asian construction markets. The INEOS Group, a European chemical conglomerate, occupies a strong position through its integrated production facilities across the region. Westlake Corporation, based in North America, represents a specialist focusing on rigid PVC applications, catering to regional demand for infrastructure materials. These companies anchor different geographical and product segments, collectively shaping the market's supply dynamics.
| Leading Market Players |
|---|
| LG Chem |
| ChemChina |
| Shin-Etsu Chemical |
| Braskem |
| OxyChem |
| Westlake Corporation |
| INEOS Group |
| Mitsubishi Chemical Corporation |
| Formosa Plastics Group |
| Others |
Cost & Logistics Intelligence
Specialized chemical engineering talent in the Yangtze River Delta impacts global PVC production costs, influencing pricing tiers across commodity and specialty grades. This labor-cost differential influences competitive positioning for high-volume producers, particularly those serving Asian markets.
Pricing Analysis
Fluctuating ethylene and chlorine prices directly impact PVC resin manufacturing costs, which producers pass through to buyers via contract-based long-term offtake agreements and commodity spot pricing for immediate needs. Price differentiation stems from product quality grade and regional certification levels, such as EU REACH compliance. Pricing softness in bulk commodity grades results from significant overcapacity in Asian markets. Building and construction companies exhibit high price sensitivity for pipes and fittings, while healthcare applications prioritize performance over cost.
Supply Chain Analysis
High logistics and freight costs for bulk PVC resins influence regional supply chain configurations, particularly impacting delivery to distant markets. Global supply concentrates in chemical production hubs across China, the United States, and Germany. The industry relies heavily on ethylene and chlorine as primary feedstocks. Commodity price volatility for these inputs represents a significant structural risk. Distribution primarily runs through direct sales channels to major industrial clients and specialized distributors serving smaller-volume, niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyvinyl chloride resins market is transitioning into a late-cycle quality story, driven by a demand shift towards premium specifications for medical-grade and high-performance building materials. Buyers increasingly prioritize certified, high-purity compounds over basic commodity resins.
For Market Incumbents: Acquire advanced recycling technologies to convert post-consumer PVC waste into virgin-quality raw materials, defending against regulatory pressure for recycled content. Incumbents should also optimize existing production facilities for lower-carbon pathways to meet evolving environmental standards. Investing in certification for non-phthalate and bio-based plasticizers helps mitigate the threat of EU REACH regulations. Controlling key intellectual property for specialized PVC compounds ensures market leadership.
For New Entrants and Emerging Players: Enter via strategic partnerships with local distributors in underpenetrated African infrastructure markets, targeting foundational water and sanitation projects. New entrants can also focus on developing specialized PVC compounds for high-value automotive exteriors, leveraging enhanced UV resistance. The most penetrable segment involves bio-based plasticizer formulations, offering a route to compliance-driven markets. A go-to-market angle involves collaborating with existing compounders to integrate novel additives.
For Investors and Strategic Acquirers: Chemical conglomerates are the most active acquirers in this space, seeking to consolidate market share and acquire specialized technologies. The polyvinyl chloride market demonstrates long-term viability over a 5-10 year window due to sustained demand in building, construction, and healthcare. Acquisition targets should be niche specialists focused on advanced PVC formulations or chemical recycling capabilities. The signal to watch is increased M&A activity centered on sustainable PVC solutions and bio-based plasticizer developers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Supports extensive demand for PVC pipes in water supply and sanitation projects across India. |
| Green Manufacturing Transition | Reduces environmental footprint and meets stricter emission standards imposed by regulators like the US EPA. |
| Advanced Recycling Technology Investment | Addresses policy mandates for recycled content, particularly within the European Union's Circular Economy Action Plan. |
| Bio-Based Plasticizer Development | Opens access to previously restricted consumer and medical markets by meeting stringent chemical safety regulations. |
| Long-term Supply Agreements with Automotive OEMs | Ensures stable demand for specialized PVC compounds in high-value automotive interior and exterior applications. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative market models — were reconciled to build a comprehensive view of the polyvinyl chloride resins market. This included conversations with plant managers, procurement leads at construction firms, R&D directors for PVC compounds, and regulatory affairs specialists. Secondary validation drew from customs/trade data, chemical industry association reports, national standards bodies, and company annual reports. A bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-use industry, form, and regional regulatory landscape. Compound annual growth rates were derived through a regression analysis of these key variables. Ethylene and chlorine price forecasts, alongside global infrastructure spending projections, served as critical forecast inputs.
Inputs from major chemical producers and national statistics agencies were available through the study window; gaps in real-time feedstock price data introduce uncertainty bands. Forecasts reflect assumptions regarding global economic stability and regulatory enforcement. Geopolitical tensions impacting feedstock supply or unforeseen regulatory shifts could revise these projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Concrete Containing Polymer Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Petroleum Resins Market