
 Asia-Pacific Polyamide Market | 2026-2036
Asia-Pacific Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyamide Market Insights
China's GB standards on industrial emissions and dual carbon goals is rebalancing capital allocation across the polyamide value chain. Shenma Industrial Co., Ltd leverages its captive adiponitrile capacity to anchor cost positions in PA66. Toray Industries, Inc. sustains technology leadership in high-performance PA6 and PA66 grades for automotive and electronics applications. BASF competes through its integrated Ludwigshafen-derived process know-how applied to Asian manufacturing assets.
Polyamide refers to a class of thermoplastic polymers containing repeating amide linkages, typically synthesized through condensation of diamines and dicarboxylic acids or ring-opening polymerization of lactams, with melt temperatures ranging from 220°C for PA6 to 265°C for PA66. These materials serve primarily as engineering plastics and synthetic fibers where strength, chemical resistance, and thermal stability are critical. PA6 dominates volume flows across the region due to lower feedstock sensitivity and broader processing latitude, while PA66 commands margin pools in automotive under-hood and electrical connector applications where thermal performance justifies premium positioning. Fibers and granules represent the most actively traded forms, with fiber-grade PA6 sustaining textile demand in Zhejiang and Jiangsu provinces while injection-molding granules penetrate automotive OEM supply chains.
China's MEE enforces wastewater and VOC thresholds that elevate environmental compliance costs for adipic acid and caprolactam producers. Japan's METI promotes recycled-content targets under its resource circulation framework, pressuring virgin polymer pricing in Japanese domestic markets. India's BIS certification requirements for engineering plastics in automotive safety components create non-tariff barriers for unqualified imports. Stakeholders must monitor feedstock cost trajectories and regulatory differentiation across Chinese provincial implementation of national standards to calibrate capacity commitments and product mix decisions.
Market Dynamics
China's dual carbon goals and tightening GB standards on industrial emissions are compressing feedstock availability while automotive OEMs in Shanghai and Zhejiang chemical clusters accelerate lightweight engine component specifications.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in China and India are specifying polyamide grades for under-hood components to meet fuel efficiency targets, pulling volume through injection-molding supply chains.
- MEE wastewater enforcement:China's Ministry of Ecology and Environment thresholds are accelerating capital deployment into closed-loop adipic acid systems that reduce environmental liability.
- Caprolactam process advances:New catalyst systems are lowering energy intensity in PA6 production, expanding margin pools for fiber-grade material serving Zhejiang textile operations.
Market Restraints
- Adiponitrile supply concentration:Captive production of this PA66 precursor concentrates among integrated petrochemical complexes, exposing non-integrated compounders to feedstock rationing during maintenance cycles.
- GB standard compliance costs:China's industrial emission specifications require VOC abatement equipment that elevates fixed costs for caprolactam producers serving eastern chemical clusters.
- Recycled-content substitution:Japan's METI resource circulation framework is elevating post-industrial polyamide recovery rates, pressuring virgin polymer pricing in domestic automotive applications.
Strategic Opportunities
- India BIS certification gaps:Engineering plastics for automotive safety components face non-tariff barriers that qualified domestic compounders can exploit ahead of import competitors.
- High-voltage connector grades:Electric vehicle platform architectures are creating specification windows for thermally stable PA66 in 800V charging infrastructure.
- Regional chemical cluster expansion:Zhejiang province infrastructure investments are enabling integrated caprolactam-to-fiber operations that compress logistics costs for export-oriented textile producers.
Industry Challenges
- Specialized polymer engineering talent:Formulation expertise for high-performance automotive grades concentrates among experienced technologists, constraining new entrant scale-up timelines.
- Multi-standard certification complexity:Concurrent compliance with China's GB standards, Japan's JIS specifications, and India's BIS requirements fragments quality management systems for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyamide Market |
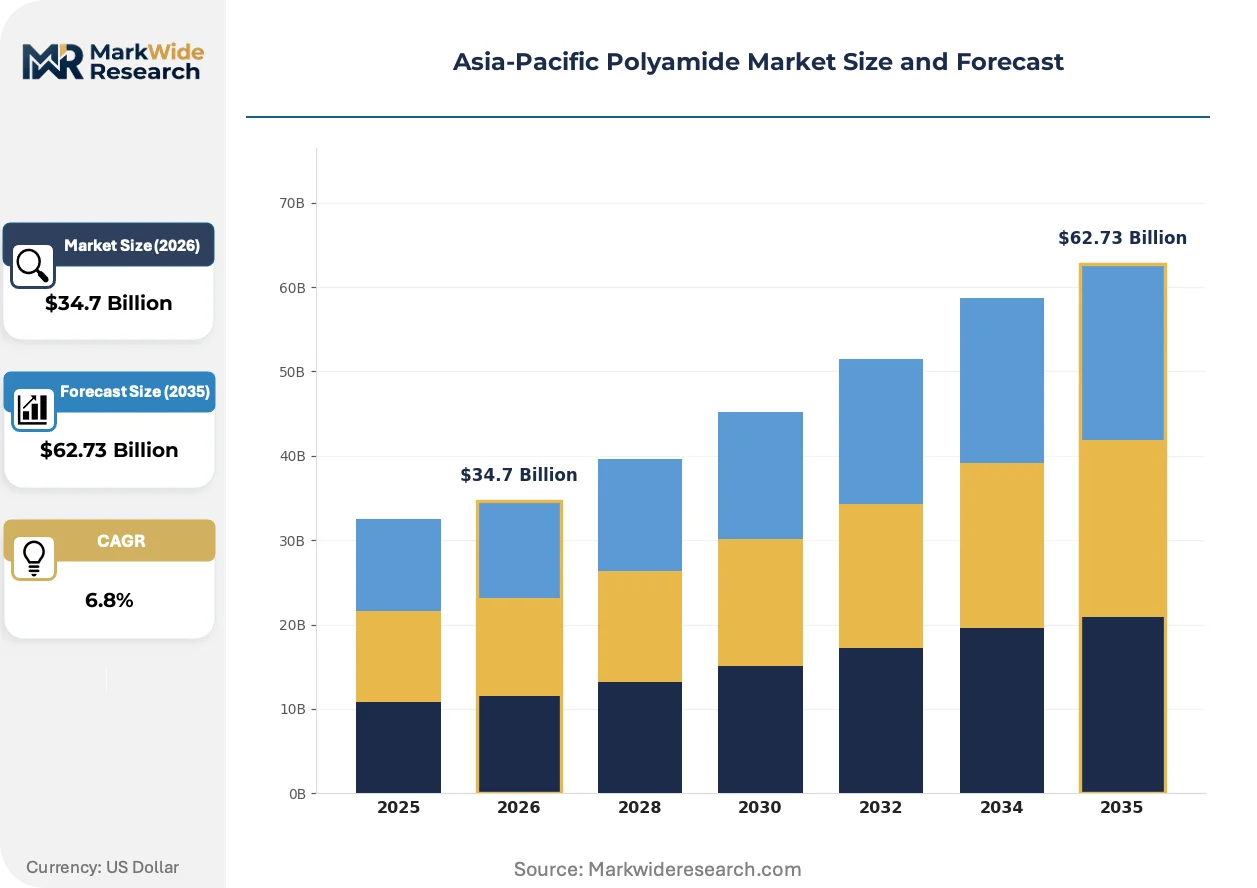
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
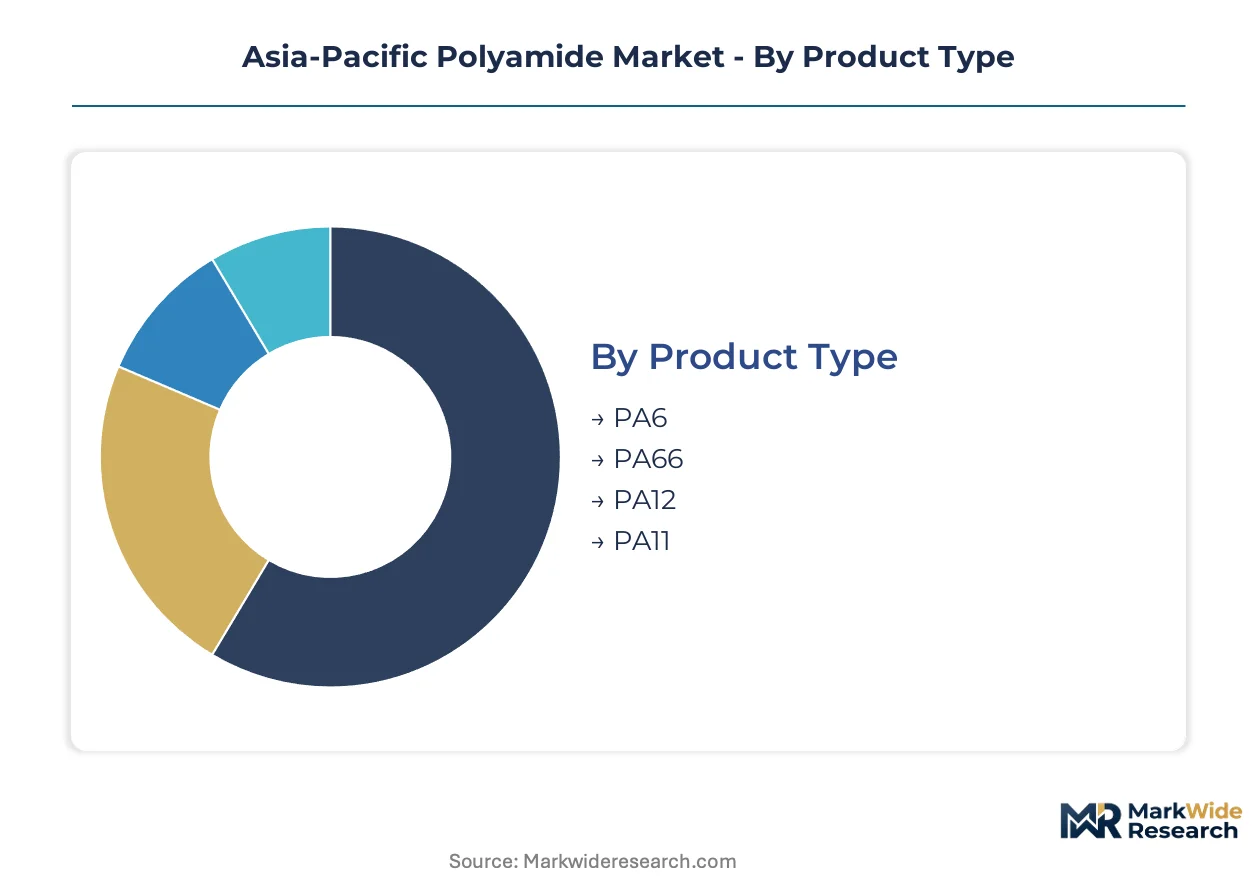
| Segmentation | Product Type: PA6, PA66, PA12, PA11 Application: Automotive, Textiles, Electronics, Packaging End User: OEMs, Aerospace, Construction, Consumer Goods Form: Granules, Sheets, Fibers, Films |
| Companies Covered | Toray Industries, Inc., Mitsui Chemicals, Inc, Shenma Industrial Co., Ltd, Formosa Plastics Corporation, Asahi Kasei Corporation, Guangdong Xinhui Meida Nylon Co., Ltd., UBE Corporation, BASF, Highsun Holding Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyamide Market Trends and Innovations
Bio-based feedstock pathways and closed-loop recycling infrastructure are reconfiguring raw material sourcing strategies across the polyamide value chain, while digital process control systems compress quality variance in high-specification automotive grades.
Advanced catalyst systems for caprolactam production are unifying energy efficiency with product consistency. Toray Industries and regional compounders in Jiangsu province are deploying these systems to serve automotive OEMs demanding tighter molecular weight distribution. This technology convergence is unifying cost positions across PA6 producers previously segmented by feedstock access.
China's GB 31571 standard on pollutant emissions from petroleum chemical industries is mandating real-time monitoring of wastewater discharge. Caprolactam producers in Shanghai chemical parks are retrofitting biological treatment capacity to avoid production halts. Fiber-grade operations in Zhejiang face the steepest compliance cost escalation due to higher water intensity in textile-grade polymer finishing.
Automotive OEM procurement teams are consolidating supplier panels and demanding compounder-held inventory at assembly plant proximity. Tier-1 suppliers in India and Thailand are replacing spot-market resin purchases with consignment arrangements. This shift is most visible in southern India, where Hyundai and Kia operations are qualifying local compounders for just-in-sequence delivery of under-hood components.
Asia-Pacific Polyamide Market Segmentation
Polyamide procurement decisions across the Asia-Pacific region hinge on thermal performance thresholds, regulatory compliance burdens, and supply chain proximity to chemical clusters. Understanding how buyers prioritize these factors across product grades, applications, and delivery forms reveals where margin pools concentrate and where commoditization pressures dominate.
Product Type:
Buyers select polyamide grades based on melt temperature requirements, feedstock cost exposure, and the regulatory burden of precursor chemical handling.
- PA6:Synthesized via ring-opening polymerization of caprolactam with melt temperatures near 220°C, this grade dominates volume flows across Zhejiang textile operations and automotive injection-molding supply chains due to lower feedstock sensitivity and broader processing latitude. Jiangsu province compounders leverage PA6's cost position to serve Hyundai and Kia procurement panels in southern India.
- PA66:Condensation polymerization of adipic acid and hexamethylenediamine yields melt temperatures around 265°C, commanding premium positioning in Shanghai automotive clusters where under-hood thermal performance justifies higher procurement costs. Shenma Industrial's captive adiponitrile capacity anchors domestic Chinese supply security for this grade.
- PA12:Long-chain aliphatic structure delivers superior moisture resistance and dimensional stability for electrical connector applications in Japan's automotive electronics tier.
- PA11:Bio-based castor oil feedstock pathway attracts sustainability-focused OEMs in Thailand and Malaysia seeking reduced Scope 3 emissions in interior component specifications.
PA6 leads on scale; PA66 leads on momentum as electric vehicle thermal management requirements intensify.
Application:
End-use specifications fragment the market by performance certification requirements and proximity to assembly operations.
- Automotive:Under-hood components, electrical connectors, and structural parts demand flame-retardant grades meeting China's GB standards on material emissions. Shanghai and Zhejiang chemical clusters concentrate injection-molding capacity to serve just-in-sequence delivery requirements from Hyundai, Kia, and domestic Chinese OEMs.
- Textiles:Fiber-grade PA6 sustains woven and knitted fabric production across Zhejiang and Jiangsu provinces, with water-intensive finishing operations facing steep MEE wastewater compliance cost escalation.
- Electronics:High-voltage connector specifications for 800V charging infrastructure create demand windows for thermally stable PA66 grades in Japan and South Korea.
- Packaging:Film and barrier layer applications concentrate in Southeast Asian converting operations serving regional food and industrial packaging demand.
Automotive applications command the steepest expansion trajectory; textiles maintain the largest installed consumption base.
End User:
Procurement scale and certification burden vary sharply across buyer categories, with regulatory qualification requirements creating divergent market access conditions.
- OEMs:Automotive original equipment manufacturers in China and India consolidate supplier panels and demand compounder-held inventory at assembly plant proximity, replacing spot-market resin purchases with consignment arrangements.
- Aerospace:High-performance grades for interior and structural components face stringent flame-smoke-toxicity specifications, with qualification timelines constraining supplier rotation.
- Construction:Reinforced grades for cable ties, fasteners, and insulation penetrate infrastructure projects across India and Southeast Asia where BIS and local certification requirements vary by state.
- Consumer Goods:Appliance housings, power tool components, and sporting equipment drive steady demand for standard-grade PA6 through distributor channels.
OEMs dominate procurement scale; aerospace commands the highest specification premiums.
Form:
Logistics configuration and processing equipment compatibility determine form selection, with inventory carrying costs and handling characteristics influencing buyer preferences.
- Granules:Standard pellet form for injection molding and extrusion dominates automotive and industrial procurement, with bulk silo deliveries compressing per-kilogram logistics costs for high-volume compounders.
- Sheets:Extruded plate and slab stock serve machining operations and thermoforming applications in industrial equipment and prototyping workflows.
- Fibers:Continuous filament and staple forms feed textile spinning operations in Zhejiang chemical parks, with fiber-grade specifications demanding tighter molecular weight distribution control.
- Films:Biaxially oriented and cast film structures penetrate flexible packaging and industrial barrier applications across Southeast Asian converting clusters.
Granules lead on procurement volume; fibers face the most concentrated geographic demand pattern.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyamide engineering talent and production infrastructure concentrate in eastern Chinese chemical clusters, with specialized compounders and fiber operations anchoring supply security across automotive and textile value chains.
China
Automotive OEMs in Shanghai and Zhejiang provinces specify PA66 grades for under-hood thermal management while GB 31571 emission standards force caprolactam producers into wastewater retrofit investments. MEE enforcement elevates environmental compliance costs for adipic acid operations serving eastern chemical parks.
India
Hyundai and Kia procurement panels in Tamil Nadu and Karnataka states drive qualified compounder expansion for just-in-sequence delivery of lightweight engine components. BIS certification requirements for automotive safety plastics create non-tariff barriers that domestic compounders exploit against import competition.
Japan
METI resource circulation frameworks elevate post-industrial polyamide recovery rates, pressuring virgin polymer pricing in domestic automotive electronics applications. High-voltage connector specifications for 800V EV infrastructure create demand windows for thermally stable grades.
South Korea
Automotive tier suppliers around Busan-Ulsan industrial corridors consolidate resin procurement through consignment arrangements replacing spot-market purchases. Electric vehicle platform architectures pull specification-grade PA66 through qualified compounder networks.
Thailand
Sustainability-focused OEMs specify bio-based PA11 for interior component applications to reduce Scope 3 emissions reporting burdens. Southeast Asian packaging converters sustain steady demand for film-grade materials serving regional food and industrial barrier applications.
Asia-Pacific Polyamide Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive adiponitrile or caprolactam capacity. Market concentration reflects feedstock access advantages rather than formulation differentiation alone. Three archetypes dominate: integrated upstream producers controlling precursor supply, regional compounders serving qualified automotive tiers, and fiber-grade specialists anchored to textile chemical parks. Capacity expansion and strategic partnerships constitute the dominant competitive moves as stakeholders secure qualified supply positions ahead of OEM panel consolidation.
Among Japan-based industrial conglomerates, Toray Industries, Inc. and Mitsui Chemicals, Inc occupy positions exemplifying technology leadership in high-performance grades. Chinese integrated producers including Shenma Industrial Co., Ltd anchor cost-competitive supply through captive feedstock infrastructure. European-headquartered BASF competes through process know-how transfer to Asian manufacturing assets, representing the multinational technology-licensing archetype.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Mitsui Chemicals, Inc |
| Shenma Industrial Co., Ltd |
| Formosa Plastics Corporation |
| Asahi Kasei Corporation |
| Guangdong Xinhui Meida Nylon Co., Ltd. |
| UBE Corporation |
| BASF |
| Highsun Holding Group |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in eastern Chinese chemical clusters anchor feedstock security through captive caprolactam and adiponitrile capacity, compressing procurement costs for integrated compounders while forcing non-integrated competitors into spot-market vulnerability. This ownership pattern tightens pricing discipline across PA6 and PA66 grades as state-supported entities absorb margin compression that would destabilize privately held operators.
Pricing Analysis
Contract-based long-term offtake agreements dominate high-volume automotive procurement, while spot-market transactions persist for fiber-grade PA6 serving Zhejiang textile operations. Price differentiation rests on certification grade—BIS-qualified automotive safety compounds command substantial premiums over standard industrial grades—and volume scale, with OEM consignment arrangements locking in annual volume commitments. Pricing pressure stems from Japan's METI resource circulation framework elevating post-industrial polyamide recovery rates and pressuring virgin polymer margins. Tier-1 automotive suppliers exhibit lowest price sensitivity due to qualification timelines and just-in-sequence delivery requirements, while packaging converters and consumer goods distributors remain highly sensitive to resin cost fluctuations.
Supply Chain Analysis
Regional distribution centers in Shanghai and Zhejiang chemical parks compress logistics costs for automotive compounders serving Hyundai and Kia operations in southern India. Geographic supply concentrates in China, Japan, and South Korea, with Chinese integrated producers controlling caprolactam flows and Japanese specialists anchoring high-performance PA66 grades. Raw material dependencies center on benzene-derived cyclohexane for caprolactam, butadiene-based adiponitrile for PA66, and castor oil feedstocks for bio-based PA11. Single-source vulnerability concentrates in adiponitrile, where Shenma Industrial's captive capacity dominates domestic Chinese supply. Distribution runs through qualified compounder networks holding consignment inventory at OEM assembly plant proximity, replacing traditional distributor channels in automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific polyamide market reads as a late-cycle quality story, with electric vehicle thermal management requirements and 800V charging infrastructure specifications pulling demand toward premium PA66 grades with tighter molecular weight distribution control.
For Market Incumbents: Lock in qualified supply positions ahead of OEM panel consolidation by securing BIS certification for automotive safety compounds in India and investing in closed-loop adipic acid systems that reduce MEE environmental liability. Defend margin pools through backward integration into caprolactam or adiponitrile precursors, as feedstock rationing during maintenance cycles exposes non-integrated compounders to production halts. Prioritize formulation expertise retention as specialized polymer engineering talent concentrates among experienced technologists. For New Entrants and Emerging Players: Domestic Indian compounders face exploitable gaps in BIS-qualified automotive safety plastics as Hyundai and Kia procurement panels consolidate supplier bases around qualified local producers. Southeast Asian packaging converters present penetrable white-space for film-grade PA6 and PA66 materials serving regional food and industrial barrier applications. Establish go-to-market positioning through technical service partnerships with regional distributors rather than direct OEM qualification, compressing time-to-revenue while building formulation credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders with qualified automotive positions but limited feedstock integration, as margin compression from virgin polymer pricing pressure and recycled-content substitution creates distressed entry points. Long-term viability favors assets with demonstrated BIS, GB, or JIS certification portfolios and proximity to Zhejiang or Shanghai chemical clusters. Monitor electric vehicle platform architecture announcements as the critical inflection signal—800V charging infrastructure qualification timelines will determine which compounders capture specification-grade PA66 volume pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Shenma Industrial's captive capacity anchors cost positions in PA66 grades for under-hood thermal management. |
| BIS Certification Investment | Domestic Indian compounders exploit non-tariff barriers against import competitors in automotive safety plastics. |
| Closed-Loop Recycling Infrastructure | Japan's METI resource circulation framework elevates post-industrial recovery rates and pressures virgin polymer pricing. |
| Regional Distribution Center Expansion | Zhejiang province infrastructure investments compress logistics costs for export-oriented textile producers. |
| High-Voltage Connector Grade Development | Electric vehicle 800V charging architectures create specification windows for thermally stable PA66 compounds. |
Research Methodology
Multiple input streams—structured interviews with polyamide plant managers and OEM procurement leads, customs and trade flow databases, and SEC filings from integrated petrochemical conglomerates—were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged technical R&D directors at Japanese high-performance grade specialists, distribution channel partners in Zhejiang chemical parks, and Tier-1 supplier procurement teams at Hyundai and Kia operations in Tamil Nadu. Secondary validation drew from China Customs import-export statistics, ACC and Cefic chemical industry reports, and MEE regulatory filings on wastewater discharge compliance.
Cross-referencing historical capacity utilization patterns against panel input from compounder executives and automotive platform engineers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, and regional production hub classification. CAGRs were derived through trend extrapolation of feedstock cost trajectories and regulatory compliance cost escalation, with electric vehicle penetration rates and GB standard implementation timelines serving as industry-specific forecast inputs.
Inputs from MEE enforcement records and BIS certification databases were available through the study window; gaps in real-time adiponitrile spot pricing and provincial-level VOC abatement cost disclosures introduce uncertainty bands around margin compression estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Polyol Esters Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Water-Borne Resins Market