
 Norway Lubricants Market | 2026-2036
Norway Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Lubricants Market Analytics
Aftermarket technical services and fluid analysis programs is tilting margin pools away from bulk product sales toward lifecycle contracts. Shell PLC leverages its integrated supply chain to dominate offshore logistics channels along the Norwegian coast. FUCHS sustains R&D intensity in biodegradable formulations tailored to aquaculture and hydropower applications. TotalEnergies SE anchors its position through direct technical service partnerships with Statoil-operated platforms.
Lubricants are formulated mixtures of base oils and additives engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from ISO VG 32 to ISO VG 680 for industrial applications and SAE 0W-16 to SAE 60 for automotive engines. Their primary commercial purpose is extending machinery operational life while reducing energy consumption and maintenance intervals in high-load environments. Engine oils command the largest revenue share within product type categories due to fleet density and drain-interval compression, while biodegradable grades represent the fastest-expanding segment as Norwegian aquaculture and hydropower operators face tightening discharge permits. Synthetic lubricants carry premium positioning in marine applications where cold-start reliability and extended service life offset higher unit costs.
The Norwegian Environment Agency enforces REACH-aligned substance restrictions and waste-oil recovery mandates that elevate compliance costs for mineral-based formulations. The EU Green Deal's carbon-border adjustment mechanisms and Norway's EEA adoption of CSRD reporting standards are pushing industrial buyers toward lower-carbon lubricant procurement criteria. Stakeholders must monitor how the EU AI Act's predictive maintenance requirements reshape fluid-condition monitoring contracts and service bundling strategies.
Market Dynamics
The Norwegian lubricants sector is pivoting toward lifecycle service contracts as Statoil-operated platforms and aquaculture fleets demand predictive fluid management rather than transactional bulk purchases. This structural shift compresses traditional product margins while elevating technical service revenues.
Growth Catalysts
- EU F-Gas Regulation amendments:Tightening discharge permits for industrial fluids are forcing mineral-oil users toward synthetic and biodegradable alternatives in offshore drilling operations.
- North Sea equipment life extension:Subsea drilling contractors are prioritizing high-performance synthetics to reduce unplanned maintenance in corrosive deepwater environments.
- Stavanger-Bergen maintenance hub concentration:Clustering of marine logistics fleets and subsea service vessels is creating localized demand density for specialized lubricant distribution.
Market Restraints
- Base oil supply concentration:Dependence on Group III and PAO imports from Northwestern European refiners exposes Norwegian blenders to feedstock volatility and currency fluctuation risk.
- REACH compliance cost escalation:ECHA substance notification requirements and waste-oil recovery mandates impose disproportionate burdens on small-scale mineral-oil distributors.
- Extended drain interval technology:Synthetic formulations lasting 2-3x longer than conventional oils are structurally compressing volume demand in mature fleet segments.
Strategic Opportunities
- CSRD-aligned procurement criteria:Norwegian EEA adoption of EU corporate sustainability reporting standards is creating preference premiums for lubricants with verified carbon footprints.
- Aquaculture biodegradable penetration:Salmon farming operators around Bergen face tightening discharge permits that favor vegetable-based hydraulic fluids in net-pen equipment.
- AI Act predictive maintenance convergence:EU-mandated condition monitoring systems are opening service contracts integrating sensor hardware with fluid analysis programs.
Industry Challenges
- Tribology-specialist scarcity:Norwegian technical universities produce insufficient lubricant formulation chemists to staff expanding R&D programs at domestic blenders.
- Offshore certification timelines:NORSOK standard compliance for subsea applications requires 18-24 month validation cycles that delay new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Lubricants Market |
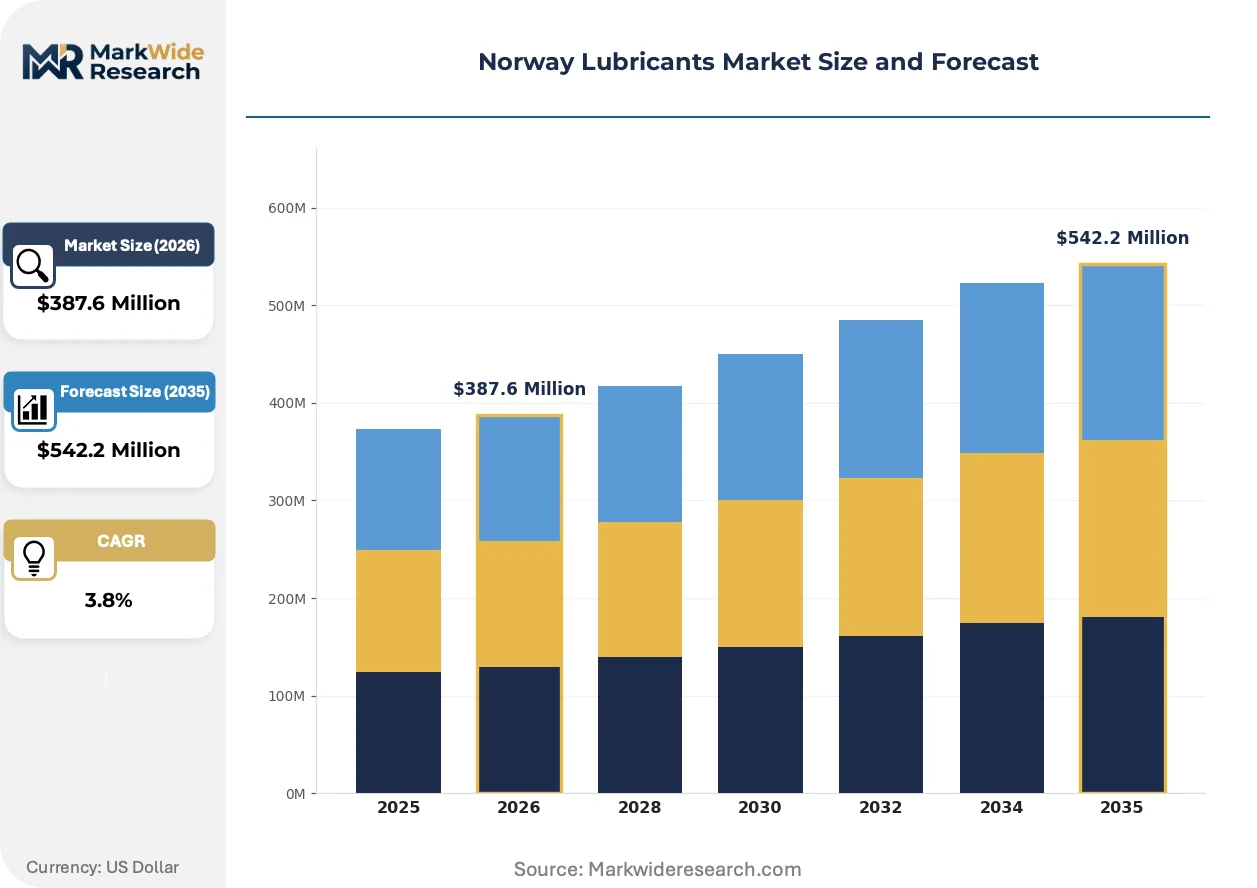
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $542.2 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Hydraulic Fluids, Gear Oils, Greases End User: Automotive Sector, Industrial Machinery, Marine Applications, Construction Grade: Mineral, Synthetic, Semi-Synthetic, Biodegradable Application: Automotive, Manufacturing, Oil & Gas, Power Generation |
| Companies Covered | TotalEnergies SE, Chevron Corporation, Shell PLC, PETRONAS Lubricants International, Valvoline Inc., ExxonMobil Corporation, BP PLC, Gulf Oil International, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Lubricants Market Evolving Landscape
Synthetic-biodegradable hybrid formulations are disrupting conventional mineral-oil dominance as Norwegian industrial buyers face overlapping regulatory and operational pressures. Three convergent developments are reshaping competitive positioning.
Polyalkylene glycol (PAG) and ester-based biodegradable base stocks are hybridizing with synthetic mineral oils to deliver cold-flow performance in North Sea marine applications without sacrificing aquatic toxicity profiles. Offshore supply vessel operators in Bergen are piloting these formulations for stern tube and deck machinery lubrication. The hybridization is compressing demand for single-attribute conventional products while expanding the addressable premium segment.
Norway's alignment with EU F-Gas Regulation amendments is accelerating refrigerant-lubricant compatibility testing for industrial heat pumps and offshore HVAC systems. The Norwegian Environment Agency enforces substance restrictions that disqualify mineral oils in new equipment warranties. Hydropower turbine operators are responding by specifying POE lubricants in generator cooling circuits to preempt compliance-driven retrofit costs.
Fluid analysis programs are displacing fixed-interval drain practices among Stavanger-based drilling contractors seeking to optimize helicopter logistics and platform inventory. Condition-based maintenance contracts bundle sensor deployment with laboratory testing services. This behavioral shift is most pronounced in subsea BOP control systems where unplanned failure costs dwarf preventive service expenditures.
Norway Lubricants Market Segmentation
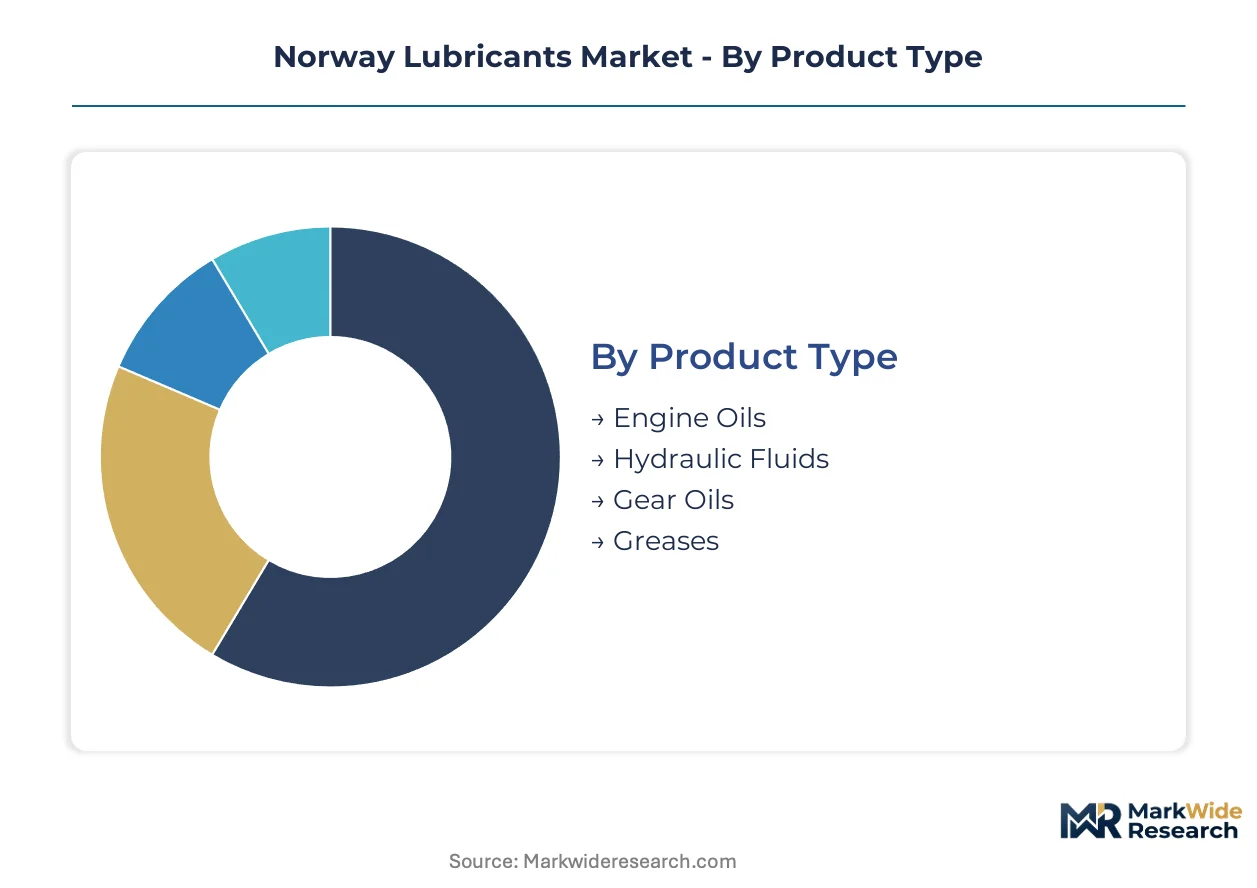
Segmentation in the Norwegian lubricants market reveals how regulatory pressure and operational specialization fragment demand across incompatible technical specifications. Each dimension exposes different margin structures and service bundling opportunities.
Product Type:
Engine oils dominate volume throughput while hydraulic fluids capture premium positioning in subsea applications.
- Engine Oils:Formulated with Group II/III base stocks and detergent-dispersant additive packages meeting ACEA C3 and API SP specifications. Demand concentrates in Oslo's commercial fleet maintenance corridors where drain interval compression drives higher-value synthetic uptake.
- Hydraulic Fluids:ISO VG 32-68 viscosity grades with anti-wear and oxidation stability additives for high-pressure systems. Norwegian aquaculture operators around Bergen specify biodegradable ester-based formulations to satisfy discharge permit conditions.
- Gear Oils:Extreme-pressure additives protect hypoid and helical gear sets in marine propulsion and wind turbine drivetrains.
- Greases:Thickener-stabilized lubricants for rolling-element bearings in offshore platform cranes and subsea connectors.
Established volume favors engine oils; emerging adoption favors hydraulic fluids.
End User:
Marine applications command the steepest price premiums while automotive delivers scale efficiency.
- Automotive Sector:Passenger car and commercial vehicle service fill and aftermarket replacement. Oslo-Stavanger highway corridor fleets generate concentrated demand for long-drain synthetics.
- Industrial Machinery:Manufacturing equipment, material handling systems, and process industry rotating machinery.
- Marine Applications:Deep-sea vessels, offshore supply boats, and subsea equipment operating in corrosive North Sea conditions. NORSOK-standard compliance requirements extend procurement cycles and elevate technical service bundling.
- Construction:Earthmoving equipment and mobile cranes facing intermittent duty cycles and contamination exposure.
Marine applications generate the highest service attach rates; automotive provides the broadest distribution footprint.
Grade:
Grade selection in Norway tracks regulatory stringency more closely than cost optimization.
- Mineral:Refined petroleum base stocks with additive packages for standard-duty applications. REACH compliance costs and waste-oil recovery mandates compress margins for independent distributors.
- Synthetic:PAO, PAG, and ester base stocks delivering thermal stability and extended service intervals. North Sea platform operators prioritize these formulations to reduce helicopter logistics for offshore maintenance.
- Semi-Synthetic:Blended mineral-synthetic formulations balancing performance upgrade against price sensitivity in mid-tier fleet segments.
- Biodegradable:Vegetable oil and synthetic ester bases with aquatic toxicity certification for aquaculture and hydropower discharge environments.
Synthetics anchor offshore procurement; biodegradable grades are climbing fastest under EU F-Gas alignment.
Application:
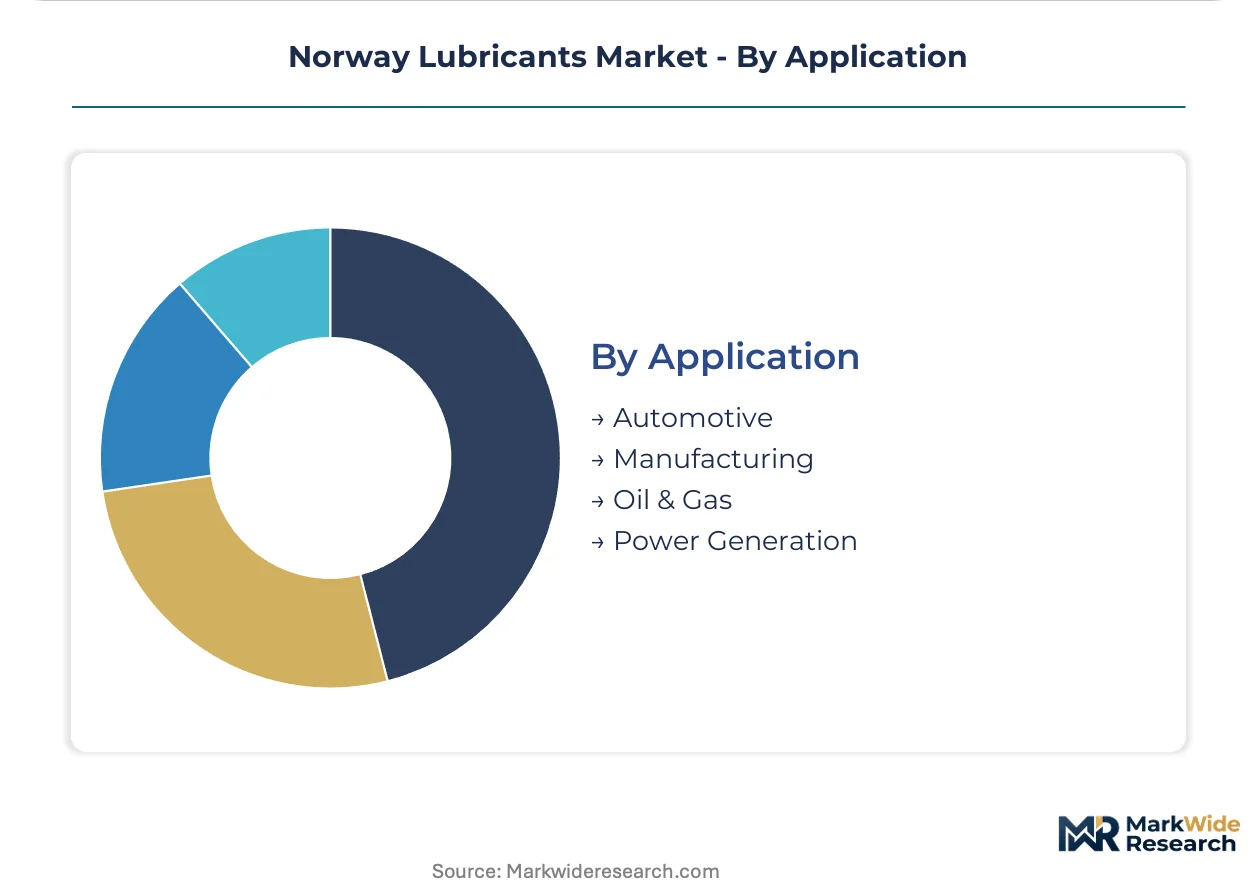
Application-based segmentation exposes divergent certification requirements and channel structures.
- Automotive:Light-duty and heavy-duty vehicle lubrication with OEM warranty compliance specifications.
- Manufacturing:Metalworking fluids, compressor oils, and general machinery lubrication in process industries.
- Oil & Gas:Drilling mud lubricants, subsea production system fluids, and pipeline corrosion inhibitors. Stavanger-based contractors specify products validated through 18-24 month NORSOK certification timelines.
- Power Generation:Hydropower turbine oils and generator cooling circuit lubricants. Norwegian hydropower operators specify POE formulations to preempt refrigerant-lubricant compatibility retrofit costs under tightening F-Gas amendments.
Oil & gas commands the longest sales cycles; power generation is gaining share fastest on decarbonization procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Norway's sub-regions. Aquaculture operators around Bergen exhibit high price sensitivity on standard hydraulic fluids, while Statoil-linked offshore contractors in Stavanger absorb premium synthetics without volume reduction.
Stavanger
North Sea drilling contractors drive synthetic lubricant procurement for subsea BOP systems and platform machinery. The Norwegian Environment Agency enforces REACH-aligned discharge permits that disqualify mineral oils in new equipment warranties. Local maintenance hubs concentrate technical service contracts integrating fluid analysis with helicopter logistics optimization.
Bergen
Salmon farming operators specify biodegradable hydraulic fluids for net-pen equipment under tightening aquaculture discharge regulations. EU F-Gas Regulation amendments accelerate refrigerant-lubricant compatibility testing for industrial heat pumps. Marine supply vessel fleets pilot PAG-ester hybrid formulations for stern tube applications.
Oslo
Commercial fleet corridors along the E18 highway generate concentrated demand for long-drain synthetic engine oils. The Norwegian Public Roads Administration enforces Euro 6 emission standards that elevate ACEA C3 specification requirements. Urban service centers compress drain intervals through predictive maintenance programs.
Trondheim
Hydropower turbine operators specify POE lubricants in generator cooling circuits to preempt refrigerant compatibility retrofit costs. The Norwegian Water Resources and Energy Directorate mandates environmental discharge assessments for lubricant selection. Regional utilities cluster procurement through cooperative purchasing agreements.
Tromsø
Arctic fishing vessel fleets prioritize cold-flow synthetic formulations for deck machinery in sub-zero operating conditions. Norwegian Maritime Authority safety inspections elevate technical documentation requirements for lubricant certification. Remote port logistics constrain inventory holding, favoring consolidated supplier relationships.
Norway Lubricants Market Competitive Landscape
Capability concentration sits with integrated majors possessing offshore certification infrastructure; scale advantage sits with global blenders leveraging feedstock purchasing power. The Norwegian market structures around three archetypes: vertically integrated oil majors with platform-direct service networks, specialized lubricant formulators with biodegradable R&D depth, and regional distributors with Stavanger-Bergen logistics density. Dominant competitive moves include lifecycle contract bundling that displaces transactional bulk sales, and NORSOK validation investments that extend product commercialization timelines.
Within the integrated major tier, Shell PLC and TotalEnergies SE exemplify offshore-direct positioning through technical service partnerships with Statoil-operated platforms. FUCHS occupies a position representing specialized formulator archetype, with R&D intensity directed toward aquaculture and hydropower biodegradable applications. These three anchors illustrate how certification depth and service bundling separate premium-tier competitors from commodity distributors.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Chevron Corporation |
| Shell PLC |
| PETRONAS Lubricants International |
| Valvoline Inc. |
| ExxonMobil Corporation |
| BP PLC |
| Gulf Oil International |
| FUCHS |
| Others |
Value Network & Pricing Analysis
Northwestern European refinery clusters in Rotterdam and Antwerp anchor feedstock pricing power for Norwegian blenders, with Group III and PAO base oil availability directly conditioning margin structures across the Stavanger-Bergen corridor. Their capacity utilization swings transmit into landed cost volatility that domestic formulators must absorb or pass through to offshore contractors.
Pricing Analysis
Lifecycle technical service contracts now drive lifetime value capture, displacing transactional bulk product margins with recurring fluid analysis and predictive maintenance revenues. Pricing stratifies across NORSOK-certified premium synthetics, REACH-compliant standard mineral formulations, and economy-grade automotive service fills. Cost compression in mineral-oil segments is intensifying because ECHA substance notification requirements and waste-oil recovery mandates disproportionately burden independent distributors. Aquaculture operators around Bergen exhibit highest price sensitivity on standard hydraulic fluids, while Statoil-linked offshore contractors in Stavanger absorb premium synthetics without volume reduction.
Supply Chain Analysis
EU dual-use export controls on advanced synthetic base stock manufacturing technology constrain technology transfer to non-EEA blenders, preserving competitive advantage for established European formulators. Supply concentrates in Germany, Belgium, and the Netherlands for Group III and PAO base oils; Norway draws from these hubs for 80% of feedstock requirements. Raw material dependencies center on ethylene oxide for PAG synthesis, alpha-olefin feedstocks for PAO production, and vegetable oil esters for biodegradable grades. Single-source vulnerability runs through Rotterdam-Antwerp logistics corridors where congestion or regulatory delays cascade into Norwegian inventory shortages. Distribution runs through Stavanger-Bergen maintenance hubs with helicopter logistics integration for offshore platform delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norwegian lubricants sector functions as a service-attach opportunity where fluid analysis programs and condition-based maintenance contracts expand recurring revenue faster than underlying product volume. This structural shift rewards competitors who bundle technical services with hardware procurement.
For Market Incumbents: Insulate margin pools by deepening NORSOK certification infrastructure to extend validation timelines that block fast-follower entry, while consolidating channel control through exclusive helicopter logistics partnerships with Stavanger-based offshore contractors. Synthetic-biodegradable hybrid R&D programs represent the critical lever against mineral-oil substitution threats from EU F-Gas compliance deadlines.
For New Entrants and Emerging Players: Build out aquaculture-facing biodegradable formulation capabilities around Bergen, where salmon farming discharge permits create penetrable demand for vegetable-based hydraulic fluids absent entrenched supplier relationships. Direct technical service partnerships with net-pen equipment operators offer the most viable go-to-market angle against integrated majors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized formulators with biodegradable R&D depth and NORSOK validation track records over commodity distributors facing REACH compliance cost escalation. Long-term viability hinges on service-contract attach rates rather than product volume throughput. The signal to watch is CSRD-aligned procurement criteria adoption speed among hydropower utilities and aquaculture cooperatives.
| Strategic Initiative | Industry Significance |
|---|---|
| NORSOK Certification Investment | Eighteen-month validation cycles create defensive moats against fast-follower entry in subsea applications. |
| Biodegradable Formulation R&D | Aquaculture discharge permits under EU F-Gas alignment drive specification shifts toward vegetable-based esters. |
| Lifecycle Service Contract Bundling | Fluid analysis programs displace transactional sales with recurring revenue streams among drilling contractors. |
| Helicopter Logistics Integration | Offshore platform delivery partnerships anchor channel control in Stavanger maintenance hub concentration. |
| Backward Integration into Base Oil Sourcing | Direct PAO and Group III supply agreements reduce currency fluctuation exposure for Norwegian blenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at Statoil-operated platforms, procurement leads at Bergen aquaculture cooperatives, technical R&D directors at domestic blenders, and aftermarket service heads at marine logistics fleets. Secondary validation drew from Norwegian Environment Agency discharge permit filings, ECHA substance notification databases, NORSOK standard documentation, customs trade data on base oil imports, and SEC 10-K disclosures from integrated majors. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the Norwegian industrial economy.
Calibration against historical volume trajectories and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry vertical, application certification requirement, regional demand cluster, and service contract attachment rate. CAGRs were derived from regression analysis of segment-level drivers. Industry-specific forecast inputs incorporated EU F-Gas amendment implementation schedules and CSRD reporting adoption curves among Norwegian EEA-member enterprises.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated majors to acquire specialized biodegradable formulators would shift competitive dynamics and margin pool distribution. Material shifts in REACH substance restriction scope or EU carbon-border adjustment mechanism coverage would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Industrial Gear Oil Market
Lubricants
Africa Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Morocco Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Thailand Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Nigeria Lubricants Market