
 Global Furan Resins Market | 2026-2036
Global Furan Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Furan Resins Market Intelligence
Low-VOC and reduced-formaldehyde furan resin formulations are rotating the market toward higher-value, environmentally compliant binders. This shift addresses stricter air quality mandates in industrial zones. ASK Chemicals GmbH leverages its specialized portfolio for the foundry sector to meet these specifications. Hexion Inc. competes on a global scale with its broad resin manufacturing capabilities, while Jinan Shengquan Group Co. Ltd. anchors a significant portion of the Asian supply chain.
Furan resins are thermosetting polymers produced through the polycondensation of furfuryl alcohol, often in an acidic medium. These materials exhibit exceptional thermal stability, high chemical resistance against non-oxidizing acids and bases, and strong adhesion properties. Liquid furan resin formats dominate sales volume due to their ease of application in automated mixing systems. Within end-user industries, foundry shell molding remains the largest consumer, though the adhesives and binders segment offers higher margin potential.
Producers must navigate a complex regulatory environment, including the US EPA's rules on volatile organic compounds and the EU's REACH framework for chemical registration. In China, national environmental protection standards (GB standards) dictate permissible emission levels from foundries using these resins. Future investment decisions for manufacturers will hinge on balancing production costs with the development of next-generation, ultra-low emission resin systems.
Market Dynamics
The central structural force shaping the furan resins market is the regulatory mandate for lower emissions. This pressure from bodies like the US EPA and under the EU's REACH framework is compelling a fundamental reformulation of binders toward environmentally compliant systems.
Growth Catalysts
- Foundry Modernization:Demand for high-performance binders in the foundry shell molding industry to produce complex, high-precision metal castings for the automotive and aerospace sectors acts as a primary catalyst.
- Regulatory Compliance:The European Union's REACH framework creates demand for specifically formulated furan resins that meet its stringent chemical registration and safety requirements, favoring compliant producers.
- Manufacturing Concentration:The clustering of industrial production in specific economic zones within China creates dense pockets of consumption for furan resins, supporting localized supply chain development and volume growth.
Market Restraints
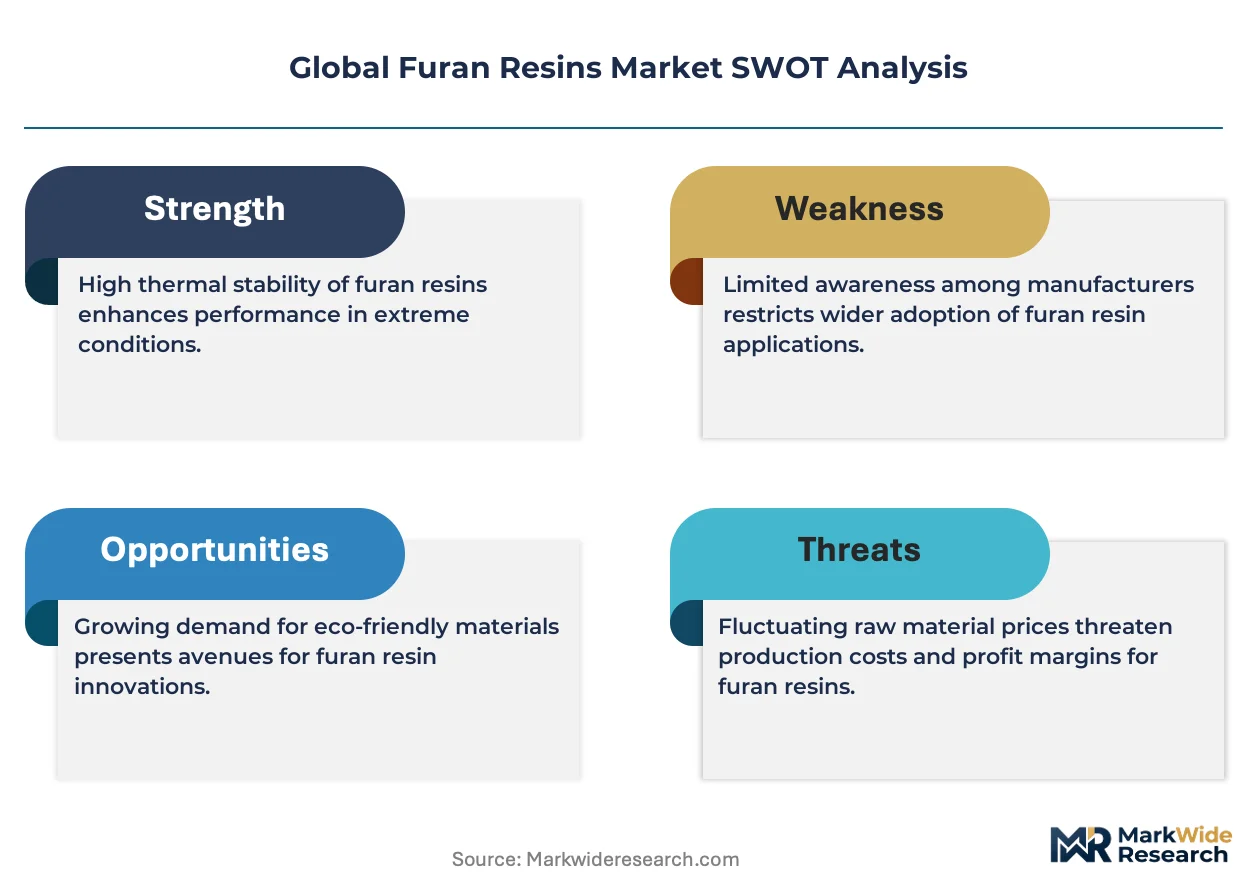
- Input Cost Volatility:The price of furfuryl alcohol, the primary raw material derived from agricultural biomass like corncobs, is subject to fluctuations based on crop yields and alternative uses.
- Substitution Threat:In certain non-critical applications, phenolic and other thermosetting resins can serve as viable substitutes, particularly during periods of high furan resin pricing.
- Technical Limitations:The inherent brittleness of cured furan resins compared to some alternative polymers limits their application in sectors requiring high impact strength without formulation modification.
Strategic Opportunities
- Bio-Composite Development:The formulation of furan resins as a bio-based matrix material for fiber-reinforced composites presents an opportunity in construction and automotive interior components.
- Adhesives and Sealants:Developing specialized, high-margin furan-based adhesives for niche industrial applications offers an avenue for growth beyond the dominant foundry segment.
- Geographic Expansion:Manufacturing hubs in Southeast Asia and Mexico represent underpenetrated markets where foundry and chemical production are expanding, creating new demand centers.
Industry Challenges
- Capital Investment:The significant capital expenditure required to construct new facilities or retrofit existing plants for the production of next-generation, ultra-low emission resin systems is a major hurdle.
- Multi-Jurisdictional Certification:Navigating the complex and time-consuming process of certifying a single resin formulation against disparate regulatory standards like the US EPA rules, EU REACH, and China's GB standards is a significant operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Furan Resins Market |
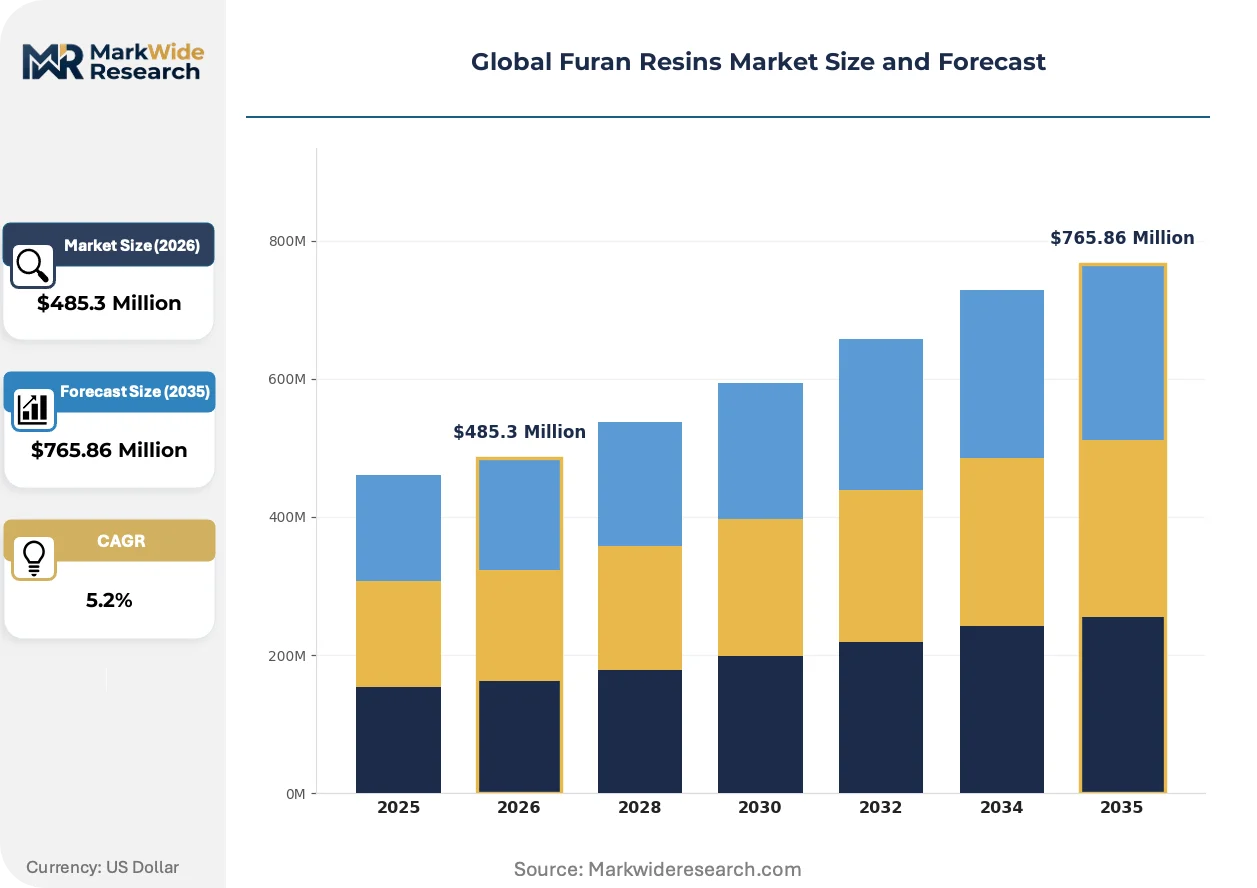
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $765.86 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furan Resin Powder, Liquid Furan Resin, Hardeners, Prepolymers End User Industry: Foundry Shell Molding, Adhesives & Binders, Automotive Parts, Construction Materials, Chemical Processing Application: Abrasive Tools, Corrosion Resistant Coatings, Insulation Materials, Composite Manufacturing, Casting Shells Packaging Type: Drums, Carboys, Bulk Bags, Fiber Drums, Steel Containers |
| Companies Covered | Vesuvius plc, HongYe Chemical Co. Ltd., BASF SE, Jinan Shengquan Group Co. Ltd., International Furan Chemicals BV, Hexion Inc., Dyna Chem Inc., Continental Industries Group Inc., ASK Chemicals GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Furan Resins Market Strategic Shifts & Innovations
A clear division is emerging between standard-grade materials and high-performance, environmentally compliant binders. This trend, driven by stricter air quality mandates, is compelling producers to invest heavily in formulation science and process technology to remain competitive in regulated markets.
Ultra-low emission furan resin systems are advanced binders designed to minimize the release of formaldehyde and other volatile organic compounds during application. Foundries operating in regulated industrial zones in Europe and North America are steadily adopting these systems to comply with stringent air quality permits. This adoption is bifurcating the market into a premium, compliant segment and a separate tier of standard resins used in less regulated environments.
China's national environmental protection standards, specifically the GB standards, impose strict emission limits on industrial facilities, including foundries. This policy directly compels local metal casters to upgrade from older binder technologies to newer, cleaner furan resin systems to avoid operational penalties. The automotive parts casting sector within China is most affected, accelerating the domestic market's shift toward compliant formulations.
A distinct shift in buying criteria now favors suppliers that provide extensive documentation certifying compliance across multiple international regulations. This change in procurement behavior effectively sidelines smaller resin producers who cannot absorb the costs associated with testing for frameworks like REACH or US EPA rules. The trend is most visible among multinational heavy equipment manufacturers requiring uniform material standards across their global foundry supply chains.
Global Furan Resins Market Segmentation
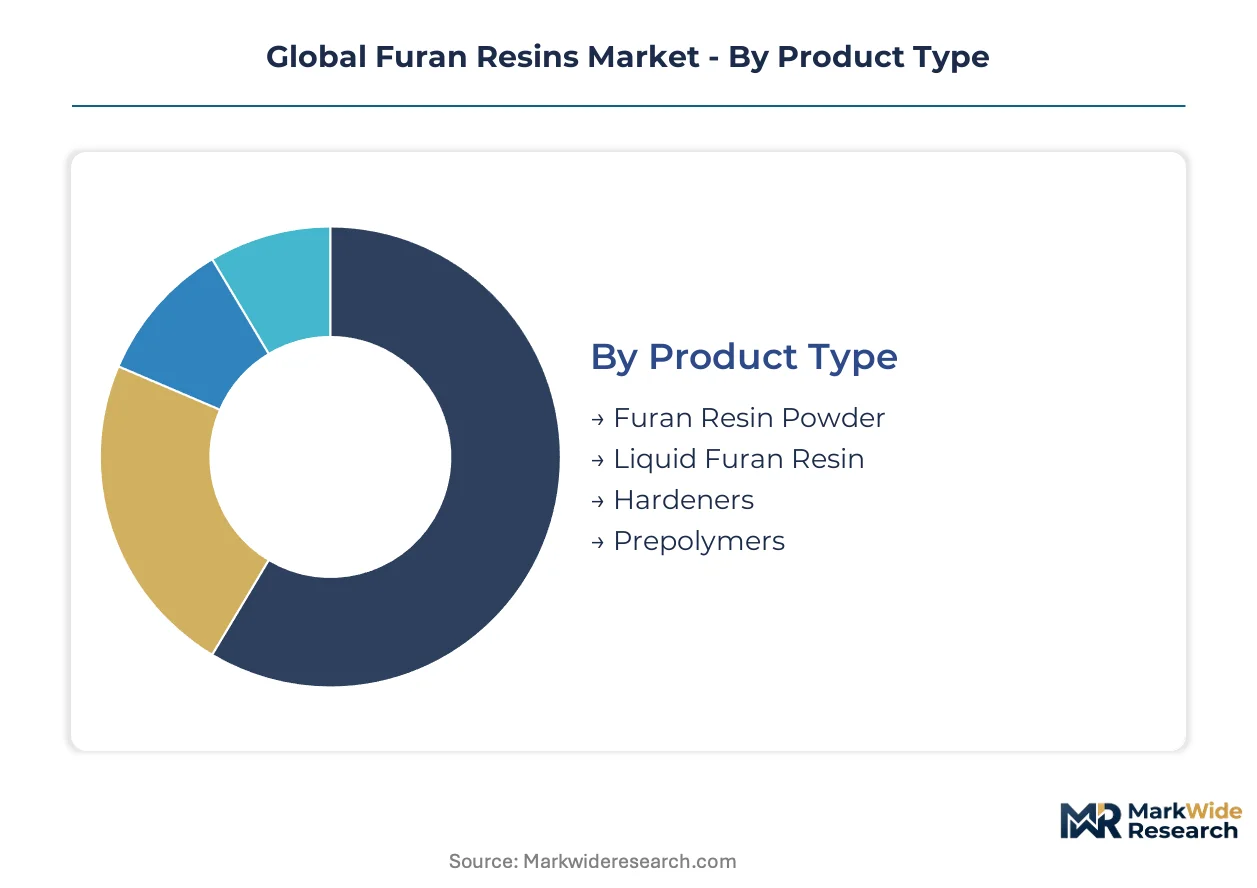
Understanding the segmentation of the global furan resins market reveals distinct value propositions and operational complexities across different product forms, end-user applications, and logistical requirements. Each segment responds uniquely to regulatory pressures and technological advancements, influencing investment and strategic focus for manufacturers.
Product Type:
Margin pools within the product type category are often concentrated in specialized formulations and critical components that enable high-performance outcomes.
- Liquid Furan Resin:This format represents the dominant sales volume, primarily due to its ease of application in automated mixing systems within foundry operations. Its versatility and efficient curing properties make it a staple in high-throughput manufacturing processes.
- Hardeners:These are essential co-reactants that initiate and control the polymerization process of furan resins, dictating cure speed and final material properties. Demand for advanced hardeners with reduced odor and extended pot life is high in regulated industrial zones.
- Furan Resin Powder:This form is typically used in specific niche applications requiring dry blending or where solvent-free systems are preferred, such as in certain composite or refractory material formulations.
- Prepolymers:These are partially polymerized furan resin systems offering specific molecular weights and functionalities, tailored for custom applications demanding precise control over final material characteristics.
Liquid Furan Resin holds installed capacity. Furan Resin Powder is rotating up the share rankings.
End User Industry:
Volume concentration across end-user industries directly shapes supply chain dynamics and dictates the scale of production for furan resin manufacturers.
- Foundry Shell Molding:This industry remains the largest consumer, utilizing furan resins as high-performance binders for creating complex, high-precision metal castings. The automotive and aerospace sectors drive continuous demand for advanced foundry materials.
- Adhesives & Binders:This segment offers significant margin potential by developing specialized furan-based formulations for niche industrial bonding applications, often requiring exceptional chemical resistance and thermal stability. These high-value applications extend beyond conventional foundry uses.
- Automotive Parts:Furan resins are used in various automotive components, including brake pads, engine parts, and composite structures, benefiting from their thermal stability and chemical inertness.
- Construction Materials:The construction sector employs furan resins in corrosion-resistant mortars, coatings, and specialized concretes, particularly in environments exposed to harsh chemicals.
- Chemical Processing:Furan resins find application in chemical processing equipment, such as pipes, tanks, and linings, where resistance to aggressive non-oxidizing acids and bases is paramount.
The Automotive Parts segment is expanding most quickly, driven by lightweighting trends.
Application:
The specific application of furan resins defines the required performance attributes and influences the formulation complexity for producers.
- Casting Shells:Furan resins are critical for producing high-strength, dimensionally stable casting shells and cores in the foundry industry, enabling intricate designs for metal components. Foundries globally rely on these resins for precision casting.
- Corrosion Resistant Coatings:Furan-based coatings provide superior chemical resistance, protecting industrial equipment and infrastructure from corrosive environments, especially in chemical plants and wastewater treatment facilities. These coatings extend the lifespan of critical assets.
- Abrasive Tools:Furan resins serve as binders in the manufacturing of abrasive tools like grinding wheels and sandpaper, providing the necessary strength and thermal stability during high-friction operations.
- Insulation Materials:In certain high-temperature insulation applications, furan resins offer excellent thermal stability and fire resistance, contributing to energy efficiency and safety.
- Composite Manufacturing:Furan resins act as matrix materials in fiber-reinforced composites, particularly where high chemical resistance or fire retardancy is required, such as in marine or aerospace components.
Insulation Materials are becoming critical for performance. Composite Manufacturing is gaining share fastest.
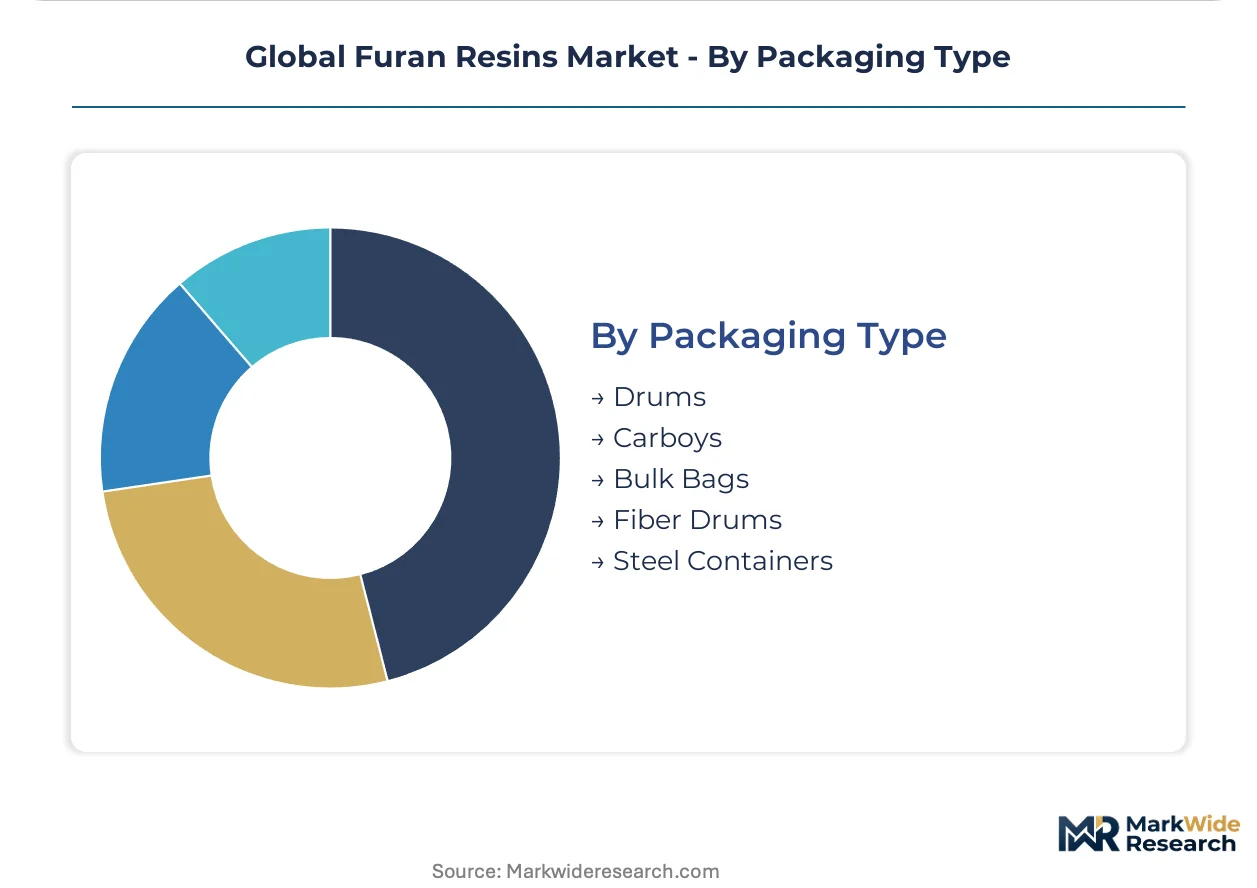
Packaging Type:
Logistics efficiency and cost considerations are primary drivers influencing the choice of packaging type for furan resins across the supply chain.
- Drums:Standard drums remain a prevalent packaging choice for furan resins, offering a balance of transportability, storage efficiency, and protection for moderate volumes. This packaging type is widely adopted for bulk distribution.
- Bulk Bags:These large, flexible containers are primarily used for furan resin powder, providing a cost-effective and efficient solution for shipping and handling significant quantities. Their use optimizes logistics for high-volume powder deliveries.
- Carboys:Smaller carboys are utilized for specialized or lower-volume furan resin formulations, ensuring safe handling and dispensing for precise applications in laboratories or niche manufacturing.
- Fiber Drums:These lightweight, durable containers offer an alternative for transporting furan resin powders or solid forms, balancing protection with ease of disposal.
- Steel Containers:Robust steel containers are employed for large-volume shipments of liquid furan resins, providing maximum protection during long-distance transport and storage.
Steel Containers are driving sustainability efforts. Fiber Drums are gaining traction for specific applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for furan resins varies significantly across global markets, with established industrial economies exhibiting higher price sensitivity for compliant formulations while developing regions prioritize volume and cost efficiency. This dynamic influences investment in next-generation, ultra-low emission systems.
China
China's extensive manufacturing base drives substantial demand for furan resins in its foundry sector, particularly for automotive parts casting. The national environmental protection standards (GB standards) compel local metal casters to upgrade to cleaner binder technologies. Industrial clusters in the Yangtze River Delta actively adopt advanced furan resin systems to meet stringent emission limits.
Germany
The German market demands high-performance, environmentally compliant furan resins, driven by its advanced automotive and machinery industries. The European Union's REACH framework significantly influences material formulations and market access for producers. Companies like ASK Chemicals GmbH in the Rhine-Main region leverage specialized portfolios to meet these strict specifications.
United States
Foundries in the United States require high-performance binders for complex metal castings, with demand influenced by the automotive and aerospace sectors. The US EPA's rules on volatile organic compounds necessitate the adoption of low-VOC furan resin formulations. Manufacturing hubs in the Midwest are steadily integrating these cleaner systems to comply with air quality permits.
India
India's rapidly expanding automotive and infrastructure sectors generate increasing demand for furan resins in its foundry industry. The country's evolving environmental regulations are gradually pushing for cleaner production methods and material inputs. Industrial zones around Chennai and Pune are seeing a rise in the adoption of more advanced furan resin technologies.
Global Furan Resins Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the furan resins market. The market exhibits a tiered structure, with a few global manufacturers providing broad portfolios and numerous regional specialists serving niche applications. Strategic archetypes include integrated chemical giants, specialized foundry chemical suppliers, and biomass-to-chemical producers. Dominant competitive moves involve both strategic partnerships for technology co-development and targeted capacity expansions in high-growth regions.
Specialized foundry chemical suppliers, like Germany-based ASK Chemicals GmbH, represent the premium segment focused on high-performance, environmentally compliant binders for demanding applications in regulated markets. Global chemical manufacturers, such as Hexion Inc., occupy a position of broad resin manufacturing capabilities, leveraging their scale for global distribution across diverse end-user industries. Jinan Shengquan Group Co. Ltd., a China-based entity, anchors a significant portion of the Asian supply chain, exemplifying the regional concentration of production and consumption for both standard and evolving compliant formulations.
| Leading Market Players |
|---|
| Vesuvius plc |
| HongYe Chemical Co. Ltd. |
| BASF SE |
| Jinan Shengquan Group Co. Ltd. |
| International Furan Chemicals BV |
| Hexion Inc. |
| Dyna Chem Inc. |
| Continental Industries Group Inc. |
| ASK Chemicals GmbH |
| Others |
Cost & Logistics Intelligence
Extensive manufacturing capabilities in China's industrial clusters drive significant scale economies for furan resin production. This concentration of capacity establishes competitive price floors, particularly for standard-grade formulations, influencing global market dynamics.
Pricing Analysis
The European Union's REACH framework dictates the pricing tier structure for furan resins, establishing a premium for compliant, low-emission formulations. Contract-based long-term offtake agreements are common for high-volume standard grades, while certification levels and brand premium drive significant price differentiation. Pricing softness affects standard resins due to substitution threats from phenolic resins. Automotive parts manufacturers exhibit lower price sensitivity for compliant, high-performance binders compared to general foundry operations.
Supply Chain Analysis
Foundries often maintain strategic stockpiles of furan resins to ensure continuous production, mitigating risks from supply disruptions. The global supply concentrates heavily in China, with significant production also in Germany and the United States. Input cost volatility stemming from furfuryl alcohol's biomass origin represents a key supply chain risk. Production relies on furfuryl alcohol derived from agricultural biomass. Distribution primarily occurs through chemical distributors and direct sales channels to large industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The furan resins market is entering a cyclical recovery, driven by renewed capital expenditure in the automotive and aerospace sectors. This upswing presents opportunities across the value chain as industrial output normalizes.
For Market Incumbents: Fortify core market positions by investing in next-generation ultra-low emission resin systems, directly countering the threat of stricter GB standards in China. Pursue strategic partnerships for technology co-development to share the capital investment burden for new facilities. Enhance channel control through direct sales to large foundries, mitigating margin pressure from intermediaries. Leverage R&D in bio-based feedstocks to stabilize input costs.
For New Entrants and Emerging Players: Accelerated REACH certification pathways for novel bio-based furan resins offer a rapid entry point into European markets. Target specialized adhesives and sealants for niche industrial applications, leveraging their higher margin potential beyond foundry uses. Focus on underpenetrated markets in Southeast Asia where foundry and chemical production are expanding. A go-to-market strategy centered on performance guarantees and localized technical support can differentiate offerings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized foundry chemical suppliers with proprietary low-VOC resin formulations. The market demonstrates long-term viability, particularly for suppliers capable of consistently meeting evolving global environmental mandates over the next five to ten years. Acquisition targets should include mid-sized firms possessing strong intellectual property in ultra-low emission systems or unique bio-composite development capabilities. The signal to watch is the widespread adoption rate of these advanced systems in emerging industrial clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | This initiative aligns production processes with EU Green Deal objectives, reducing operational environmental impact. |
| Capacity Expansion in Southeast Asia | Expanding capacity in Southeast Asia addresses growing demand from its rapidly industrializing foundry sector. |
| Long-term Supply Agreements for Furfuryl Alcohol | Securing long-term supply agreements mitigates input cost volatility for the primary raw material, furfuryl alcohol. |
| Joint Venture for Bio-Composite Development | A joint venture accelerates the development of furan resin-based bio-composites for construction and automotive components. |
| Certification Investment for GB Standards | Investment in GB standards certification opens market access and ensures compliance for Chinese automotive parts foundries. |
Research Approach
Operator-level perspectives from plant managers, procurement leads, technical R&D directors, and environmental compliance officers anchored the qualitative base. Primary interviews were triangulated with secondary validation from customs/trade data, ACC/Cefic reports, and China's GB standards. This approach ensured comprehensive bottom-up and top-down data synthesis.
Sensitivity analysis informed the forecast framework, evaluating market responses to varying regulatory enforcement scenarios across the analysis window. The model segmented demand by product type, end-user industry, application, and regional production hub. Compound Annual Growth Rates were derived from historical trends and projected industrial output. Key forecast inputs included furfuryl alcohol price forecasts and global foundry modernization rates.
The analysis sits within stated boundaries; outcomes outside current regulatory trajectories or raw material supply stability would require recalibration. Forecasts reflect documented assumptions regarding environmental compliance. Revision becomes warranted when major policy shifts or unforeseen technological disruptions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market