
 North America Engineering Plastics Market | 2026-2036
North America Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Engineering Plastics Market Analytics
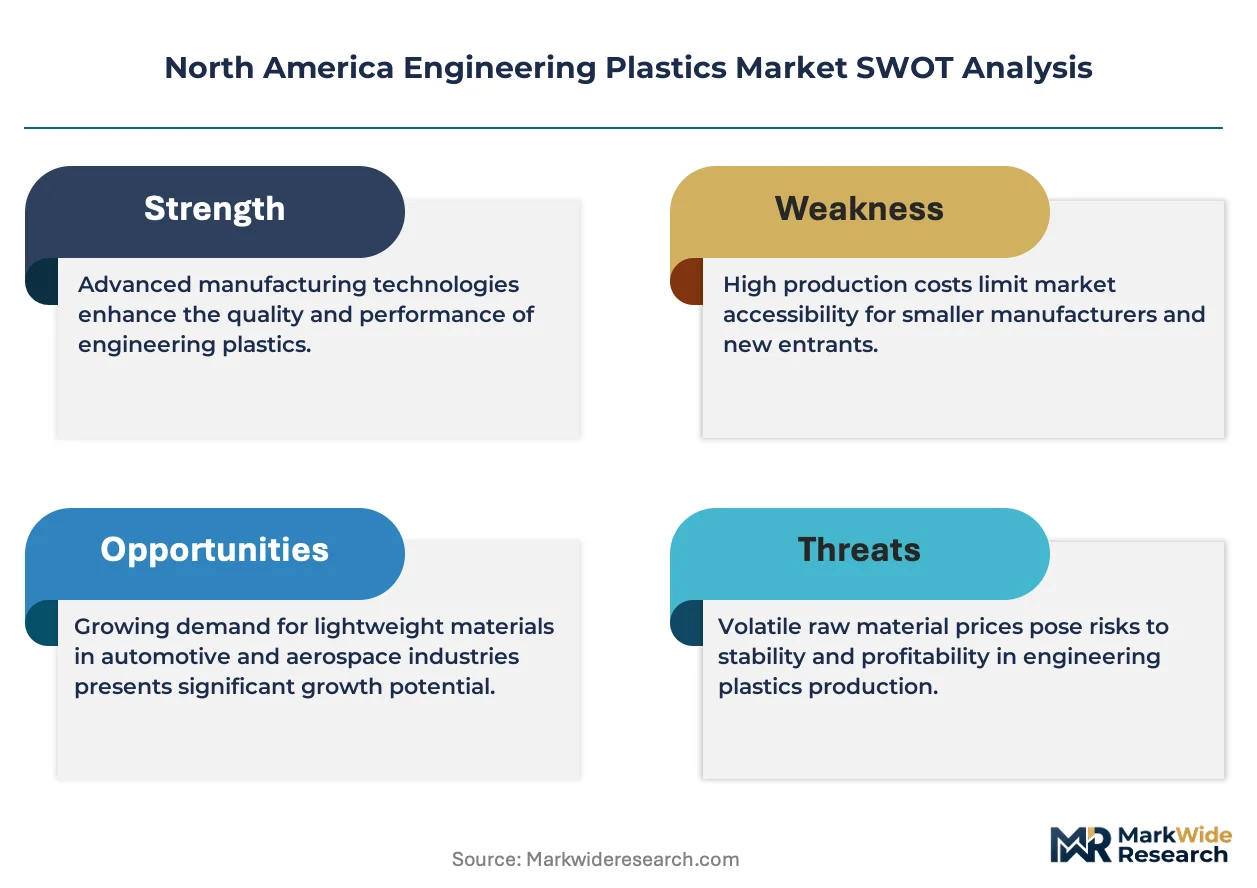
Lightweighting is narrowing the performance gap between advanced composites and engineering plastics in structural automotive applications. BASF leverages its integrated polyamide value chain to supply battery module brackets for electric vehicle platforms across the region. DuPont sustains technology leadership in high-heat nylon formulations for under-hood components. SABIC anchors its position through polycarbonate capacity serving medical device and electronics housing demand.
Engineering plastics encompass thermoplastic polymers engineered to withstand mechanical stress, thermal loads, and chemical exposure beyond commodity resin capabilities, typically exhibiting tensile strength above 40 MPa and continuous service temperatures exceeding 100 degrees Celsius. These materials serve as metal replacements in precision components where weight reduction, design freedom, and corrosion resistance deliver operational value. Polycarbonate dominates optical and safety-critical applications due to its unique combination of transparency and impact resistance, while nylon captures the largest share of structural load-bearing uses in automotive and industrial machinery. Acrylonitrile Butadiene Styrene competes aggressively in cost-sensitive electronics housings and consumer appliance segments where surface aesthetics and processability outweigh extreme performance requirements.
The EPA regulates volatile organic compound emissions from polymer processing facilities under Clean Air Act provisions, while NHTSA crashworthiness standards dictate material selection in automotive safety cells. FDA biocompatibility requirements govern resin grades entering medical device supply chains, creating certification barriers for unqualified suppliers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and Canada that threaten to reshape post-consumer recycling economics and virgin resin cost structures.
Market Dynamics
Automotive electrification is collapsing the traditional metal-to-polymer substitution timeline as OEMs redesign battery architectures and thermal management systems around resin-based solutions.
Growth Catalysts
- EPA Fuel-Economy Mandates:Corporate Average Fuel Economy standards compel Detroit Three automakers to shed vehicle weight through nylon and polycarbonate structural components in chassis and body-in-white assemblies.
- Battery Housing Demand:Electric vehicle platform proliferation across the Great Lakes corridor is pulling flame-retardant polyamide grades into module enclosures and cell separation frames.
- NHTSA Crashworthiness Protocols:Updated side-impact and pedestrian safety regulations favor engineered polymers with tunable energy absorption over stamped metal in bumper beams and fender systems.
Market Restraints
- Caprolactam Feedstock Volatility:Nylon 6 production costs swing with benzene and cyclohexane pricing, compressing compounder margins when oil markets destabilize.
- Midwest Resin Concentration:Polymerization capacity clusters along the Gulf Coast and Ohio River Valley, exposing buyers to single-point weather and logistics disruptions.
- High-Temperature Ceiling:Continuous service temperatures above 150 degrees Celsius still favor aluminum and magnesium in powertrain components adjacent to electric motor windings.
Strategic Opportunities
- Canadian Medical Device Expansion:Health Canada biocompatibility certifications for implantable-grade polycarbonate create a procurement beachhead in Toronto-Waterloo surgical instrument manufacturing.
- IRA Clean Energy Tax Credits:Domestic content bonuses for North American-assembled electric vehicles incentivize resin sourcing from US and Ontario compounders over Asian imports.
- 3D Printing Convergence:Fused filament fabrication with carbon-fiber-reinforced nylon is collapsing prototyping-to-production lead times in aerospace tooling and jigs.
Industry Challenges
- Color-Matching Expertise Gap:Automotive OEMs report 18-month recruitment cycles for polymer scientists capable of formulating low-VOC pigments that survive e-coat bake cycles without degradation.
- FDA Master File Navigation:Medical device suppliers face 24-36 month documentation timelines to secure Device Master File acceptance for new resin grades, freezing formulation innovation.
- Legacy Injection Molding Retooling:Tier-2 processors in Michigan and Ohio confront six-figure capital outlays to upgrade clamp tonnage and barrel configurations for high-heat nylon processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Engineering Plastics Market |
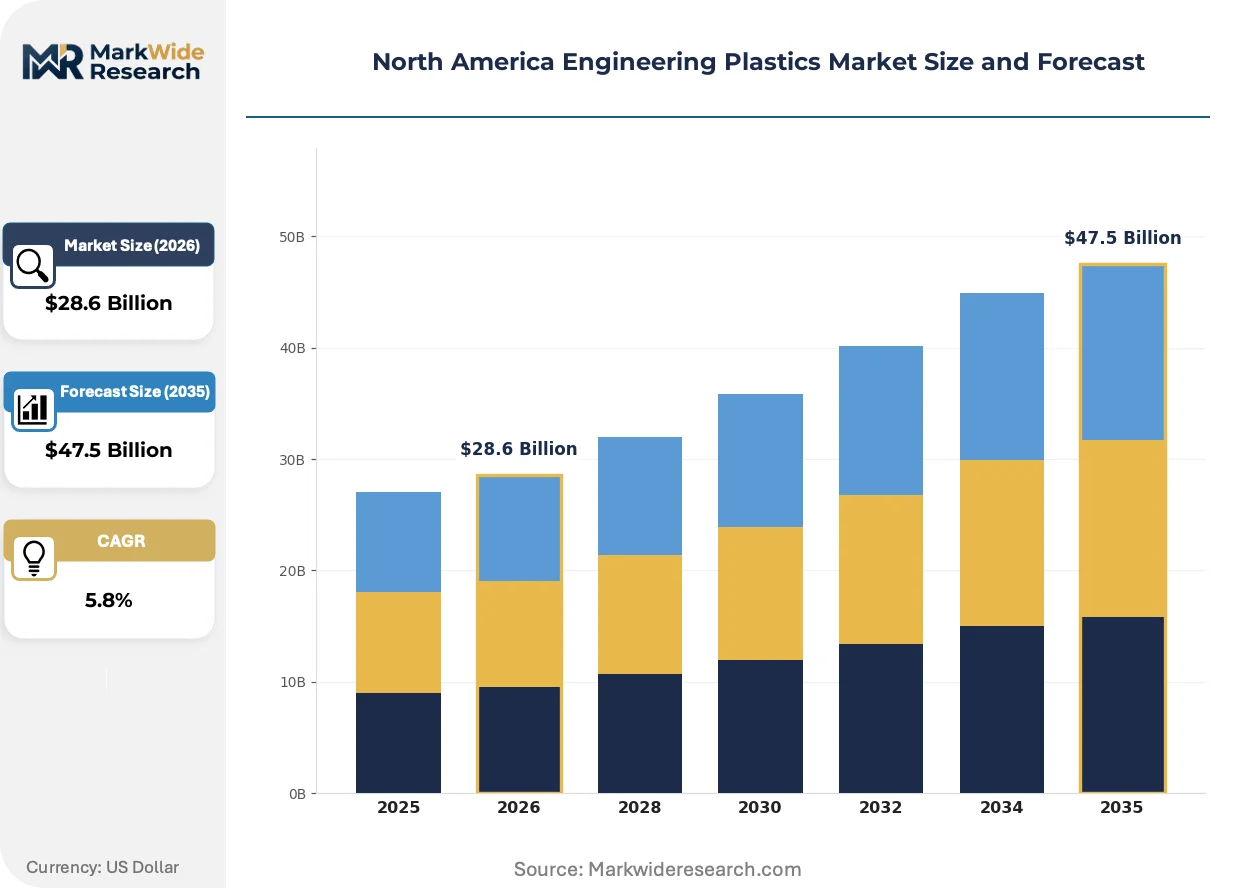
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Nylon, Polypropylene, Acrylonitrile Butadiene Styrene End User: Aerospace, Automotive, Electronics, Medical Devices Application: Structural Components, Insulation, Housing, Packaging Form: Sheets, Films, Rods, Injection Molding |
| Companies Covered | BASF, DuPont, SABIC, Celanese Corporation, Covestro AG, LyondellBasell Industries Holdings B.V., Dow Inc., RTP Company, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Engineering Plastics Market Evolving Landscape
Material science breakthroughs and regulatory pressure are compressing development cycles across automotive, medical, and electronics verticals. Three converging forces are redefining competitive positioning.
Long-fiber thermoplastic injection molding is collapsing the performance gap between compression-molded composites and conventional injection grades. Tier-1 suppliers in Detroit and Windsor are adopting 40-50% glass-filled polypropylene and nylon systems for semi-structural battery trays and seat frames. The technology enables single-tool processing of complex geometries that previously required metal stamping and welding assemblies.
California's extended producer responsibility framework for plastics is forcing resin producers to validate post-consumer recycled content streams for engineering-grade applications. The state's draft regulations mandate 30% recycled content in specified product categories by 2030, compelling compounders to invest in chemical recycling and advanced sorting infrastructure. Medical and food-contact segments face the steepest compliance cliffs due to FDA contamination thresholds.
Direct-to-mold coloring is displacing traditional masterbatch distribution in high-volume automotive contracts. OEMs in the Ohio-Kentucky-Tennessee manufacturing arc are specifying pellet-in-pigment systems to eliminate compounding steps and reduce lot-to-lot variation. The shift concentrates procurement power with resin producers capable of precision dispersion at polymerization scale rather than independent color houses.
North America Engineering Plastics Market Segmentation
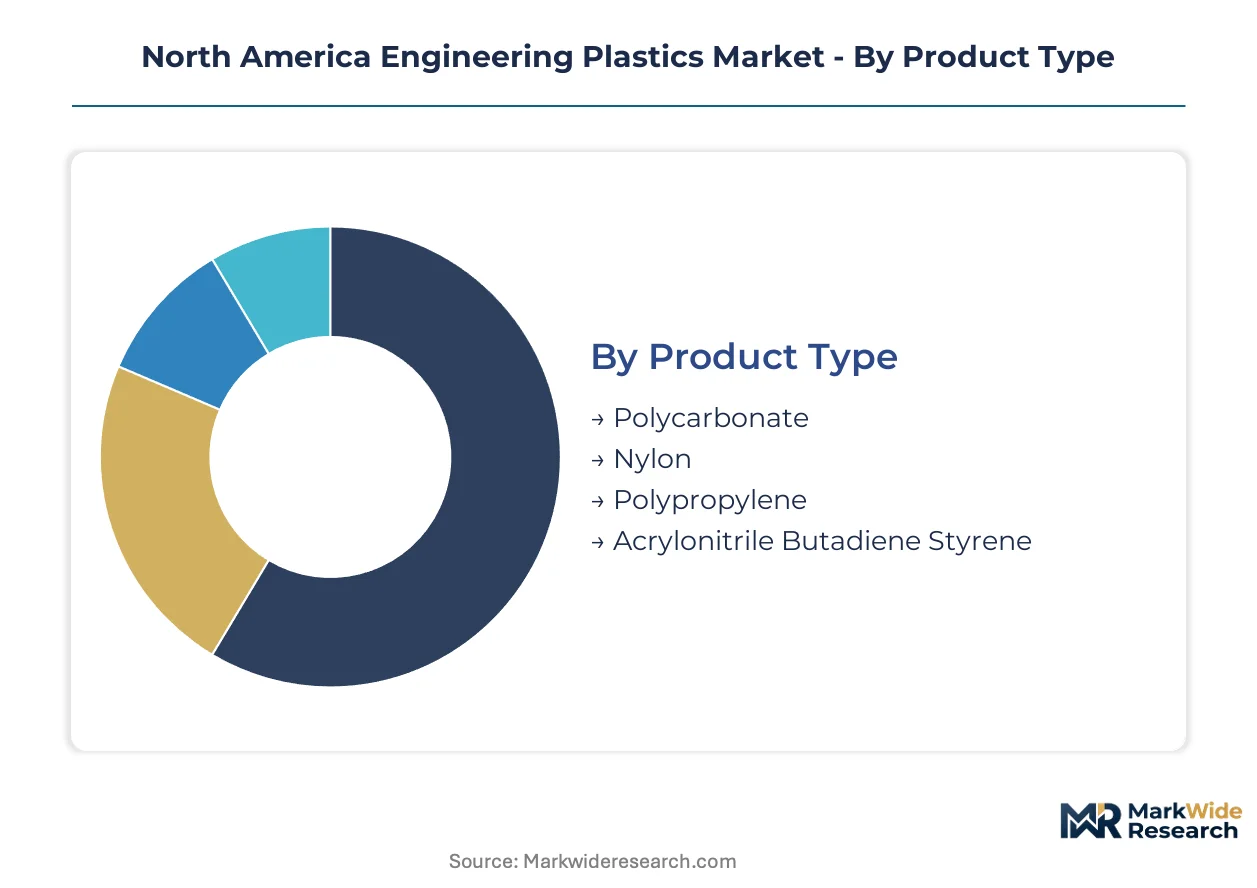
Engineering plastics exhibit divergent performance profiles across resin chemistries and processing forms, demanding precise alignment between material specification and end-use thermal or mechanical loads. Segmentation reveals how polycarbonate and nylon architectures dominate safety-critical and structural applications while alternative polymers capture cost-optimized niches.
Product Type:
Cost tier stratification separates premium high-heat formulations from commodity-competitive grades, with feedstock integration and compounding complexity driving margin structures across the value chain.
- Polycarbonate:Amorphous thermoplastic delivering optical clarity above 90% light transmission alongside notched Izod impact resistance exceeding 800 J/m. Medical device manufacturers in the Toronto-Waterloo corridor specify medical-grade polycarbonate for surgical instrument housings requiring sterilization compatibility and FDA biocompatibility clearance.
- Nylon:Semicrystalline polyamide family spanning Nylon 6 and Nylon 6,6 with tensile strength ranging 70-85 MPa and continuous service temperature to 150°C. Battery enclosure demand across Michigan and Ohio assembly plants pulls flame-retardant grades into electric vehicle module brackets and cell separation frames.
- Polypropylene:Lightweight olefin with density 0.90-0.91 g/cm³ and flexural modulus tuned through talc or glass reinforcement for semi-structural applications. Interior automotive trim and appliance housings in the Ohio-Kentucky-Tennessee manufacturing arc specify mineral-filled grades for cost-controlled dimensional stability.
- Acrylonitrile Butadiene Styrene:Terpolymer balancing processability, surface aesthetics, and moderate impact strength for electronics enclosures where extreme thermal performance is secondary to design freedom and colorability. Consumer appliance OEMs favor ABS for control panels and housing assemblies subject to moderate mechanical stress.
Polycarbonate and Nylon command the established base. The steepest expansion runs through flame-retardant Nylon grades serving electrified automotive architectures.
End User:
Application maturity varies dramatically across end-use verticals, with regulatory certification timelines and performance validation requirements creating divergent procurement patterns and supplier qualification barriers.
- Automotive:Largest demand concentration spanning powertrain, chassis, and electrification subsystems. EPA Corporate Average Fuel Economy standards and NHTSA crashworthiness protocols compel Detroit Three OEMs to substitute stamped metal with glass-filled nylon in bumper beams and fender systems.
- Electronics:High-volume housing and connector applications where surface finish, electromagnetic shielding compatibility, and thin-wall processability outweigh extreme mechanical requirements. Server rack manufacturers and consumer device assemblers drive specification standardization.
- Medical Devices:Implantable and surgical instrument segments requiring FDA Device Master File acceptance and biocompatibility testing per ISO 10993 protocols. Health Canada certification creates parallel procurement pathways for Ontario-based device manufacturers.
- Aerospace:Niche but high-specification demand for cabin interior components and non-structural hardware subject to FAA flammability standards. Weight reduction mandates in commercial aviation sustain premium pricing for certified grades.
Automotive absorbs the dominant volume share. Medical Devices present the most demanding qualification trajectory but command superior margin structures.
Application:
Functional role within the finished assembly determines material selection priority, with structural loads, electrical isolation, and environmental exposure each dictating distinct resin specifications and processing routes.
- Structural Components:Load-bearing assemblies including battery trays, seat frames, and chassis reinforcements where long-fiber thermoplastic injection molding bridges composite and conventional polymer performance. Tier-1 suppliers in Detroit and Windsor adopt 40-50% glass-filled systems to collapse metal-to-polymer substitution timelines.
- Housing:Enclosure applications spanning electronics, appliances, and medical equipment where dimensional stability, aesthetic surface quality, and assembly integration dominate specification criteria. Direct-to-mold coloring is displacing masterbatch distribution in high-volume automotive contracts.
- Insulation:Electrical and thermal barrier applications in battery modules, connector systems, and power electronics where dielectric strength and flame retardancy are paramount. Electric vehicle platform proliferation accelerates demand for tracking-resistant grades.
- Packaging:Specialized industrial and medical packaging requiring sterilization compatibility, barrier properties, or impact protection for sensitive contents. Pharmaceutical primary packaging segments face FDA contamination threshold constraints.
Structural Components anchor capital deployment. Insulation applications are climbing the fastest as electrification redesigns thermal management architectures.
Form:
Processing technology and intermediate form factor shape supply chain configuration, with conversion economics and design flexibility creating divergent value capture across the production chain.
- Injection Molding:Dominant conversion route for complex three-dimensional geometries in high-volume automotive and electronics applications. Michigan and Ohio Tier-2 processors confront six-figure capital outlays to upgrade clamp tonnage and barrel configurations for high-heat nylon processing.
- Sheets:Flat stock for thermoforming, fabrication, and secondary machining in medical device trays, equipment housings, and architectural glazing. Polycarbonate sheet commands optical and safety-critical applications.
- Films:Thin-gauge extrusions for membrane switches, display overlays, and flexible circuit substrates where clarity, printability, and dielectric performance converge. Electronics manufacturing clusters in Guadalajara and Silicon Valley pull specialized grades.
- Rods:Bar stock for precision machining of bearings, gears, and custom hardware in industrial machinery and fluid handling systems. Nylon rod dominates wear-resistant applications.
Injection Molding commands the established base. The steepest expansion runs through sheet and film formats serving medical and electronics verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and medical device manufacturers concentrate procurement power across three North American jurisdictions, each presenting distinct regulatory pathways and industrial cluster configurations.
United States
EPA Corporate Average Fuel Economy standards and NHTSA crashworthiness protocols compel Detroit Three automakers to specify glass-filled nylon for bumper beams and battery enclosures. The Great Lakes manufacturing corridor spanning Michigan and Ohio hosts Tier-1 injection molding operations serving electric vehicle platform redesigns. Michigan processors confront capital outlays for high-heat barrel configurations as OEMs accelerate metal-to-polymer substitution timelines.
Canada
Health Canada biocompatibility certifications for implantable-grade polycarbonate create procurement beachheads in Toronto-Waterloo surgical instrument manufacturing. The country's extended producer responsibility frameworks in Ontario and British Columbia reshape post-consumer recycling economics for compounders. Quebec-based resin distributors serve medical device clusters requiring ISO 10993 protocol compliance and FDA Device Master File navigation support.
Mexico
Nearshoring momentum in Nuevo León and the Bajío Region pulls automotive electronics housing demand from Asian suppliers. Mexico's automotive manufacturing integration under USMCA domestic content rules incentivizes resin sourcing from US and Ontario compounders. Guanajuato assembly plants specify ABS and polypropylene grades for interior trim and appliance control panels serving North American export markets.
North America Engineering Plastics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where feedstock-integrated multinationals anchor supply security and independent compounders capture specification-intensive niches. The vendor base stratifies between resin producers with polymerization assets and downstream formulators serving medical and automotive qualification pathways. Two strategic archetypes dominate: integrated petrochemical players with captive monomer supply, and technology-focused compounders with FDA Master File portfolios. Competitive moves center on direct-to-mold coloring capabilities and long-fiber thermoplastic processing partnerships with Tier-1 automotive suppliers.
Within the integrated chemical producer tier, BASF and Covestro AG exemplify archetypes combining polymerization scale with application development resources. DuPont occupies a position representing specialty nylon formulation expertise for high-heat under-hood components. SABIC anchors the polycarbonate segment serving medical device and electronics housing demand. These three companies sit within distinct competitive vectors—feedstock integration, high-performance formulation, and optical-grade capacity—rather than direct overlap across all specification tiers.
| Leading Market Players |
|---|
| BASF |
| DuPont |
| SABIC |
| Celanese Corporation |
| Covestro AG |
| LyondellBasell Industries Holdings B.V. |
| Dow Inc. |
| RTP Company |
| Asahi Kasei Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in flame-retardant polyamide compounding across the Great Lakes corridor is pushing contract terms toward buyers while resin producers defend margins through benzene-indexed pricing clauses. Gulf Coast polymerization assets running above nameplate utilization are extracting premium pricing for spot volumes, forcing automotive OEMs into longer offtake commitments with Detroit-area compounders.
Pricing Analysis
Cost-plus contracts with benzene and caprolactam indexation dominate nylon grade procurement, insulating compounders from feedstock volatility while passing cyclohexane cost swings to automotive buyers. Price differentiation hinges on FDA Device Master File certification tier and flame-retardant UL94 V-0 compliance grade. Cost compression in standard-grade polycarbonate is intensifying because SABIC and Covestro are prioritizing optical-grade capacity for medical device demand. Tier-2 processors in Michigan exhibit highest price sensitivity due to legacy equipment amortization burdens, while medical device OEMs accept premium pricing for implantable-grade biocompatibility.
Supply Chain Analysis
Extended payment terms stretching to 90 days and supply-chain finance facilities anchored by resin distributors are easing working capital pressure on Ohio-Kentucky-Tennessee processors. Feedstock concentration draws from benzene crackers along the US Gulf Coast, caprolactam producers in the Ohio River Valley, and bisphenol-A facilities in Texas and Louisiana. Single-source vulnerability runs through hurricane-exposed Gulf Coast polymerization assets that supply 60% of North American polycarbonate resin. Distribution runs through regional compounders with silo storage and railcar receiving infrastructure serving the automotive manufacturing arc.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across electrification subsystems is creating specification niches as battery platform architectures diverge between Detroit Three OEMs, rewarding compounders with formulation agility over commodity scale.
For Market Incumbents: Harden qualification pathways by securing NHTSA crashworthiness pre-certification for long-fiber thermoplastic grades before competitors complete validation cycles. Deepen backward integration into caprolactam monomer supply through Ohio River Valley offtake agreements, insulating margin structures from benzene volatility that threatens independent compounders without polymerization assets. For New Entrants and Emerging Players: Mexican medical device manufacturing clusters in Nuevo León represent underpenetrated demand for implantable-grade polycarbonate outside Toronto-Waterloo dominance. Target Health Canada biocompatibility certification as the entry credential, then leverage USMCA domestic content rules to supply Guanajuato surgical instrument exporters seeking North American resin sourcing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with FDA Master File portfolios serving medical device OEMs on multi-year supply agreements with automatic renewal clauses. Long-term viability across the analysis window favors acquisition targets with captive polymerization or toll-compounding partnerships in the Great Lakes corridor, where IRA clean energy tax credits are anchoring electric vehicle production. The signal to watch is Tier-1 automotive supplier consolidation toward single-source resin qualification, which would concentrate procurement power and compress margins for non-integrated compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive monomer supply locks in margin stability against benzene price cycles for nylon compounders. |
| FDA Device Master File Expansion | Additional resin grade certifications open procurement pathways into implantable medical device supply chains. |
| Long-Fiber Thermoplastic Partnership | Co-development agreements with Detroit Tier-1 suppliers accelerate metal-to-polymer substitution in battery trays. |
| Direct-to-Mold Coloring Investment | Pellet-in-pigment dispersion at polymerization scale eliminates masterbatch steps and captures automotive specification power. |
| Chemical Recycling Infrastructure | Advanced sorting and depolymerization assets position compounders for California extended producer responsibility mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive platform engineers, medical device procurement managers, polymerization plant managers, and distribution channel partners in Michigan, Ohio, and Ontario. Secondary validation drew from EPA Clean Air Act enforcement records, NHTSA crashworthiness test databases, FDA 510(k) and Device Master File repositories, and ACC resin production statistics. Bottom-up volume estimates from end-use application sizing were triangulated against top-down capacity and utilization data from polymerization facilities.
Calibration against historical price realizations and demand elasticities shaped the projection framework across the analysis window. Segmentation dimensions modeled include resin chemistry family, thermal performance tier, end-use vertical, and regional manufacturing cluster propensity. CAGRs were derived from elasticity-adjusted demand curves incorporating electric vehicle platform rollout schedules and medical device regulatory approval pipelines. Feedstock cost scenarios and capacity expansion announcements informed supply-side constraints.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, benzene pricing volatility, or electric vehicle subsidy policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Resin Glue Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Middle East Polycarbonate (PC) Market