
 Flexible Polymer Foam Market | 2026-2036
Flexible Polymer Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Polymer Foam Market Analysis
Modular seating platforms are restructuring procurement patterns across automotive and furniture supply chains. BASF SE leverages integrated polyol production to sustain cost advantages in flexible polyurethane systems. Dow Inc. anchors North American supply through dedicated foam technology centers. Huntsman International LLC differentiates via specialized MDI formulations for high-resilience bedding applications.
Flexible polymer foam comprises cellular elastomeric materials manufactured through controlled expansion of thermosetting or thermoplastic polymers, typically achieving densities between 10 and 80 kg per cubic meter with open-cell structures that permit air and moisture permeability. These materials primarily function as energy-absorbing, thermally insulating, or comfort-enhancing layers across industrial and consumer products. Polyurethane Foam dominates value generation due to established supply chains and formulation versatility across temperature and durability requirements. Polyethylene Foam represents the fastest-expanding category driven by waterproof packaging demand for electronics and medical device shipment. The Bedding application concentrates margin pools where premium viscoelastic and high-resilience grades command sustained price premiums over commodity slabstock.
The EPA oversees VOC emissions from foam manufacturing under Clean Air Act standards, while OSHA regulates diisocyanate exposure limits in production facilities. REACH restrictions on halogenated flame retardants and ECHA classifications of certain isocyanates are redirecting formulation investments toward bio-based polyols and reactive flame-retardant additives. Stakeholders must monitor evolving chemical hazard designations across multiple jurisdictions to anticipate reformulation timelines and capital allocation for compliant production assets.
Market Dynamics
Automotive lightweighting mandates and appliance energy-efficiency standards are compressing foam density specifications while expanding performance requirements across temperature ranges and durability cycles.
Growth Catalysts
- EU F-Gas Regulation phase-down:Manufacturers are accelerating HFO and CO2-based blowing agent conversions ahead of 2030 quotas, creating replacement demand for compliant foam systems in refrigeration and construction.
- China domestic appliance clusters:Concentrated refrigerator and washing machine production in Hefei, Qingdao, and Foshan drives bulk polyurethane offtake with integrated polyol-tdi supply chains.
- High-resilience MDI formulations:Bedding and seating producers are adopting modified isocyanate systems that reduce component counts while improving compression set performance.
Market Restraints
- Toluene diisocyanate price volatility:Crude oil-linked aromatics and nitric acid costs transmit directly to foam system pricing, compressing converter margins during energy price spikes.
- REACH authorization timelines:ECHA's substance of very high concern listings for certain flame retardants and isocyanates are forcing multi-year reformulation cycles with uncertain approval outcomes.
- Polyethylene foam substitution:Expanded polypropylene and molded pulp solutions are capturing waterproof packaging share from cross-linked PE in consumer electronics shipment.
Strategic Opportunities
- India automotive seating:Maruti Suzuki, Tata Motors, and Hyundai's expanding domestic production create localized foam demand currently served by imported slabstock.
- Bio-based polyol mandates:The EU Green Deal's 30% renewable content targets for plastics are opening formulation partnerships between chemical producers and agricultural feedstock suppliers.
- Direct-to-furniture-brand distribution:E-commerce mattress and sofa companies are bypassing traditional foam distributors, enabling margin capture through specification control and compressed delivery cycles.
Industry Challenges
- Diisocyanate safe-use training:OSHA's expanded hazard communication requirements and EU REACH restrictions are mandating certified handler programs that strain smaller converter operations.
- Multi-jurisdiction flame retardant compliance:California TB 117-2013, EU REACH SVHC listings, and emerging state-level restrictions create conflicting test protocols that fragment product lines.
- Legacy continuous slabstock asset repositioning:Rectangular block production lines face utilization pressure as molded and variable-pressure dispensing systems capture automotive and medical volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Polymer Foam Market |
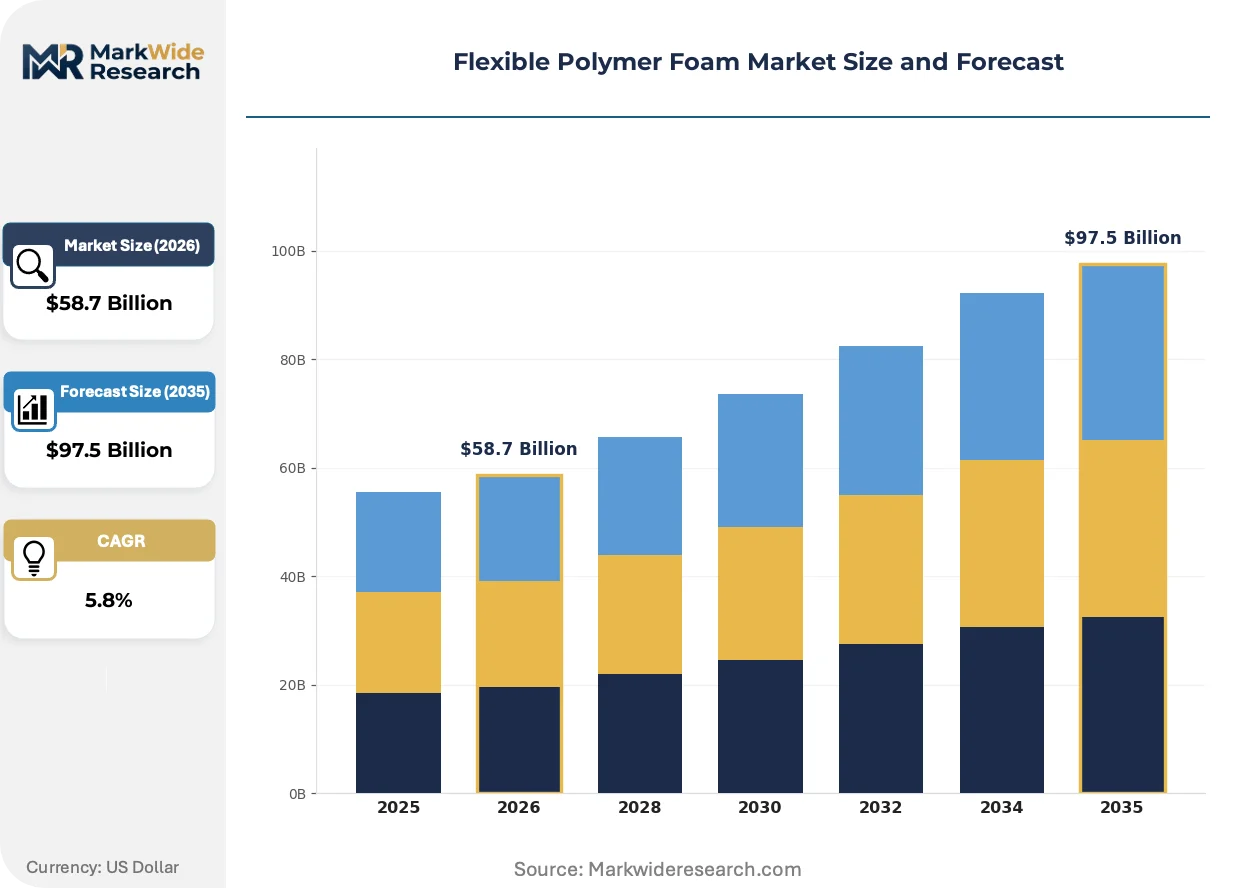
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polyethylene Foam, Polystyrene Foam, PVC Foam End User: Automotive, Furniture, Packaging, Construction Application: Insulation, Bedding, Soundproofing, Cushioning Features: Lightweight, Waterproof, Fire-Resistant, Recyclable |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Huntsman International LLC, Woodbridge, Recticel Group, INOAC Corporation, Carpenter Co., Armacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Polymer Foam Market Emerging Trajectories
Formulation chemistry, manufacturing process control, and supply chain configuration are converging to redefine competitive differentiation beyond commodity density specifications.
Reactive processing technologies are decentralizing production economics in the flexible foam value chain. Variable-pressure molding and direct-to-shape dispensing systems enable converters to produce finished components without intermediate block cutting, reducing scrap rates from 15% to under 5%. Tier-one seating suppliers in Germany and the US are installing captive foam cells adjacent to assembly lines, compressing logistics costs and enabling just-in-sequence delivery.
REACH restrictions on halogenated flame retardants are redirecting formulation investments across European supply chains. ECHA's 2023 SVHC candidate list expansion for certain organophosphorus compounds is forcing bedding and furniture producers to validate phosphorus-nitrogen synergist systems through full-scale fire testing. German and Italian converter clusters are consolidating specification approval processes through shared testing consortia to distribute compliance costs.
Modular platform architectures are restructuring procurement relationships in automotive seating. Volkswagen, Stellantis, and Hyundai-Kia are specifying common foam density and hardness zones across multiple vehicle programs, enabling volume aggregation that favors suppliers with integrated polyol-to-foam production. Tier-one suppliers in Michigan, Bavaria, and Shanghai are responding with dedicated technology centers that co-develop formulations with OEM engineering teams.
Flexible Polymer Foam Market Segmentation
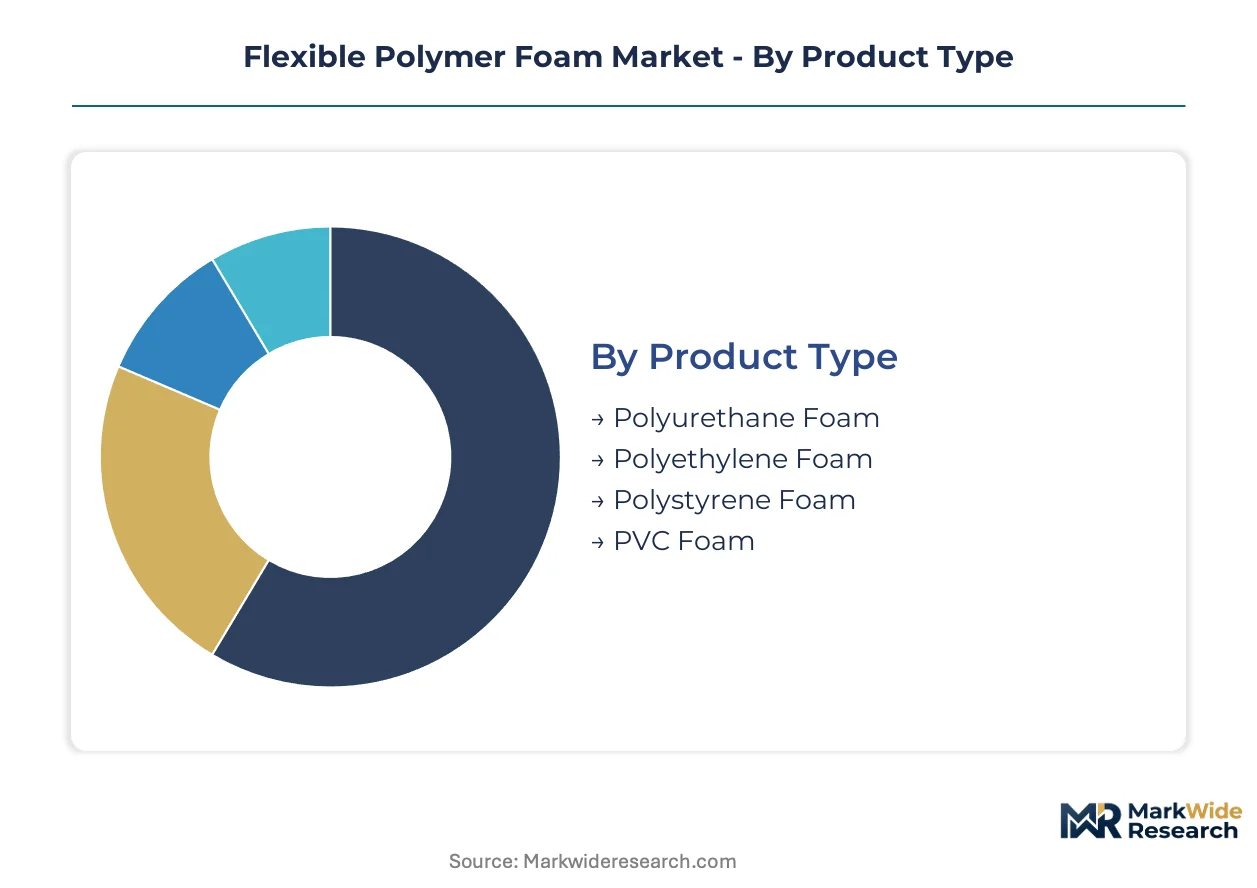
Segmentation in flexible polymer foam markets reveals how formulation chemistry, end-use performance requirements, and regulatory compliance intersect to create distinct value pools. Understanding these boundaries enables suppliers to align R&D investments with margin concentration and anticipate substitution risks.
Product Type:
Density specifications and polymer backbone chemistry define the performance envelope for each foam category, with blowing agent selection and cell structure engineering determining thermal stability and mechanical durability.
- Polyurethane Foam:Thermosetting polymer systems built from polyol-isocyanate reactions achieve tunable density gradients from 16 to 80 kg/m³ through controlled expansion. Automotive seating manufacturers in Germany, Michigan, and Shanghai specify high-resilience grades for compression set resistance across temperature cycling. REACH restrictions on halogenated flame retardants are redirecting European bedding producers toward phosphorus-nitrogen synergist formulations.
- Polyethylene Foam:Cross-linked or non-cross-linked thermoplastic structures deliver closed-cell waterproofing with densities ranging 25-330 kg/m³ depending on expansion ratio. Medical device and consumer electronics shippers in Shenzhen and Rotterdam are adopting expanded PE for sterile barrier packaging. Substitution pressure from expanded polypropylene and molded pulp solutions is compressing share in consumer electronics logistics.
- Polystyrene Foam:Expanded bead or extruded sheet configurations provide rigid thermal insulation with low moisture absorption characteristics. Cold chain logistics operators specify polystyrene for temperature-sensitive pharmaceutical distribution.
- PVC Foam:Cellular vinyl structures combine chemical resistance with fire-retardant properties inherent to the polymer backbone. Marine and transportation interior applications drive specification in coastal manufacturing clusters.
Polyurethane Foam leads on scale; Polyethylene Foam leads on momentum.
End User:
Procurement patterns diverge sharply between specification-driven OEM relationships and price-sensitive distributor channels, with compliance requirements fragmenting product lines across jurisdictions.
- Automotive:Seating and interior trim specifications demand compression set resistance below 10% after 70°C aging cycles. Volkswagen, Stellantis, and Hyundai-Kia are consolidating foam density zones across modular platforms to aggregate volume. Tier-one suppliers in Bavaria and Michigan are installing captive foam cells adjacent to assembly lines for just-in-sequence delivery.
- Furniture:Mattress and upholstery producers specify viscoelastic and high-resilience grades for differentiated comfort positioning. E-commerce mattress brands are bypassing traditional distributors to capture margin through direct specification control.
- Packaging:Fragile goods protection requirements drive demand for energy-absorbing foams with controlled deceleration curves. Electronics manufacturers specify cross-linked PE for waterproof shipment integrity.
- Construction:Building envelope insulation and acoustic treatment applications require flame-retardant certification under multi-jurisdiction test protocols. California TB 117-2013 and EU REACH SVHC listings create conflicting compliance pathways.
Automotive commands the largest procurement volumes; Furniture offers the steepest expansion trajectory through e-commerce channel development.
Application:
Functional performance requirements determine polymer selection, with thermal conductivity targets and acoustic absorption coefficients driving formulation decisions.
- Insulation:Low thermal conductivity specifications below 0.025 W/m·K drive polyurethane system selection for refrigeration and building envelope applications. EU F-Gas Regulation phase-down is accelerating HFO and CO₂-based blowing agent conversions ahead of quota deadlines.
- Bedding:Pressure distribution and airflow permeability specifications differentiate premium viscoelastic grades from commodity slabstock. German and Italian converter clusters are consolidating fire-testing approval processes through shared consortia to distribute REACH compliance costs.
- Soundproofing:Open-cell structures with controlled airflow resistance absorb acoustic energy across frequency ranges. Automotive NVH engineering teams specify multi-density laminates for cabin quietness targets.
- Cushioning:Energy absorption and recovery characteristics determine foam selection for seating and protective packaging. Compression set resistance after repeated loading cycles differentiates high-resilience MDI formulations.
Insulation dominates tonnage offtake; Bedding captures the widest margin dispersion across specification tiers.
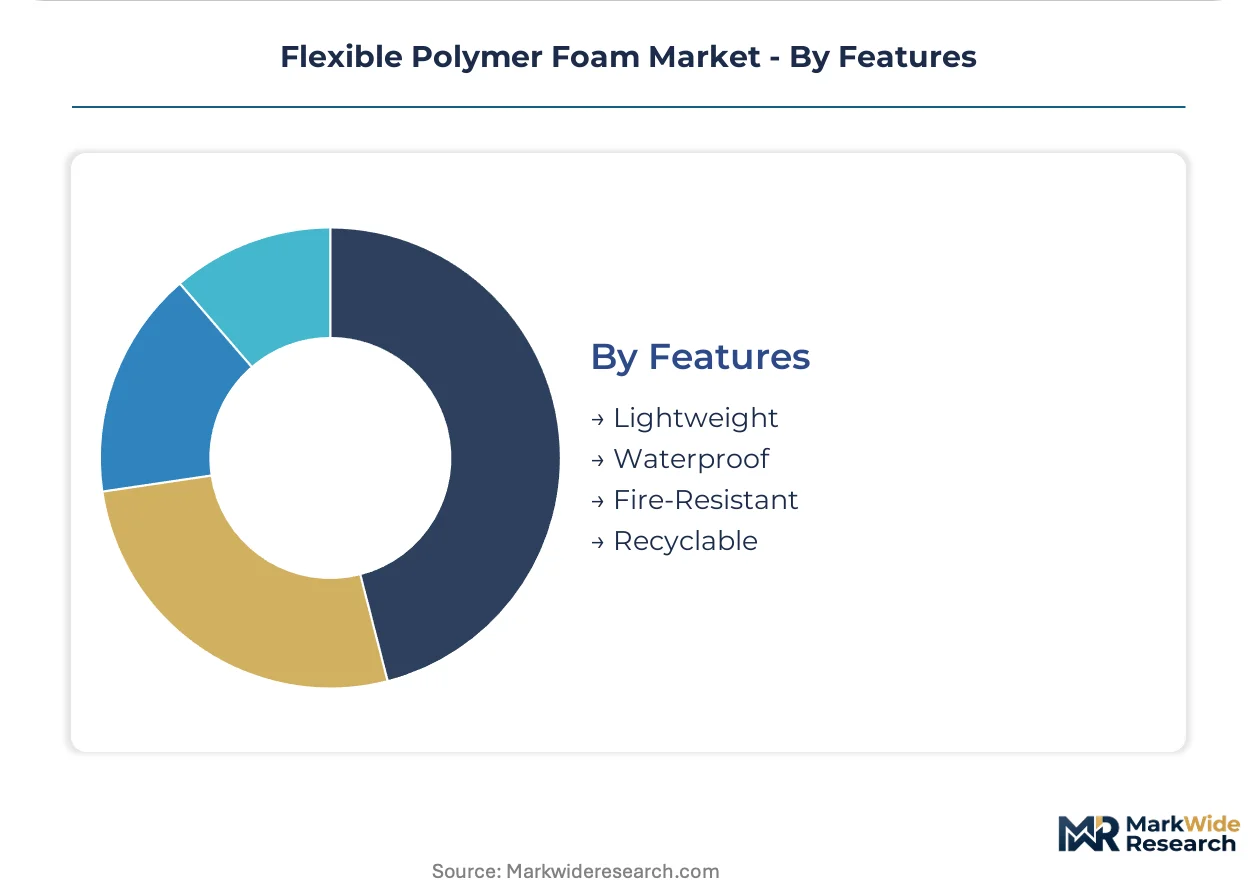
Features:
Certification requirements and sustainability positioning are redefining feature sets from commodity attributes to compliance-mandated specifications with price implications.
- Lightweight:Density reduction targets below 30 kg/m³ enable fuel economy improvements in transportation applications. Automotive lightweighting mandates are compressing foam specifications while expanding temperature range requirements.
- Waterproof:Closed-cell structures with water absorption below 1% by volume protect sensitive electronics and medical devices during shipment. Cross-linked PE dominates this specification band.
- Fire-Resistant:California TB 117-2013 smolder resistance and EU REACH SVHC restrictions on halogenated compounds are forcing reformulation investments. Phosphorus-nitrogen synergist systems are gaining validation through full-scale fire testing.
- Recyclable:EU Green Deal targets for 30% renewable content in plastics are opening partnerships between chemical producers and agricultural feedstock suppliers. Bio-based polyol availability constrains scaling.
Lightweight features anchor the largest installed base; Recyclable specifications are climbing the fastest as regulatory mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible polymer foam production scaled through German chemical engineering in the mid-20th century before dispersing to automotive and appliance manufacturing clusters across Asia and North America. Today, formulation expertise and end-use demand concentrate in distinct national ecosystems shaped by local regulatory frameworks and industrial specialization.
United States
Automotive seating specifications from Detroit-area OEMs drive high-resilience polyurethane consumption for compression set resistance. EPA Clean Air Act standards govern VOC emissions from foam manufacturing facilities. Michigan and Ohio host captive foam cells adjacent to tier-one assembly lines for just-in-sequence delivery to vehicle plants.
Germany
Modular platform architectures from Volkswagen and Stellantis consolidate foam density zones across multiple vehicle programs. EU F-Gas Regulation phase-down accelerates HFO and CO₂-based blowing agent conversions ahead of 2030 quotas. Bavarian converter clusters co-develop formulations with OEM engineering teams at dedicated technology centers.
China
Domestic appliance production in Hefei, Qingdao, and Foshan drives bulk polyurethane offtake for refrigerator and washing machine insulation. MIIT energy-efficiency standards compress foam density specifications while expanding performance requirements. Yangtze River Delta and Pearl River Delta house integrated polyol-TDI supply chains serving regional manufacturers.
India
Maruti Suzuki, Tata Motors, and Hyundai expanding domestic automotive production create localized foam demand currently served by imported slabstock. BIS certification requirements for automotive materials redirect specification investments toward compliant formulations. Tamil Nadu and Maharashtra automotive corridors attract tier-one seating suppliers establishing regional foam conversion capacity.
Japan
High-resilience bedding applications from domestic furniture manufacturers specify modified MDI formulations for premium comfort positioning. METI chemical safety guidelines influence diisocyanate handling protocols in production facilities. Kansai region converter clusters specialize in viscoelastic grades for export-oriented mattress producers.
Flexible Polymer Foam Market Vendor Landscape
The competitive structure tilts toward integrated chemical producers with captive polyol supply. BASF SE, Covestro AG, and Dow Inc. anchor the upstream tier through backward integration into polyether and polyester polyol production. Mid-scale foam converters compete on specification agility and regional logistics proximity. Dominant competitive moves include captive technology center establishment adjacent to OEM engineering hubs and bio-based polyol partnership formation with agricultural feedstock suppliers.
Among integrated chemical producers, BASF SE and Covestro AG exemplify the upstream-control archetype through in-house polyol production. Dow Inc. occupies a parallel position in North American supply configuration. Huntsman International LLC represents the formulation-specialist tier with modified isocyanate systems. These three entities collectively illustrate how competitive positioning stratifies between raw material integration and application-specific chemistry expertise.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Huntsman International LLC |
| Woodbridge |
| Recticel Group |
| INOAC Corporation |
| Carpenter Co. |
| Armacell |
| Others |
Supply Flow & Price Mechanics
Variable-pressure molding and direct-to-shape dispensing systems are compressing converter economics while redistributing margin capture toward captive foam cells adjacent to OEM assembly lines in Michigan, Bavaria, and Shanghai. This production-method transition simultaneously reduces scrap rates from intermediate block cutting and concentrates procurement leverage among tier-one seating suppliers with integrated polyol-to-foam capabilities.
Pricing Analysis
Three-tier pricing structure across premium viscoelastic, standard high-resilience, and economy slabstock grades anchors the market. Price differentiation separates REACH-compliant phosphorus-nitrogen formulations from commodity halogenated systems, while volume scale determines contract positioning for automotive OEMs versus furniture distributors. Cost compression in standard grades is intensifying because TDI price volatility transmits directly from crude oil-linked aromatics. Furniture distributors exhibit the highest price sensitivity; automotive tier-one suppliers prioritize compression set performance over unit cost.
Supply Chain Analysis
Freight cost differentials between bulk polyol shipments and finished foam components are driving regionalization of conversion capacity. Supply concentrates in Germany, China, and the United States, with integrated polyol-TDI production feeding Yangtze River Delta and Pearl River Delta appliance clusters. Raw material dependencies rest on crude oil-derived aromatics, nitric acid for TDI synthesis, and bio-based feedstocks for EU Green Deal compliance. Single-source vulnerability around MDI systems from concentrated isocyanate producers poses structural risk. Distribution runs through direct-to-OEM contracts for automotive and traditional distributor networks for furniture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible polymer foam market functions as a geographic-arbitrage play where EU REACH compliance costs and F-Gas Regulation timelines create 18-24 month formulation lead time advantages for producers with established European technology centers versus Asian competitors facing delayed certification cycles.
For Market Incumbents: Acquire captive polyol production assets to secure cost advantages against TDI price volatility and secure backward integration into bio-based feedstock partnerships. BASF SE and Covestro AG already demonstrate this archetype. Defend market position by establishing dedicated technology centers adjacent to Volkswagen and Stellantis engineering hubs in Bavaria, co-developing modular platform specifications that aggregate volume and raise switching costs for converters. For New Entrants and Emerging Players: Enter via regional foam conversion capacity in Tamil Nadu and Maharashtra automotive corridors, where Maruti Suzuki and Tata Motors expansion creates localized demand currently served by imported slabstock. Target India's underpenetrated automotive seating tier-two supplier base with BIS-certified formulations. Pursue direct-to-furniture-brand distribution partnerships with e-commerce mattress companies bypassing traditional distributors, capturing margin through specification control and compressed delivery cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European converters facing REACH reformulation costs but possessing established OEM approval relationships and shared testing consortia infrastructure. Long-term viability over the next decade hinges on successful transition to bio-based polyol systems and HFO blowing agent conversion ahead of regulatory deadlines. Monitor ECHA SVHC candidate list expansions for phosphorus-nitrogen flame retardant validation as the inflection signal for compliant formulation premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | BASF SE secures cost advantages and formulation control across European supply chains. |
| Captive Foam Cell Installation | Tier-one seating suppliers in Michigan compress logistics costs through just-in-sequence delivery. |
| Bio-based Polyol Partnership Formation | Chemical producers collaborate with agricultural feedstock suppliers to meet EU Green Deal targets. |
| HFO Blowing Agent Conversion | Manufacturers accelerate compliant system development ahead of EU F-Gas Regulation quotas. |
| Direct-to-Furniture-Brand Distribution | E-commerce mattress companies capture margin through specification control and compressed cycles. |
Methodological Framework
Direct dialogue with plant managers at polyurethane conversion facilities, procurement leads at automotive tier-one suppliers, distribution channel partners in furniture and bedding, and technical R&D directors at integrated chemical producers grounded the qualitative foundation. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and EPA Clean Air Act enforcement records. Bottom-up demand modeling from end-use consumption patterns and top-down supply validation from production capacity databases were triangulated to establish market sizing.
Segment-level value and volume estimates across the projection horizon reflect discrete modeling of polyurethane, polyethylene, polystyrene, and PVC foam chemistries intersecting with automotive, furniture, packaging, and construction end-uses. Grade tier, regional production hub concentration, and blowing agent technology pathway served as segmentation dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating automotive lightweighting mandates and appliance energy-efficiency standards as structural demand shapers.
The model holds under stable regulatory enforcement timelines and continued OEM platform consolidation; deviation in ECHA authorization outcomes or sudden TDI feedstock disruptions would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market