
 Global Cyanuric Chloride Market | 2026-2036
Global Cyanuric Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cyanuric Chloride Market Foresight
Specialty chemical intermediates revenue is rewriting margin allocation across the cyanuric chloride value chain. Evonik Industries leverages its European manufacturing footprint to sustain supply security for pharmaceutical-grade derivatives. Ynnovate Sanzheng anchors volume production through backward integration into chlor-alkali feedstocks. Lonza differentiates via cGMP-compliant manufacturing protocols that command premium positioning in reagent-grade segments.
Cyanuric chloride is a symmetrical triazine compound with the formula C3Cl3N3, manufactured through continuous gas-phase chlorination of cyanuric acid at temperatures exceeding 200°C; it serves primarily as a reactive intermediate for nucleophilic substitution reactions in agrochemical, dye, and pharmaceutical synthesis. Technical grade dominates current volume flows due to its specification adequacy for bulk pesticide and water treatment chemical manufacturing, while pure grade captures disproportionate margin pools from pharmaceutical intermediates and high-performance dye applications. Powder form leads logistics efficiency for large-scale chemical processors, though granule demand is strengthening among water treatment plants seeking reduced dust exposure and improved dissolution control.
EPA registration requirements under FIFRA constrain pesticide-grade cyanuric chloride import and formulation standards in the United States, while REACH authorization processes in Europe impose sustained toxicological documentation burdens on suppliers seeking continued market access. China's MEE enforcement of dual carbon goals is elevating energy-intensity scrutiny for chlor-alkali and chlorination processes, pressuring cost structures at Shandong and Jiangsu production clusters. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate qualification cost escalations and supply relocation signals.
Market Dynamics
Energy-intensity scrutiny under China's dual carbon goals is compressing chlor-alkali feedstock economics and forcing capacity rationalization across Shandong and Jiangsu production clusters. This structural pressure is redrawing supplier qualification protocols and margin allocation across pharmaceutical-grade and technical-grade derivative streams.
Growth Catalysts
- Agrochemical formulation demand:Herbicide and pesticide manufacturers in India and Brazil are scaling triazine-based active ingredient procurement. FIFRA registration pathways in the United States sustain import pull for EPA-compliant material.
- REACH authorization compliance:European ECHA processes for Substances of Very High Concern are filtering out non-compliant Asian suppliers. Pharmaceutical-grade derivative producers with toxicological documentation capture displaced volume.
- Continuous gas-phase chlorination:Temperature-optimized reactor designs above 200°C are improving yield rates and reducing chlorine consumption per ton. Process licensors in Germany and Japan command technology transfer premiums.
Market Restraints
- Chlorine supply volatility:European chlor-alkali curtailments during winter energy peaks transmit directly to cyanuric chloride unit economics. Merchants without captive chlorine face margin compression.
- Substitution by alternative triazine intermediates:Melamine cyanurate complexes are displacing cyanuric chloride in select flame-retardant applications. Polymer compounders in South Korea and Taiwan are qualifying these alternatives.
- Concentrated production geography:Over 60% of merchant capacity resides in China's eastern coastal provinces. Geopolitical friction or logistics disruption risks systemic supply tightness.
Strategic Opportunities
- Underpenetrated pharmaceutical reagent demand:cGMP-compliant manufacturers in Switzerland and Singapore are qualifying cyanuric chloride for peptide coupling chemistry. Lonza's Basel operations demonstrate premium positioning feasibility.
- Water treatment channel expansion:Granule-form material for reduced dust exposure is gaining specification at municipal treatment facilities in Australia and Canada. Distribution partnerships with regional chemical distributors unlock access.
- India PLI scheme for agrochemical intermediates:Domestic production incentives are attracting joint venture proposals from Chinese technology licensors. Gujarat and Maharashtra states offer feedstock integration advantages.
Industry Challenges
- Specialized reactor engineering talent scarcity:Gas-phase chlorination above 200°C requires process safety expertise concentrated at German and Japanese engineering firms. Knowledge transfer to emerging market operators proceeds slowly.
- Multi-jurisdiction registration timeline compression:Simultaneous EPA, REACH, and NMPA dossier preparation strains regulatory affairs bandwidth. Staggered submission strategies delay revenue recognition.
- Legacy batch process retrofit complexity:Semi-continuous assets in Eastern Europe require capital-intensive automation upgrades to meet pharmaceutical-grade specifications. Financing constraints prolong competitive disadvantage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cyanuric Chloride Market |
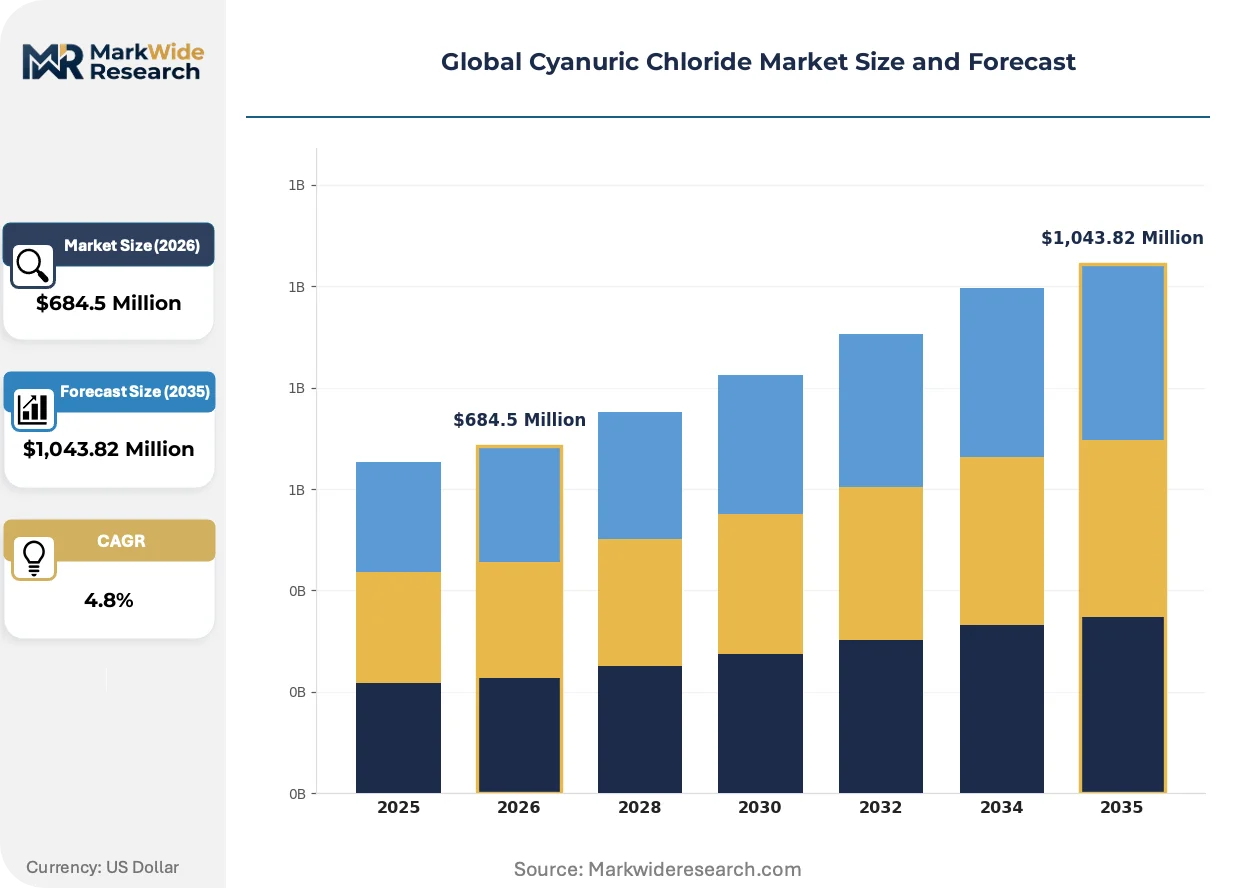
| Market Size in 2026 | $684.5 Million |
| Market Size in 2035 | $1,043.82 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Grade, Technical Grade, Industrial Grade, Reagent Grade Application: Pesticides, Dyes, Water Treatment, Textile Chemicals, Pharmaceutical Intermediates End User Industry: Chemical Manufacturers, Agrochemical Producers, Textile Processors, Pharmaceutical Companies, Water Treatment Plants Form: Powder, Granules, Flakes, Crystals |
| Companies Covered | Evonik Industries, Syngenta, Ynnovate Sanzheng, Volochem Inc, Santa Cruz Biotechnology, HeBei ChengXin, Lonza, Sigma-Aldrich, WeylChem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cyanuric Chloride Market Shifts & Advancements
Process intensification and regulatory digitization are converging to compress qualification timelines and reshape competitive differentiation across derivative grade tiers. Three developments merit particular attention.
Continuous flow reactor technology with real-time spectroscopic monitoring is digitizing quality assurance protocols for pharmaceutical-grade batches. Swiss and German manufacturers are adopting these systems fastest, collapsing release testing from days to hours. The compression is enabling just-in-time inventory models for high-value reagent customers.
REACH's SCIP database requirements for article-level substance disclosure are extending documentation burdens downstream into formulated pesticide and dye applications. EU-based formulators now demand batch-level traceability certificates from intermediate suppliers. Technical-grade producers without digitized chain-of-custody systems face exclusion from premium contract tiers.
Agrochemical procurement teams are consolidating supplier panels and demanding multi-year fixed-price arrangements with volume flexibility clauses. Large multinational herbicide manufacturers in the United States and Brazil are displacing spot-market purchasing. The shift concentrates volume at integrated producers with captive chlorine and cyanuric acid positions.
Global Cyanuric Chloride Market Segmentation
Segmentation in cyanuric chloride markets separates volume-driven commodity flows from specification-sensitive premium tiers. Grade purity, application toxicity requirements, and form factor logistics each create distinct margin pools and supplier qualification barriers.
Product Type:
Mature specifications dominate agrochemical and industrial channels, while emerging pharmaceutical and reagent grades command toxicological documentation premiums.
- Technical Grade:Contains 95-98% cyanuric chloride with controlled moisture and hydrolysable chlorine specifications. Agrochemical formulators in India and Brazil absorb the majority of technical grade volume for triazine herbicide synthesis, with EPA registration requirements sustaining import pull from compliant suppliers.
- Pure Grade:Exceeds 99% purity with stringent heavy metal and organic impurity limits. Pharmaceutical intermediate manufacturers in Switzerland and Singapore specify pure grade for peptide coupling reagents, where cGMP compliance and batch traceability justify substantial price premiums over technical material.
- Industrial Grade:Lower purity specification for non-critical applications; water treatment chemical processors in Australia and Canada represent primary offtake for bulk cyanurate stabilization products.
- Reagent Grade:Ultra-high purity with spectroscopic certification; analytical chemistry laboratories and specialty synthesis operations in Germany and Japan qualify limited volumes against pharmacopeial standards.
Technical Grade retains volume leadership; Pure Grade holds the steepest expansion curve.
Application:
Cost tier differentiation separates bulk pesticide manufacturing from pharmaceutical and dye intermediate value chains.
- Pesticides:Triazine-based herbicides and fungicides consume cyanuric chloride for active ingredient construction. Formulators in the United States and Brazil scale procurement under FIFRA registration constraints, with multi-year supply agreements displacing spot market purchasing.
- Pharmaceutical Intermediates:Peptide coupling chemistry and heterocyclic building block synthesis demand reagent-grade material with full toxicological dossiers. Swiss and German manufacturers capture this tier through cGMP-compliant production protocols.
- Dyes:Reactive dye intermediate production concentrates in China's Jiangsu and Zhejiang provinces, where integrated dye houses consume technical grade for triazine anchor group attachment.
- Water Treatment:Cyanurate stabilization for swimming pool and municipal applications drives steady demand; granule form preference is strengthening among treatment plants seeking reduced dust exposure.
- Textile Chemicals:Flame retardant and dye-fixative applications in South Korea and Taiwan face substitution pressure from melamine cyanurate complexes.
Pesticides retain volume leadership; Pharmaceutical Intermediates hold the steepest expansion curve.
End User Industry:
Customer type fragmentation creates divergent procurement patterns across integrated chemical houses and specialized formulators.
- Agrochemical Producers:Large multinational herbicide manufacturers in the United States, Brazil, and India consolidate supplier panels and demand volume flexibility clauses. Captive chlor-alkali integration at major producers insulates against chlorine supply volatility.
- Chemical Manufacturers:Dye intermediate and specialty chemical houses in China and India represent the deepest volume pool, with backward integration into chlor-alkali feedstocks compressing merchant market participation.
- Pharmaceutical Companies:cGMP-compliant manufacturers in Switzerland, Singapore, and Germany qualify cyanuric chloride against pharmacopeial monographs; batch-level SCIP database documentation extends REACH compliance burdens downstream.
- Textile Processors:Dye houses and finishing operations in South Korea and Taiwan consume technical grade for reactive dye synthesis, with substitution risk from alternative triazine intermediates.
- Water Treatment Plants:Municipal facilities in Australia and Canada specify granule-form material for handling safety; regional chemical distributors mediate access to qualified supply.
Chemical Manufacturers retain volume leadership; Agrochemical Producers hold the steepest expansion curve.
Form:
Logistics efficiency and handling safety drive form selection across powder, granule, flake, and crystal presentations.
- Powder:Fine particulate maximizes surface area for rapid dissolution in continuous chemical processing. Large-scale agrochemical and dye intermediate manufacturers in China and India prefer powder for reactor feed efficiency.
- Granules:Compacted spherical particles reduce dust generation and improve flowability. Water treatment plants in Australia and Canada increasingly specify granules for occupational safety compliance and controlled dissolution rates.
- Flakes:Thin compressed sheets offer intermediate handling characteristics; limited adoption in specialty chemical processing where precise dosing control matters.
- Crystals:Large crystalline structure for high-purity reagent applications; pharmaceutical intermediate manufacturers in Germany and Switzerland specify crystals for visual impurity detection and precise gravimetric handling.
Powder retains volume leadership; Granules hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across regions. Indian and Brazilian agrochemical formulators absorb technical-grade volume at cost-sensitive terms, while Swiss and German pharmaceutical buyers accept substantial premiums for cGMP-compliant pure-grade material.
China
Domestic dye intermediate manufacturers in Jiangsu and Zhejiang provinces consume the deepest technical-grade volumes for reactive dye synthesis. MEE enforcement of dual carbon goals is elevating energy-intensity scrutiny for chlor-alkali operations. Shandong production clusters face capacity rationalization pressure as captive chlor-alkali integration becomes mandatory for cost competitiveness.
United States
FIFRA-registered herbicide manufacturers consolidate supplier panels under multi-year procurement agreements. EPA registration requirements constrain import pathways for pesticide-grade material. Gulf Coast chemical processors leverage captive chlorine positions to insulate margins against European chlor-alkali volatility.
Germany
Pharmaceutical-grade derivative demand concentrates around Basel-adjacent cGMP facilities serving peptide coupling chemistry. REACH authorization processes filter non-compliant Asian suppliers from premium contract tiers. Ludwigshafen and Leverkusen industrial corridors host process licensors commanding technology transfer premiums for continuous gas-phase chlorination systems.
India
Triazine herbicide formulators in Gujarat and Maharashtra scale procurement under PLI scheme incentives for agrochemical intermediate domestication. CDSCO registration timelines compress as multinational herbicide manufacturers qualify local supply. Dahej and Mundra port corridors attract joint venture proposals from Chinese technology licensors seeking feedstock integration.
Brazil
Soybean belt agrochemical distributors drive technical-grade import demand for triazine-based herbicide formulation. ANVISA registration alignment with FIFRA standards sustains pull for EPA-compliant material. São Paulo state chemical distributors mediate access to qualified Asian supply amid port congestion and currency volatility.
Global Cyanuric Chloride Market Competitive Landscape
Capability concentration sits with European cGMP-compliant specialists; scale advantage sits with Chinese integrated producers. The market structures around three tiers: captive chlor-alkali operators with backward integration into cyanuric acid feedstocks, technology-licensed merchant producers dependent on spot chlorine markets, and pharmaceutical-grade specialists commanding toxicological documentation premiums. Dominant competitive moves include capacity consolidation in Shandong and Jiangsu clusters and strategic partnerships between Indian PLI beneficiaries and Chinese process licensors.
Among European cGMP-compliant specialists, Lonza and Evonik Industries exemplify the premium-tier archetype through Basel and German manufacturing footprints. Ynnovate Sanzheng anchors the scale-driven segment through Shandong-based captive chlor-alkali integration. These three occupy positions spanning the capability-scale spectrum without overlapping customer segments.
| Leading Market Players |
|---|
| Evonik Industries |
| Syngenta |
| Ynnovate Sanzheng |
| Volochem Inc |
| Santa Cruz Biotechnology |
| HeBei ChengXin |
| Lonza |
| Sigma-Aldrich |
| WeylChem |
| Others |
Supply & Pricing Matrix
Shanghai-Ningbo port corridor freight differentials compress margins for merchant producers while amplifying pricing power for Shandong-based captives with chlor-alkali integration. This logistics asymmetry stratifies procurement costs across technical-grade agrochemical buyers and pharmaceutical-grade specialists seeking cGMP-certified supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between large agrochemical manufacturers and integrated Chinese producers, displacing spot-market purchasing for volume-tier material. Three-tier pricing structure across premium, standard, and economy levels separates cGMP-compliant pharmaceutical grades from EPA-registered technical grades and bulk industrial specifications. Cost compression in technical-grade streams is intensifying because MEE dual carbon enforcement elevates energy-intensity compliance costs. Brazilian and Indian herbicide formulators exhibit highest price sensitivity, while Swiss peptide chemistry buyers accept substantial premiums for toxicological documentation.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for merchant chlorine procurement, straining working capital at non-integrated producers without supply-chain finance facilities. Manufacturing concentration rests on China, Germany, and India, with Jiangsu province hosting over half of global merchant capacity. Feedstock dependencies center on cyanuric acid, chlorine gas, and catalytic reactor systems. Single-source vulnerability runs through Shandong chlor-alkali clusters where MEE enforcement is triggering capacity rationalization. Distribution runs through regional chemical distributors mediating access to qualified supply for water treatment and municipal facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas-phase chlorination engineering expertise sits with fewer than a dozen qualified process licensors globally, creating acquisition premiums for technology-holding assets and forcing qualification timelines that favor incumbents with documented production histories.
For Market Incumbents: Harden cGMP-compliant manufacturing protocols to defend pharmaceutical-grade positioning against emerging Indian PLI beneficiaries seeking technology partnerships. Deepen backward integration into chlor-alkali feedstocks at Shandong and Jiangsu clusters to insulate margins from European chlorine supply volatility. Capture stranded technical-grade volume as REACH authorization filters non-compliant Asian suppliers from European contract tiers. For New Entrants and Emerging Players: Build out granule-form production capacity targeting Australian and Canadian municipal water treatment specifications where dust-exposure regulations drive form-factor substitution. India PLI scheme incentives for agrochemical intermediates offer the most penetrable entry vector through joint venture structures with Gujarat-based feedstock integrators. Lead with SCIP database compliance capabilities to unlock EU formulator procurement panels demanding batch-level traceability. For Investors and Strategic Acquirers: REACH authorization milestone reshapes the acquisition landscape by conferring durable competitive moats on toxicological documentation holders. Target European cGMP-compliant specialists with Basel-adjacent manufacturing footprints and existing pharmaceutical customer qualifications. Watch for CDSCO registration acceleration in India as signal of successful technology transfer and local supply qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive chlorine supply insulates Shandong producers from European energy-peak curtailments. |
| cGMP Certification Investment | Basel-adjacent facilities command peptide chemistry premiums through pharmacopeial compliance. |
| Continuous Flow Reactor Adoption | Swiss and German manufacturers collapse release testing timelines via real-time spectroscopic monitoring. |
| India PLI Joint Venture Formation | Gujarat feedstock integration attracts Chinese technology licensors seeking regional market access. |
| Granule Form Factor Expansion | Australian and Canadian municipalities specify compacted material for occupational safety compliance. |
Research Methodology
Desk research of customs trade databases, ECHA REACH registration filings, and chlor-alkali industry association reports preceded structured interviews with plant managers at cyanuric chloride production facilities, procurement leads at agrochemical formulators, distribution channel partners, and technical R&D directors at dye intermediate manufacturers. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis and capacity utilization assessments across the analysis window.
Assumptions held MEE dual carbon enforcement intensity, FIFRA registration pathway stability, and REACH authorization timeline progression within observed regulatory patterns across the projection horizon. Segmentation dimensions modeled include grade purity tier, end-use industry application, form factor logistics, and regional production hub concentration. CAGRs were derived from slope-log regression on normalized volume data with industry-specific inputs including herbicide formulation demand curves and pharmaceutical reagent procurement elasticity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese producers or accelerated technology transfer to Indian PLI beneficiaries would shift outcomes. Macroeconomic deviation in chlorine feedstock costs, regulatory enforcement intensity variation, or breakthrough substitution in flame-retardant applications would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Industrial Closures Market