
 Dioctyl Phthalate Market | 2026-2036
Dioctyl Phthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Dioctyl Phthalate Market Analysis
Bio-based feedstock substitution is reconfiguring conventional phthalate production economics and supplier qualification protocols across the plasticizer value chain. Eastman Chemical leverages its integrated oxo-alcohol platform to sustain cost-advantaged positions in high-purity grades. BASF SE anchors European supply through backward integration into propylene and oxo-chemistry assets. LG Chem competes on scale from its Yeosu complex, where captive naphtha cracking supports flexible output allocation.
Dioctyl phthalate is a diester of phthalic anhydride and 2-ethylhexanol, functioning primarily as a plasticizer that imparts flexibility and durability to polyvinyl chloride resins at loadings typically ranging from 30 to 50 parts per hundred. The compound lowers glass transition temperature and enhances processability in extrusion and calendering operations across wire insulation, flooring, and synthetic leather applications. Plasticizers dominate product-type revenue as the largest functional category, though margin pools are compressing under regulatory pressure on ortho-phthalates. Automotive components lead application demand structurally, driven by under-the-hood wiring harness specifications and interior trim flexibility requirements that resist migration and fogging.
REACH restrictions through ECHA and EPA action under the Toxic Substances Control Act are tightening permissible exposure limits and triggering substitution mandates in consumer-contact applications. The EU Green Deal and associated CSRD reporting obligations are forcing downstream OEMs to document plasticizer provenance and carbon intensity through supply chain tiers. Stakeholders must monitor regulatory divergence between jurisdictions where classification thresholds differ, while positioning R&D investment toward non-phthalate chemistries that preserve processing performance without triggering equivalent compliance burdens.
Market Dynamics
REACH restrictions through ECHA are forcing ortho-phthalate substitution across European flexible PVC applications, while automotive wiring harness specifications in Asia-Pacific absorb compliant plasticizer volumes at reformulated loadings.
Growth Catalysts
- Automotive wiring harness demand:Under-the-hood specifications requiring migration resistance and fogging control are pulling high-purity grades into EV and ICE vehicle platforms.
- REACH SVHC listing protocols:ECHA's candidate list expansion is redirecting procurement toward compliant alternatives and bio-based pathways that preserve processing performance.
- Construction sector scaling:Flooring and synthetic leather applications in China and India are absorbing incremental plasticizer volumes as residential and commercial building accelerates.
Market Restraints
- 2-ethylhexanol feedstock volatility:Oxo-alcohol pricing swings tied to propylene and naphtha cracker economics compress margin predictability for integrated producers.
- Substitution threat from adipates and trimellitates:Non-phthalate chemistries are capturing share in medical device and food-contact films where migration limits are most stringent.
- European supply concentration:BASF's Ludwigshafen complex and INEOS's integrated assets create bottleneck risk for regional compliant-grade availability.
Strategic Opportunities
- India cable manufacturing corridors:PLI scheme incentives for domestic wire and cable production are creating localized demand for plasticizer qualification at scale.
- Bio-based feedstock certification:ISCC PLUS and RSB chain-of-custody frameworks are enabling premium positioning for renewable-content grades in EU Green Deal procurement.
- Digital supply chain traceability:Blockchain-enabled provenance documentation is opening CSRD-compliant channels for OEMs requiring tiered carbon intensity disclosure.
Industry Challenges
- Reformulation validation timelines:OEM qualification cycles for replacement plasticizers extend 18-24 months, freezing procurement decisions during regulatory transition periods.
- Cross-jurisdictional classification divergence:EPA TSCA Section 6 risk evaluation thresholds differ from ECHA SVHC criteria, complicating unified product portfolio design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dioctyl Phthalate Market |
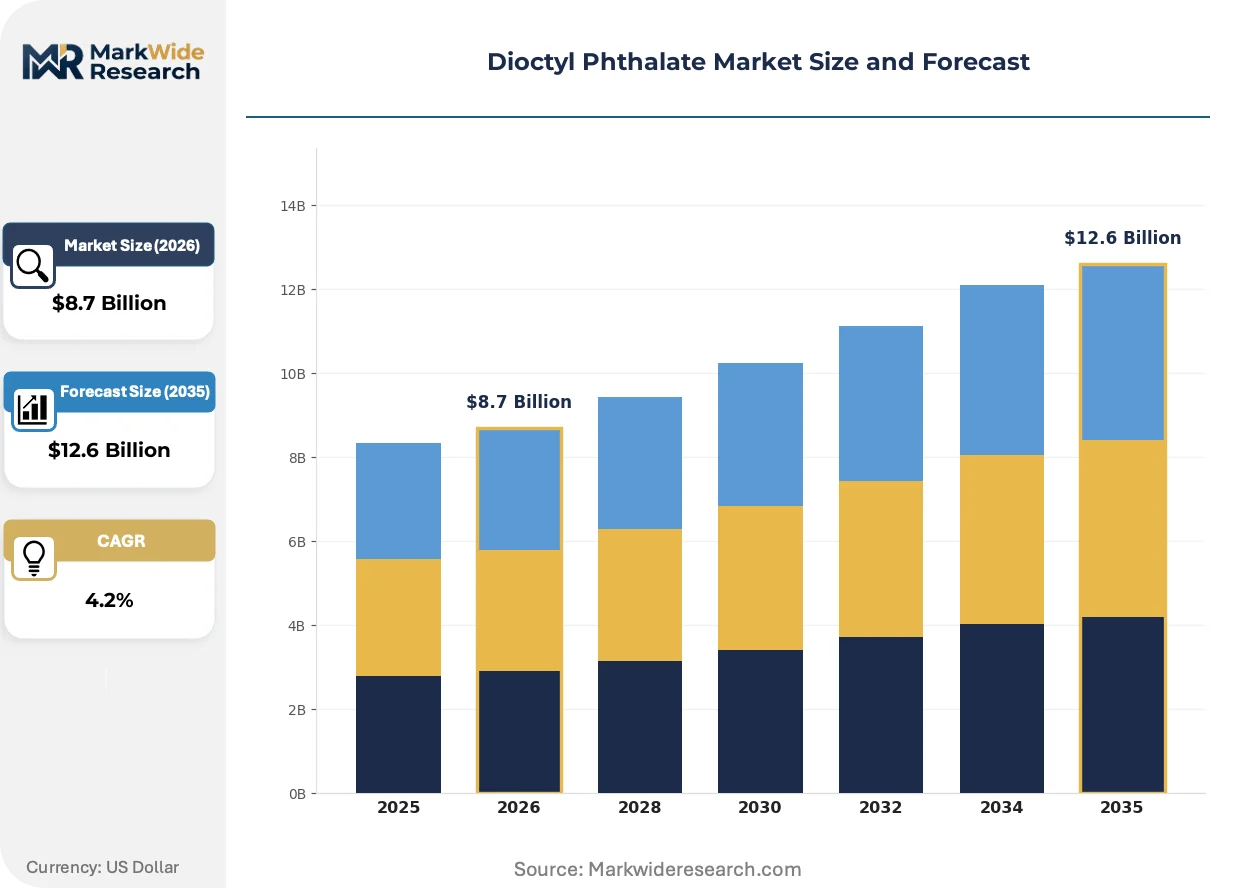
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Solvents, Adhesives, Coatings Application: Automotive Components, Flooring, Electrical Cables, Medical Devices End User: Manufacturing, Construction, Healthcare, Telecommunications Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | UPC Technology, Eastman Chemical, BASF SE, LG Chem, Nan Ya Plastics, Dow Chemicals, Aekyung Petrochemical, KLJ Plasticizers Ltd, ExxonMobil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dioctyl Phthalate Market Emerging Trajectories
Digital process control systems are compressing batch-to-batch variability in plasticizer compounding, while regulatory disclosure mandates are forcing supply chain visibility investments across tiered supplier networks.
Process analytical technology (PAT) is digitizing real-time monitoring of esterification reactions and downstream purification. Automotive cable compounders in Germany and Japan are deploying these systems to reduce off-specification rates and accelerate lot release. The technology is digitizing quality assurance workflows that previously relied on offline chromatography, compressing working capital cycles for high-volume harness producers.
ECHA's SCIP database obligations under the Waste Framework Directive are mandating article-level plasticizer disclosure across the EU internal market. Downstream OEMs must now map substance presence through complex cable and flooring assemblies. Medical device manufacturers are responding fastest, restructuring supplier contracts to force upstream data submission before 2027 enforcement deadlines.
Compounders are consolidating procurement around qualified supplier lists that pre-certify REACH and TSCA compliance status. Tier-1 automotive suppliers in Michigan and Bavaria are disintermediating spot-market traders, preferring direct long-term contracts with integrated oxo-chemical producers. This concentration is most visible in North American wire insulation, where three compounders now control majority plasticizer specification authority.
Dioctyl Phthalate Market Segmentation
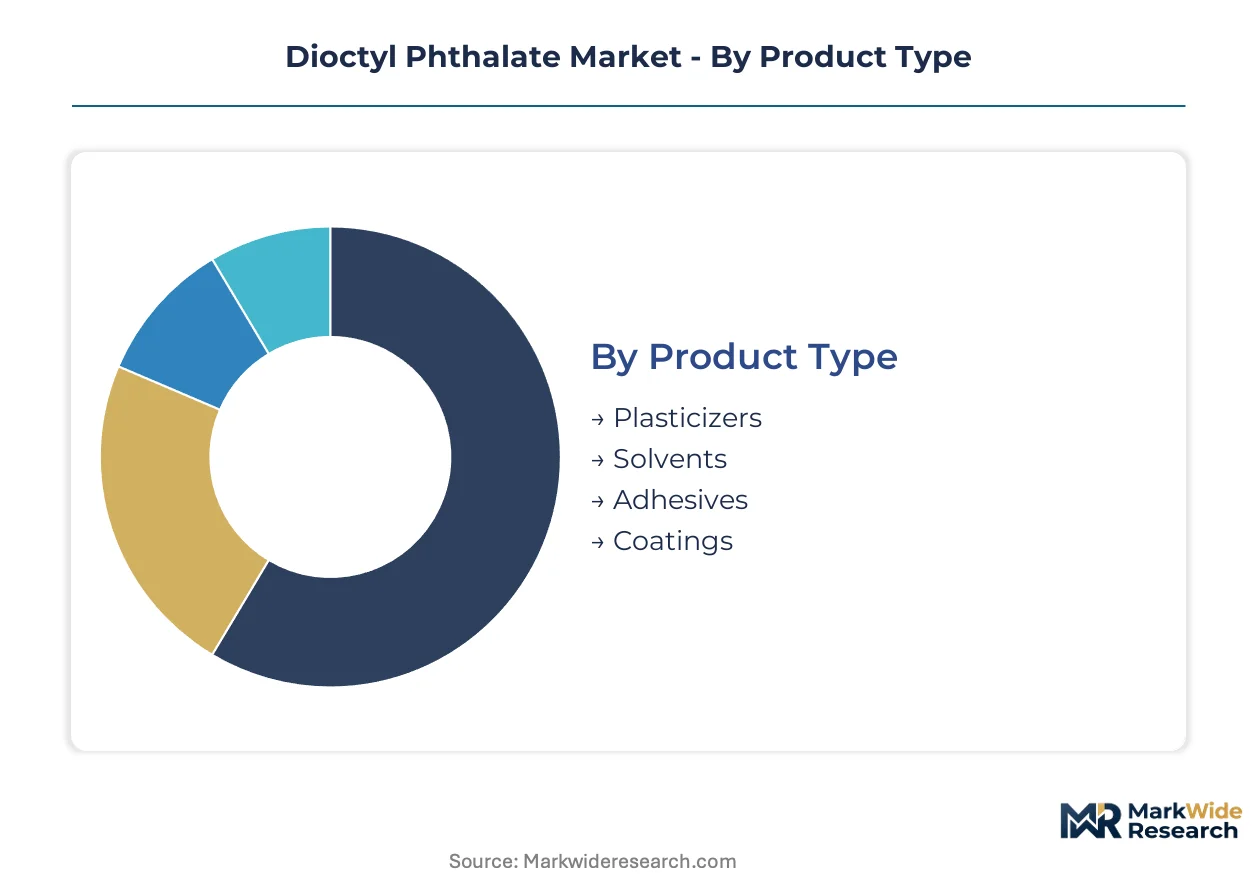
Segmentation in dioctyl phthalate procurement reveals how regulatory pressure and application-specific performance requirements fragment purchasing behavior across industries. Buyers in automotive and medical verticals operate under incompatible compliance frameworks, forcing suppliers to maintain parallel qualification streams.
Product Type:
After-sales service intensity varies sharply across product categories, with technical plasticizer grades demanding formulation support that commodity solvents never require.
- Plasticizers:Diesters of phthalic anhydride and 2-ethylhexanol formulated at 30-50 phr loadings to lower PVC glass transition temperatures. Demand concentrates in automotive wire harness specifications across Germany and Japan where migration resistance and fogging control resist substitution. ECHA SVHC protocols and EPA TSCA Section 6 evaluations are compressing margin pools while redirecting R&D toward compliant alternatives.
- Solvents:Carrier systems for coatings and printing inks leveraging dioctyl phthalate's compatibility with polar and non-polar resins. China and India absorb dominant volumes as industrial coatings production scales across Asia-Pacific manufacturing corridors. Naphtha cracker economics and propylene derivative pricing inject volatility that integrated oxo-alcohol producers mitigate through captive feedstock.
- Adhesives:Tackifier and flexibility modifiers in pressure-sensitive and structural bonding formulations.
- Coatings:Film-forming aids and plasticizing agents in protective and decorative surface treatments.
Plasticizers holds the largest share; momentum sits with reformulated grades that satisfy REACH and TSCA thresholds without sacrificing processing performance.
Application:
Application segmentation tracks divergent regulatory exposure, with medical and food-contact films facing substitution pressure that construction flooring escapes.
- Automotive Components:Under-the-hood wiring harnesses and interior trim specifications demanding migration-resistant, low-fogging plasticizer grades. EV and ICE platforms in Michigan, Bavaria, and Japan pull high-purity volumes through Tier-1 supplier qualification protocols. OEM reformulation cycles extend 18-24 months, freezing procurement decisions during regulatory transition periods.
- Flooring:Flexible vinyl sheet and tile applications absorbing incremental volume as residential and commercial construction accelerates across China and India. BIS certification requirements and PLI scheme incentives for domestic cable production are creating localized demand corridors with distinct qualification timelines.
- Electrical Cables:Wire insulation and jacketing compounds requiring flame retardance and low-temperature flexibility.
- Medical Devices:Tubing, blood bags, and film applications where FDA and EMA migration limits trigger fastest substitution toward adipates and trimellitates.
Automotive Components commands the dominant revenue position; Medical Devices faces the steepest displacement trajectory from non-phthalate chemistries.
End User:
End user segmentation maps how downstream industry structure determines procurement concentration versus fragmentation.
- Manufacturing:Compounders and converters across automotive supply chains in Germany, Japan, and Michigan consolidating procurement around qualified supplier lists that pre-certify REACH and TSCA compliance.
- Construction:Flooring and synthetic leather producers in China and India scaling volume absorption as building activity intensifies.
- Healthcare:Medical device manufacturers restructuring supplier contracts to force upstream SCIP database submission before enforcement deadlines.
- Telecommunications:Cable infrastructure deployers sourcing through distributor networks with limited formulation technical support.
Manufacturing exhibits the highest procurement concentration; Healthcare is gaining share fastest from regulatory disclosure mandates.
Distribution Channel:
Channel segmentation reflects the tension between technical specification authority and procurement efficiency.
- Direct Sales:Long-term contracts between integrated oxo-chemical producers and Tier-1 automotive compounders in North America and Europe, disintermediating spot-market traders.
- Distributors:Regional stockholding intermediaries serving mid-volume construction and cable manufacturing accounts with formulation guidance.
- Online Retail:Small-lot procurement for R&D and specialty adhesive formulations with limited technical service.
- Wholesalers:Bulk volume handlers in Asia-Pacific corridors serving price-sensitive flooring and coatings producers.
Direct Sales captures the majority plasticizer specification authority; Distributors maintains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports dioctyl phthalate volumes across Southeast Asia and South Asia as domestic oxo-alcohol capacity absorbs regional plasticizer procurement. Germany and Japan supply high-purity grades into automotive wire harness specifications across North American and European assembly plants. India scales domestic manufacturing under import substitution programs while US producers navigate EPA TSCA Section 6 risk evaluation thresholds.
China
Construction flooring and synthetic leather manufacturers in Jiangsu and Zhejiang provinces absorb dominant plasticizer volumes as residential building accelerates. NMPA and GB standards regulate chemical substance registration while provincial environmental bureaus enforce dual carbon goals on naphtha cracker operations. The Yangtze River Delta concentration of cable compounders sources captive oxo-alcohol from integrated petrochemical complexes at Ningbo and Shanghai.
Germany
Automotive wiring harness specifications from BMW and Volkswagen pull REACH-compliant plasticizer grades through Tier-1 suppliers in Bavaria and Baden-Württemberg. ECHA SVHC listing protocols and EU Green Deal carbon intensity disclosure requirements force supply chain restructuring. The Ludwigshafen chemical cluster anchors European high-purity production with backward integration into propylene derivatives.
United States
Wire insulation compounders in Michigan and Ohio consolidate procurement around qualified supplier lists as EPA TSCA Section 6 evaluations progress. NHTSA safety standards and FDA migration limits create divergent compliance frameworks across automotive and medical applications. The Gulf Coast petrochemical corridor supplies oxo-alcohol feedstock to domestic plasticizer producers facing feedstock volatility from shale gas economics.
India
PLI scheme incentives for domestic cable and wire manufacturing create localized demand corridors in Maharashtra and Gujarat. BIS certification requirements and DGFT import tariffs protect nascent domestic plasticizer capacity from Chinese competition. The Mumbai-Pune industrial belt hosts emerging compounder qualification programs for automotive harness exports to European OEMs.
Japan
Automotive cable specifications from Toyota and Honda demand low-fogging, migration-resistant grades processed through Nagoya and Tokyo-area compounders. METI chemical management policies and JIS standards govern substance disclosure in article-level supply chains. The Kansai region maintains specialized production of electronics-grade plasticizers for high-reliability insulation applications.
Dioctyl Phthalate Market Vendor Landscape
On the supply side, the industry is consolidating around integrated oxo-chemical producers with captive naphtha cracking and propylene derivative assets. Three strategic archetypes dominate: Asian petrochemical conglomerates with scale advantages, European specialty chemical groups with regulatory compliance expertise, and North American diversified materials companies with Gulf Coast feedstock access. Competitive moves center on backward integration into 2-ethylhexanol production and long-term contract consolidation with Tier-1 automotive compounders.
Among Asian producers, UPC Technology, LG Chem, and Nan Ya Plastics exemplify the scale-driven archetype with integrated manufacturing complexes serving regional cable and construction markets. Eastman Chemical and BASF SE occupy positions within the compliance-focused tier, leveraging European and North American regulatory expertise to supply automotive OEM qualification programs. These named companies represent the concentration of supply-side capability without exhausting the competitive field.
| Leading Market Players |
|---|
| UPC Technology |
| Eastman Chemical |
| BASF SE |
| LG Chem |
| Nan Ya Plastics |
| Dow Chemicals |
| Aekyung Petrochemical |
| KLJ Plasticizers Ltd |
| ExxonMobil |
| Others |
Supply Flow & Price Mechanics
Captive oxo-alcohol production in China, South Korea, and Germany concentrates margin capture upstream, forcing downstream compounders in Michigan and Bavaria to absorb feedstock volatility through long-term contract structures that lock in specification authority.
Pricing Analysis
Current-generation high-purity automotive grades command premium positioning against prior-generation standard industrial grades and emerging next-generation bio-based alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by REACH/TSCA certification tier and captive 2-ethylhexanol integration. Cost compression in standard grades is intensifying because naphtha cracker economics inject propylene derivative volatility. Construction flooring producers in India exhibit highest price sensitivity; automotive harness compounders in Germany show lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Integrated oxo-chemical producers including BASF at Ludwigshafen, LG Chem at Yeosu, and Eastman Chemical at Kingsport hold dominant conversion capacity. Geographic supply concentrates in China, Germany, and South Korea as downstream compounding scales across India and Southeast Asia. Feedstock draws from propylene derivatives, naphtha cracking economics, and bio-based alcohol pilot streams. Single-source vulnerability runs through European high-purity grade availability given BASF's regional concentration. Distribution runs through direct long-term contracts with Tier-1 automotive suppliers, disintermediating spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Tier-1 automotive compounders in Michigan and Bavaria, fragmenting specification authority away from distributors and forcing upstream restructuring around qualified supplier lists.
For Market Incumbents: Insulate margin pools by deepening captive 2-ethylhexanol production and accelerating ISCC PLUS certification for bio-based grade pipelines before 2027 SCIP enforcement deadlines. Defensive consolidation around long-term supply agreements with BMW and Volkswagen harness producers counters substitution threats from adipate and trimellitate chemistries in medical device applications. For New Entrants and Emerging Players: Pursue qualification gaps in India's PLI-supported cable manufacturing corridors, where domestic compounding capacity is scaling faster than local plasticizer supply. White-space exists in bio-based feedstock certification for EU Green Deal procurement channels. A direct sales model with technical formulation support outperforms distributor relationships for automotive harness penetration. For Investors and Strategic Acquirers: Capital is best deployed toward integrated oxo-chemical specialists with backward control over propylene derivatives and established REACH/TSCA qualification protocols. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale alone. Monitor ECHA SVHC list expansion velocity and EPA TSCA Section 6 evaluation timelines as inflection signals for substitution trajectory acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 2-Ethylhexanol | Captive oxo-alcohol production insulates margin pools from naphtha cracker volatility at Ludwigshafen and Yeosu complexes. |
| ISCC PLUS Certification Investment | Bio-based feedstock chain-of-custody unlocks premium positioning for EU Green Deal procurement by BMW and Volkswagen. |
| Long-term Supply Agreement Consolidation | Direct contracts with Tier-1 automotive compounders in Michigan disintermediate spot-market traders and freeze specification authority. |
| Digital Process Control Deployment | PAT-enabled real-time esterification monitoring accelerates lot release for high-volume harness producers in Nagoya and Bavaria. |
| Regional Capacity Addition in India | Domestic plasticizer production under PLI scheme incentives captures cable manufacturing demand in Maharashtra and Gujarat corridors. |
Methodological Framework
Operator-level perspectives from plant managers at integrated oxo-chemical complexes, procurement leads at Tier-1 automotive harness compounders, technical R&D directors at flexible PVC formulators, and distribution channel partners in Asia-Pacific anchored the qualitative base. Primary fieldwork combined with secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance registration databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions covering grade tier (high-purity automotive versus standard industrial), end-use industry (automotive wire harness, construction flooring, medical device, electrical cable), and regional production hub concentration. CAGRs derived from elasticity-adjusted demand modeling incorporating automotive production forecasts, construction activity indices, and regulatory substitution timelines. Industry-specific inputs included ECHA SVHC candidate list velocity and EPA TSCA Section 6 evaluation progress.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian petrochemical conglomerates or accelerated bio-based feedstock scale-up by European specialty groups would shift outcomes. Forecasts assume regulatory divergence between ECHA and EPA thresholds persists without harmonization. Quarterly review of ECHA SVHC list additions, EPA TSCA evaluation milestones, and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Anthracene Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Bromobenzene Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Acrylic Acid Market