
 Shrink Tanks Market | 2026-2036
Shrink Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Tanks Market Analytics
The EU F-Gas Regulation is pivoting industrial buyers toward cryogenic shrink-fit systems that eliminate conventional refrigerant dependencies. Chart Industries leverages its liquefied gas handling heritage to anchor North American supply chains for precision manufacturing customers. INOXCVA dominates stainless steel fabrication for double-chamber configurations serving pharmaceutical cleanroom standards. Cryo-Tech Industrial Company specializes in custom capacity vessels that navigate the tooling requirements of Germany's automotive tier-one suppliers.
Shrink tanks are vacuum-insulated or non-insulated pressure vessels engineered to maintain cryogenic temperatures between minus 150 and minus 196 degrees Celsius, enabling thermal contraction of metal components for interference-fit assembly in precision engineering. Stainless steel construction leads material selection due to thermal cycling durability and cleanroom compatibility, while composite alternatives gain traction in weight-sensitive aerospace tooling applications. Double-chamber designs command premium positioning by isolating active cooling zones from loading bays, reducing thermal loss and nitrogen consumption during batch operations. The Food & Beverage end-user segment represents the fastest-growing demand pool as processors adopt shrink-fit methods for sanitary equipment maintenance and high-speed line changeovers.
The EPA enforces refrigerant management standards that constrain conventional cooling approaches in US manufacturing facilities, while REACH compliance in Europe mandates material traceability for cryogenic vessel steels and sealing compounds. China's GB standards for pressure equipment safety create certification barriers for imported shrink tank designs, favoring domestic fabricators with SAMR approval pathways. Stakeholders must monitor evolving refrigerant phase-down schedules and pressure equipment directives to align product portfolios with regional compliance architectures.
Market Dynamics
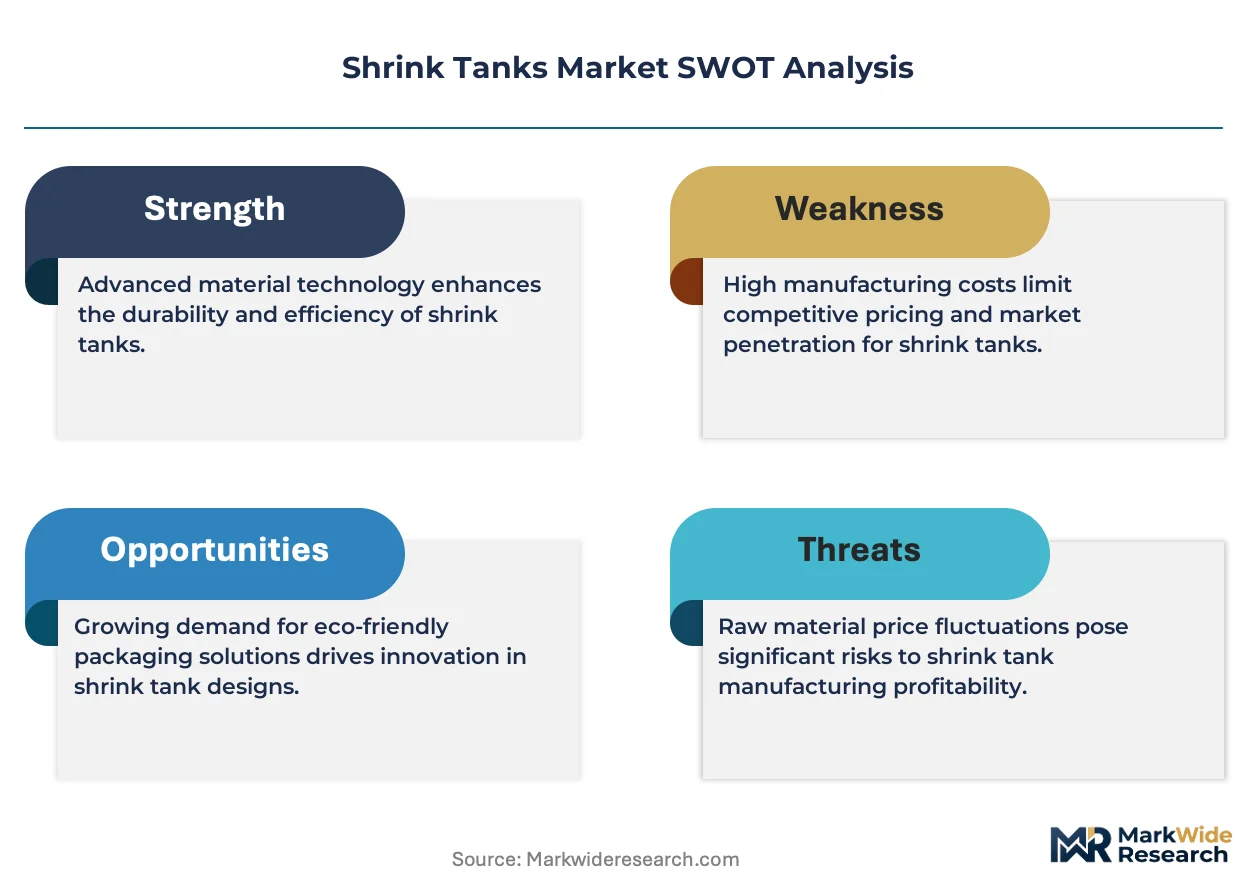
The EU F-Gas Regulation is compressing refrigerant-dependent cooling architectures and rerouting capital toward cryogenic shrink-fit infrastructure across precision manufacturing clusters. This regulatory pivot is redrawing equipment procurement criteria and supplier qualification protocols in real time.
Growth Catalysts
- REACH compliance architecture:Material traceability mandates for cryogenic vessel steels are locking in stainless steel specifications that favor established fabricators with certified supply chains.
- Food & Beverage line changeover velocity:Sanitary equipment maintenance protocols are incorporating shrink-fit methods to compress tooling swap cycles and reduce downtime penalties.
- German automotive tooling density:Tier-one supplier clusters in Stuttgart and Munich are driving specialized tank procurement for precision interference-fit assembly operations.
Market Restraints
- Liquid nitrogen supply volatility:Cryogen production concentration among industrial gas majors creates input cost exposure for shrink tank operators.
- GB standards certification friction:China's SAMR pressure equipment directives impose testing timelines that delay imported vessel market entry.
- Conventional refrigerant residual inertia:Legacy cooling infrastructure in mature manufacturing bases slows capital redeployment toward cryogenic alternatives.
Strategic Opportunities
- Pharmaceutical cleanroom expansion:Double-chamber configurations meeting ISO 14644 standards are penetrating aseptic processing facilities in Ireland and Switzerland.
- Composite vessel aerospace adoption:Weight-sensitive tooling applications are opening specification windows for carbon-fiber-reinforced alternatives to stainless steel construction.
- IRAct energy transition incentives:US manufacturing facilities accessing federal credits for industrial decarbonization are prioritizing refrigerant-free cooling architectures.
Industry Challenges
- Cryogenic welding certification scarcity:Qualified technicians for stainless steel vessel fabrication command wage premiums that compress fabricator margins.
- Dual-chamber integration complexity:Sealing system engineering for isolated cooling zones extends commissioning timelines and elevates field service requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Tanks Market |
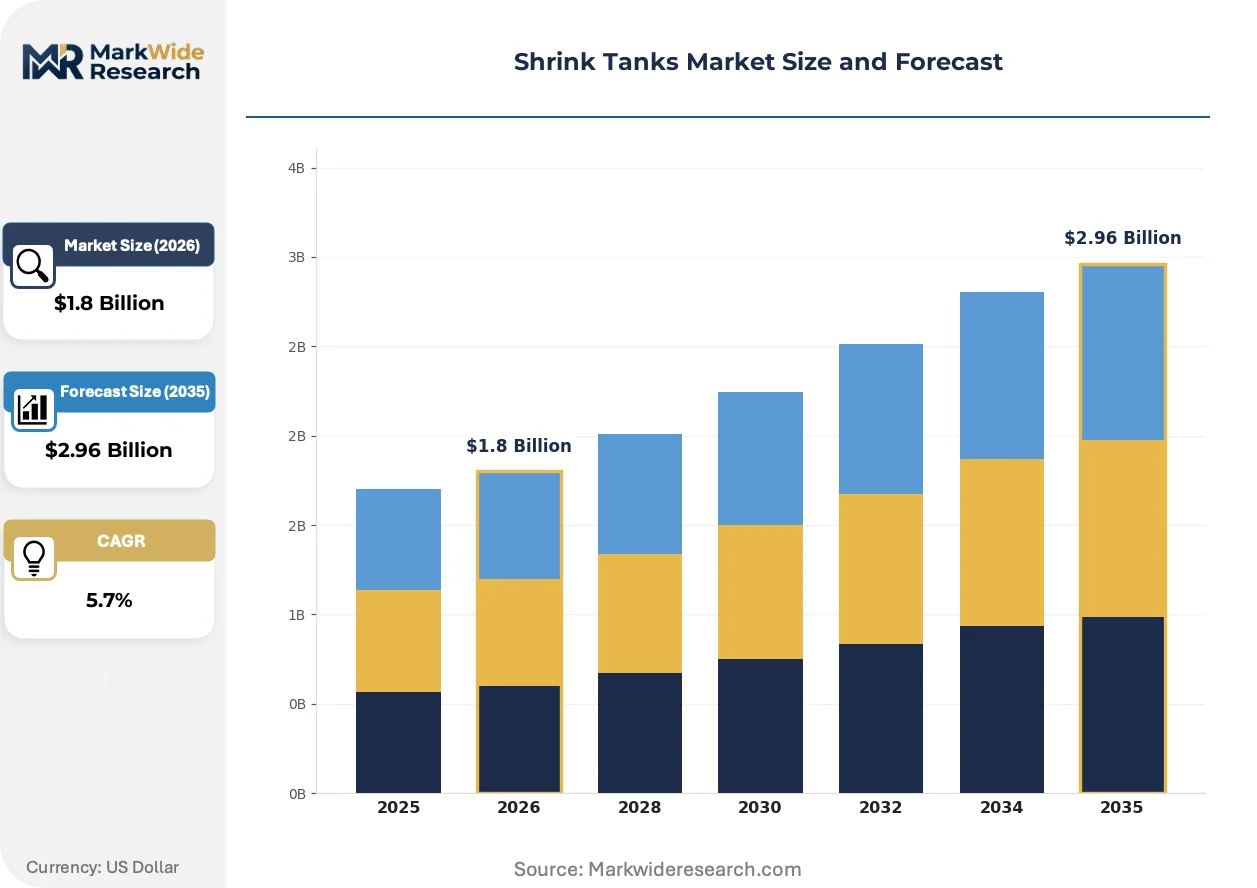
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Double Chamber, Insulated, Non-Insulated Material: Stainless Steel, Carbon Steel, Plastic, Composite End User: Manufacturing, Food & Beverage, Chemicals, Pharmaceuticals Capacity: Small, Medium, Large, Custom |
| Companies Covered | Cryo-Tech Industrial Company, INOXCVA, Chart Industries, Auguste Cryogenics, Wessington Cryogenics, Linde Engineering, Cryofab, Cryolor, Taylor-Wharton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Tanks Market Evolving Landscape
Cryogenic shrink-fit systems are displacing mechanical pressing and thermal expansion methods across interference-fit assembly operations. Equipment architecture, refrigerant chemistry, and procurement contracting are all undergoing simultaneous revision.
Vacuum-insulated double-chamber designs are converging with automated loading systems to enable batch processing without thermal loss penalties. Automotive transmission manufacturers in Germany are adopting these configurations for gear-shaft assembly lines. The technology is converging with nitrogen recovery systems to reduce operating cost structures and extend service intervals.
The EPA refrigerant management standards are constraining conventional cooling approaches in US manufacturing facilities. Facilities exceeding threshold refrigerant volumes face reporting burdens and leak detection mandates. Processors in California and Texas are accelerating cryogenic shrink-fit evaluations to eliminate regulatory exposure entirely.
Service contracting is unbundling from equipment supply as buyers seek performance guarantees on thermal cycle consistency. Aftermarket nitrogen logistics and vessel recertification are separating from initial capital transactions. This pattern is most visible among Food & Beverage processors managing seasonal volume spikes.
Shrink Tanks Market Segmentation
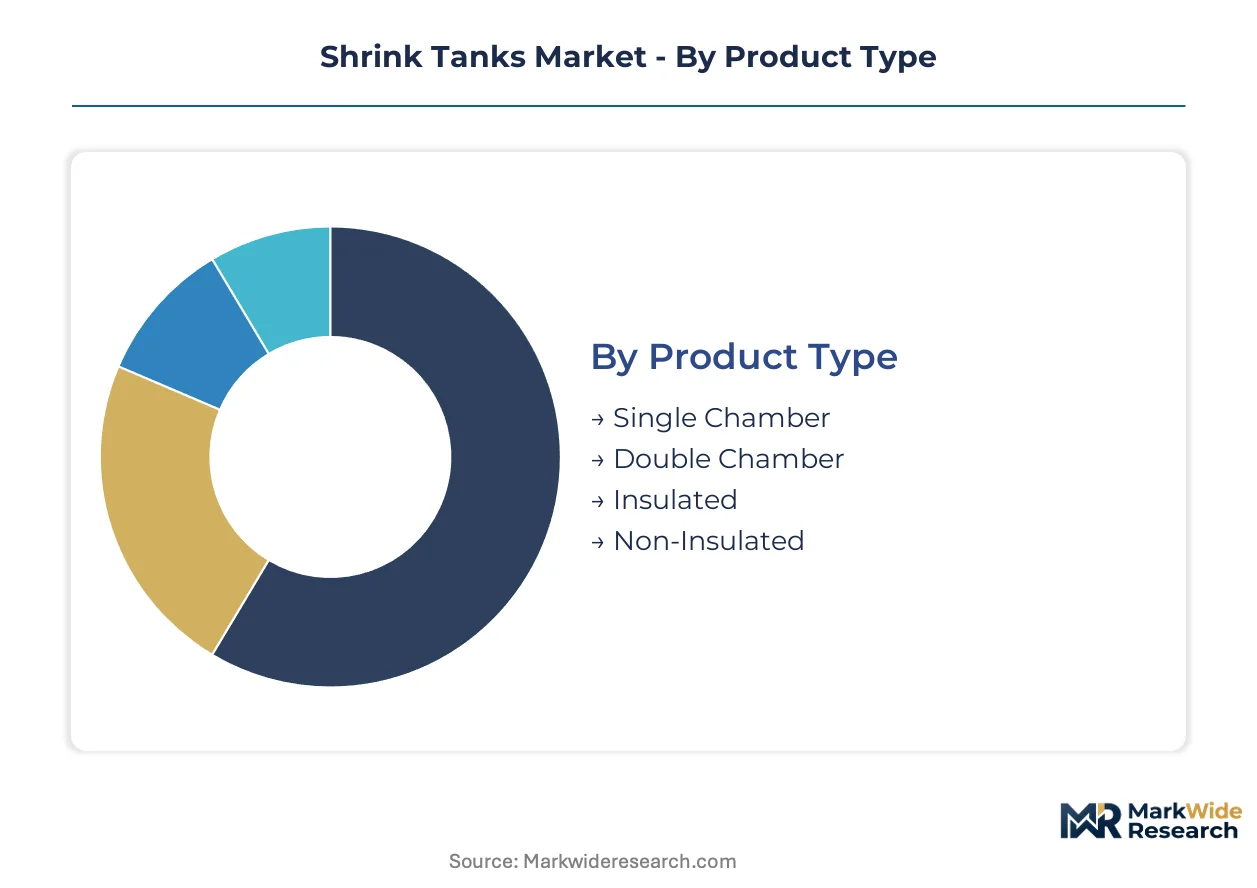
Segmentation in shrink tanks reveals how procurement criteria diverge across precision manufacturing, regulatory-intensive processing, and custom tooling applications. Supply-side capabilities cluster around material certification and chamber engineering, creating distinct competitive arenas.
Product Type:
Supply concentration among vacuum-insulation specialists and chamber-integration engineers shapes competitive positioning across product architectures.
- Single Chamber:Simplified vessel geometry with integrated cooling and loading zones reduces capital outlay for entry-level shrink-fit operations. German automotive toolrooms deploy these units for standardized gear-shaft assemblies where batch consistency outweighs nitrogen efficiency concerns. REACH-compliant stainless steel specifications dominate procurement criteria.
- Double Chamber:Isolated active cooling zones separated from loading bays cut thermal loss and extend nitrogen hold times. Pharmaceutical cleanrooms in Ireland and Switzerland specify these configurations for ISO 14644-compliant aseptic processing. Sealing system complexity elevates field service requirements and commissioning timelines.
- Insulated:Vacuum-insulated panels or multi-layer insulation systems maintain cryogenic temperatures with reduced boil-off rates.
- Non-Insulated:Open-top or minimally protected designs serve short-cycle operations where rapid access trumps thermal efficiency.
Double Chamber absorbs the bulk of installed capacity in pharmaceutical and aerospace precision clusters; Single Chamber is expanding most quickly among tier-two automotive suppliers and maintenance workshops.
Material:
Cost tier stratification separates certified supply chains from commodity alternatives, with traceability mandates locking in premium specifications.
- Stainless Steel:Austenitic grades 304 and 316 dominate for thermal cycling durability and cleanroom compatibility. ECHA REACH mandates on material traceability favor established fabricators with mill-certified supply chains. Food & Beverage processors specify these grades for sanitary equipment maintenance protocols.
- Carbon Steel:Lower alloy content reduces raw material costs for non-sanitary industrial applications with limited thermal cycling demands. Chemical processors in cost-sensitive regions specify these vessels for intermittent shrink-fit operations where corrosion resistance requirements are moderate.
- Plastic:Polymer-based liners or structural components reduce weight in portable or temporary installations.
- Composite:Carbon-fiber-reinforced alternatives penetrate weight-sensitive aerospace tooling applications where every kilogram of vessel mass translates to handling efficiency gains.
Stainless Steel commands the dominant share of value and certification-intensive applications; Composite is climbing the fastest among next-generation mobility and satellite manufacturing programs.
End User:
Application-specific performance requirements drive divergent specifications across interference-fit precision, sanitary protocols, and chemical handling environments.
- Manufacturing:Automotive transmission plants and precision toolrooms deploy shrink tanks for gear-shaft, bearing, and spindle assemblies. Stuttgart and Munich clusters drive specialized procurement with tight tolerance requirements and high-throughput line integration.
- Food & Beverage:Sanitary equipment maintenance and high-speed line changeovers adopt shrink-fit methods to compress tooling swap cycles. Seasonal volume spikes push processors toward unbundled service contracts covering nitrogen logistics and vessel recertification.
- Chemicals:Process equipment maintenance and specialty piping installations require corrosion-resistant specifications.
- Pharmaceuticals:Aseptic processing facilities demand double-chamber configurations with validated thermal cycle consistency and comprehensive documentation packages.
Manufacturing retains the largest installed base and replacement demand; Food & Beverage is gaining share fastest as line velocity pressures intensify across processing networks.
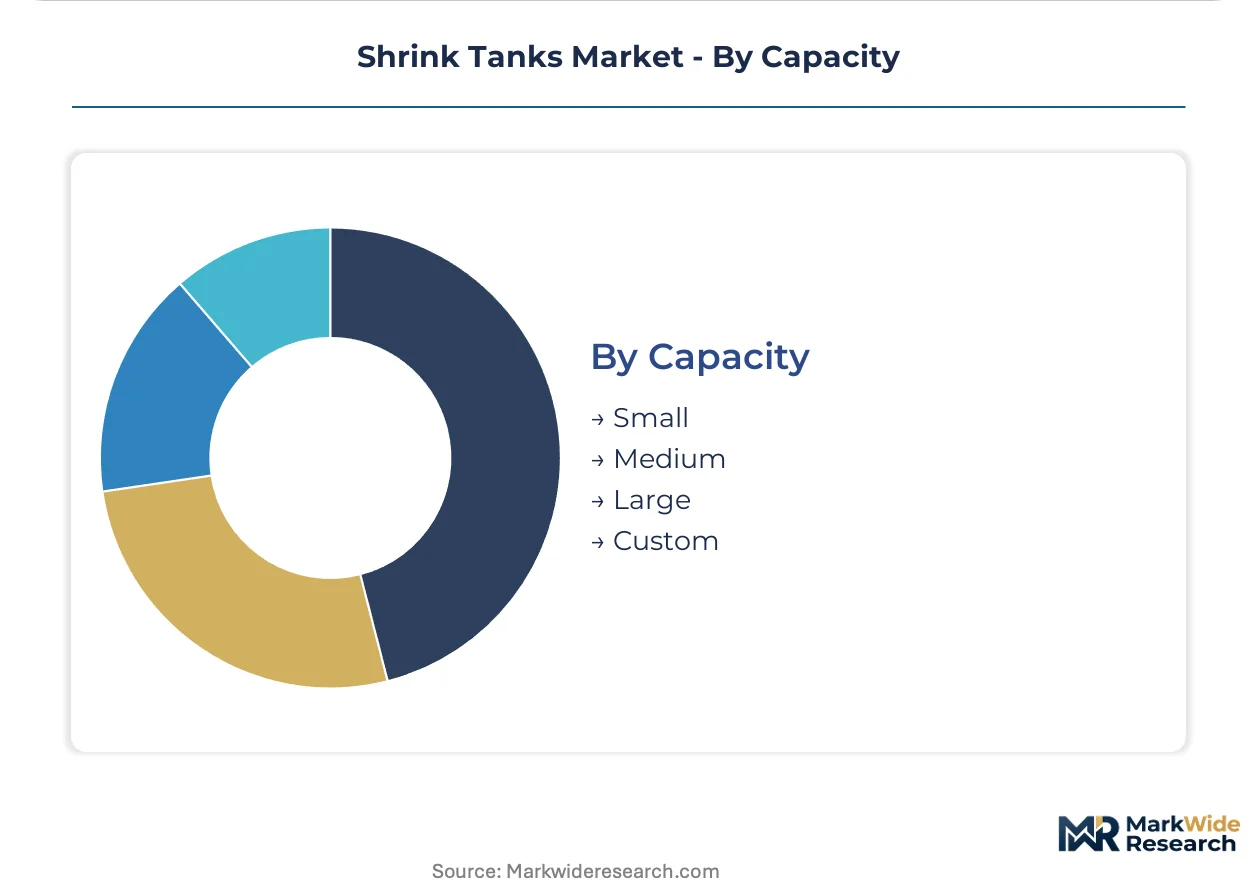
Capacity:
Customer type and volume scale determine specification windows, from benchtop units to integrated production line systems.
- Small:Compact footprints suit maintenance workshops and prototype development cells with intermittent batch requirements.
- Medium:Standardized dimensions align with mid-volume manufacturing lines and multi-shift operations.
- Large:High-throughput configurations serve dedicated production lines with continuous shrink-fit integration.
- Custom:Bespoke vessel geometries and capacity ratings navigate specialized tooling requirements for Germany's automotive tier-one suppliers and aerospace component manufacturers.
Medium and Large capacities dominate current procurement volumes; Custom specifications are expanding most quickly as precision engineering applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision manufacturing demand for shrink tanks, with automotive transmission plants driving specialized vessel procurement across interference-fit assembly lines.
Germany
Automotive tier-one suppliers in Stuttgart and Munich deploy custom-capacity shrink tanks for gear-shaft precision assembly. The EU F-Gas Regulation accelerates transitions toward refrigerant-free cryogenic cooling architectures. Bavarian tooling clusters command premium double-chamber configurations with nitrogen recovery integration.
United States
EPA refrigerant management standards constrain conventional cooling in California and Texas manufacturing facilities. The Inflation Reduction Act energy transition incentives prioritize industrial decarbonization investments. Processors in the Great Lakes automotive corridor evaluate cryogenic shrink-fit systems to eliminate regulatory reporting burdens.
China
GB standards pressure equipment certification creates market entry friction for imported vessel designs. SAMR approval pathways favor domestic fabricators with established testing relationships. Yangtze River Delta automotive clusters source locally certified shrink tanks for precision assembly operations.
Switzerland
Pharmaceutical cleanroom expansion in Basel and Geneva drives double-chamber specification for ISO 14644-compliant aseptic processing. Swissmedic oversight of manufacturing equipment elevates documentation and validation requirements. Precision engineering clusters around Zurich specify vacuum-insulated configurations for satellite component assembly.
India
Bureau of Indian Standards pressure vessel certification shapes procurement criteria for domestic manufacturing facilities. PLI scheme incentives for precision engineering support tooling infrastructure investments. Maharashtra automotive hubs in Pune and Mumbai adopt shrink-fit methods for transmission component assembly.
Shrink Tanks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and chamber engineering complexity. The vendor base stratifies between stainless steel specialists with mill-certified supply chains and regional fabricators serving cost-sensitive intermittent applications. Three archetypes dominate: liquefied gas handling heritage firms, stainless steel vessel fabricators with cleanroom credentials, and custom-capacity specialists navigating automotive tooling requirements. Competitive moves concentrate on strategic partnerships for nitrogen logistics integration and geographic expansion through SAMR-certified manufacturing presence.
Within the heritage-anchored tier, Chart Industries represents North American supply chain positioning for precision manufacturing customers. INOXCVA exemplifies stainless steel fabrication dominance for double-chamber pharmaceutical configurations. Cryo-Tech Industrial Company occupies the custom-capacity specialist position serving Germany's automotive tier-one supplier clusters.
| Leading Market Players |
|---|
| Cryo-Tech Industrial Company |
| INOXCVA |
| Chart Industries |
| Auguste Cryogenics |
| Wessington Cryogenics |
| Linde Engineering |
| Cryofab |
| Cryolor |
| Taylor-Wharton |
| Others |
Value Network & Pricing Analysis
Liquid nitrogen spot pricing indices cascade through shrink tank supply chains into three distinct procurement tiers, with stainless steel mill surcharges amplifying cost stratification between REACH-certified fabricators and commodity vessel producers.
Pricing Analysis
Throughput-based pricing anchors procurement contracts for double-chamber pharmaceutical configurations, with buyers paying premiums tied to validated thermal cycle consistency and nitrogen recovery integration. Pricing stratifies across premium, standard, and economy tiers based on chamber complexity and certification documentation depth. Cost compression in single-chamber segments is intensifying as regional fabricators compete for tier-two automotive maintenance workshop demand. Food & Beverage processors exhibit highest price sensitivity due to seasonal volume volatility, while pharmaceutical cleanroom operators prioritize performance guarantees over capital outlay.
Supply Chain Analysis
Liquid nitrogen production rests on industrial gas majors concentrated in Germany, the United States, and China, creating input cost exposure for shrink tank operators dependent on cryogen logistics networks. Raw material dependencies center on austenitic stainless steel grades 304 and 316 from mill-certified European suppliers, vacuum-insulation panel substrates, and specialized sealing compounds meeting REACH traceability mandates. Single-source vulnerability in cryogenic welding certification creates qualified technician scarcity that extends commissioning timelines. Distribution runs through OEM-direct channels for custom-capacity pharmaceutical configurations and regional distributor networks for standardized single-chamber units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shrink tanks market functions as a cost-of-compliance story where EU F-Gas Regulation phase-down schedules erect barrier-to-entry moats favoring fabricators with established refrigerant-free cryogenic architectures and certified material traceability systems.
For Market Incumbents: Hedge nitrogen supply volatility through long-term offtake agreements with industrial gas majors operating liquefaction capacity near Stuttgart and Munich automotive clusters. Defend margin position by deepening backward integration into stainless steel mill relationships that lock in REACH-compliant grade 316 allocations ahead of traceability mandate tightening. For New Entrants and Emerging Players: Enter via composite vessel specifications for aerospace satellite manufacturing programs in Switzerland and Germany, where weight-sensitive tooling applications remain underpenetrated by incumbent stainless steel specialists. Target tier-two automotive maintenance workshops in India's Maharashtra corridor with single-chamber units featuring simplified certification pathways under Bureau of Indian Standards pressure vessel directives. For Investors and Strategic Acquirers: Distressed-cycle entries favor custom-capacity specialists with SAMR-certified manufacturing presence in China's Yangtze River Delta, where GB standards friction delays imported vessel market entry and creates captive demand for domestic fabrication capabilities. Watch liquid nitrogen infrastructure buildout rates as the inflection indicator for cryogenic shrink-fit adoption velocity across precision manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Nitrogen Recovery System Integration | Reduces operating cost structures for Bavarian automotive transmission manufacturers adopting double-chamber configurations. |
| SAMR Certification Pathway Investment | Unlocks market access for imported vessel designs navigating China's GB standards pressure equipment directives. |
| Composite Vessel R&D Partnership | Opens specification windows for carbon-fiber-reinforced alternatives in Swiss satellite component assembly operations. |
| REACH-Compliant Supply Chain Lock-in | Secures mill-certified stainless steel allocations ahead of ECHA material traceability mandate intensification. |
| Unbundled Service Contract Expansion | Captures aftermarket nitrogen logistics and vessel recertification revenue from Food & Beverage processors managing seasonal spikes. |
Research Methodology
Multi-period observation of nitrogen infrastructure buildout rates, EU F-Gas Regulation compliance timelines, and automotive tooling procurement cycles anchored the trend analysis, supplemented by interviews with plant engineers at German transmission manufacturers, pharmaceutical cleanroom facility managers in Switzerland, and aftermarket service heads at industrial gas distributors. Secondary validation drew from ECHA REACH substance databases, SAMR pressure equipment certification registries, and SEC filings of liquefied gas handling equipment suppliers. Bottom-up vessel shipment tracking across capacity tiers converged with top-down industrial gas consumption modeling to establish market sizing boundaries.
Input-output matrices mapped cryogen demand drivers to shrink tank installation rates across the projection horizon, with segmentation dimensions spanning chamber architecture, material grade certification, end-use industry, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns against automotive production forecasts and pharmaceutical cleanroom expansion pipelines. Industry-specific forecast inputs incorporated nitrogen spot price volatility indices and stainless steel surcharge trajectories from European mill reporting.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU refrigerant phase-down schedules or prolonged SAMR certification delays for imported vessel designs. Forecasts reflect documented assumptions regarding nitrogen logistics infrastructure maturation and REACH traceability mandate enforcement intensity. A small set of named triggers warrants ongoing watch: industrial gas major consolidation activity, GB standards testing timeline revisions, and IRA energy transition credit allocation clarity for refrigerant-free cooling architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Couplings Market
Industrial Materials
Metal Heat Treatment Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Tooling Board Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
GCC Heat Treating Market