
 Polymer Modified Bitumen (PMB) Market | 2026-2036
Polymer Modified Bitumen (PMB) Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Modified Bitumen (PMB) Market Analysis
Aftermarket service revenue from road maintenance contracts is narrowing as state agencies shift toward full-lifecycle pavement procurement. Shell plc leverages its integrated bitumen-polymer supply chain to secure long-term infrastructure tenders across Asia-Pacific. TotalEnergies anchors its position through proprietary SBS blending technology that extends pavement durability in tropical climates. NYNAS AB specializes in naphthenic base oils that improve low-temperature elasticity for Nordic and alpine applications.
Polymer Modified Bitumen comprises conventional bitumen blended with synthetic polymers, typically styrene-butadiene-styrene (SBS) at 3-7% by weight, to enhance elastic recovery, rutting resistance, and thermal stability across temperature extremes from -40°C to 80°C. The material serves primarily as a high-performance binder for asphalt pavements and waterproofing membranes where standard bitumen would deform or crack. Styrene-Butadiene-Styrene formulations dominate volume due to their proven performance in heavy-traffic road construction, while Ethylene-Vinyl Acetate segments occupy narrower niches in roofing and waterproofing where flexibility and adhesion properties command premium positioning. Road Construction applications sustain the largest revenue pool, though Waterproofing is accelerating as building codes in flood-prone regions mandate enhanced membrane standards.
The US Federal Highway Administration (FHWA) and state DOTs enforce Superpave performance-graded binder specifications that effectively mandate polymer modification for interstate highways in extreme climate zones. India's BIS certification requirements and the Ministry of Road Transport and Highways' technical standards for national highway projects create compliance barriers that favor established compounders with testing infrastructure. Europe's REACH regulation and ECHA substance restrictions on aromatic oils in bitumen formulations are reshaping formulation chemistry across the supply base. Stakeholders must monitor how evolving green procurement criteria and recycled content mandates in public infrastructure tenders redefine competitive qualification thresholds.
Market Dynamics
India's Bureau of Indian Standards has tightened polymer content specifications, forcing manufacturers to rebuild formulation chemistry around certified SBS percentages rather than conventional blending ratios. This regulatory compression is redrawing competitive qualification thresholds across the supply base.
Growth Catalysts
- Highway Resurfacing Mandates:India's Ministry of Road Transport and Highways specifies PMB for national highway projects, creating guaranteed offtake volumes for certified compounders.
- REACH Aromatic Oil Restrictions:ECHA substance restrictions on aromatic oils in bitumen formulations are accelerating cleaner polymer chemistry adoption across European supply chains.
- Tropical Climate Durability Requirements:State highway departments in Maharashtra and Gujarat now mandate PMB for high-traffic corridors where thermal cycling degrades conventional binders.
Market Restraints
- Styrene-Butadiene-Styrene Feedstock Volatility:SBS polymer prices track butadiene monomer markets, exposing formulators to petrochemical margin squeezes without pass-through mechanisms in fixed-price tenders.
- Testing Infrastructure Concentration:BIS certification requires specialized rheological testing equipment that concentrates in Mumbai, Chennai, and Delhi, excluding regional blenders from national highway qualification.
- Recycled Asphalt Pavement Substitution:Warm-mix asphalt technologies with high RAP content are displacing virgin PMB in lower-tier road maintenance contracts across several Indian states.
Strategic Opportunities
- Waterproofing Membrane Code Expansion:Building codes in flood-prone coastal districts are mandating enhanced elastomeric membrane standards, opening non-road revenue pools for SBS-EVA hybrid formulations.
- Full-Lifecycle Pavement Procurement:State agencies are piloting performance-based contractor payments tied to 10-year rutting indices, rewarding suppliers with proven tropical durability data.
- Superpave Performance-Grade Export Alignment:Indian compounders with BIS-recognized laboratories can cross-certify against FHWA binder specifications for Southeast Asian infrastructure tenders.
Industry Challenges
- Polymer-Bitumen Compatibility Expertise Gap:Formulation chemists with simultaneous mastery of naphthenic base oil selection and SBS grafting protocols are concentrated at a handful of legacy refiners.
- BIS Certification Timeline Compression:New product qualification requires 180-day accelerated aging protocols that delay tender participation for modified formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Modified Bitumen (PMB) Market |
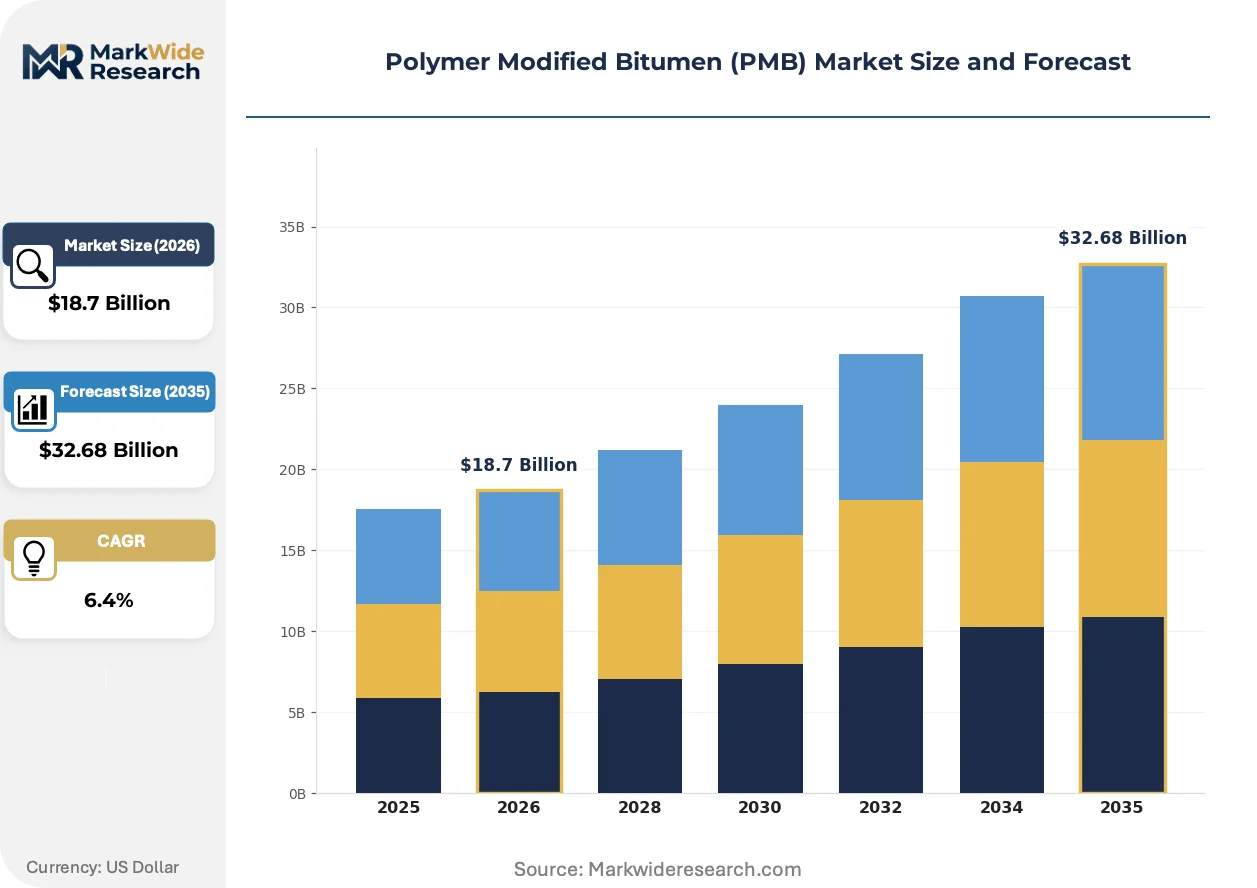
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene-Butadiene-Styrene, Styrene-Butylene-Styrene, Ethylene-Vinyl Acetate, Rubberized Bitumen Application: Road Construction, Waterproofing, Roofing, Paving End User: Construction Companies, Infrastructure Developers, Road Maintenance Agencies, Manufacturers Technology: Hot Mix, Cold Mix, Emulsion, Crumb Rubber |
| Companies Covered | Oil India Limited, Gazprom, Shell plc, Lagan Asphalt Group, NYNAS AB, Exxon Mobil Corporation, Sika AG, Benzene International Pte Ltd, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Modified Bitumen (PMB) Market Emerging Trajectories
Formulation intelligence and procurement digitization are converging to compress specification-to-delivery cycles. Three developments are restructuring how PMB moves from refinery blending to pavement placement.
Real-time viscosity monitoring through IoT-enabled tank farm sensors is digitizing quality assurance workflows. State highway department labs in Gujarat are piloting continuous rheology tracking that replaces batch sampling with live polymer dispersion verification. This compression of testing protocols is enabling just-in-time blending decisions that reduce inventory carrying costs for toll-road operators.
REACH substance restrictions on polycyclic aromatic hydrocarbons in extender oils are forcing base oil substitution strategies. European formulators are pivoting toward Group III naphthenic stocks that maintain low-temperature elasticity without aromatic content. Indian compounders serving export markets are pre-emptively aligning formulation archives to ECHA compliance timelines ahead of domestic adoption.
Performance-graded binder procurement is displacing generic penetration-grade purchasing in state tender documents. Maharashtra's Public Works Department now specifies PG 76-22 binders for elevated corridor projects, forcing contractors to source certified PMB rather than conventional bitumen. This specification upgrade is concentrating contract awards among compounders with in-house Superpave testing capability.
Polymer Modified Bitumen (PMB) Market Segmentation
PMB formulation chemistry and placement methods fragment the market into distinct technical tiers. Specification standards from BIS, FHWA, and ECHA create compliance boundaries that reshape competitive positioning across each segment boundary.
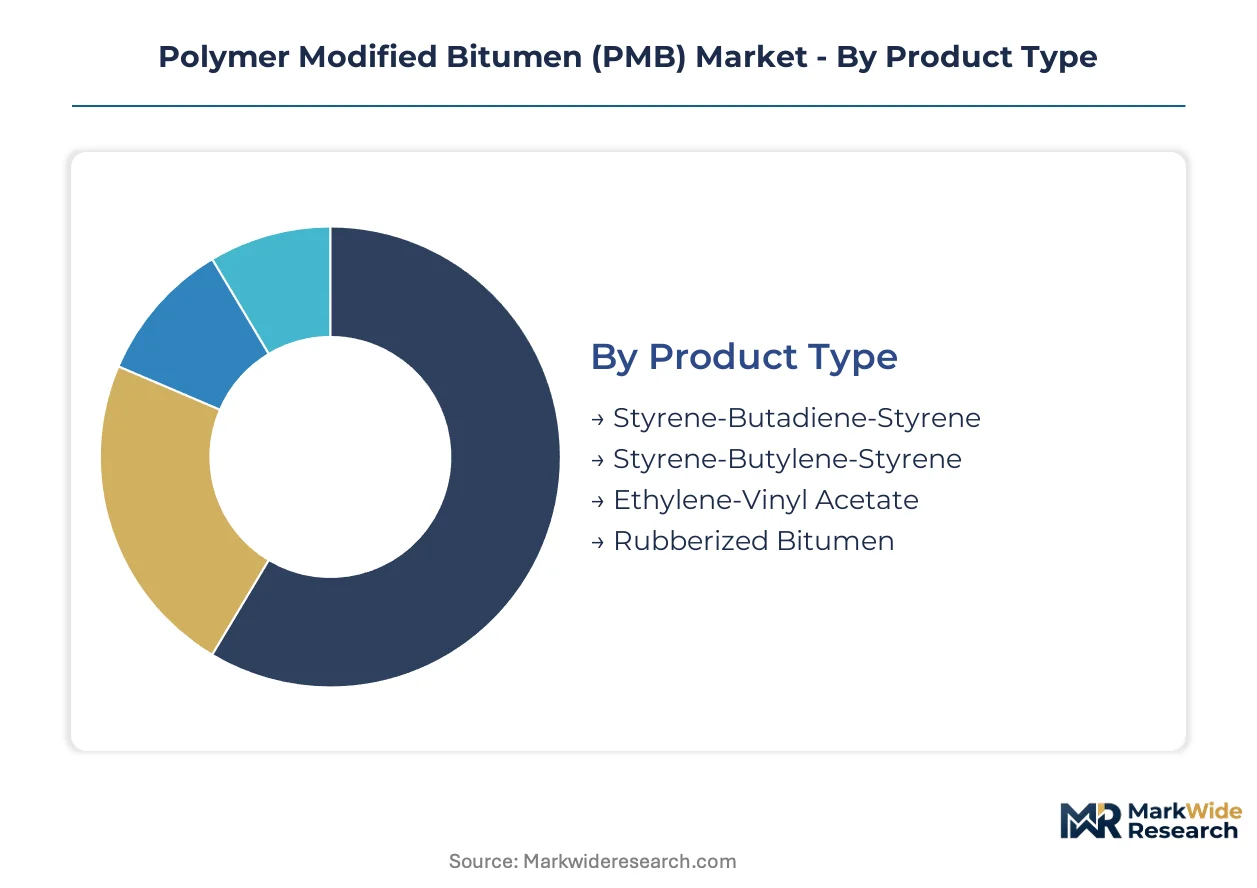
Product Type:
Use-case spectrum spans heavy-traffic highways requiring elastic recovery through specialized roofing membranes demanding adhesion flexibility.
- Styrene-Butadiene-Styrene:Linear block copolymer at 3-7% weight loading delivers rutting resistance above 60°C and thermal crack prevention below -30°C. Maharashtra and Gujarat state highway departments specify SBS for national corridor resurfacing where axle loads exceed 10 tons per axle. BIS polymer content mandates are compressing formulation tolerances toward certified 5% minimum loadings.
- Styrene-Butylene-Styrene:Hydrogenated midblock variant offers enhanced oxidation stability for tropical ultraviolet exposure. SBS dominates volume, but SBS adoption is climbing fastest in southern Indian states with intense monsoon-heat cycling.
- Ethylene-Vinyl Acetate:Copolymer binder with 12-18% vinyl acetate content improves low-temperature flexibility for waterproofing membranes. EVA formulations command premium positioning in coastal flood-zone building codes.
- Rubberized Bitumen:Crumb rubber from end-of-life tires dispersed at 15-20% weight fraction creates porous friction course binders. Kerala and Karnataka pilot projects specify rubberized PMB for noise-reduction pavement layers.
The dominant share belongs to Styrene-Butadiene-Styrene, while Styrene-Butylene-Styrene is closing the gap fastest.
Application:
Volume concentration tracks public infrastructure procurement cycles, with private construction creating secondary demand pools.
- Road Construction:Binder applications for asphalt wearing courses, binder courses, and base layers constitute the primary revenue pool. India's Ministry of Road Transport and Highways mandates PMB for all national highway projects above 100 lane-kilometers.
- Waterproofing:Elastomeric membrane systems for basements, tunnels, and bridge decks use SBS-modified sheets with polyester reinforcement. Mumbai and Chennai municipal corporations now require certified membrane systems for underground metro infrastructure.
- Roofing:Torch-applied and self-adhesive membranes for commercial and industrial buildings specify EVA-SBS hybrid formulations. Gujarat industrial corridor warehousing projects are expanding membrane specifications.
- Paving:Specialized applications include airport runways, racetracks, and container terminal surfaces requiring extreme durability. Jawaharlal Nehru Port Trust specifications drive premium PMB adoption for container yard pavements.
Road Construction holds the dominant share, with Waterproofing expanding most quickly behind flood-resilient building mandates.
End User:
Procurement authority determines specification complexity, with public agencies enforcing certified compliance that private developers sometimes bypass.
- Construction Companies:Tier-1 contractors with in-house testing laboratories qualify for national highway tenders requiring BIS-certified PMB supply chains.
- Infrastructure Developers:PPP concession holders specify performance-graded binders with 10-year durability warranties for toll road operations.
- Road Maintenance Agencies:State Public Works Departments in Maharashtra, Gujarat, Karnataka, and Tamil Nadu concentrate PMB demand through centralized procurement cells.
- Manufacturers:Waterproofing membrane producers and preformed roofing system fabricators source bulk PMB for downstream product fabrication.
Road Maintenance Agencies command the dominant share, while Infrastructure Developers are gaining procurement authority fastest through asset monetization frameworks.
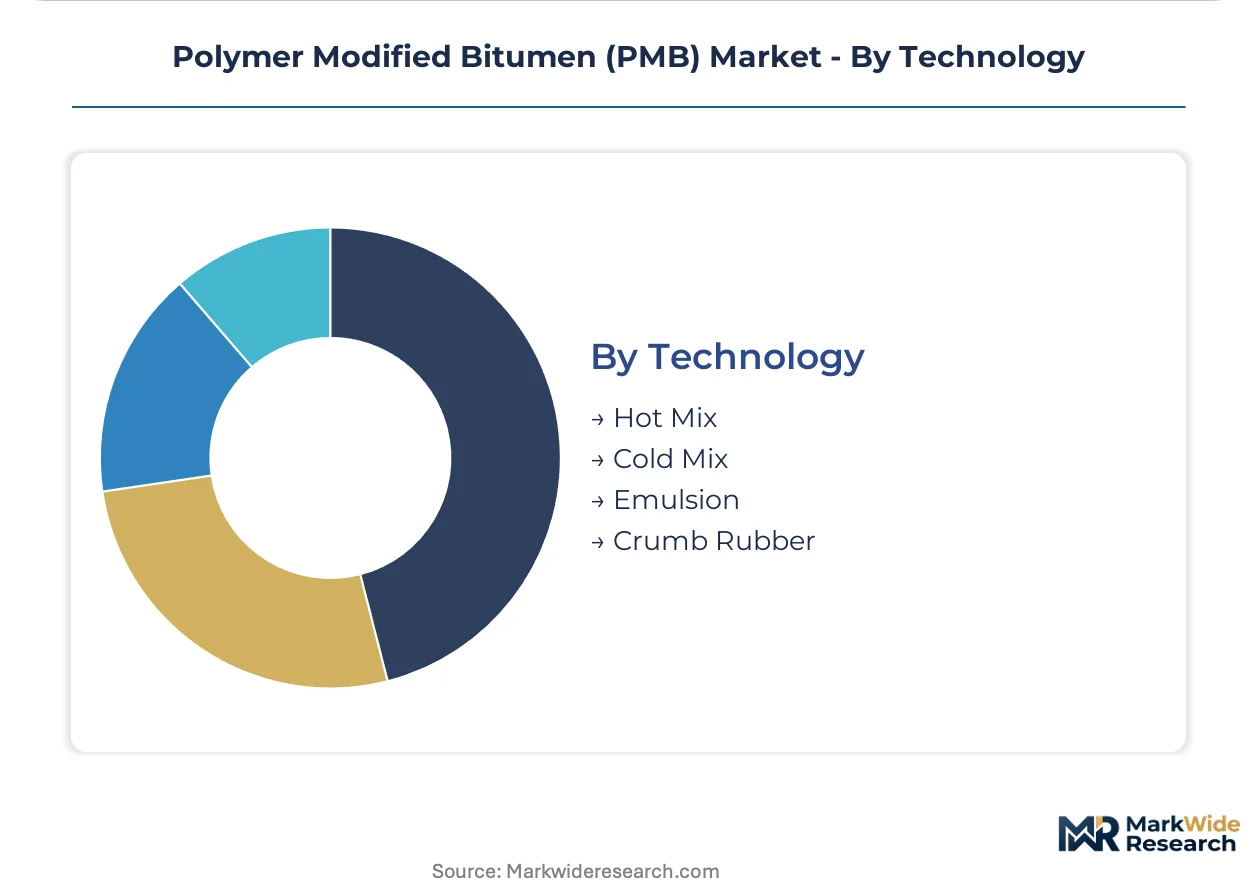
Technology:
Placement temperature and mixing methodology create distinct equipment and logistics requirements that segment supply capabilities.
- Hot Mix:Conventional asphalt plant production at 150-170°C with polymer pre-blending or inline injection dominates high-volume highway construction.
- Cold Mix:Cutback or emulsion-based systems enable pothole repair and low-volume road maintenance without heating infrastructure.
- Emulsion:Water-based PMB dispersions allow spray applications for tack coats, chip seals, and slurry surfacing in environmentally sensitive zones.
- Crumb Rubber:Terminal blend or continuous blend systems integrate ground tire rubber at 10-20% substitution rates for noise and durability benefits.
Hot Mix retains the dominant share, though Emulsion technology is climbing fastest behind cold-weather and emission-constrained project specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. India deploys PMB predominantly for highway resurfacing under federal mandates, while European markets prioritize low-temperature elasticity formulations for alpine infrastructure. The United States enforces performance-graded specifications that effectively require polymer modification for interstate corridors in extreme climate zones.
India
Maharashtra and Gujarat state highway departments drive demand through PMB mandates for high-traffic corridors exceeding 10 tons per axle. India's Bureau of Indian Standards tightened polymer content specifications, forcing manufacturers toward certified SBS formulations. Mumbai, Chennai, and Delhi concentrate BIS-recognized testing infrastructure, excluding regional blenders from national highway qualification.
United States
The Federal Highway Administration enforces Superpave performance-graded binder specifications that mandate polymer modification for interstate highways in extreme climate zones. State DOTs across the Sun Belt and Upper Midwest specify PG 64-22 and PG 76-22 grades for thermal cycling resistance. Texas and California anchor domestic demand through centralized state procurement systems for highway rehabilitation.
Germany
Federal transport infrastructure planning prioritizes durable pavement binders for the autobahn network's heavy freight corridors. ECHA REACH restrictions on aromatic extender oils accelerate base oil substitution toward Group III naphthenic stocks. The Rhine-Ruhr industrial corridor hosts formulation facilities serving alpine export markets requiring low-temperature elasticity.
China
National expressway construction targets sustain bulk PMB consumption for high-grade asphalt wearing courses across subtropical and temperate zones. GB standards for polymer-modified asphalt binders align with performance-graded specifications in coastal province tenders. The Yangtze River Delta concentrates blending capacity serving municipal infrastructure projects in Shanghai and Jiangsu.
United Arab Emirates
Federal infrastructure agencies specify premium PMB formulations for airport runways and container terminal pavements exposed to extreme thermal cycling. Dubai's Roads and Transport Authority mandates enhanced binder standards for elevated corridor projects. Jebel Ali Port specifications drive premium adoption for heavy-haul container yard surfaces.
Polymer Modified Bitumen (PMB) Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors possessing proprietary SBS blending technology; scale advantage sits with national oil companies commanding captive bitumen supply. The market structures around three tiers: global majors with full value-chain control, regional compounders with BIS or FHWA certification infrastructure, and specialty blenders serving waterproofing membrane fabricators. Dominant competitive moves include backward integration into polymer feedstock production and strategic partnerships with state highway departments for long-term tender positioning.
Within the integrated majors tier, Shell plc and TotalEnergies exemplify archetypes combining bitumen refining with polymer modification expertise. NYNAS AB occupies a specialist position anchored in naphthenic base oil formulation for low-temperature applications. Among Asia-Pacific compounders, Oil India Limited represents the national oil company archetype with captive bitumen supply advantages.
| Leading Market Players |
|---|
| Oil India Limited |
| Gazprom |
| Shell plc |
| Lagan Asphalt Group |
| NYNAS AB |
| Exxon Mobil Corporation |
| Sika AG |
| Benzene International Pte Ltd |
| TotalEnergies |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European aromatic extender oil refining is compressing formulation margins for PMB compounders serving REACH-regulated markets, forcing suppliers toward naphthenic base oil substitution while reshaping procurement negotiations with state highway departments.
Pricing Analysis
Long-term offtake contracts dominate pricing structures for national highway tenders in India and the United States, insulating certified compounders from SBS feedstock volatility while locking in volume commitments. Price differentiation rests on BIS certification tier and performance-grade specification complexity, with PG 76-22 binders commanding substantial premia over penetration-grade alternatives. Cost compression in standard-grade SBS formulations is intensifying as warm-mix asphalt with high RAP content displaces virgin PMB in maintenance contracts. Road maintenance agencies exhibit highest price sensitivity due to fixed budget allocations, while infrastructure developers under performance-based procurement show lowest sensitivity given durability warranty requirements.
Supply Chain Analysis
Tariff exposure between Middle Eastern bitumen exporters and Indian compounders dominates supply chain risk calculations for Asia-Pacific formulation facilities. Manufacturing gravity centers on India, Germany, and the United States, with blending capacity clustering near Mumbai, the Rhine-Ruhr corridor, and Texas Gulf Coast refining complexes. Raw material dependencies draw from South Korean and Chinese SBS polymer production, Russian vacuum residue feedstock, and Group III naphthenic base oils from European refiners. Distribution runs through state highway department tender systems with mandatory BIS or FHWA certification gates, creating qualification bottlenecks that exclude uncertified regional blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by India's national infrastructure buildout, where federal highway resurfacing mandates are compressing tender cycles and rebuilding order backlogs for certified compounders.
For Market Incumbents: Harden tender positioning through captive SBS polymer supply arrangements that neutralize butadiene monomer price spikes threatening fixed-price contract profitability. Expand BIS-recognized laboratory capacity into secondary cities beyond Mumbai, Chennai, and Delhi to capture state highway department procurement cells migrating toward decentralized qualification. Deepen backward integration into naphthenic base oil sourcing as REACH aromatic restrictions accelerate formulation chemistry shifts. For New Entrants and Emerging Players: Pursue waterproofing membrane fabrication partnerships in Maharashtra and Gujarat coastal districts where flood-resilient building codes are mandating SBS-EVA hybrid specifications with limited certified supply. Target cold-mix emulsion technology gaps in northern Indian states with seasonal construction constraints, leveraging lower capital intensity versus hot-mix infrastructure requirements. Anchor go-to-market strategy through municipal corporation relationships for underground metro infrastructure membrane contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with decade-long state highway department performance-based procurement contracts tied to rutting index warranties. Long-term viability favors acquisition targets possessing simultaneous BIS certification infrastructure and Superpave testing capability for cross-regional qualification. Monitor tender participation rates from national oil company affiliates as the inflection signal for competitive intensity shifts in federal highway segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SBS Polymer Production | Shell plc and TotalEnergies neutralize butadiene feedstock volatility through captive styrene-butadiene-styrene manufacturing. |
| BIS Certification Laboratory Expansion | Regional compounders in Chennai and Delhi extend qualification access to state Public Works Departments decentralizing procurement. |
| Naphthenic Base Oil Formulation Pivot | NYNAS AB and European compounders preempt REACH aromatic oil restrictions through Group III stock substitution. |
| Performance-Based Contractor Partnerships | Infrastructure developers lock in 10-year durability warranties with compounders supplying tropical climate-certified binders. |
| Waterproofing Membrane Code Alignment | Sika AG and specialty blenders capture coastal district mandates through SBS-EVA hybrid certification. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of BIS certification registries, FHWA binder specification databases, and ECHA REACH substance restriction filings to validate market sizing and competitive positioning claims. Primary interviews engaged technical directors at PMB formulation facilities, procurement leads at Maharashtra and Gujarat state highway departments, polymer supply managers at SBS manufacturers, and waterproofing membrane fabricators in Mumbai and Chennai industrial corridors. Secondary validation drew from Ministry of Road Transport and Highways tender documentation, Bureau of Indian Standards polymer content specifications, and customs data on bitumen and synthetic rubber trade flows. Bottom-up volume estimates from state-level procurement aggregations were triangulated against top-down petrochemical feedstock consumption patterns.
Forecast inputs incorporate polymer modification adoption rates across national highway project pipelines, REACH compliance timeline acceleration for aromatic oil substitution, and Superpave performance-grade specification migration in state tender documents. Segmentation modeling spans product type chemistry, application end-use, technology placement methodology, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections tied to infrastructure budget allocation trajectories and formulation cost curve shifts from base oil substitution. Industry-specific inputs include BIS certification queue lengths and warm-mix asphalt displacement rates in maintenance contract segments.
Sensitivities concentrate around SBS polymer price volatility from butadiene monomer supply disruptions, accelerated REACH aromatic restriction enforcement compressing formulation timelines, and recycled asphalt pavement technology advances displacing virgin PMB volumes. Forecasts reflect assumptions on state highway department procurement centralization trends and federal infrastructure budget continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Global Furan Resins Market