
 Polyethylene Terephthalate (PET) Compounding Market | 2026-2036
Polyethylene Terephthalate (PET) Compounding Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate (PET) Compounding Market Analytics
Subscription-based technical support for compounding recipe optimization is consolidating what processors actually purchase, shifting value from resin volume to formulation-as-a-service. BASF SE leverages its global catalyst technology network to anchor premium specialty PET compounds for medical and automotive grades. RTP Company specializes in small-batch engineered formulations, competing through rapid custom color and additive matching for niche industrial applications.
Polyethylene Terephthalate compounding denotes the melt-blending of virgin or recycled PET resin with additives, nucleating agents, impact modifiers, and reinforcing fillers to achieve specified intrinsic viscosity, crystallization rates, and mechanical performance profiles for targeted fabrication processes. The resulting compounds serve primarily as feedstock for injection-molded automotive components, blow-molded beverage containers, and thermoformed food trays requiring controlled clarity and barrier properties. Recycled PET compounds command expanding formulation attention as brand owners mandate post-consumer content thresholds, though bottle-grade PET retains the dominant volume position due to entrenched beverage industry specifications. Fiber-grade PET occupies a mature trajectory with slower innovation cycles, while sheet-grade compounds targeted at thermoforming applications capture widening margin pools from ready-meal packaging proliferation.
The European Chemicals Agency enforces REACH compliance for additive substances in PET compounds destined for food-contact applications, directly shaping permissible nucleating and clarifying chemistries. The FDA maintains rigorous extraction and migration testing protocols for PET compounds entering US food packaging channels, creating dual-track certification burdens for multinational compounders. China's Ministry of Ecology and Environment implements escalating waste-plastic import restrictions that redirect recycled PET feedstock flows toward domestic Southeast Asian reprocessing hubs. Stakeholders must monitor evolving extended-producer-responsibility frameworks and recycled-content verification standards to secure compound offtake agreements with sustainability-committed brand owners.
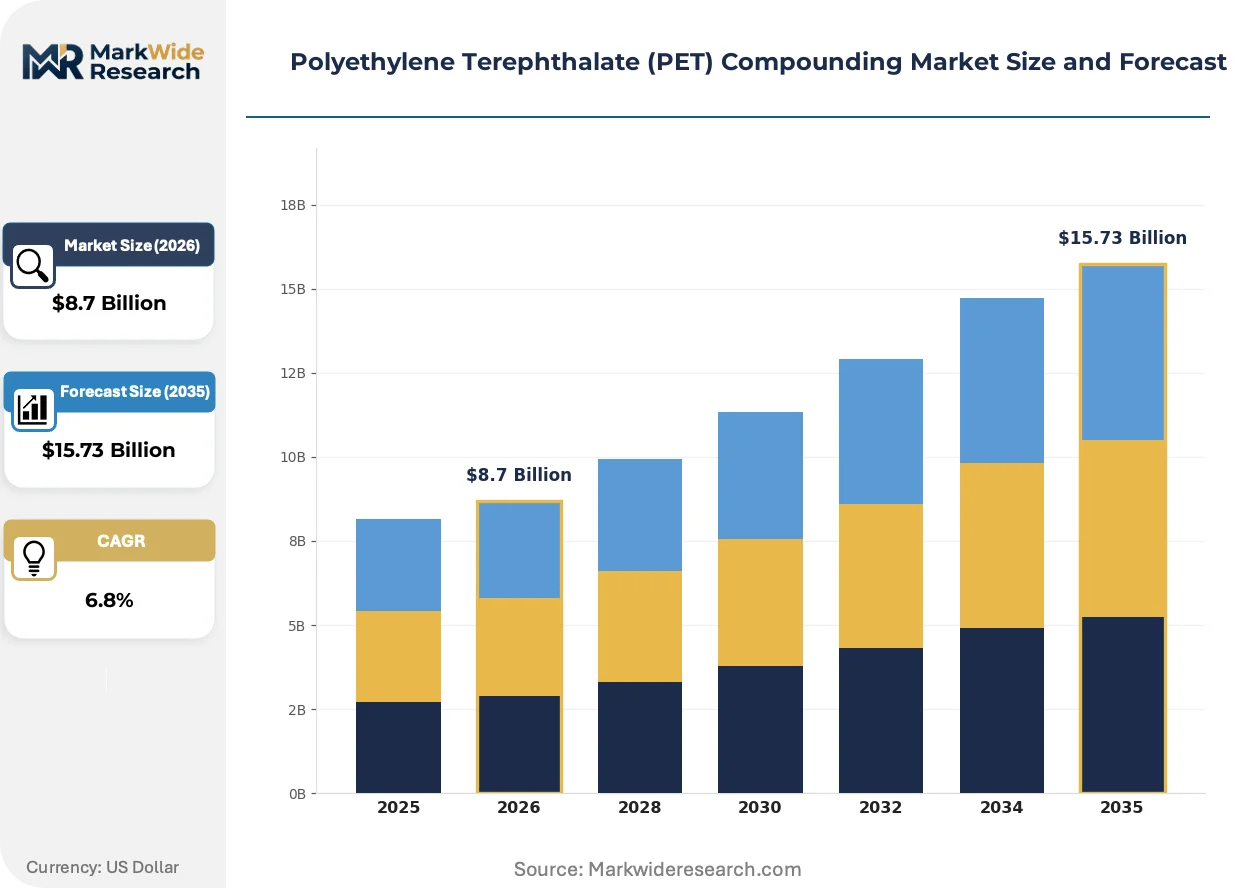
Market Dynamics
The EU Single-Use Plastics Directive mandates minimum recycled content thresholds, forcing compounders to reconfigure formulation architectures around certified post-consumer feedstock streams rather than virgin resin optimization alone.
Growth Catalysts
- REACH-compliant additive innovation:ECHA's evolving substance restrictions compel reformulation of nucleating agents, creating competitive advantage for compounders with in-house regulatory chemistry capabilities.
- Lightweighting in automotive:OEMs specify glass-reinforced PET compounds for under-hood components, displacing metal and denser engineering thermoplastics in thermal management modules.
- Rhine corridor concentration:Germany's dense clustering of packaging converters and automotive Tier-1s enables just-in-time compound delivery with reduced working capital requirements.
Market Restraints
- rPET feedstock volatility:China's MEE waste-plastic import bans have redirected bale flows to Vietnam and Thailand, fragmenting supply security for European compounders.
- Intrinsic viscosity degradation:Mechanical recycling of post-consumer bottles produces chain-shortened PET requiring costly solid-state repolymerization to meet bottle-grade specifications.
- Polypropylene substitution:Clarified random copolymer PP captures share in hot-fill beverage closures where PET crystallization rates prove incompatible with cycle time requirements.
Strategic Opportunities
- Medical-grade barrier compounds:FDA's tightened extraction protocols for pharmaceutical packaging create premium formulation segments requiring dedicated clean-room compounding infrastructure.
- Digital recipe platforms:Cloud-based viscosity modeling enables remote formulation tuning, opening technical service revenue streams independent of physical resin shipments.
- Poland packaging corridor:Relocated beverage bottling capacity from Western Europe creates demand for localized compounding capacity with reduced logistics exposure.
Industry Challenges
- Color-matching complexity:rPET feedstock inconsistency demands spectroscopic batch analysis and automated pigment dosing systems that strain mid-scale compounder capex budgets.
- Dual-track certification:Simultaneous EFSA and FDA compliance for global food-contact compounds extends qualification timelines and freezes formulation iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate (PET) Compounding Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled PET, Bottle Grade PET, Sheet Grade PET, Fiber Grade PET End Use Industry: Food & Beverage, Textile, Automotive, Consumer Goods Form: Granules, Pellets, Sheets, Films Technology: Extrusion, Injection Molding, Blow Molding, Thermoforming |
| Companies Covered | BASF SE, DuPont, SABIC, Indorama Ventures Public Company Limited, Alpek S.A.B. de C.V., RTP Company, Dow Chemical Company, Sinopec, LOTTE Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate (PET) Compounding Market Evolving Landscape
Digital formulation platforms and closed-loop recycling infrastructure are compressing the traditional separation between resin production, compounding, and converter processing into integrated supply nodes.
Reactive extrusion with in-situ chain extenders is overtaking conventional solid-state polymerization for restoring intrinsic viscosity in recycled PET streams. Automotive under-hood component suppliers adopt these compounds for charge-air ducts and coolant reservoirs. The technology is overtaking batch repolymerization by eliminating energy-intensive crystallization and nitrogen-purging steps, collapsing processing economics for medium-viscosity grades.
REACH authorization requirements for phthalate-based plasticizers are tightening migration limits in food-contact PET compounds. Compounders reformulate with bio-based adipate esters and citrate alternatives to maintain clarity and flexibility. Blow-molded beverage containers face the steepest compliance burden, with German converters accelerating third-party migration testing to secure EFSA favorable opinions ahead of sunset dates.
Brand-owners now specify mass-balance-certified recycled content rather than mechanically recycled compounds alone. Beverage multinationals audit polymerization and compounding facilities for ISCC PLUS chain-of-custody documentation. This procurement compression is most visible in Nordic markets, where deposit-return systems generate high-purity bale streams that justify premium pricing for verified circularity claims.
Polyethylene Terephthalate (PET) Compounding Market Segmentation
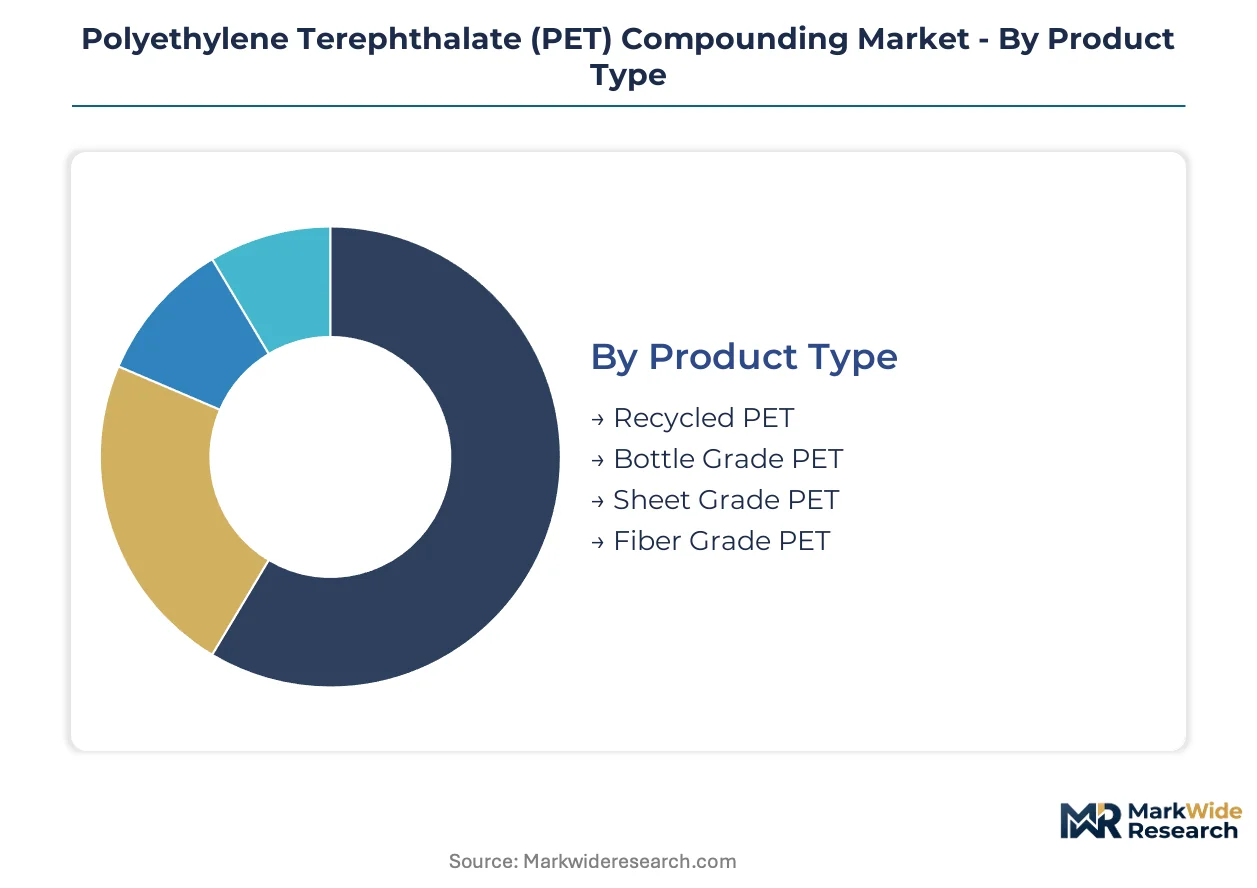
PET compounding formulations diverge sharply across product grades, with intrinsic viscosity and crystallization kinetics determining suitability for specific fabrication processes. End-use specifications from beverage bottlers and automotive Tier-1s cascade backward through the value chain, forcing compounders to maintain parallel production lines with distinct additive packages.
Product Type:
Intrinsic viscosity and post-consumer content thresholds differentiate commercial positioning across the four product grades.
- Bottle Grade PET:High intrinsic viscosity resin compounded with acetaldehyde scavengers and UV stabilizers maintains carbonation retention and clarity for carbonated soft drink containers. Demand concentrates with multinational beverage bottlers in Germany and Poland where deposit-return systems secure high-purity rPET feedstock streams. REACH-compliant additive packages face ECHA scrutiny for migration limits.
- Recycled PET:Post-consumer flake undergoes solid-state repolymerization or reactive extrusion with chain extenders to restore molecular weight for bottle-to-bottle applications. Automotive under-hood component suppliers in the Rhine corridor specify these compounds for coolant reservoirs and charge-air ducts to meet corporate sustainability targets.
- Sheet Grade PET:Nucleated formulations with controlled crystallization rates serve thermoformed ready-meal trays and blister packaging. EFSA compliance for food-contact applications dominates formulation priorities.
- Fiber Grade PET:Lower intrinsic viscosity compounds with titanium dioxide delustering for textile staple and filament applications. Mature demand trajectory with slower innovation cycles compared to packaging grades.
Bottle Grade PET leads on scale; Recycled PET leads on momentum.
End Use Industry:
Application-specific performance requirements dictate additive selection and certification burdens across downstream sectors.
- Food & Beverage:Barrier-enhanced compounds with oxygen scavengers and active packaging additives extend shelf life for sensitive products. FDA extraction protocols and EFSA favorable opinion requirements create dual-track qualification timelines for global suppliers.
- Automotive:Glass-reinforced and mineral-filled compounds displace metal in thermal management modules and electrical housings. OEM lightweighting mandates in Germany accelerate specification of PET over denser engineering thermoplastics.
- Textile:Fiber-grade compounds with controlled intrinsic viscosity for melt-spinning operations. Relatively stable demand with limited compounding value-add beyond standard delustering and dye receptivity modifiers.
- Consumer Goods:Cosmetic packaging and household articles requiring clarity and dimensional stability. Smaller batch sizes favor compounders with rapid color-matching capabilities.
Food & Beverage commands volume concentration; Automotive shows steepest specification upgrading.
Form:
Physical presentation determines handling economics and converter equipment compatibility.
- Pellets:Standard cylindrical extrudate for bulk injection molding and blow molding operations. Rhine corridor compounders optimize pellet geometry for pneumatic conveying efficiency to just-in-time packaging converters.
- Granules:Irregular regrind form primarily for recycled PET streams requiring downstream densification. Lower bulk density increases logistics costs but suits compounders without strand pelletizing capacity.
- Sheets:Pre-extruded flat stock for direct thermoforming, bypassing converter extrusion steps. Ready-meal packaging proliferation drives demand for coextruded barrier sheet structures.
- Films:Thin-gauge cast or oriented products for flexible packaging laminations. Specialized slit-die extrusion requirements limit compounding participation.
Pellets dominate shipment volumes; Sheets capture widening margin pools from thermoforming integration.
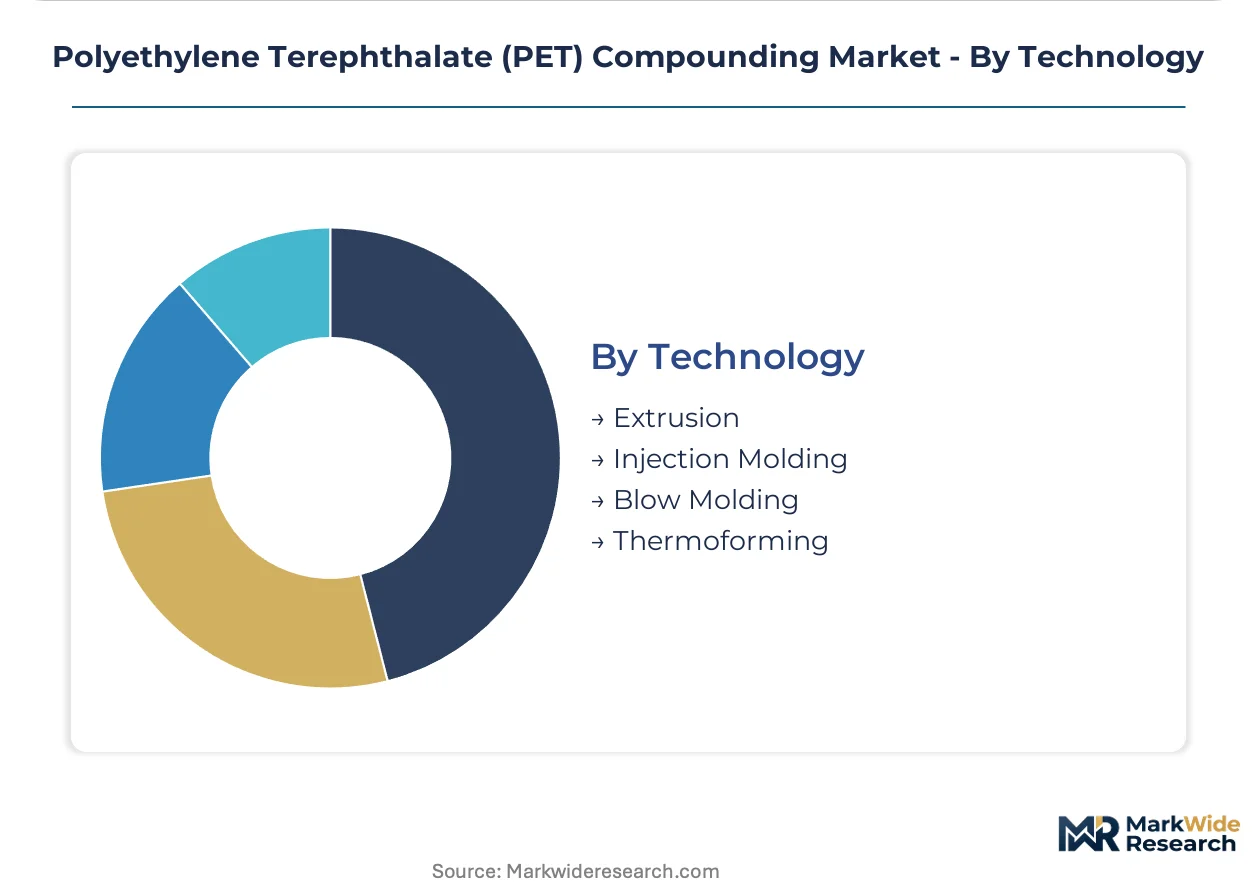
Technology:
Fabrication method compatibility shapes crystallization rate specifications and nucleating agent selection.
- Extrusion:Continuous melt processing for sheet, film, and profile applications requiring controlled shear history. ECHA REACH restrictions on certain nucleating chemistries directly impact formulation options.
- Injection Molding:High-pressure cavity filling for automotive components and preforms demands rapid crystallization kinetics and precise viscosity control.
- Blow Molding:Stretch-blow processes for beverage containers require strain-hardening behavior and acetaldehyde generation suppression during melt processing.
- Thermoforming:Solid-phase forming of pre-extruded sheet into trays and clamshells favors nucleated compounds with broad processing windows.
Extrusion anchors installed capacity; Blow Molding faces steepest recycled-content integration pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting compounding capacity toward jurisdictions with streamlined REACH-equivalent compliance pathways, as ECHA substance restrictions inflate European formulation costs relative to Asian manufacturing bases.
Germany
Automotive OEM lightweighting mandates and deposit-return packaging systems drive bottle-grade PET demand. ECHA REACH authorization requirements for nucleating agents compel reformulation investments. The Rhine industrial corridor clusters BASF SE and RTP Company facilities serving just-in-time delivery to Tier-1 suppliers.
United States
FDA extraction protocols for food-contact applications create premium qualification barriers for pharmaceutical packaging compounds. The IRA's domestic manufacturing incentives attract recycled PET infrastructure investment. Gulf Coast petrochemical corridors leverage integrated resin-to-compounding economics.
China
MEE waste-plastic import bans redirect domestic reprocessing capacity toward Vietnam and Thailand. Dual carbon goals accelerate chemical recycling pilot projects for bottle-grade rPET restoration. Yangtze River Delta converters source compounds from captive Sinopec compounding lines.
Poland
Relocated beverage bottling capacity from Western Europe generates localized compound demand. EU Single-Use Plastics Directive recycled-content thresholds apply without grandfathering exemptions. The Łódź packaging corridor attracts German compounder satellite facilities.
Thailand
Redirected Chinese bale flows establish Southeast Asian reprocessing hubs for European rPET feedstock. National industrial upgrading programs subsidize reactive extrusion capacity for intrinsic viscosity restoration. Eastern Economic Corridor zones offer tax incentives for clean-room medical-grade compounding.
Polyethylene Terephthalate (PET) Compounding Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation-as-a-service models capturing margin pools that volume-based resin suppliers cannot access. The vendor base organizes around three archetypes: integrated petrochemical majors with captive catalyst technology, mid-scale engineering compounders with rapid color-matching capabilities, and regional processors serving converter clusters with logistics-optimized delivery. Consolidation pressures concentrate among European compounders facing dual EFSA-FDA certification burdens, while Asian players expand through government-subsidized capacity additions.
Within the integrated petrochemical tier, BASF SE and SABIC anchor premium specialty positioning through catalyst-controlled viscosity architectures. RTP Company exemplifies the rapid-formulation archetype, occupying a position between mass-market resin supply and custom-engineered small-batch production. DuPont and Dow Chemical Company sit within the materials science conglomerate segment, representing diversified portfolio approaches that span multiple thermoplastic chemistries beyond PET specialization.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| SABIC |
| Indorama Ventures Public Company Limited |
| Alpek S.A.B. de C.V. |
| RTP Company |
| Dow Chemical Company |
| Sinopec |
| LOTTE Chemical Corporation |
| Others |
Value Network & Pricing Analysis
rPET flake procurement costs cascade through three distinct pricing tiers as post-consumer bale flows fragment across Southeast Asian reprocessing hubs and European compounders absorb logistics premiums for certified circularity claims. The EU Single-Use Plastics Directive's recycled-content mandates force brand-owners to pay formulation premiums that virgin resin suppliers cannot capture, compressing margin pools toward additive innovation and regulatory compliance capabilities.
Pricing Analysis
Distributor margins for specialty PET compounds compress as direct-to-OEM contracts expand in Germany's Rhine corridor, where BASF SE and RTP Company negotiate long-term offtake agreements with automotive Tier-1s. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified medical grades from EFSA-compliant food-contact formulations and uncertified industrial compounds. Cost compression in recycled PET streams intensifies because intrinsic viscosity restoration demands reactive extrusion infrastructure that mid-scale compounders cannot finance. Multinational beverage bottlers exhibit lowest price sensitivity due to sustainability-linked procurement mandates, while regional packaging converters face acute margin pressure from rPET feedstock volatility.
Supply Chain Analysis
Skilled polymer chemist availability constrains expansion in Germany's Rhine corridor and Poland's Łódź packaging corridor, where ECHA REACH compliance expertise commands wage premiums that Asian competitors avoid. Manufacturing gravity centers on Germany, Thailand, and Vietnam, with reprocessing capacity migrating toward Eastern Economic Corridor zones following China's MEE waste-plastic import bans. Virgin PET resin draws from Sinopec's Yangtze River Delta polymerization lines, while recycled feedstock sources from Vietnam and Thailand reprocessing hubs. Single-source vulnerability concentrates in chain-extender additive supply, where REACH authorization restrictions have eliminated qualified European suppliers. Distribution runs through just-in-time pneumatic conveying networks to converter clusters, with satellite compounding facilities co-located at major beverage bottling sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET compounding market functions as a regulatory compounder, with the EU Single-Use Plastics Directive's minimum recycled-content thresholds forcing formulation architecture redesigns that favor compounders with in-house regulatory chemistry capabilities.
For Market Incumbents: Lock in rPET feedstock security through backward integration into Southeast Asian bale-sorting infrastructure or long-term supply agreements with Vietnam and Thailand reprocessors, as China's MEE restrictions have permanently fragmented post-consumer supply. Prioritize clean-room compounding capacity for FDA-certified medical-grade barrier compounds, where tightened extraction protocols create premium formulation segments with qualification barriers that commodity resin suppliers cannot breach. Defend margin position by accelerating ISCC PLUS mass-balance certification to capture brand-owner audits for verified circularity claims. For New Entrants and Emerging Players: Enter via Poland's Łódź packaging corridor, where relocated beverage bottling capacity from Western Europe generates localized compound demand without incumbent saturation. Target sheet-grade nucleated formulations for thermoformed ready-meal trays, a segment capturing widening margin pools from packaging proliferation with lower certification burdens than bottle-grade PET. Pursue rapid color-matching capabilities and spectroscopic batch analysis systems to serve mid-scale consumer goods converters that multinational compounders ignore. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-track EFSA-FDA certification burdens strain mid-scale European compounder capex budgets and freeze formulation iterations. Over the projection horizon, acquisition value concentrates in regional processors with captive rPET feedstock streams and established brand-owner offtake relationships, rather than virgin-resin-dependent commodity suppliers. The signal to watch is accelerated ISCC PLUS audit activity among beverage multinationals, indicating procurement compression toward verified circularity claims that justify premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Extrusion Capacity Expansion | Reactive extrusion with in-situ chain extenders collapses processing economics for medium-viscosity recycled PET grades. |
| Backward Integration into rPET Feedstock | Captive bale-sorting infrastructure in Vietnam and Thailand secures supply security fragmented by China's MEE import bans. |
| Clean-Room Medical-Grade Compounding | FDA extraction protocols create premium formulation segments requiring dedicated infrastructure that commodity suppliers cannot replicate. |
| ISCC PLUS Mass-Balance Certification | Beverage multinationals audit polymerization facilities for chain-of-custody documentation that justifies premium circularity claims. |
| Digital Recipe Platform Development | Cloud-based viscosity modeling opens technical service revenue streams independent of physical resin shipments. |
Research Methodology
Direct dialogue with PET compounding plant managers, procurement leads at automotive Tier-1 suppliers, distribution channel partners, and technical R&D directors anchored qualitative insights across formulation optimization and regulatory compliance workflows. Secondary validation drew from ECHA REACH substance restriction databases, FDA extraction protocol filings, customs and trade flow data, and SEC 10-K disclosures from integrated petrochemical majors. Bottom-up and top-down triangulation cross-checked capacity utilization rates against end-use demand projections from beverage bottling and automotive OEM sourcing data.
Top-down macroeconomic drivers framed the analytical lens, while bottom-up segmentation by product grade, end-use industry, physical form, and fabrication technology anchored volume and value outputs across the analysis window. CAGRs derived from regression analysis of historical resin pricing, additive cost trajectories, and converter procurement patterns. Industry-specific forecast inputs included ECHA authorization timelines for phthalate-based plasticizers and deposit-return system bale purity metrics from Nordic markets.
The model holds under stable regulatory enforcement of EU Single-Use Plastics Directive thresholds and continued MEE waste-plastic import restrictions; deviation in REACH authorization sunset dates or sudden rPET feedstock flow redirection would shift compounder formulation investments and margin pool distribution. Forecasts reflect assumptions about certification timeline durations and brand-owner procurement compression rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Epoxy Casting Potting Resin Market