
 Polyether Polyols Market | 2026-2036
Polyether Polyols Market Size, Share, and Industry Trends Forecast 2026-2036
Polyether Polyols Market Analysis
Modular polyether polyol blends bundled with isocyanate co-feeds and surfactant packages is expanding buyer choice in polyurethane systems. Covestro AG leverages its backward integration into propylene oxide feedstock to sustain margin control across flexible foam grades. BASF SE anchors European supply through its Ludwigshafen hub, while Wanhua Chemical Group dominates Asian volume with manufacturing scale in Ningbo and Yantai.
Polyether polyols are hydroxyl-terminated polymers synthesized via anionic ring-opening polymerization of alkylene oxides, typically propylene oxide or ethylene oxide, with molecular weights ranging from hundreds to over ten thousand grams per mole; they function as the primary soft-segment building blocks in polyurethane synthesis. Flexible foam applications lead consumption due to entrenched bedding and automotive seating demand, while rigid foam segments capture higher margins from construction insulation specifications. Biobased process technology is gaining traction as manufacturers reformulate to meet renewable content targets without sacrificing hydroxyl functionality or reactivity profiles.
EPA regulations under the Toxic Substances Control Act and REACH registration requirements in Europe are restricting certain amine catalysts and phthalate plasticizers, forcing polyol suppliers to certify reformulated systems for compliance. China's GB standards and evolving MEE enforcement on volatile organic compound emissions are tightening plant-level requirements for domestic producers and importers alike. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure market access for next-generation low-emission formulations.
Market Dynamics
Construction sector specifications for rigid foam insulation are compressing reformulation cycles as REACH and EPA volatile organic compound limits force suppliers to validate low-emission catalyst systems within compressed certification windows.
Growth Catalysts
- Construction Insulation Mandates:China's GB standards for building energy efficiency are accelerating rigid foam specification in residential and commercial projects across tier-one cities.
- REACH Registration Requirements:ECHA compliance deadlines are pushing European formulators toward certified low-emission polyol systems that maintain hydroxyl functionality.
- Propylene Oxide Feedstock Expansion:Captive supply of alkylene oxide precursors is enabling margin control for integrated producers serving flexible foam grades.
Market Restraints
- Propylene Oxide Price Volatility:Feedstock cost swings tied to refinery output constrain margin predictability for non-integrated polyol manufacturers.
- Supply Concentration in Ningbo-Yantai Corridor:Domestic Chinese producers anchor regional volume, creating import dependency risks for Southeast Asian formulators.
- Technical Limitation in Bio-Based Functionality:Renewable-content polyols face reactivity profile trade-offs that disqualify them from high-performance automotive seating specifications.
Strategic Opportunities
- Underpenetrated Indian Subcontinent:BIS certification gaps and nascent cold-chain infrastructure create whitespace for rigid foam suppliers targeting pharmaceutical logistics.
- Automotive Lightweighting Convergence:Seat cushion density reduction targets are converging with structural foam applications in electric vehicle battery enclosures.
- EU Green Deal Tailwinds:Renewable content mandates in public procurement are opening specification windows for bio-based polyol blends with verified carbon accounting.
Industry Challenges
- Reformulation Certification Timelines:EPA Toxic Substances Control Act pre-manufacture notice requirements extend new product validation cycles by 12-18 months.
- Specialized Catalysis Talent Scarcity:Formulation chemists with expertise in low-emission amine systems command premium compensation, constraining R&D throughput at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyether Polyols Market |
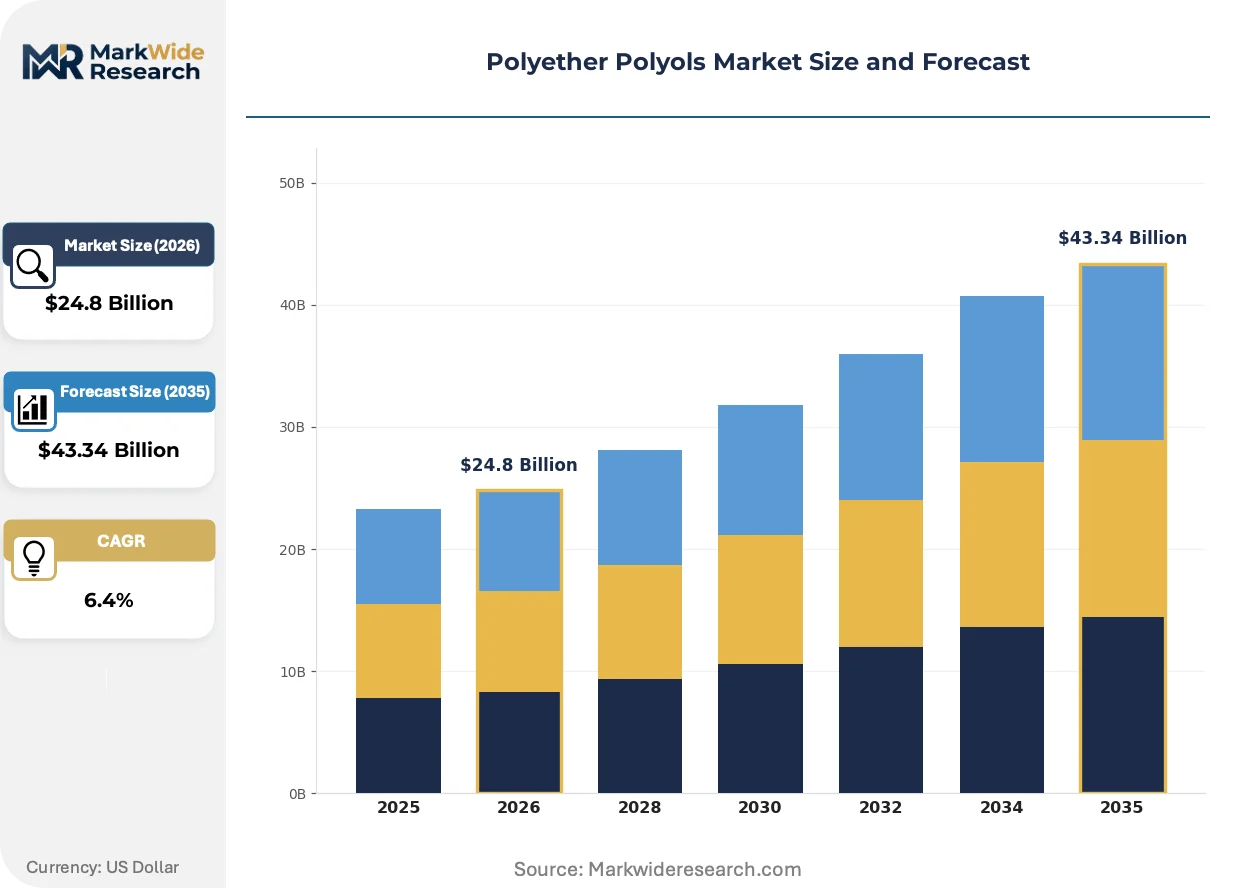
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Diols, Triols, Polyether Polyols, Others Application: Flexible Foam, Rigid Foam, Coatings, Adhesives End User: Automotive, Furniture, Electronics, Construction Technology: Batch Process, Continuous Process, Biobased Process, Others |
| Companies Covered | Covestro AG, BASF SE, Dow Inc., Huntsman Corporation, Shell Chemicals, Wanhua Chemical Group, Mitsui Chemicals, Inc., Stepan Company, Repsol S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyether Polyols Market Emerging Trajectories
Process intensification and regulatory compliance automation are compressing development cycles while molecular architecture advances enable property-specific tuning without sacrificing production economics.
Continuous reactor technology for alkylene oxide polymerization is converging with real-time spectroscopic monitoring to enable tighter molecular weight distribution control. Automotive seating suppliers are adopting these systems to reduce batch-to-batch variation in high-volume flexible foam production. The structural consequence is compression of quality assurance overhead while enabling just-in-time raw material delivery to tier-one seating manufacturers.
REACH authorization requirements for certain phthalate plasticizers are forcing reformulation of legacy flexible foam systems across European bedding and furniture supply chains. The industrial consequence is accelerated validation of alternative chain extenders that maintain compression set performance. Automotive interior segments in Germany and France are most affected, with OEMs now requiring supplier certificates of compliance at the polyol blend level rather than finished foam level.
Specification-driven procurement is consolidating buyer power among large construction chemical distributors who now bundle polyol-isocyanate-surfactant systems under single-source contracts. Regional distributors with technical service capabilities are displacing commodity traders in rigid foam insulation channels across the US Sun Belt. This shift is most visible in Texas and Florida, where spray foam applicators prioritize formulation support over price-point competition.
Polyether Polyols Market Segmentation
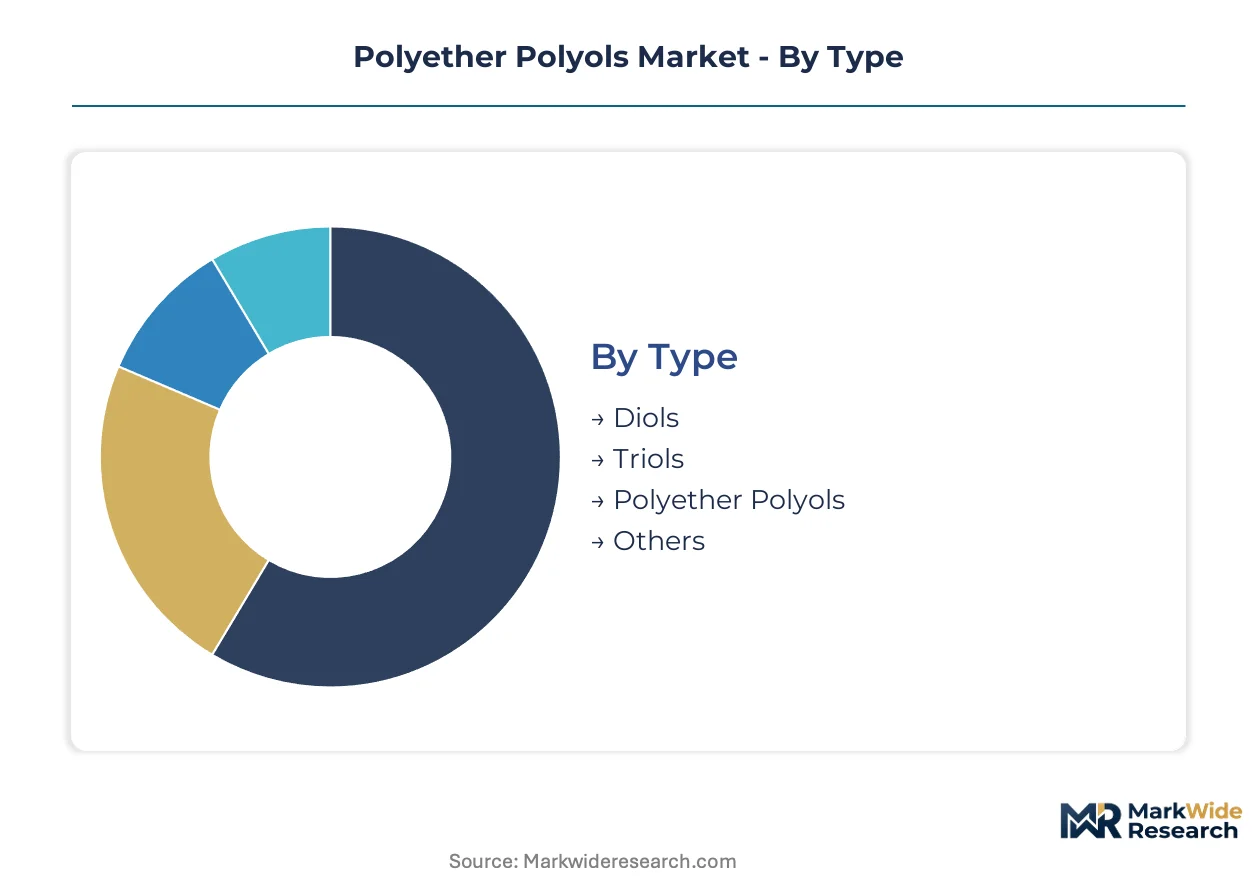
Polyether polyol segmentation determines capital deployment priorities and margin capture potential across polyurethane value chains. Technical specifications in molecular architecture and production technology create divergent investment requirements and customer lock-in dynamics.
Type:
Capital intensity escalates with molecular complexity and functional group density across polyol architectures.
- Diols:Linear hydroxyl-terminated structures with two reactive sites dominate coating and adhesive formulations. Demand concentrates in German automotive OEM clearcoat specifications where low viscosity and precise reactivity control reduce solvent content. REACH authorization pressures on aromatic isocyanates are accelerating aliphatic diol adoption in European transport coatings.
- Triols:Three-arm star architectures deliver crosslink density control essential for high-resilience flexible foams. Chinese bedding manufacturers in Zhejiang and Guangdong provinces anchor volume consumption, though automotive seating suppliers in Stuttgart and Detroit specify premium grades for durability benchmarks. Crosslinked networks from triols outperform diols in compression set resistance.
- Polyether Polyols:Higher-functionality oligomers serve specialized rigid foam insulation with tailored hydroxyl numbers for spray-applied construction systems.
- Others:Tetrols and custom multi-functional architectures address niche composite and elastomer applications with extreme crosslink requirements.
Most installed capacity flows through triol grades serving mass-market flexible foam. Expansion is steepest in diol segments climbing fastest on coating reformulation mandates.
Application:
Volume concentration versus margin capture splits distinctly across polyurethane end-uses, with construction specifications commanding premium positioning.
- Flexible Foam:Open-cell structures from polyether triols dominate mattress, pillow, and automotive seating production. Tier-one suppliers in the US Sun Belt and China's Yangtze River Delta integrate directly with polyurethane machinery lines for just-in-time slabstock delivery. Density reduction targets in electric vehicle seating are compressing specification cycles.
- Rigid Foam:Closed-cell insulation boards and spray foam systems capture construction sector premiums through thermal conductivity performance. China's GB standards for building energy efficiency in Beijing, Shanghai, and Shenzhen are accelerating specification in commercial envelope retrofits. Higher isocyanate index requirements and precise blowing agent compatibility elevate technical barriers.
- Coatings:Polyether diols enable low-VOC polyurethane dispersions for wood furniture and industrial maintenance finishes.
- Adhesives:Reactive hot-melt and two-component systems leverage polyol tunability for packaging and footwear bonding.
Flexible foam absorbs the greatest raw material tonnage. Rigid foam gains share fastest on insulation code enforcement.
End User:
Customer concentration and technical service intensity vary sharply across downstream sectors, reshaping supplier engagement models.
- Automotive:Seating density reduction and structural foam integration for battery enclosures create dual demand streams. German and Japanese OEMs now require polyol blend certificates at the raw material level rather than finished foam testing.
- Furniture:Bedding and upholstery manufacturers in the US Southeast and China's Pearl River Delta drive flexible foam consumption with compressed inventory cycles.
- Electronics:Encapsulation and thermal management applications demand ultra-low moisture content and precise viscosity control.
- Construction:Spray foam applicators and panel producers in Texas, Florida, and Australia's eastern seaboard prioritize distributor technical support over commodity pricing.
Automotive commands the highest technical service investment per ton supplied. Construction delivers the steepest volume expansion trajectory.
Technology:
Process selection determines molecular weight distribution precision, energy intensity, and regulatory compliance automation capabilities.
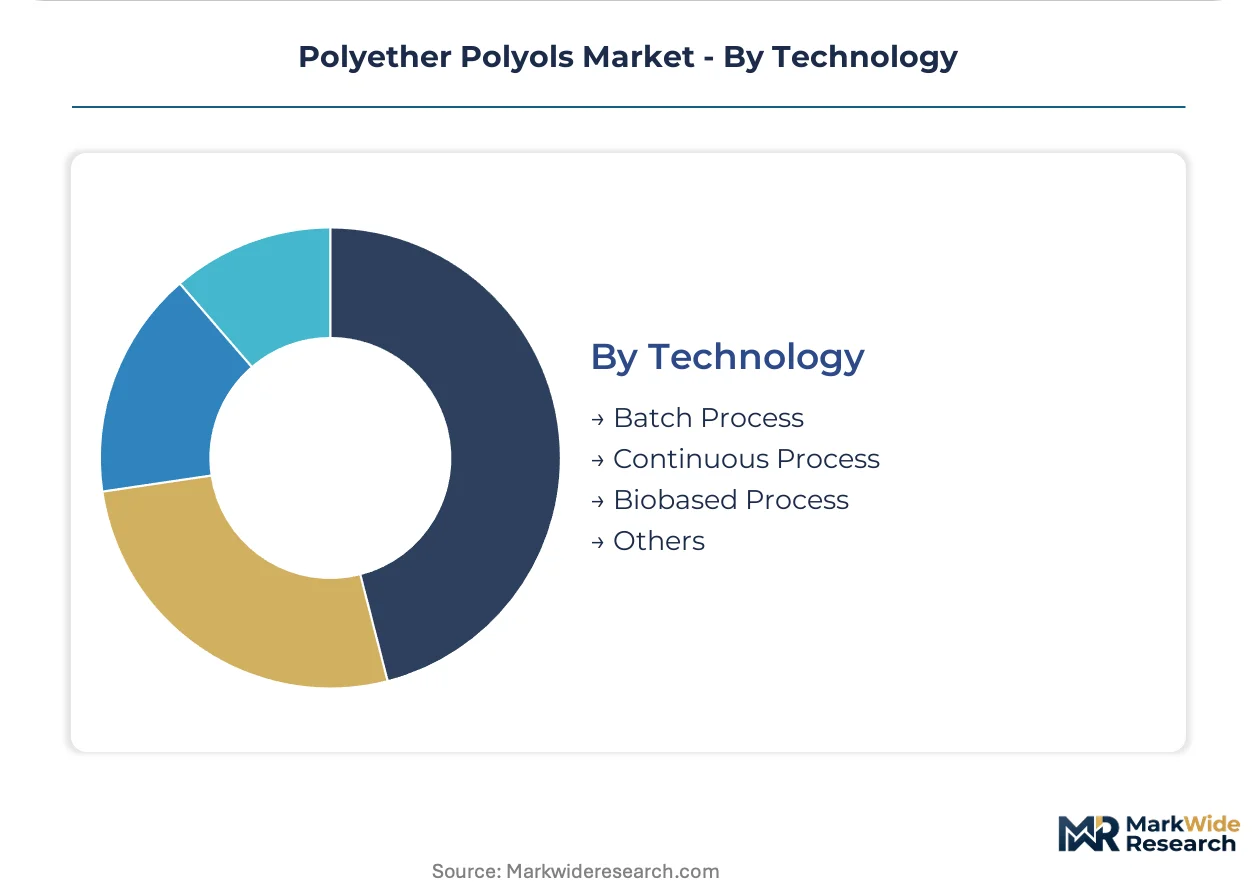
- Batch Process:Conventional stirred-tank polymerization dominates legacy flexible foam grades with broad molecular weight tolerance. Indian and Southeast Asian producers retain batch infrastructure for cost-sensitive mattress markets where specification windows remain wide.
- Continuous Process:Tubular reactor systems with real-time spectroscopic monitoring enable sub-one-percent molecular weight variation for automotive seating consistency. Covestro's European and Chinese assets leverage continuous technology to supply just-in-time tier-one manufacturers with compressed quality assurance overhead.
- Biobased Process:Renewable feedstock incorporation via epoxidized vegetable oils or sugar-derived platform chemicals addresses EU Green Deal procurement mandates. Reactivity profile trade-offs currently exclude bio-based grades from high-performance automotive specifications.
- Others:Hybrid semi-batch systems and catalytic process intensification technologies occupy niche positions between conventional and fully continuous operations.
Continuous process capacity serves the most demanding customer specifications. Biobased technology is climbing fastest on public procurement renewable content thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale polyether polyol production during the post-war polyurethane expansion, establishing the technical foundation that now diffuses across integrated chemical complexes worldwide.
China
Wanhua Chemical Group's manufacturing scale in Ningbo and Yantai anchors regional volume, serving domestic construction activity and Southeast Asian formulators. MEE enforcement on volatile organic compound emissions tightens plant-level requirements for producers and importers. The Yangtze River Delta cluster concentrates flexible foam supply for bedding manufacturers in Zhejiang and Guangdong provinces.
United States
Spray foam applicators in Texas and Florida prioritize distributor technical support over commodity pricing for rigid foam insulation systems. EPA standards under the Toxic Substances Control Act extend new product validation cycles for low-emission catalyst systems. The US Sun Belt corridor concentrates construction chemical distribution networks serving commercial envelope retrofits.
Germany
BASF SE's Ludwigshafen hub anchors European supply for automotive seating specifications requiring premium-grade triols. REACH authorization requirements for phthalate plasticizers force reformulation of legacy flexible foam systems across bedding and furniture supply chains. Stuttgart-based OEMs now require supplier certificates of compliance at the polyol blend level.
India
BIS certification gaps and nascent cold-chain infrastructure create whitespace for rigid foam suppliers targeting pharmaceutical logistics applications. The country's national chemical regulator maintains evolving standards for industrial chemical imports. Maharashtra and Gujarat industrial corridors concentrate batch-process flexible foam production for cost-sensitive mattress markets.
Japan
Automotive seating suppliers adopt continuous reactor technology with real-time spectroscopic monitoring to reduce batch-to-batch variation. METI guidelines on chemical substance management influence formulation disclosure requirements for polyurethane system suppliers. The Kansai region around Osaka maintains specialized catalysis expertise for high-resilience foam grades.
Polyether Polyols Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive alkylene oxide supply. Three to five multinational producers control the majority of installed capacity across flexible and rigid foam grades. Strategic archetypes include backward-integrated petrochemical majors, regional specialists with technical service depth, and emerging Asian scale players. Dominant competitive moves encompass capacity expansion in high-growth corridors and technology licensing partnerships for continuous process systems.
Among German-based chemical conglomerates, BASF SE and Covestro AG exemplify the integrated archetype with upstream control over propylene oxide feedstock. Wanhua Chemical Group occupies a position as the scale-driven Asian producer with manufacturing concentration in China's eastern seaboard. These three anchors represent divergent geographic strategies while converging on technical service intensity for automotive and construction specifications.
| Leading Market Players |
|---|
| Covestro AG |
| BASF SE |
| Dow Inc. |
| Huntsman Corporation |
| Shell Chemicals |
| Wanhua Chemical Group |
| Mitsui Chemicals, Inc. |
| Stepan Company |
| Repsol S.A. |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with expertise in low-emission amine systems cluster in Germany's Kansai region and China's Yangtze River Delta, where labor-cost differentials of 40-60% between these hubs widen pricing-tier spreads for premium versus standard-grade polyol blends.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the polyether polyols market by certification grade and volume scale. Premium tiers command spreads based on REACH-compliant low-emission certificates and automotive OEM qualification, while economy tiers serve cost-sensitive mattress producers in India and Southeast Asia. Pricing pressure stems from propylene oxide feedstock volatility squeezing non-integrated manufacturers. Construction distributors in Texas and Florida show lowest price sensitivity, prioritizing technical service and formulation support over per-kilogram rates.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs in Stuttgart and Detroit mandate multi-supplier qualification for tier-one seating manufacturers, forcing polyol buyers to maintain approved vendor lists across at least two production hubs. Supply concentrates in China, Germany, and the United States, with captive propylene oxide production anchoring margin control for integrated producers. Raw material flows draw from refinery-derived alkylene oxides, specialized amine catalysts, and surfactant packages. Single-source vulnerability runs through the Ningbo-Yantai corridor where Wanhua Chemical Group dominates Asian volume. Distribution runs through construction chemical distributors bundling polyol-isocyanate-surfactant systems under technical service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyether polyols market functions as a stable compounder, with construction insulation mandates across China's tier-one cities and the US Sun Belt delivering steady, regulation-anchored demand growth.
For Market Incumbents: Lock in backward integration into propylene oxide feedstock to defend margins against volatile refinery output swings. Prioritize certification investment for REACH-compliant low-emission systems ahead of ECHA authorization deadlines, as regulatory non-compliance poses stranded inventory risk in European automotive seating channels. Channel control through distributor technical service partnerships secures rigid foam specification in construction markets.
For New Entrants and Emerging Players: Begin with BIS certification gaps in India's pharmaceutical cold-chain infrastructure, where nascent rigid foam demand for vaccine logistics offers whitespace with limited incumbent presence. Target spray foam applicators in Australia's eastern seaboard through formulation support partnerships rather than commodity price competition. Technical service bundling represents the most penetrable go-to-market angle against established distributors.
For Investors and Strategic Acquirers: Chemical conglomerates with captive alkylene oxide supply are the most active acquirer in this space, consolidating regional specialists to secure construction and automotive qualification certificates. The five-to-ten-year viability window favors targets with continuous process technology and established automotive OEM relationships. Acquisition target archetype: mid-scale European or Asian producers with REACH-compliant product portfolios and underutilized technical service capabilities. Watch for inflection where EPA Toxic Substances Control Act pre-manufacture notice timelines extend beyond eighteen months, compressing new entrant product launch windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock supply insulates Covestro and BASF from refinery margin volatility. |
| Continuous Process Technology Licensing | Tubular reactor systems with spectroscopic monitoring reduce batch variation for automotive seating. |
| REACH Compliance Certification Investment | ECHA authorization deadlines force reformulation of legacy flexible foam systems across Europe. |
| Long-term Supply Agreement with Construction Distributors | Bundle polyol-isocyanate-surfactant systems to displace commodity traders in Texas and Florida. |
| Joint Venture for Biobased Process Scale-Up | EU Green Deal procurement mandates open specification windows for renewable-content polyol blends. |
Methodological Framework
Bottom-up polyurethane end-use modeling reconciled against top-down alkylene oxide supply-side tracking forms the analytical core of this study. Primary interviews with plant managers at integrated chemical complexes, procurement leads at automotive seating manufacturers, distribution channel partners in construction chemicals, and technical R&D directors for low-emission catalyst systems generated demand-side intelligence. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and EPA Toxic Substances Control Act pre-manufacture notice databases. Triangulation between these sources anchored volume and value estimates.
Input-output matrices map propylene oxide feedstock availability through polyol production capacities to downstream consumption across flexible foam, rigid foam, coatings, and adhesives segments. The framework models grade tier, end-use industry, and regional production hub dimensions across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating construction code enforcement timelines and automotive lightweighting penetration rates. Forecast inputs include MEE enforcement intensity on volatile organic compound emissions in China and evolving GB standards for building energy efficiency.
Caveats apply where propylene oxide price volatility, regulatory divergence between EPA and REACH jurisdictions, or technical limitations in bio-based reactivity profiles could materially shift the outlook. Forecasts reflect assumptions about certification timeline continuity and construction sector demand elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
PA66 Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market