
 France Automotive Thermoplastic Polymer Composites Market | 2026-2036
France Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Thermoplastic Polymer Composites Market Foresight
CE marking under the EU's End-of-Life Vehicles Directive is collapsing the supplier base to firms with verified recycling pathways. Celanese Corporation leverages its European compounding network to serve French OEMs with localized polyamide supply. Solvay anchors the high-performance segment through its specialty polymer grades for under-the-hood thermal applications. Faurecia competes by integrating composite interior modules directly into vehicle assembly sequences.
Automotive thermoplastic polymer composites combine thermoplastic matrices—polypropylene, polyamide, or polycarbonate—with discontinuous or continuous fiber reinforcement, processed via injection molding or compression molding at cycle times under two minutes. These materials deliver weight reductions of forty to sixty percent versus stamped steel while enabling complex geometries for crash-optimized structures. Long fiber reinforced composites command premium positioning due to superior impact resistance in structural parts, whereas short fiber reinforced grades dominate high-volume interior component production where cost efficiency governs procurement decisions. Polyamide formulations capture concentrated margin pools in thermal management applications requiring continuous service temperatures above 150°C.
France's national implementation of EU REACH restrictions on substance of very high concern classifications directly shapes permissible resin chemistries and reinforcement coatings. The French Environment and Energy Management Agency enforces extended producer responsibility frameworks that penalize non-recyclable automotive materials, redirecting R&D budgets toward closed-loop polypropylene systems. ANSM and CNIL oversight of industrial data governance additionally conditions how connected vehicle component suppliers manage material traceability databases. Stakeholders must monitor the interplay between tightening EU F-Gas Regulation limits on processing emissions and emerging bio-based feedstock certification schemes before committing capital to expanded compounding capacity.
Market Dynamics
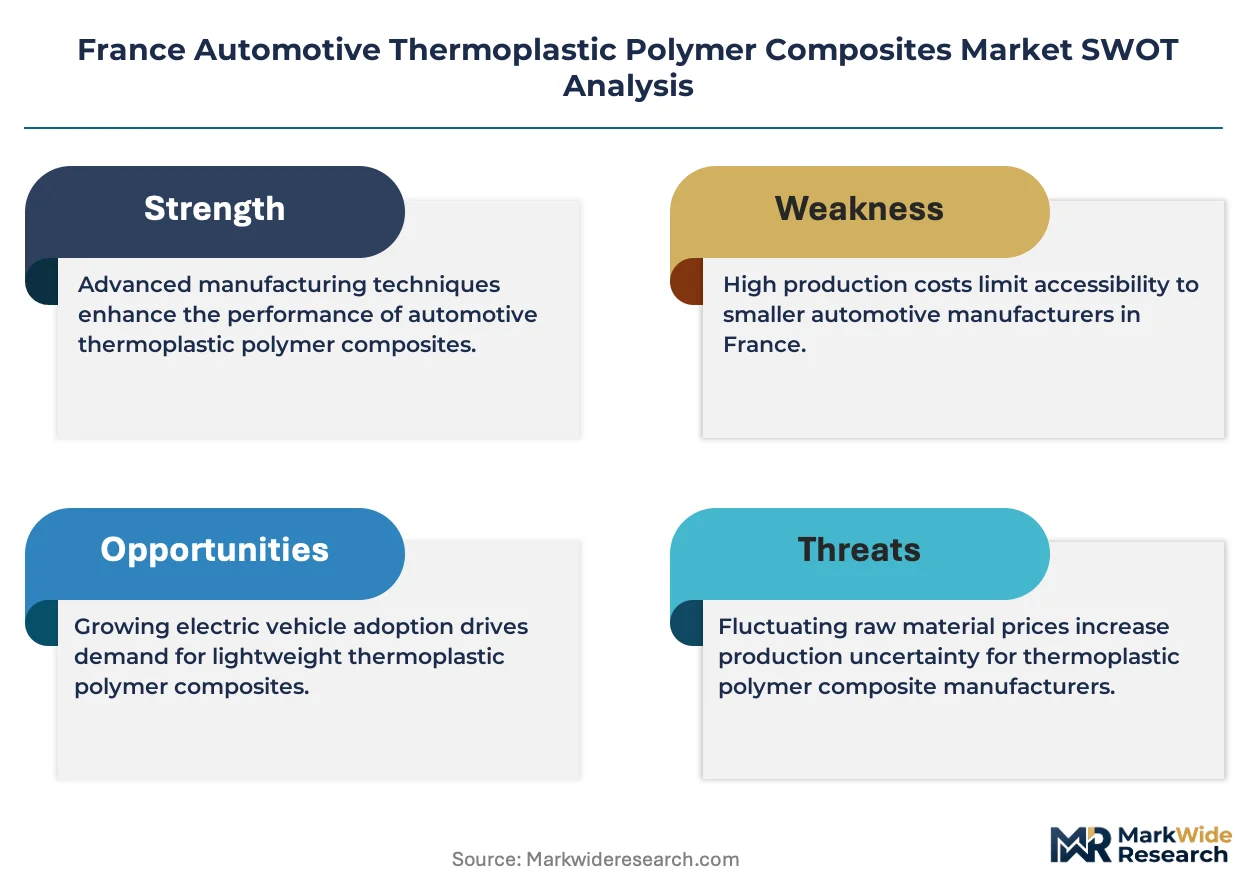
EU Green Deal emissions mandates are collapsing the metal-to-polymer substitution timeline across French OEM platforms, compressing supplier qualification cycles from sixty months to under thirty-six months for structural thermoplastic components.
Growth Catalysts
- EU End-of-Life Vehicles Directive:CE marking requirements under this framework are eliminating suppliers without verified closed-loop recycling pathways, concentrating procurement among certified compounders.
- Electric vehicle structural platforms:Battery enclosure and floor pan applications are pulling long fiber reinforced thermoplastics into load-bearing architectures previously reserved for aluminum.
- Paris-Saclay automotive cluster:Concentrated R&D infrastructure here is accelerating co-development contracts between material suppliers and Tier 1 integrators for crash-optimized geometries.
Market Restraints
- Polyamide feedstock volatility:Caprolactam price swings tied to benzene derivatives are compressing margin predictability for compounders serving thermal management applications.
- High-performance resin supply concentration:Specialty polyamide and PPS grades rely on a narrow European compounding base centered in Germany and Belgium, creating single-source vulnerability.
- REACH substance restrictions:ECHA classifications of certain flame retardants and reinforcement coatings are forcing reformulation cycles that delay platform approvals by twelve to eighteen months.
Strategic Opportunities
- Rhône-Alpes manufacturing corridor:Underpenetrated composite seat structures and interior modules present white space for localized production serving Stellantis and Renault assembly plants.
- Bio-based feedstock certification:Emerging ISCC PLUS and RSB schemes are creating premium positioning for polypropylene compounds with mass-balanced content, commanding procurement preference from sustainability-linked OEM targets.
- Connected vehicle traceability:Integration of material passports with blockchain-verified recycling data is opening new service revenue streams for compounders managing end-of-life liability.
Industry Challenges
- Recycling infrastructure gaps:France lacks sufficient automated sorting and re-compounding capacity for multi-material automotive components, forcing reliance on German and Dutch processors.
- CAF qualification timelines:Crash performance validation for new composite grades requires eighteen to twenty-four months of OEM-specific testing, locking out smaller compounders from platform awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Thermoplastic Polymer Composites Market |
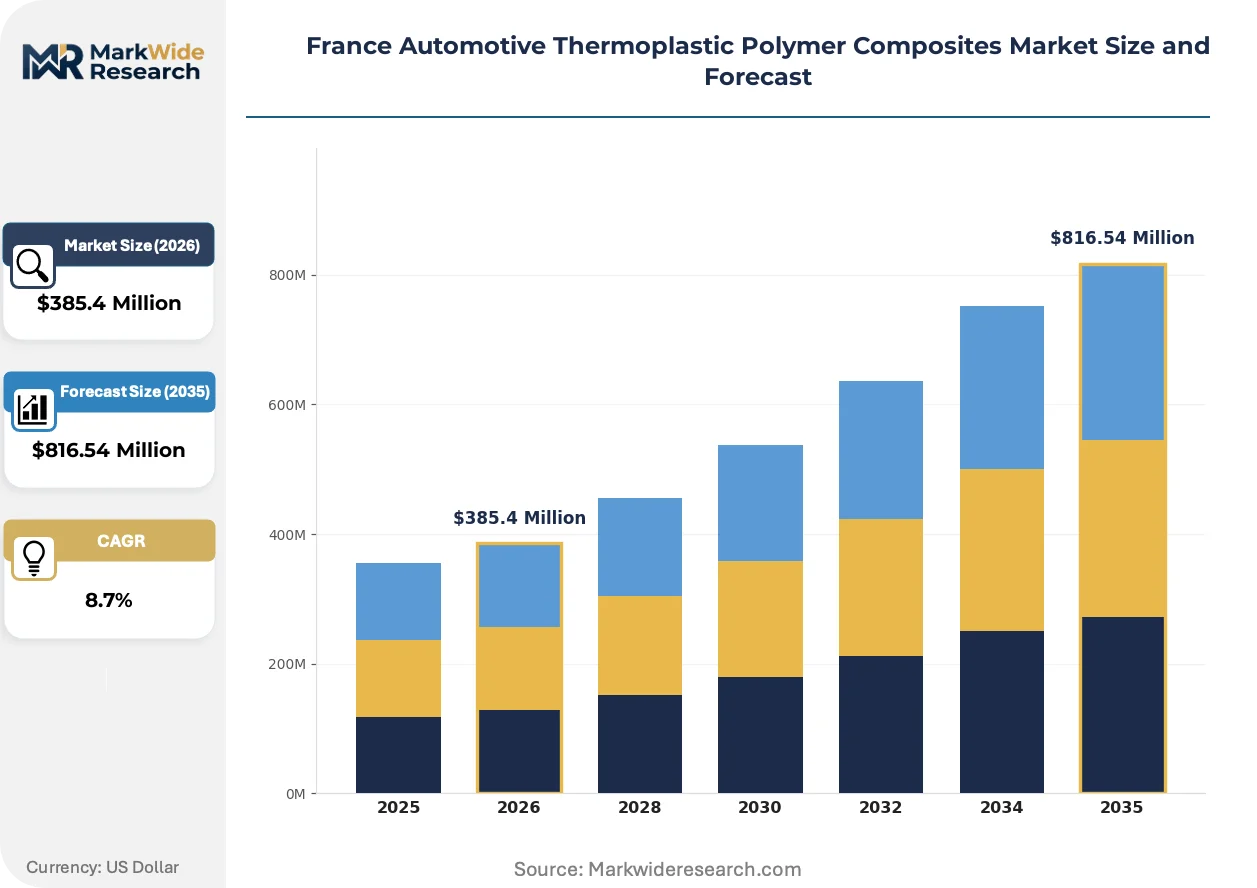
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Polymer Type: Polypropylene, Polyamide, Polycarbonate, Acrylonitrile Butadiene Styrene, Polyethylene Terephthalate, Polyphenylene Sulfide Composite Form: Sheet Molding Compound, Long Fiber Reinforced, Short Fiber Reinforced, Bulk Molding Compound, Spray-up, Film Application: Interior Components, Exterior Panels, Structural Parts, Electrical Housings, Thermal Management, Under-the-Hood Parts End User Type: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assembly Plants, Component Fabricators, Retrofitters |
| Companies Covered | Gurit, Celanese Corporation, 3B-Fiberglass, Hexcel Corporation, DuPont de Nemours, BASF, Arkema Group, Faurecia, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Thermoplastic Polymer Composites Market Shifts & Advancements
Continuous fiber-reinforced thermoplastic tapes are migrating from aerospace heritage into automotive serial production, enabling welded blank structures that merge stamping efficiency with composite performance.
Long fiber reinforced thermoplastic (LFT) direct compounding is displacing short fiber injection molding in structural battery components. Renault and Stellantis engineering teams are adopting LFT for module carriers and cooling plates at cycle times under ninety seconds. This displacement is compressing the cost gap with aluminum die-casting while enabling complex rib geometries impossible in metal.
F-Gas Regulation tightening on processing emissions is forcing compression molding operations to adopt electric press technology and closed-loop thermal management. French compounders serving under-the-hood applications must now demonstrate sub-threshold HFC leakage rates to maintain CE marking. The Rhône-Alpes corridor is responding fastest, with three facilities completing electric press retrofits in the past eighteen months.
Fleet electrification mandates are compressing buyer decision cycles for lightweighting procurement. Tier 1 suppliers now face six-month quoting windows versus historical twelve-month cycles, forcing compounders to pre-position inventory and accelerate formulation development. This pattern concentrates procurement among vertically integrated material suppliers with captive European compounding networks, disadvantaging import-dependent distributors.
France Automotive Thermoplastic Polymer Composites Market Segmentation
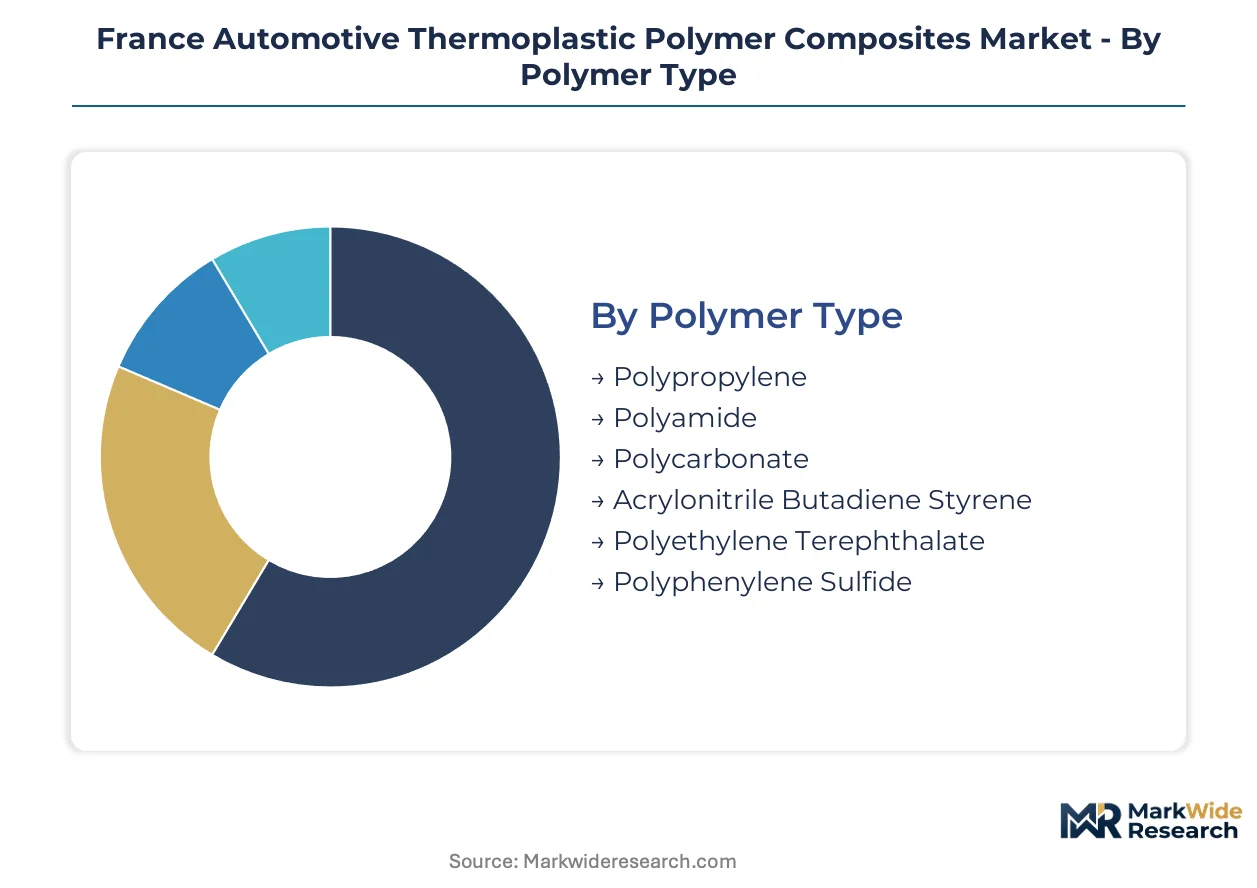
Segmentation in the France automotive thermoplastic polymer composites market reveals how EU regulatory frameworks differentially constrain or enable specific material categories. REACH substance classifications and End-of-Life Vehicles Directive recycling mandates create divergent compliance costs across polymer chemistries and composite forms, directly shaping procurement patterns among Paris-Saclay and Rhône-Alpes manufacturing clusters.
Polymer Type:
ECHA substance of very high concern classifications under REACH differentiate polymer eligibility for automotive platforms serving French OEMs.
- Polypropylene:Dominates interior component production due to low density and favorable recycling economics under extended producer responsibility frameworks enforced by the French Environment and Energy Management Agency. Rhône-Alpes compounders are accelerating closed-loop polypropylene system development to capture CAF qualification contracts from Stellantis and Renault assembly plants.
- Polyamide:Captures concentrated margin pools in thermal management applications requiring continuous service temperatures above 150°C. Demand concentrates around under-the-hood parts where ANSM and CNIL oversight of industrial data governance conditions how suppliers manage material traceability databases for connected vehicle integration.
- Polycarbonate:Serves optical-grade and high-impact glazing applications with transparent formulations.
- Acrylonitrile Butadiene Styrene:Delivers cost-efficient solutions for non-structural interior trim with established compounding infrastructure.
- Polyethylene Terephthalate:Finds niche positioning in recycled-content applications leveraging mass-balanced certification schemes.
- Polyphenylene Sulfide:Commands specialty positioning for extreme thermal environments in electrified powertrains.
Established volume favors polypropylene; emerging adoption favors polyamide for thermal management expansion.
Composite Form:
Processing cycle time and fiber length govern cost-positioning against aluminum die-casting in French battery platform architectures.
- Long Fiber Reinforced:Direct compounding processes are displacing short fiber injection molding in structural battery components. Renault and Stellantis engineering teams adopt this form for module carriers and cooling plates at cycle times under ninety seconds, compressing the cost gap with aluminum die-casting while enabling complex rib geometries impossible in metal.
- Short Fiber Reinforced:Retains dominance in high-volume interior component production where cost efficiency governs procurement decisions for Paris-Saclay cluster suppliers. F-Gas Regulation tightening on processing emissions forces compression molding operations toward electric press technology to maintain CE marking eligibility.
- Sheet Molding Compound:Enables complex exterior panel geometries with Class-A surface finishes.
- Bulk Molding Compound:Serves electrical housing applications requiring dimensional stability and flame retardancy.
- Spray-up:Retains limited automotive positioning in aftermarket and retrofit applications.
- Film:Delivers lightweight decorative and functional surface layers for interior modules.
Long fiber reinforced forms are gaining share fastest in structural electrification applications; short fiber reinforced retains margin defense in interior volume.
Application:
EU Green Deal emissions mandates compress the metal-to-polymer substitution timeline differentially across vehicle zones.
- Structural Parts:Battery enclosure and floor pan applications are pulling long fiber reinforced thermoplastics into load-bearing architectures previously reserved for aluminum. CAF qualification timelines of eighteen to twenty-four months for crash performance validation lock out smaller compounders from platform awards, concentrating procurement among vertically integrated suppliers with captive European compounding networks.
- Thermal Management:Polyamide formulations capture concentrated margin pools requiring continuous service temperatures above 150°C. F-Gas Regulation limits on processing emissions compel Rhône-Alpes facilities to demonstrate sub-threshold HFC leakage rates for CE marking maintenance.
- Interior Components:High-volume production with established recycling pathways under extended producer responsibility frameworks.
- Exterior Panels:Class-A surface requirements constrain viable polymer and process combinations.
- Electrical Housings:Flame retardant specifications subject to REACH substance restriction reformulation cycles.
- Under-the-Hood Parts:Thermal and chemical resistance requirements favor specialty resin grades with concentrated European supply.
Structural parts show steepest expansion trajectory; interior components defend established revenue base.
End User Type:
Procurement authority concentration and qualification timeline compression reshape supplier relationship economics across the value chain.
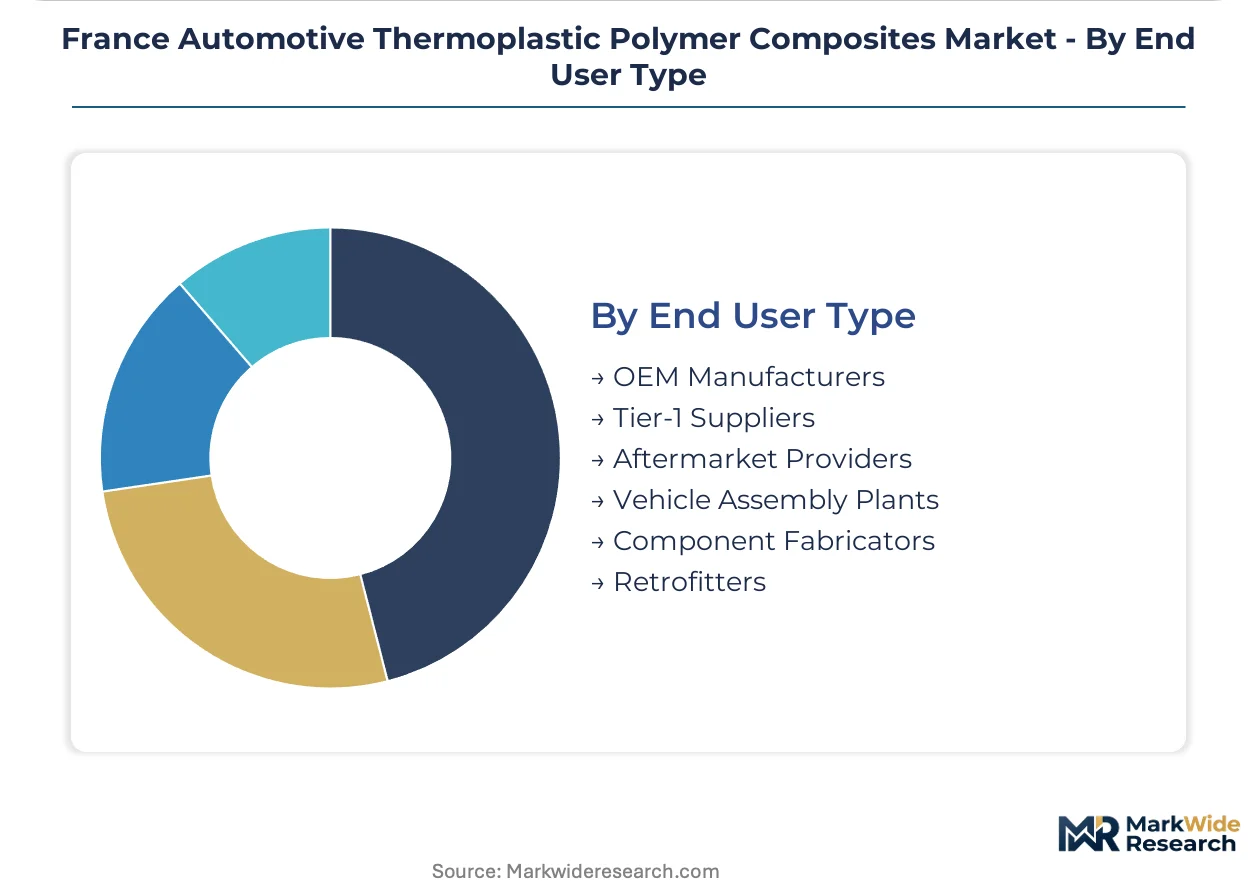
- OEM Manufacturers:Renault and Stellantis engineering teams now face six-month quoting windows versus historical twelve-month cycles, forcing compounders to pre-position inventory and accelerate formulation development. This pattern concentrates procurement among suppliers with localized European compounding networks.
- Tier-1 Suppliers:Faurecia competes by integrating composite interior modules directly into vehicle assembly sequences, capturing value through module-level integration rather than material supply alone.
- Aftermarket Providers:Serve repair and replacement demand with less stringent qualification requirements.
- Vehicle Assembly Plants:Located primarily in Rhône-Alpes corridor and Paris-Saclay cluster with just-in-time delivery requirements.
- Component Fabricators:Process semi-finished composite forms into final geometries for Tier-1 integration.
- Retrofitters:Address fleet electrification conversion demand with limited volume scale.
Tier-1 suppliers capture integration value; OEM direct procurement is concentrating for strategic structural platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emissions mandates and extended producer responsibility frameworks are redistributing composite manufacturing capacity across French industrial corridors. The analysis examines five sub-regional concentrations where thermoplastic polymer composite demand concentrates around OEM assembly footprints and Tier-1 integration nodes.
Île-de-France
The Paris-Saclay automotive cluster anchors R&D-intensive development of crash-optimized composite geometries. ANSM and CNIL oversight of industrial data governance conditions material traceability database management for connected vehicle integration. Co-development contracts between material suppliers and Tier-1 integrators accelerate formulation cycles for battery enclosure applications.
Auvergne-Rhône-Alpes
Stellantis and Renault assembly plants pull composite seat structures and interior modules into localized production sequences. F-Gas Regulation tightening forces three facilities to complete electric press retrofits for sub-threshold HFC leakage compliance. The corridor's underpenetrated composite supply chain presents white space for compounders with closed-loop polypropylene systems.
Provence-Alpes-Côte d'Azur
Specialty resin demand from electrified powertrain suppliers concentrates around thermal management component fabrication. REACH substance restrictions on flame retardant formulations delay platform approvals by twelve to eighteen months. Regional compounders face margin compression from caprolactam price volatility tied to benzene derivative markets.
Hauts-de-France
Proximity to Belgian and German compounding networks positions the region as a distribution node for high-performance polyamide grades. Recycling infrastructure gaps force reliance on cross-border automated sorting and re-compounding capacity. Extended producer responsibility penalties redirect procurement toward certified closed-loop suppliers.
Nouvelle-Aquitaine
Aerospace heritage in continuous fiber-reinforced thermoplastic tapes migrates into automotive serial production partnerships. Bio-based feedstock certification schemes create premium positioning for mass-balanced polypropylene compounds. The sub-region's polymer research institutes anchor ISCC PLUS and RSB scheme validation for sustainability-linked OEM targets.
France Automotive Thermoplastic Polymer Composites Market Competitive Landscape
Player mix skews toward European chemical conglomerates with captive compounding networks and Tier-1 integrators with module-level assembly capabilities. The supplier base concentrates around firms with verified CE marking pathways under the EU End-of-Life Vehicles Directive. Three archetypes dominate: vertically integrated resin compounders, automotive module integrators, and specialty fiber reinforcement suppliers. Competitive positioning hardens through qualification timeline compression and pre-positioned inventory commitments.
Among European resin compounders, Celanese Corporation, Solvay, and BASF exemplify the integrated archetype with localized supply infrastructure. Celanese leverages its European compounding network to serve French OEMs with polyamide supply positioned for thermal management applications. Solvay anchors the high-performance segment through specialty polymer grades for under-the-hood service temperatures above 150°C. BASF represents the scale-driven chemical conglomerate with broad portfolio coverage across polypropylene and polyamide chemistries. Faurecia occupies a distinct integrator position by embedding composite interior modules directly into vehicle assembly sequences rather than competing purely on material supply.
| Leading Market Players |
|---|
| Gurit |
| Celanese Corporation |
| 3B-Fiberglass |
| Hexcel Corporation |
| DuPont de Nemours |
| BASF |
| Arkema Group |
| Faurecia |
| Solvay |
| Others |
Supply & Pricing Matrix
Thirty-six-month qualification cycles now govern supplier selection, compressing inventory buffers and amplifying pricing power for compounders with pre-positioned European compounding networks serving French OEM platforms.
Pricing Analysis
Certification level under EU End-of-Life Vehicles Directive CE marking creates the primary spread between premium and standard tiers. Three-tier pricing structure across certified closed-loop, conventional recyclable, and uncertified grades governs procurement contracts. Cost compression in thermal management polyamides is intensifying because caprolactam feedstock volatility tied to benzene derivatives squeezes compounder margins. Tier 1 integrators exhibit lowest price sensitivity due to module-level value capture, whereas aftermarket distributors face acute margin pressure from inventory holding costs.
Supply Chain Analysis
Just-in-time delivery preferences dominate OEM procurement, forcing compounders to maintain strategic stockpiles of specialty resin grades near Rhône-Alpes and Paris-Saclay assembly corridors. Supply concentrates in Germany, Belgium, and the Netherlands for high-performance polyamide and PPS compounding. Raw material dependencies rest on caprolactam, benzene derivatives, and glass fiber reinforcement supply. Single-source vulnerability from narrow European specialty resin production creates structural risk. Distribution runs through captive Tier 1 integrator networks and direct OEM supply agreements with limited spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated OEM-Tier 1 partnerships, fragmenting procurement authority away from standalone compounders and reshaping supplier relationship economics across French automotive corridors.
For Market Incumbents: Shield qualification timelines by embedding crash performance validation data directly into OEM platform engineering systems before CAF testing windows open. Capture backward integration into glass fiber reinforcement supply to defend margin position against caprolactam volatility. Prioritize electric press retrofits for F-Gas Regulation compliance to maintain CE marking eligibility as processing emission thresholds tighten. For New Entrants and Emerging Players: Blockchain-verified material passport services represent an underdeveloped layer where incumbents under-serve OEM liability management needs. Target Rhône-Alpes composite seat structures and interior modules where localized production gaps persist. Enter through co-development contracts with Paris-Saclay R&D clusters rather than direct material supply competition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Green Deal mandates and REACH substance restrictions continuously collapse the qualified supplier base. Acquisition targets center on compounders with verified closed-loop recycling pathways and captive European compounding infrastructure. Watch for ECHA substance of very high concern classifications as inflection signals that trigger reformulation cycles and platform approval delays.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Certification | CE marking under EU End-of-Life Vehicles Directive eliminates non-certified competitors from procurement pools. |
| Electric Press Retrofit | F-Gas Regulation compliance for sub-threshold HFC leakage maintains market access for French compounders. |
| Long Fiber Reinforced Thermoplastic Direct Compounding | Renault and Stellantis battery platform adoption displaces aluminum in structural module carriers. |
| Bio-Based Feedstock Certification | ISCC PLUS and RSB schemes command procurement preference from sustainability-linked OEM targets. |
| Material Passport Blockchain Integration | ANSM and CNIL data governance requirements open service revenue streams for end-of-life liability management. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 procurement leads, compounder plant managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from EU REACH substance classifications, ECHA regulatory filings, French Environment and Energy Management Agency enforcement data, and automotive production registration databases. Bottom-up volume builds across polymer type, composite form, and application segments triangulated against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled span polymer chemistry, fiber reinforcement length, processing technology, vehicle zone application, and end-user procurement authority across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating EU emissions mandate compliance timelines and metal-to-polymer substitution coefficients. Forecast inputs include battery platform architecture adoption rates and qualification cycle compression effects on supplier market share dynamics.
Underlying assumptions cover REACH substance restriction timelines, F-Gas Regulation enforcement intensity, and OEM lightweighting procurement commitment stability, with deviation risk concentrated in caprolactam feedstock price volatility and ECHA flame retardant reclassification events. Revision becomes warranted when CAF qualification timeline compression accelerates beyond current thirty-six-month baselines or when bio-based feedstock certification schemes achieve mandatory procurement status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Wood Coating Resins Market